
 Full-Service Restaurants Market | 2026-2036
Full-Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
Full-Service Restaurants Market Analysis
Market Dynamics
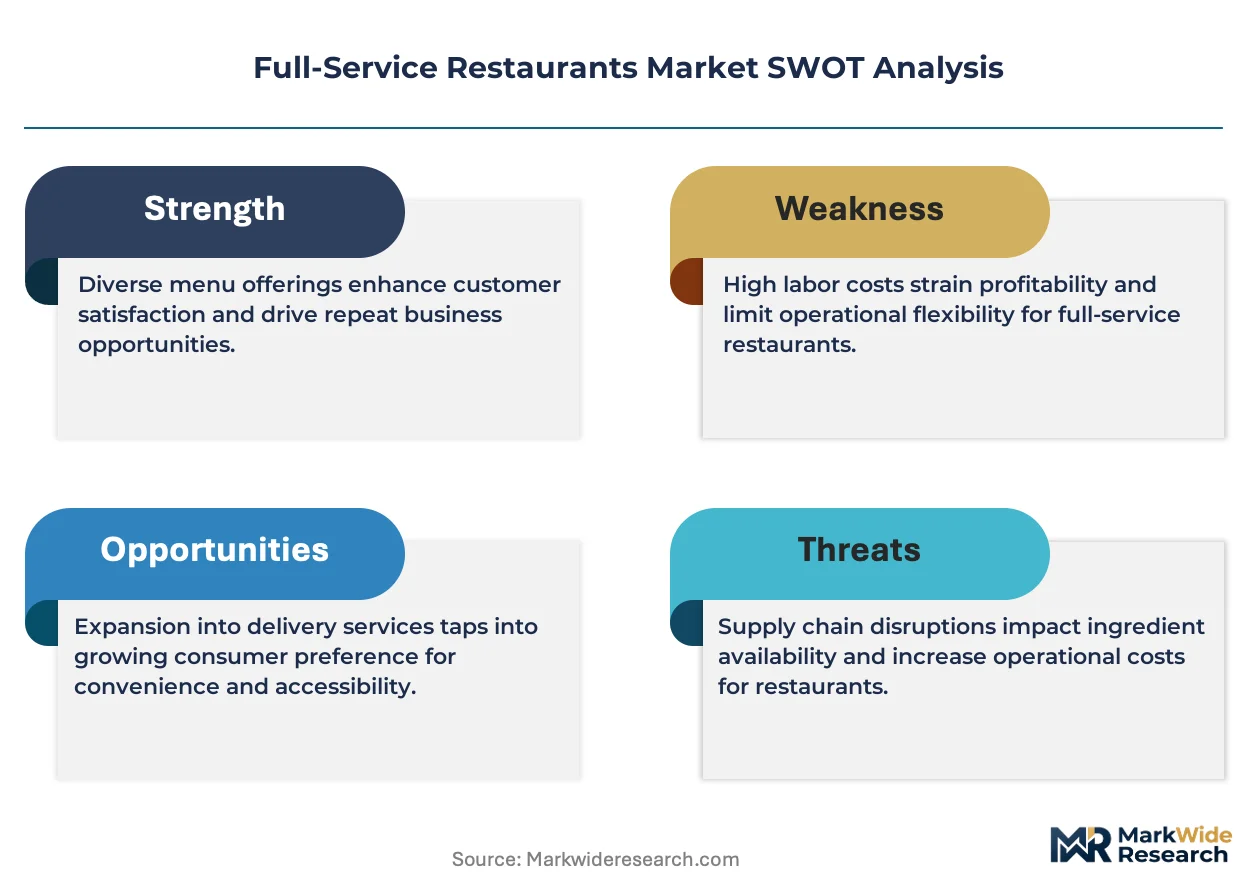
The dine-in channel is narrowing as off-premise formats capture larger share of full-service traffic. Darden Restaurants leverages its Olive Garden and LongHorn Steakhouse portfolios to sustain volume across hybrid service models. Texas Roadhouse anchors its growth in suburban markets where dine-in remains resilient. Bloomin' Brands competes through Outback Steakhouse's repositioning of bar-forward formats that blend casual and polished service elements.
Segment Structure
Full-service restaurants provide table-service dining with prepared-to-order meals across multiple courses, typically operating with average checks above limited-service equivalents and maintaining kitchen brigades for protein fabrication and sauce production. The mid-range price tier dominates transaction volume in suburban and secondary markets, while the premium tier captures disproportionate margin pools in metropolitan centers. Dine-in service retains structural importance for customer experience and alcohol attachment, though delivery integration now functions as a mandatory capability rather than optional extension.
Regulatory Environment
The FDA Food Code governs food safety protocols across United States jurisdictions, while state-level alcohol beverage control boards shape licensing economics for full-service operators. OSHA workplace safety standards and municipal health grading systems influence labor deployment and facility investment decisions. Stakeholders must monitor how evolving tip-credit regulations and minimum wage compression alter unit-level profitability models.
Market Dynamics
Off-premise dining infrastructure is compressing the traditional full-service revenue model as ghost kitchens and third-party delivery platforms capture margin pools once exclusive to dine-in operators. Labor deployment patterns now split across front-of-house service and back-of-house production for simultaneous channels.
Growth Catalysts
- Urban density premiums:Metropolitan clusters in the United States, China, and India concentrate disposable income for experiential dining occasions. These markets sustain higher average checks through location scarcity.
- FDA Food Code harmonization:Standardized food safety protocols reduce compliance friction for multi-unit operators expanding across state lines. Uniform inspection criteria lower administrative overhead.
- Alcohol licensing economics:Full-service operators leverage beverage attachment rates that limited-service competitors cannot replicate. Bar-forward formats capture margin-rich consumption occasions.
Market Restraints
- Protein input volatility:Beef and seafood commodity markets expose operators to margin compression without pricing flexibility. Contract coverage remains incomplete for mid-tier chains.
- Real estate concentration:Prime suburban and urban trade areas face limited availability and escalating rents. Site selection constrains expansion velocity.
- Third-party delivery dependency:Platform fees extract 15-30 percent of order value, eroding unit economics. Operators lack negotiating leverage against consolidated aggregators.
Strategic Opportunities
- Secondary market penetration:Smaller metropolitan areas in India and China's interior provinces show rising middle-class dining expenditure. First-mover positioning yields brand establishment before competition intensifies.
- OSHA workplace safety incentives:Proactive compliance programs reduce injury rates and associated premium costs. Operators can convert safety investments into recruitment advantages.
- Hybrid format convergence:Ghost kitchen regulations in New York City and California are forcing operators to integrate off-premise production into full-service facilities. This dual-use infrastructure lowers per-unit capital requirements.
Industry Challenges
- Culinary brigade staffing:Qualified line cooks and sauciers remain scarce as vocational pipeline output lags replacement demand. Wage compression intensifies retention battles.
- Tip-credit policy uncertainty:State-level minimum wage adjustments alter front-of-house labor models. Operators must restructure compensation without alienating service staff.
- Health grading compliance:Municipal inspection systems impose operational discipline that varies by jurisdiction. Multi-unit consistency requires localized management attention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Full-Service Restaurants Market |
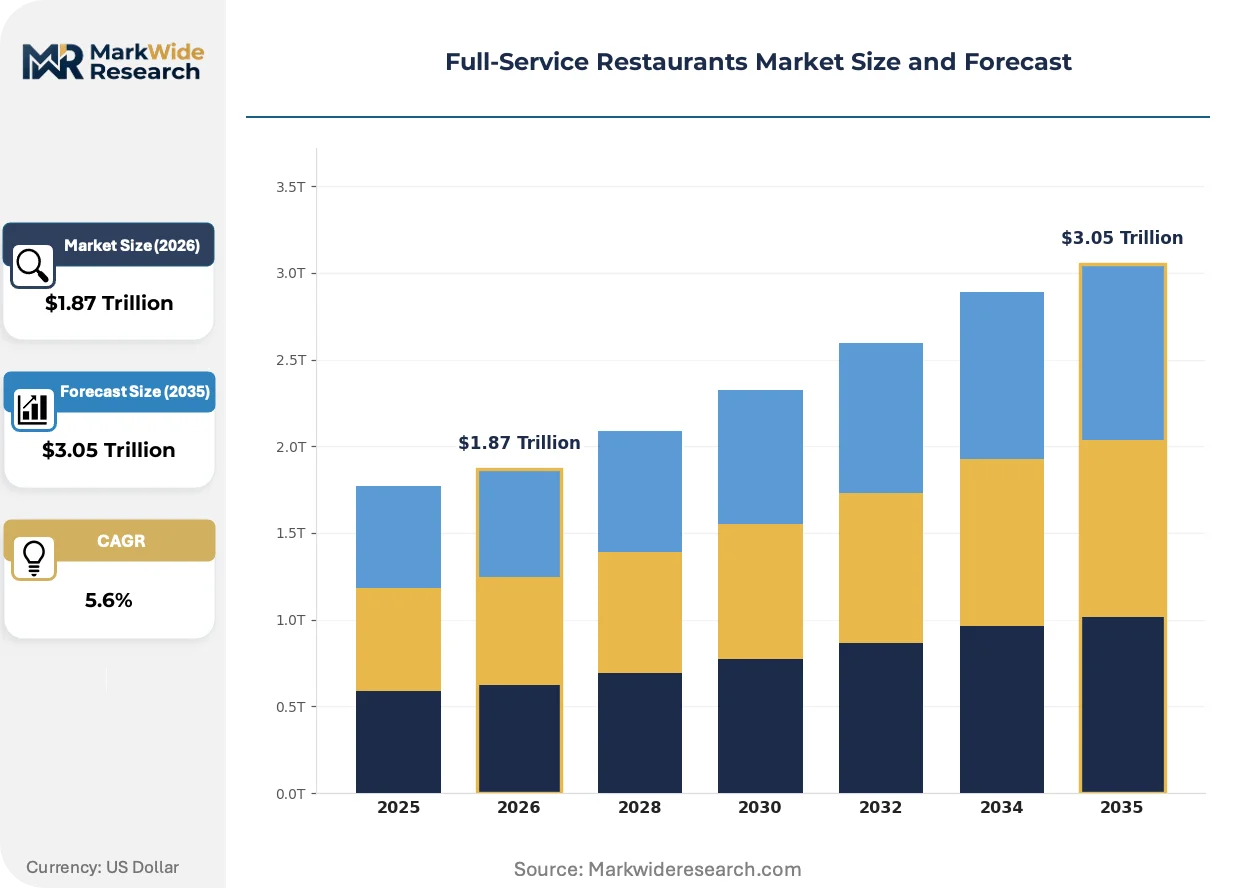
| Market Size in 2026 | $1.87 Trillion |
| Market Size in 2035 | $3.05 Trillion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-In, Takeout, Delivery, Catering Price Tier: Economy, Mid-Range, Premium, Luxury Cuisine Type: Italian, Asian, American, Mexican Customer Type: Families, Couples, Business Groups, Solo Diners |
| Companies Covered | Darden Restaurants Inc., Bloomin' Brands Inc., Brinker International Inc., Texas Roadhouse Inc., The Cheesecake Factory Inc., Applebee's Restaurants LLC, Red Lobster Hospitality LLC, Denny's Inc., IHOP Restaurants LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Full-Service Restaurants Market Emerging Trajectories
Kitchen automation and digital ordering platforms are restructuring how full-service operators deploy labor and manage throughput. These technologies compress the traditional service model while opening new operational configurations.
Tableside tablet ordering and payment systems are collapsing the server-to-guest interaction sequence into a single interface. Chains with 100-plus units deploy these devices to reallocate floor staff toward food running and guest engagement. Labor hours per cover compress while ticket averages rise through automated upsell prompts.
FDA Food Code updates governing allergen disclosure and temperature logging impose stricter documentation requirements. Operators must integrate digital monitoring systems to maintain compliance across distributed locations. Full-service chains with multi-state footprints face the steepest adaptation costs as local health departments adopt successive amendments.
Subscription-based dining memberships are displacing traditional frequency programs across metropolitan markets. Consumers pre-commit to monthly dining credits in exchange for priority reservations and menu exclusives. This model concentrates most visibly in United States coastal cities where competition for limited seats intensifies customer lock-in strategies.
Full-Service Restaurants Market Segmentation
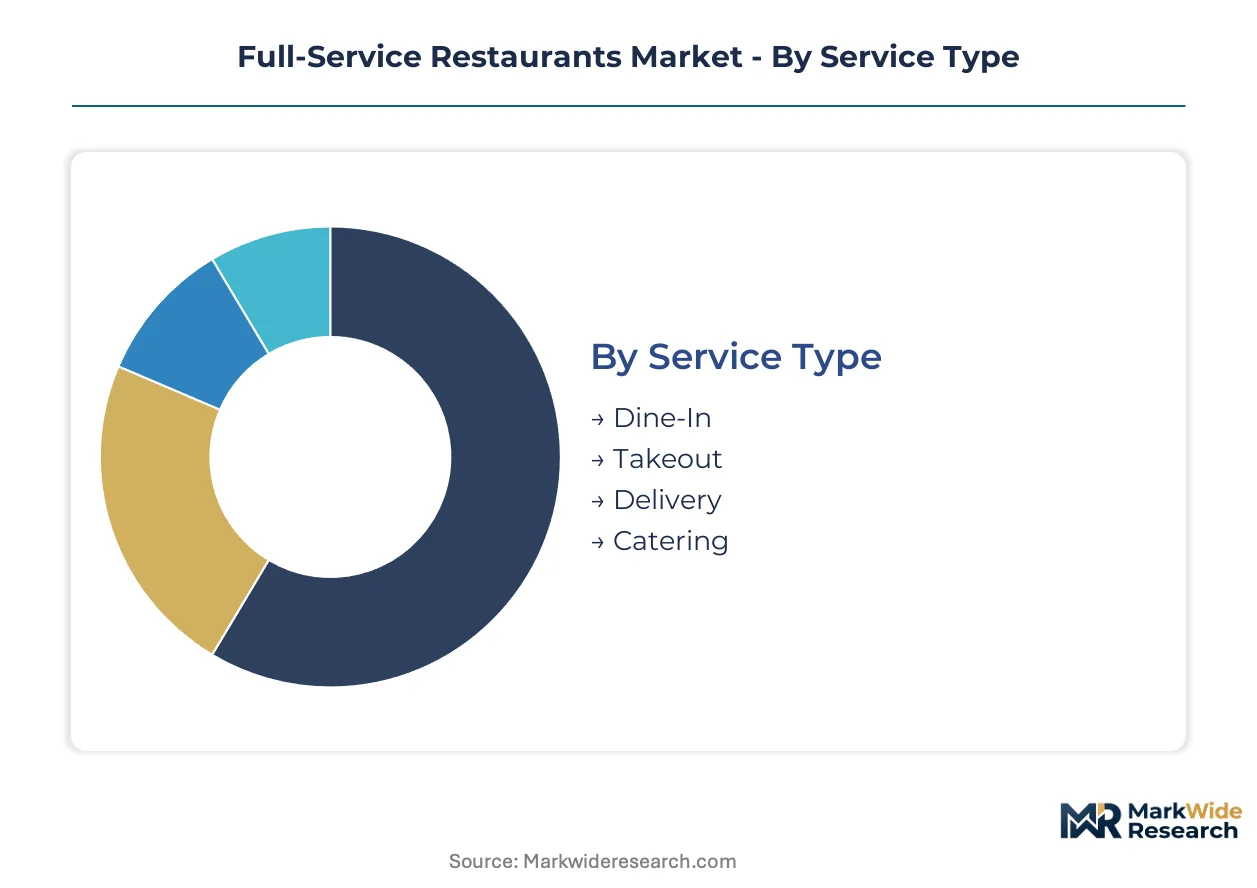
Full-service restaurants segment across service modalities, price positioning, cuisine specialization, and occasion types. These dimensions determine kitchen brigade structure, real estate requirements, and beverage licensing economics. Operators configure hybrid capabilities differently depending on which segments they target.
Service Type:
Service modality dictates labor deployment patterns and facility design across the full-service footprint. Each channel carries distinct margin profiles and throughput constraints.
- Dine-In:Table-service operations with dedicated front-of-house staff manage seated covers across multiple courses. United States suburban markets sustain this channel through alcohol attachment and celebration occasions. Labor intensity limits scalability.
- Takeout:Prepared-to-order meals packaged for customer pickup compress service labor while preserving kitchen production margins. Ghost kitchen regulations in California and New York City reshape how operators integrate this channel into full-service facilities.
- Delivery:Third-party platform integration extends reach but extracts platform fees that erode unit economics. Operators lack negotiating leverage against consolidated aggregators.
- Catering:Off-site event service with advance-order logistics captures volume occasions. Corporate accounts in metropolitan India and China drive demand concentration.
Dine-In holds installed capacity. Delivery is rotating up the share rankings.
Price Tier:
Cost positioning determines ingredient specifications, service choreography, and real estate investment levels across the competitive landscape.
- Economy:Limited menu breadth and simplified service protocols target frequency-driven occasions. Value positioning in India's expanding middle-class markets captures volume before competition intensifies.
- Mid-Range:Balanced ingredient quality with standardized preparation dominates suburban transaction volume across the United States. This tier captures disproportionate traffic in secondary metropolitan areas.
- Premium:Elevated proteins and craft beverage programs sustain higher average checks in location-scarce urban clusters. Metropolitan centers in China concentrate disposable income for experiential dining.
- Luxury:Bespoke service choreography and ingredient provenance command reservation scarcity premiums. Coastal United States cities show concentrated demand for chef-driven tasting formats.
Mid-Range holds installed capacity. Premium is climbing the fastest.
Cuisine Type:
Menu specialization shapes supply chain requirements, kitchen equipment investment, and labor skill profiles across operator portfolios.
- Italian:Pasta fabrication and sauce production require dedicated kitchen stations with specialized equipment. Olive Garden's national footprint demonstrates scalable standardization potential.
- Asian:Wok cooking and fermentation protocols demand distinct ventilation and ingredient sourcing. Urban United States markets show sustained demand for regional specialization.
- American:Protein-centric menus with grill-focused preparation dominate suburban trade areas. Texas Roadhouse anchors growth in these markets through steakhouse positioning.
- Mexican:Fresh preparation of masa and salsa programs requires localized supply relationships. California's ghost kitchen regulations particularly affect operators in this cuisine category.
American holds installed capacity. Asian is gaining share fastest.
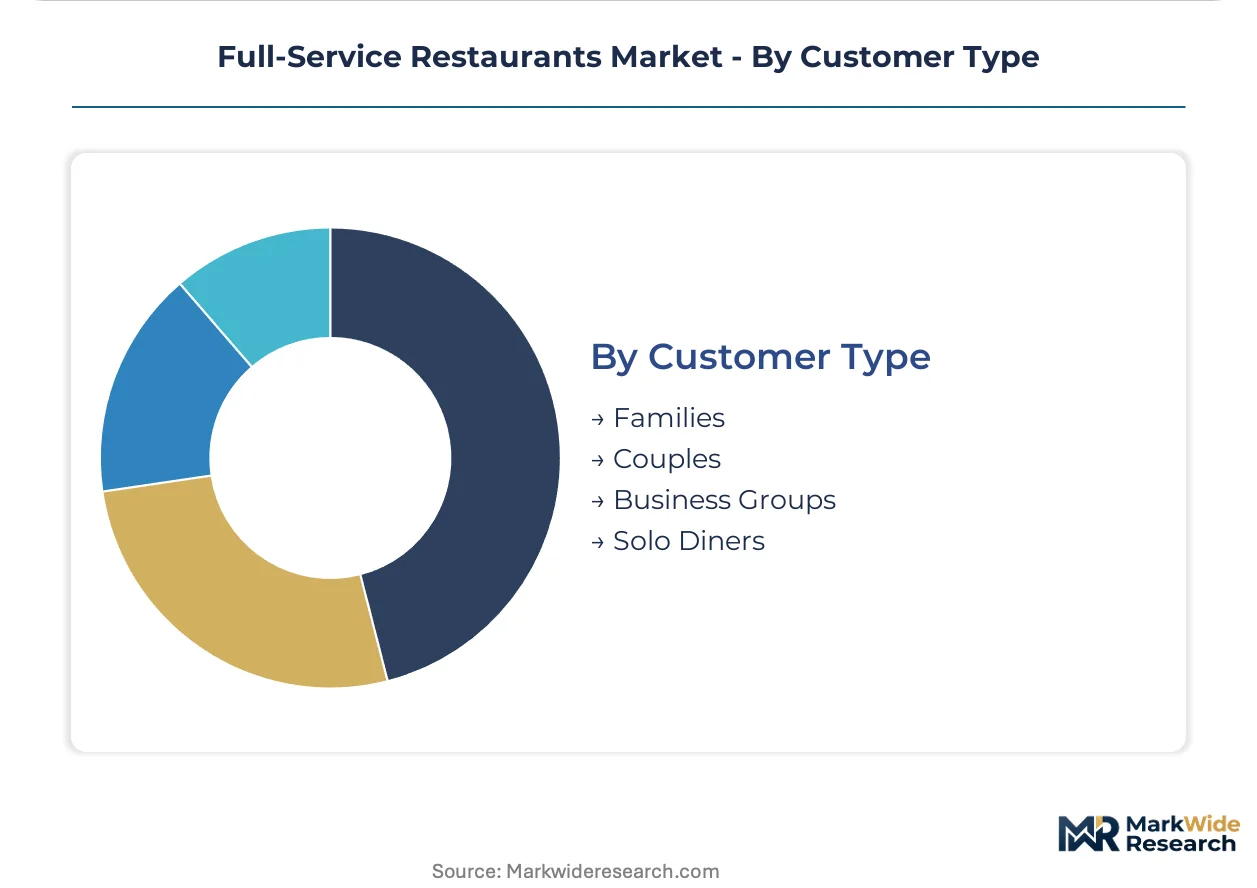
Customer Type:
Occasion segmentation determines seating configuration, pacing protocols, and beverage program design across service formats.
- Families:High-cover, rapid-turn seating with simplified menu navigation targets weekend volume peaks. Suburban United States locations optimize for this segment through kid-friendly amenities.
- Couples:Intimate seating with extended dwell times supports wine program attachment and dessert conversion. Metropolitan India shows rising demand for date-night positioning.
- Business Groups:Private dining accommodations with presentation capabilities capture corporate entertainment budgets. China's tier-one cities concentrate this demand.
- Solo Diners:Counter seating and bar-forward formats accommodate individual occasions with lower service labor per cover. Urban millennials and Gen Z consumers accelerate this segment across North America.
Families hold installed capacity. Solo Diners is climbing the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System and Class I rail corridors underpin the United States' dominance in full-service restaurant distribution, while China's high-speed rail network and port infrastructure accelerate interior market penetration.
United States
Suburban sprawl and dual-income household density sustain mid-range steakhouse and casual dining expansion across Texas, Florida, and the Southeast. OSHA workplace safety standards and FDA Food Code harmonization reduce compliance friction for multi-state operators. The Dallas-Fort Worth metroplex anchors Texas Roadhouse's corporate infrastructure and training center operations.
China
Tier-one city disposable income concentration and celebration dining culture elevate premium full-service penetration in Shanghai, Beijing, and Shenzhen. SAMR food safety inspections and municipal health grading systems impose operational discipline across provincial jurisdictions. The Yangtze River Delta cluster concentrates experiential dining investment as middle-class expenditure rotates toward service occasions.
India
Urban millennial workforce expansion and nuclear family formation accelerate dine-out frequency in Mumbai, Bangalore, and Delhi-NCR. FSSAI licensing protocols and state-level alcohol beverage control boards shape unit economics for operators expanding across Maharashtra, Karnataka, and Telangana. The Bandra-Kurla Complex in Mumbai anchors premium international format entry.
Germany
Stable wage growth and culinary tourism sustain independent full-service density across Bavaria and Baden-Württemberg. EFSA allergen disclosure requirements and municipal Gewerbeamt licensing procedures standardize operational protocols. Munich's Viktualienmarkt district concentrates chef-driven independent establishments with regional sourcing relationships.
Japan
Aging demographic dining-out persistence and business entertainment culture sustain traditional full-service formats in Tokyo and Osaka. METI small business support programs and PMDA food additive regulations govern menu development and supply chain documentation. The Ginza corridor maintains reservation scarcity premiums for luxury kaiseki and international fusion concepts.
Full-Service Restaurants Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in protein sourcing and equipment supply. The full-service restaurant market structures around consolidated national chains with 500-plus unit footprints and fragmented regional independents below 50 locations. Strategic archetypes divide between scale-driven portfolio operators, bar-forward format innovators, and suburban value-positioned steakhouse chains. Dominant competitive moves include M&A consolidation of distressed regional brands and strategic partnerships with third-party delivery platforms.
Among portfolio-anchored operators, Darden Restaurants Inc., Bloomin' Brands Inc., and Texas Roadhouse Inc. occupy positions representing distinct strategic archetypes. Darden exemplifies the diversified portfolio model with multiple cuisine formats under centralized supply chain management. Bloomin' Brands occupies a position within the bar-forward convergence tier, blending casual service protocols with polished beverage programs. Texas Roadhouse anchors the suburban value-specialist archetype, concentrating capital deployment in secondary metropolitan trade areas where dine-in resilience outperforms urban density markets.
| Leading Market Players |
|---|
| Darden Restaurants Inc. |
| Bloomin' Brands Inc. |
| Brinker International Inc. |
| Texas Roadhouse Inc. |
| The Cheesecake Factory Inc. |
| Applebee's Restaurants LLC |
| Red Lobster Hospitality LLC |
| Denny's Inc. |
| IHOP Restaurants LLC |
| Others |
Supply Flow & Price Mechanics
Protein input volatility determines both pricing tier spreads and supply chain shape across full-service restaurant operations. Beef and seafood commodity swings compress margins in mid-range tiers while forcing operators toward contract coverage strategies that reshape supplier relationships and inventory holding patterns.
Pricing Analysis
Volume-discount tiering structures dominate procurement economics as multi-unit operators leverage scale against fragmented protein suppliers. Three-tier pricing structure across premium, standard, and economy levels separates luxury steakhouse positioning from suburban casual dining and value-focused formats. Cost compression in the economy tier is intensifying because third-party delivery platform fees extract 15-30 percent of order value. Family dining segments exhibit highest price sensitivity, while premium metropolitan occasions show inelastic demand.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities anchor working capital negotiations between restaurant chains and protein distributors. Domestic beef processing concentrates in the United States, with secondary sourcing from Australia and Brazil for specialty cuts. Seafood supply draws from Alaska, Norway, and Vietnam depending on species specifications. Single-source vulnerability in domestic beef packing creates exposure to labor disruption and plant closure risks. Distribution runs through broadline foodservice distributors with regional cold-chain depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full-service restaurant economics now hinge on platform interoperability as third-party delivery aggregators become unavoidable infrastructure. Ghost kitchen regulations in California and New York City exemplify how municipal policy is forcing dine-in operators into hybrid production models.
For Market Incumbents: Pre-empt margin erosion by consolidating back-of-house capacity across brands into shared commissary production. Vertical integration into protein fabrication through direct ranch relationships reduces commodity exposure. Ghost kitchen compliance costs threaten smaller competitors; scale advantages widen through centralized off-premise infrastructure.
For New Entrants and Emerging Players: Build out bar-forward formats in secondary metropolitan India and China's interior provinces where experiential dining expenditure rises ahead of competition. Mid-range positioning in these markets offers white-space before national chains establish presence. Direct reservation platform development bypasses third-party aggregator dependency.
For Investors and Strategic Acquirers: FDA Food Code harmonization reshapes the acquisition landscape by lowering multi-state compliance friction for scaled operators. Five-to-ten-year viability favors portfolio operators with diversified cuisine formats and centralized supply chain management. Watch tip-credit policy shifts at state level as inflection indicators for front-of-house labor model restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Format Convergence | Integrating ghost kitchen production into full-service facilities lowers per-unit capital requirements under California and New York City regulations. |
| Direct Protein Sourcing | Ranch-level partnerships reduce commodity volatility exposure for steakhouse operators with standardized cut specifications. |
| Reservation Platform Development | Proprietary booking systems capture customer data and reduce third-party aggregator dependency for premium metropolitan formats. |
| Subscription Membership Launch | Monthly dining credits lock in frequency and improve forecasting accuracy for chef-driven concepts in coastal United States cities. |
| Secondary Market Expansion | First-mover positioning in India's tier-two cities captures middle-class dining expenditure before national chain saturation. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with restaurant executives, supply chain directors, and municipal health inspectors; and secondary validation through FDA Food Code amendments, state alcohol beverage control board filings, and OSHA workplace safety incident databases. Bottom-up unit economics modeling triangulated against top-down market sizing from trade association membership data and commercial real estate transaction records.
Forecast inputs incorporated service modality splits, price tier migration patterns, cuisine specialization trends, and regional regulatory cluster differentiation across the projection horizon. CAGRs derived from historical transaction volume trajectories adjusted for labor cost inflation and real estate concentration effects. Modeled dimensions included dine-in versus off-premise channel mix, mid-range versus premium positioning, and metropolitan versus secondary market density.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrated ghost kitchen operators would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Grills Market
Food Service
Beverage Napkins Market
Food Service
Commercial Griddle Market
Food Service
Food Service Gloves Market
Food Service
Food Service Disposables Market
Food Service
Global Online Food Delivery Services Market
Food Service
Germany Smokeless Indoor Grills Market
Food Service
Food Service Dairy Products Market
Food Service
Global Delivery Takeaway Food Market
Food Service
Global Combi Ovens Market
Food Service
Vacuum Flask Market
Food Service
Meal Voucher Market
Food Service
Sandwich Toasters Market
Food Service
Lunch Takeout Market
Food Service
Commercial Tableware Services Market
Food Service
Saudi Arabia Pizza Restaurants Market