
 Europe Food Service Market | 2026-2036
Europe Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Service Market Insights
Food delivery aggregators and ghost kitchen networks is rewriting how European operators reach diners, compressing traditional real estate models and forcing capital reallocation. Compass Group leverages its institutional footprint to sustain long-term contracts across hospitals and universities. Sodexo anchors its competitive position through integrated facilities management that bundles food service with cleaning and maintenance. Autogrill SpA dominates travel channel concessions in airports and motorway stops across Italy, France, and Spain.
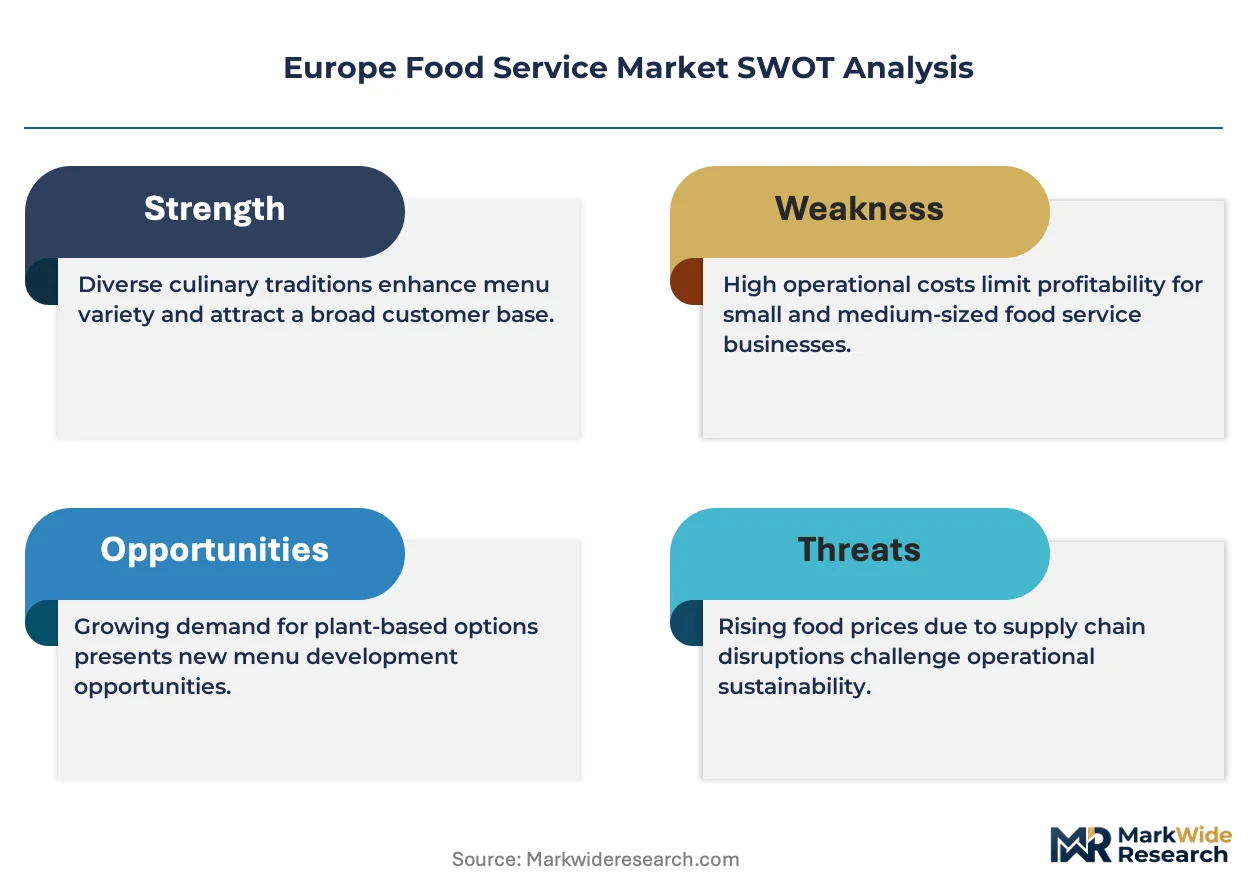
Europe food service encompasses commercial preparation and sale of meals, beverages, and related consumables through structured service formats, typically requiring compliance with HACCP protocols, allergen labeling mandates, and cold-chain integrity standards for perishable inventory. The sector serves daily nutrition needs across consumer, business, and institutional populations with varying frequency and contract terms. Quick Service Restaurants capture the largest volume share through standardized menus and throughput efficiency, while Catering Services directed at businesses and educational institutions generate more predictable recurring revenue. Full-Service Restaurants retain higher per-transaction value but face margin pressure from labor costs and floor-space economics.
EFSA guidelines on nutritional claims, EU Green Deal packaging requirements, and national health inspectorates across France, Germany, and Italy collectively shape ingredient sourcing, menu transparency, and single-use material transitions. REACH and F-Gas Regulation compliance adds cost layers to equipment procurement and refrigeration fleet management. Stakeholders must monitor how digital ordering data intersects with GDPR obligations and whether CSRD reporting will force disclosure of supply chain emissions from farm to fork.
Market Dynamics
Hybrid work stabilization is fragmenting corporate catering demand across weekdays and locations, forcing operators to reconfigure contract structures and kitchen utilization models around unpredictable office occupancy patterns.
Growth Catalysts
- EU Green Deal packaging mandates:Single-use plastic bans and extended producer responsibility schemes are accelerating investment in reusable container infrastructure and circular supply partnerships across France, Germany, and Italy.
- Ghost kitchen networks:Delivery-optimized production facilities are compressing real estate costs and enabling rapid market entry in dense urban corridors without front-of-house investment.
- Transport hub modernization:Airport and motorway concession expansions in Spain and the Netherlands are creating captive audience revenue streams with limited competitive pressure.
Market Restraints
- REACH chemical compliance:Food-contact material certification timelines and testing costs are extending supplier onboarding cycles and limiting sourcing flexibility for imported packaging.
- Wheat and dairy input volatility:Commodity price swings tied to Black Sea supply disruptions are compressing margin predictability across bakery and prepared meal categories.
- Refrigeration fleet F-Gas phase-down:Equipment replacement mandates under EU F-Gas Regulation are imposing capital burdens on cold-chain operators before cost recovery timelines align.
Strategic Opportunities
- Poland and Romania urban corridors:Underserved second-tier cities with rising disposable income and limited branded food service penetration offer first-mover expansion potential.
- CSRD supply chain disclosure:Mandatory emissions reporting is creating advisory and data infrastructure service demand from operators seeking farm-to-fork traceability systems.
- AI-driven demand forecasting:Machine learning convergence with POS data is enabling dynamic menu pricing and waste reduction for multi-site contract caterers.
Industry Challenges
- HACCP auditor scarcity:Certified food safety professionals are concentrated in Western European labor markets, constraining expansion speed in Central and Eastern European growth corridors.
- Legacy POS integration:Fragmented technology stacks across acquired restaurant portfolios are delaying unified customer data platforms and loyalty program rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Service Market |
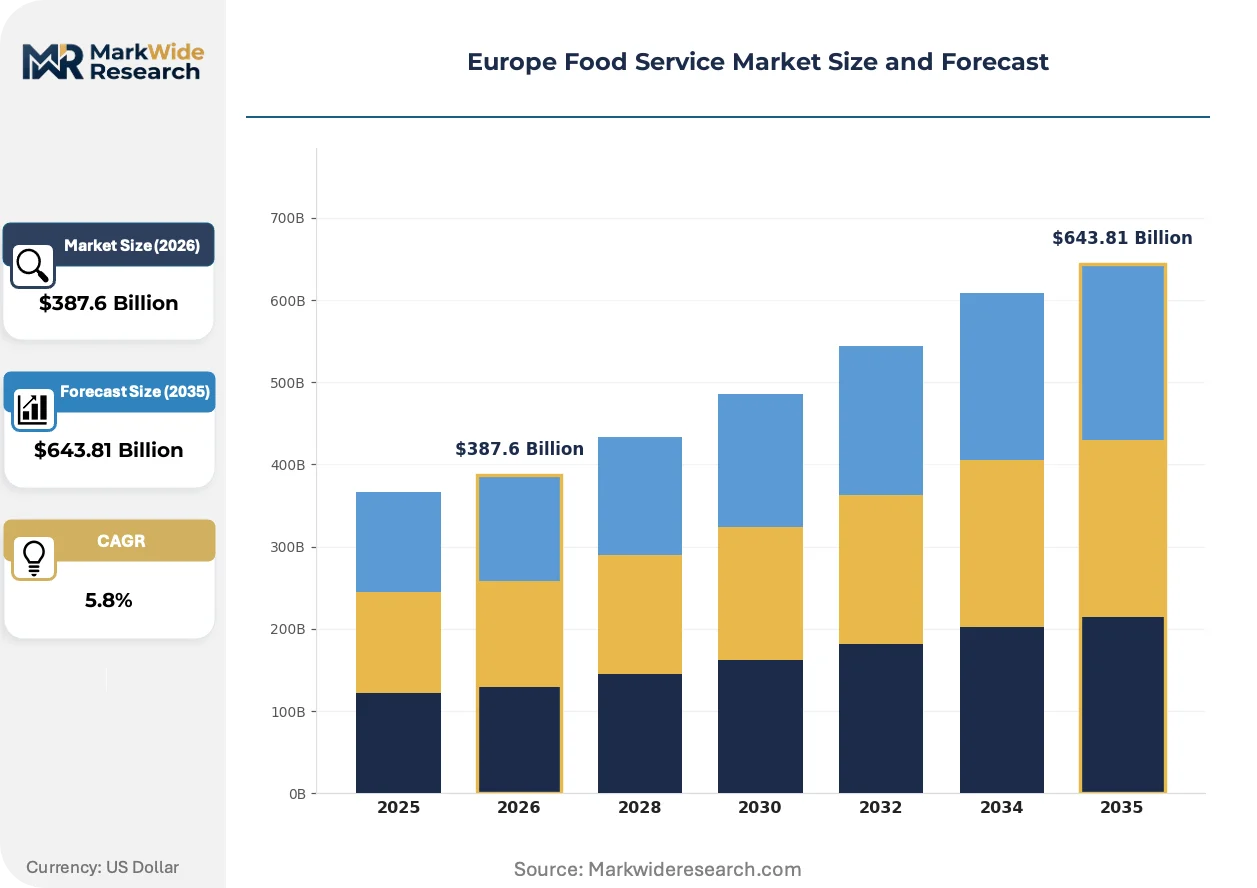
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Quick Service Restaurants, Cafes, Catering Services End User: Consumers, Businesses, Educational Institutions, Healthcare Facilities Product Type: Food, Beverages, Snacks, Desserts Pricing Model: Value Meals, À La Carte, Buffet, Subscription |
| Companies Covered | McDonald’s Corporation, Compass Group, Sodexo, Elior Group, Yum! Brands, Autogrill SpA, Greggs, SSP Group, Restaurant Brands International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Service Market Trends and Innovations
Digital infrastructure is rewiring how European food service operators manage production, procurement, and customer relationships, compressing decision cycles and exposing legacy cost structures.
Kitchen display systems and IoT-enabled equipment monitoring are digitizing back-of-house operations across mid-scale restaurant groups. Multi-site operators in Germany and the UK are deploying these tools to synchronize prep schedules with real-time demand signals from delivery aggregators. The technology is digitizing labor deployment models, reducing idle capacity during off-peak hours.
EFSA nutritional claim substantiation requirements are tightening menu transparency obligations for health-positioned products. Operators must now maintain clinical evidence files for terms like "high protein" or "low sodium," raising compliance costs for branded menu development. Full-service chains in France and Italy are responding by simplifying claim language and redirecting marketing spend toward ingredient provenance narratives.
Corporate clients are unbundling integrated facilities management contracts to separate food service from cleaning and maintenance procurement. Large employers in the Netherlands and Scandinavia are issuing standalone catering RFPs with shorter renewal cycles and performance-based pricing. This behavior is most visible among technology and professional services firms with distributed work models, where per-employee meal subsidies have replaced fixed site-based guarantees.
Europe Food Service Market Segmentation
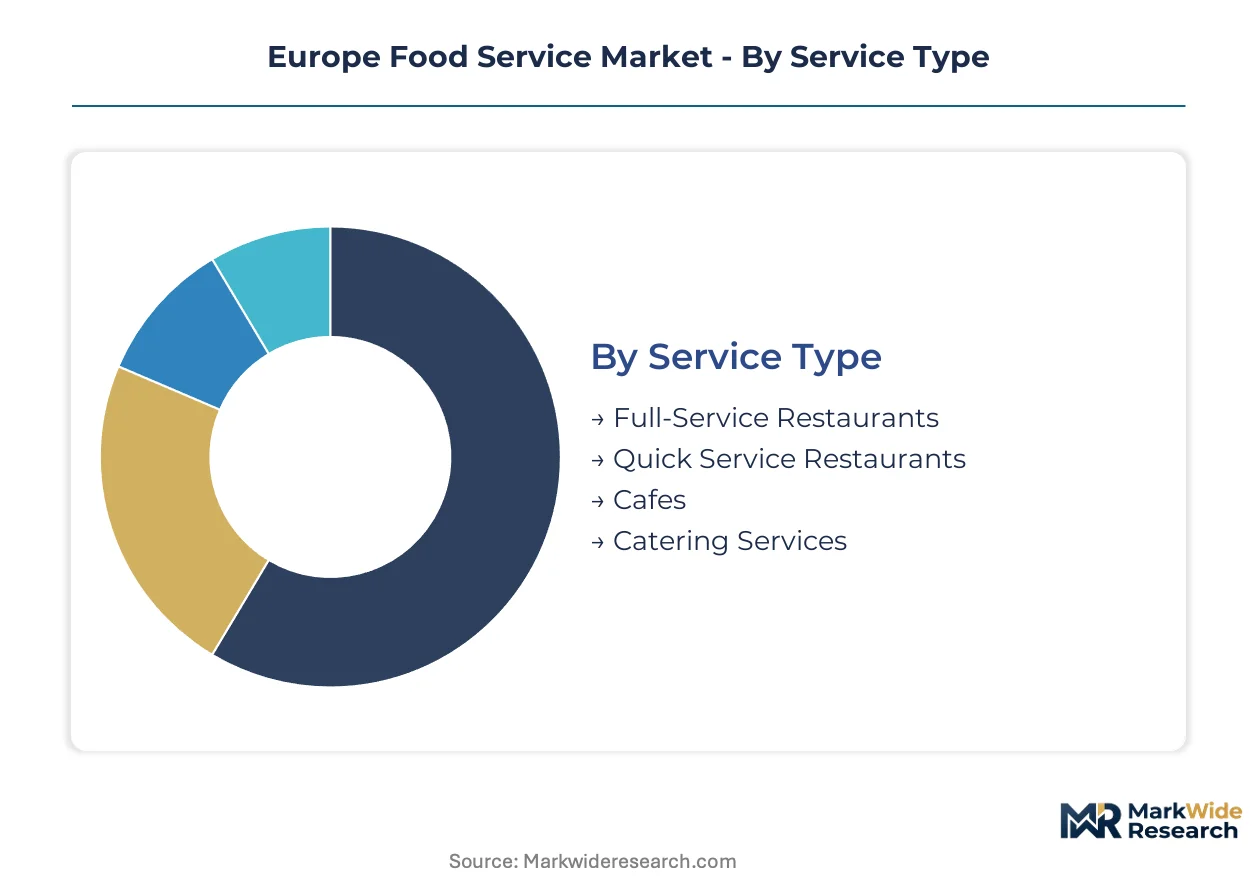
European food service operators configure their asset bases and labor models around distinct service formats and customer contracts. Segmentation reveals where capital intensity concentrates and which revenue streams offer predictability against volatile input costs.
Service Type:
Cost tier determines kitchen equipment specifications, real estate footprints, and labor deployment ratios across European operations.
- Full-Service Restaurants:Table service formats with on-premise preparation and front-of-house staffing. Revenue concentrates in Paris, Milan, and Barcelona dining corridors where experience premiums offset higher labor and rent burdens.
- Quick Service Restaurants:Standardized menus with limited customization and throughput-optimized kitchen layouts. Demand clusters at German motorway interchanges and UK retail park locations where speed and price transparency drive selection.
- Cafes:Beverage-forward formats with limited food preparation. Urban Netherlands and Scandinavian markets show concentration around transport nodes and co-working districts.
- Catering Services:Contract-based meal provision for institutional and corporate clients. Predictable volume from French hospital networks and German university systems offsets lower per-cover margins.
Quick Service Restaurants hold installed capacity. Catering Services is rotating up the share rankings.
End User:
Customer type dictates contract structure, payment timing, and menu customization requirements across the European landscape.
- Consumers:Individual diners making discretionary purchase decisions. Frequency concentrates in Spain's urban centers and Italy's tourist corridors where disposable income supports premium positioning.
- Businesses:Corporate clients procuring meals for employees, meetings, and events. Hybrid work stabilization in London and Frankfurt is fragmenting demand across smaller, more flexible contract structures.
- Educational Institutions:Schools and universities with subsidized or regulated meal programs. French and German public systems maintain long-term procurement frameworks with nutritional compliance mandates.
- Healthcare Facilities:Hospitals and care homes requiring therapeutic and restricted diets. EFSA nutritional claim requirements shape menu development for diabetic, renal, and texture-modified offerings.
Businesses segment holds installed capacity. Healthcare Facilities is rotating up the share rankings.
Product Type:
Margin profile varies sharply across product categories based on spoilage risk, preparation labor, and ingredient cost volatility.
- Food:Prepared meals and meal components requiring HACCP-compliant handling. Prepared meal demand concentrates in German retail and travel channels where cold-chain integrity standards are most stringent.
- Beverages:Hot, cold, and alcoholic drinks with higher margin contribution per unit. Italian espresso culture and UK coffee shop density create distinct competitive dynamics for hot beverage specialists.
- Snacks:Limited-preparation items with extended shelf stability. Airport and motorway concessions in France and Spain rely on snack portfolios for captive audience revenue during off-peak dining hours.
- Desserts:Sweet items with premium pricing potential and specialized ingredient sourcing. Dairy input volatility from Black Sea supply disruptions compresses margin predictability across bakery and patisserie categories.
Food holds installed capacity. Beverages is rotating up the share rankings.
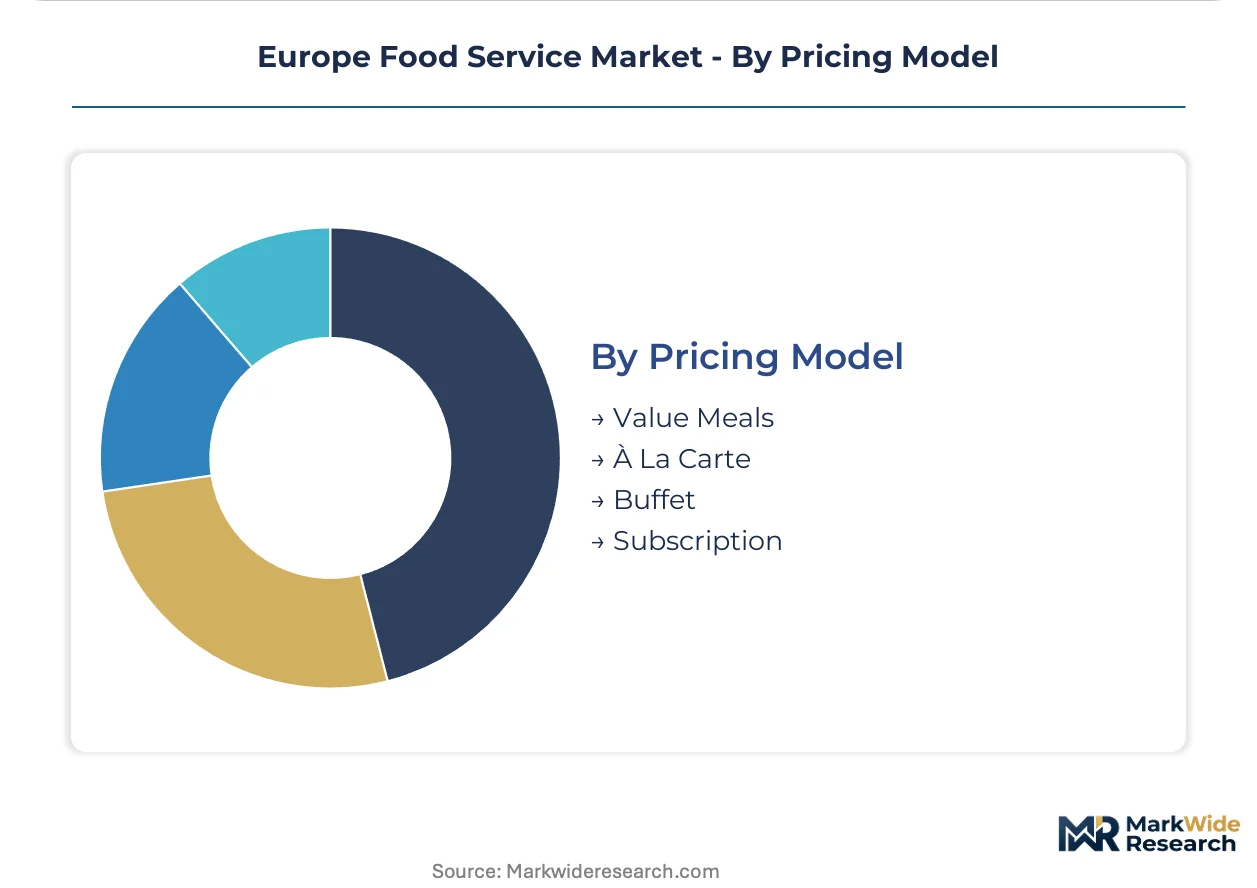
Pricing Model:
Revenue recognition timing and customer commitment depth differentiate pricing structures across European contract types.
- Value Meals:Bundled offerings at fixed price points. Quick Service Restaurants in UK and German markets deploy these to simplify decision-making and accelerate throughput during peak hours.
- À La Carte:Itemized pricing allowing customization and upselling. Full-service formats in France and Italy rely on this structure to capture experience premiums and wine pairing revenue.
- Buffet:Fixed-price unlimited consumption with self-service logistics. Corporate canteens and hotel breakfast operations in Scandinavia favor this model for labor efficiency and predictable food cost ratios.
- Subscription:Recurring payment for defined meal allowances or delivery commitments. Technology sector employers in Netherlands and Ireland are piloting per-employee meal subsidies replacing fixed site-based guarantees.
À La Carte holds installed capacity. Subscription is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German urban corridors while Spanish motorway concessions operate on thinner margin structures. This asymmetry reflects divergent labor cost trajectories and concession contract tenures across the continent.
Germany
Quick Service Restaurant throughput dominates at Autobahn interchanges and retail park clusters. The EU Green Deal packaging mandates accelerate reusable container infrastructure investment across Berlin and Hamburg logistics networks. Frankfurt's corporate catering contracts fragment as hybrid work patterns stabilize.
United Kingdom
Ghost kitchen networks compress real estate costs in London's dense urban corridors. GDPR obligations intersect with digital ordering data flows, complicating customer analytics for delivery-optimized operators. Manchester and Birmingham transport hubs see captive audience revenue concentration.
France
Full-service dining corridors in Paris and Lyon sustain experience premiums against labor and rent burdens. ANSM and national health inspectorates enforce EFSA nutritional claim substantiation for menu transparency. Hospital and university procurement frameworks maintain long-term catering contracts with nutritional compliance mandates.
Italy
Espresso culture and tourism corridors in Rome and Milan drive beverage-forward format density. REACH chemical compliance extends supplier onboarding timelines for food-contact materials. Autogrill SpA anchors travel channel concessions across motorway stops and airport terminals.
Netherlands
Corporate clients unbundle integrated facilities management contracts for standalone catering procurement with shorter renewal cycles. Technology sector employers pilot per-employee meal subsidies replacing fixed site-based guarantees. Amsterdam and Rotterdam co-working districts concentrate cafe demand around transport nodes.
Europe Food Service Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical positioning. The European food service vendor base organizes around contract caterers with institutional footprints, travel channel concessionaires, and QSR format standardizers. Three archetypes dominate: multi-service facilities integrators bundling food with maintenance, delivery-optimized production networks, and captive-audience concession operators. Competitive moves concentrate on M&A for geographic density and strategic partnerships for circular supply chain infrastructure.
Among UK-based operators, Compass Group and SSP Group occupy positions within the institutional and travel channel tiers respectively. Sodexo exemplifies the integrated facilities management archetype with bundled service offerings. Autogrill SpA anchors the travel concession segment across Mediterranean motorway and airport networks.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Compass Group |
| Sodexo |
| Elior Group |
| Yum! Brands |
| Autogrill SpA |
| Greggs |
| SSP Group |
| Restaurant Brands International |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in ghost kitchen networks across German urban corridors is compressing supplier pricing power while accelerating contract renegotiations for delivery-optimized operators. This utilization squeeze feeds directly into menu pricing strategies and procurement leverage across the continent.
Pricing Analysis
The customization-premium spread between configured-to-order catering contracts and standardized QSR menus defines pricing architecture across Europe. Subscription-based corporate meal subsidies command premium positioning against per-transaction à la carte formats. Price differentiation rests on HACCP certification tiers and cold-chain integrity guarantees rather than brand heritage alone. Pricing pressure stems from wheat and dairy input volatility tied to Black Sea supply disruptions, with quick-service formats in UK retail parks showing highest price sensitivity while Paris full-service dining maintains lowest.
Supply Chain Analysis
Tariff exposure between EU member states and Black Sea grain exporters dominates supply chain risk assessment for European food service operators. Ingredient sourcing concentrates in France, Germany, and Italy for prepared meal components, with secondary dependence on Polish and Romanian agricultural outputs. Raw material dependencies center on wheat flour, dairy proteins, and vegetable oils for core menu categories. Single-source vulnerability in F-gas compliant refrigeration equipment extends replacement timelines. Distribution runs through consolidated wholesale networks serving multi-site contract caterers and independent restaurant clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European food service market rewards operators who control scarce capabilities in HACCP-certified cold-chain logistics and EFSA-compliant nutritional claim substantiation. Talent concentration in Western European labor markets creates persistent bottlenecks for Central and Eastern European expansion.
For Market Incumbents: Build switching-cost moats through integrated facilities management bundling that locks corporate clients into multi-year cleaning, maintenance, and catering contracts. Anchor defensive positioning with backward integration into reusable container infrastructure ahead of EU Green Deal packaging mandates. Deepen channel control through exclusive airport and motorway concession renewals in Spain and Italy before transport hub modernization peaks. For New Entrants and Emerging Players: Build out ghost kitchen density in underserved Polish and Romanian urban corridors where branded food service penetration remains limited. Target second-tier cities with rising disposable income and constrained HACCP auditor supply. Penetrate through delivery-aggregator partnerships that minimize front-of-house capital requirements while capturing demand signals for dynamic menu optimization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-chain refrigeration fleets as F-Gas Regulation phase-down mandates accelerate equipment replacement cycles. Long-term viability favors contract caterers with institutional footprints in healthcare and education over discretionary full-service formats. Watch CSRD supply chain disclosure compliance as the signal indicating which operators have invested in farm-to-fork traceability infrastructure versus laggards facing audit risk.| Strategic Initiative | Industry Significance |
|---|---|
| Circular Supply Partnership | Reusable container infrastructure locks in corporate clients ahead of EU Green Deal enforcement. |
| Ghost Kitchen Network Expansion | Delivery-optimized production compresses real estate costs in dense German and UK urban corridors. |
| AI-Driven Demand Forecasting | Machine learning convergence with POS data reduces waste for multi-site contract caterers. |
| Transport Hub Concession Renewal | Captive audience revenue streams in Spanish and Dutch airports limit competitive pressure. |
| CSRD Compliance Infrastructure | Farm-to-fork traceability systems create advisory revenue from operators facing mandatory emissions disclosure. |
Research Methodology
Desk research of EU regulatory filings, EFSA nutritional claim databases, and national health inspectorate protocols preceded structured interviews with contract catering procurement directors, ghost kitchen operations managers, HACCP certification auditors, and cold-chain logistics coordinators. Primary fieldwork validated input cost assumptions with wholesale food distributors and equipment procurement leads across Germany, France, and Italy. Secondary sources incorporated customs trade data for wheat and dairy imports, REACH chemical compliance registrations, and concession contract disclosures from transport authorities. Bottom-up site-level capacity estimates triangulated against top-down market value reconstructions.
Forecast assumptions held hybrid work stabilization patterns and EU Green Deal implementation timelines fixed across the analysis window while varying commodity price scenarios and ghost kitchen penetration rates. Segmentation dimensions modeled include service format, end-user contract type, product category margin profile, and pricing model structure. CAGRs derived from weighted average growth across segment-level demand drivers, with specific inputs for F-Gas Regulation compliance costs and CSRD reporting adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by delivery-aggregator platforms or rapid ghost kitchen overbuild would shift outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Stirrers Market
Food Service
Steam Tables and Food Well Market
Food Service
Brazil Foodservice Market
Food Service
Galley Equipment Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Cambodia Foodservice Market
Food Service
Airport Quick Service Restaurants Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
South America Free from Food Market
Food Service
Bahrain Food Service Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
Flat Top Grills Market
Food Service
Sandwich Toasters Market
Food Service
Oman Food Service Market
Food Service
Ice Cream Carts Market
Food Service
Gourmet Street Food Market