
 Clear Ice Maker Market | 2026-2036
Clear Ice Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Clear Ice Maker Market Analytics
North American commercial kitchen equipment manufacturing is consolidating as clear ice production shifts toward specialized OEMs with captive refrigeration engineering. Hoshizaki Corporation leverages its vertically integrated compressor technology to dominate the premium under-counter segment. Scotsman Ice Systems sustains competitive positioning through proprietary scale-reduction systems that extend equipment lifecycle in hard-water regions.
Clear ice makers produce transparent, bubble-free ice through directional freezing or circulating water systems operating at precise temperature gradients between negative twelve and negative six degrees Celsius. The equipment serves commercial foodservice and residential markets where visual presentation and slower melt rates justify capital investment. Under-counter ice makers anchor the value pool due to permanent installation requirements and higher average selling prices in restaurant and hotel deployments. Portable ice makers compete primarily on convenience metrics for home users, while smart technology features represent the fastest-expanding specification tier as connectivity-enabled diagnostics reduce service dispatch costs.
The EPA Energy Star program and DOE commercial refrigeration standards shape minimum efficiency thresholds and refrigerant transition timelines for equipment sold in the United States. California Title 20 appliance regulations and pending F-gas phase-down requirements in multiple state jurisdictions are forcing compressor redesigns and alternative refrigerant qualification cycles. Stakeholders must monitor state-level building electrification mandates and refrigerant supply chain constraints to calibrate manufacturing capacity and distribution inventory.
Market Dynamics
Compressor miniaturization and refrigerant transition mandates are restructuring competitive economics in clear ice equipment, favoring OEMs with captive refrigeration engineering over assembly-dependent vendors.
Growth Catalysts
- EPA Energy Star certification:Federal efficiency thresholds accelerate replacement cycles in commercial foodservice installations. Equipment upgrades concentrate in California, Texas, and Florida metropolitan corridors.
- High-end cocktail bar expansion:Craft beverage establishments in the United States prioritize visual ice presentation. Directional freezing systems command permanent installation commitments.
- Smart diagnostics integration:Connectivity-enabled remote monitoring reduces service dispatch costs. Restaurant and hotel operators capture operational efficiency gains.
Market Restraints
- Refrigerant supply constraints:Pending F-gas phase-down requirements compress alternative refrigerant availability. Compressor redesign cycles extend qualification timelines.
- Hard-water equipment degradation:Scale accumulation in circulating water systems demands specialized maintenance protocols. Lifecycle costs escalate in mineral-rich municipal supply regions.
- Capital intensity threshold:Under-counter installation requirements and permanent plumbing connections exclude price-sensitive residential segments. Portable alternatives sacrifice clarity performance.
Strategic Opportunities
- Building electrification mandates:State-level decarbonization policies in California and New York create specification tailwinds for electric refrigeration systems. Electrification compliance drives equipment refresh decisions.
- Hotel chain standardization:Premium hospitality brands seek property-wide ice quality consistency. Brand-level procurement agreements consolidate vendor relationships.
- Residential smart kitchen convergence:Integration with connected appliance ecosystems opens specification channels. Voice-activated diagnostics and automated maintenance scheduling differentiate premium residential units.
Industry Challenges
- Refrigeration engineering talent scarcity:Specialized compressor design and alternative refrigerant chemistry expertise concentrates among legacy OEMs. New entrants face recruitment barriers in thermal systems engineering.
- Multi-jurisdictional certification complexity:California Title 20 appliance regulations, DOE commercial refrigeration standards, and state-specific building codes create overlapping compliance requirements. Certification timelines extend market entry durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clear Ice Maker Market |
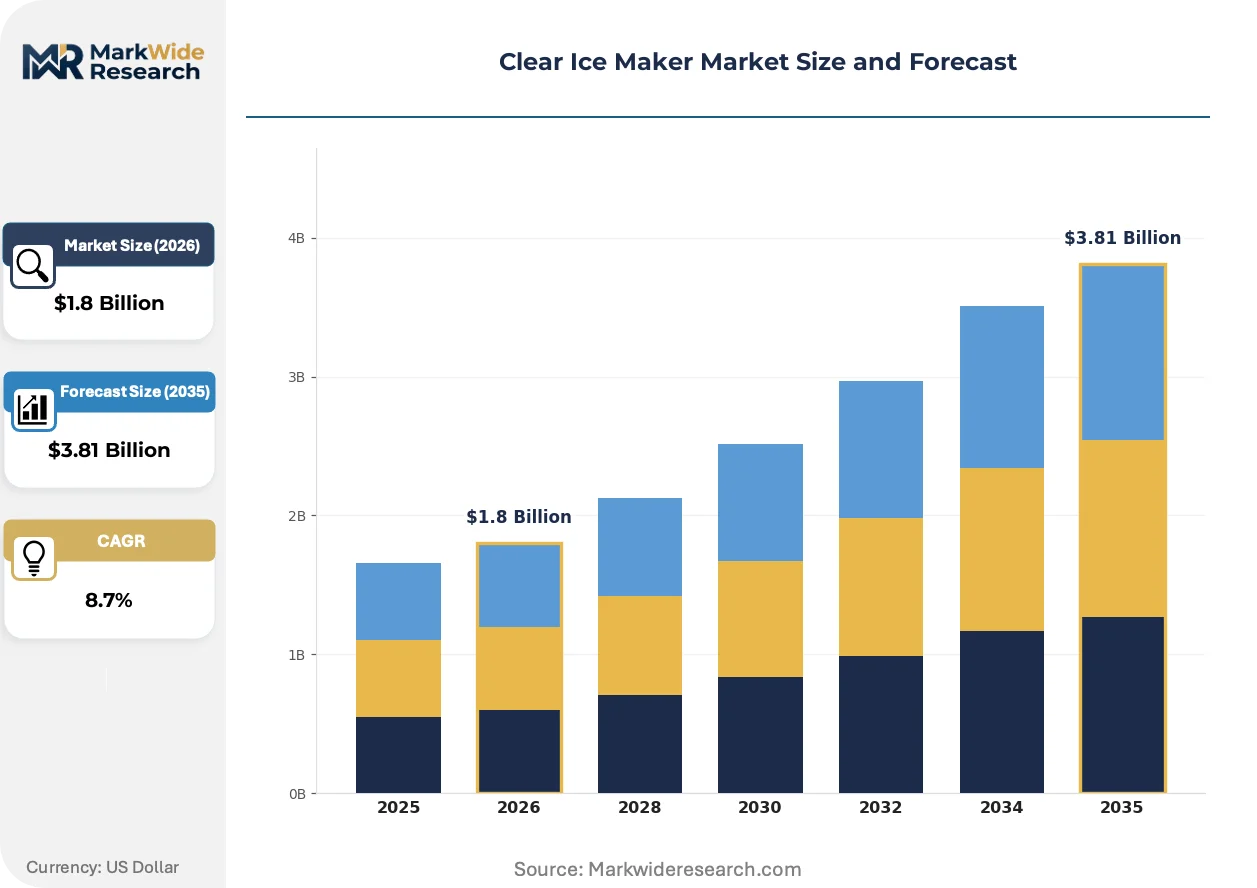
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Ice Makers, Under-Counter Ice Makers, Commercial Ice Machines, Portable Ice Makers End User: Restaurants, Bars, Hotels, Home Users Distribution Channel: Online Retailers, Specialty Stores, Wholesale Distributors, Direct Sales Feature: Self-Cleaning, Energy-Efficient, Fast Ice Production, Smart Technology |
| Companies Covered | Hoshizaki Corporation, Manitowoc Ice, Scotsman Ice Systems, Ice-O-Matic, Cornelius Inc., Maxx Ice, U-Line Corporation, NewAir, Welbilt Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clear Ice Maker Market Evolving Landscape
Directional freezing architectures and refrigerant chemistry advances are compressing incumbent technology margins while connectivity specifications rewrite procurement evaluation criteria.
Directional freezing technology produces transparent ice through controlled temperature gradients between negative twelve and negative six degrees Celsius. Premium restaurant and hotel operators are adopting circulating water systems at accelerated replacement cycles. This precision thermal control is overtaking conventional batch-freeze methods in specification-driven commercial segments.
The EPA Energy Star program and DOE commercial refrigeration standards enforce minimum efficiency thresholds and refrigerant transition timelines. Equipment manufacturers face concurrent compressor redesigns and alternative refrigerant qualification cycles. Under-counter installations in California metropolitan markets experience the most acute compliance pressure due to overlapping Title 20 regulations.
Buyers now prioritize total cost of ownership metrics over upfront equipment expenditure. Restaurant chains and hospitality groups are consolidating vendor relationships through multi-property service agreements. This specification consolidation is most visible in Texas and Florida metropolitan markets where high-volume commercial deployments concentrate procurement leverage.
Clear Ice Maker Market Segmentation
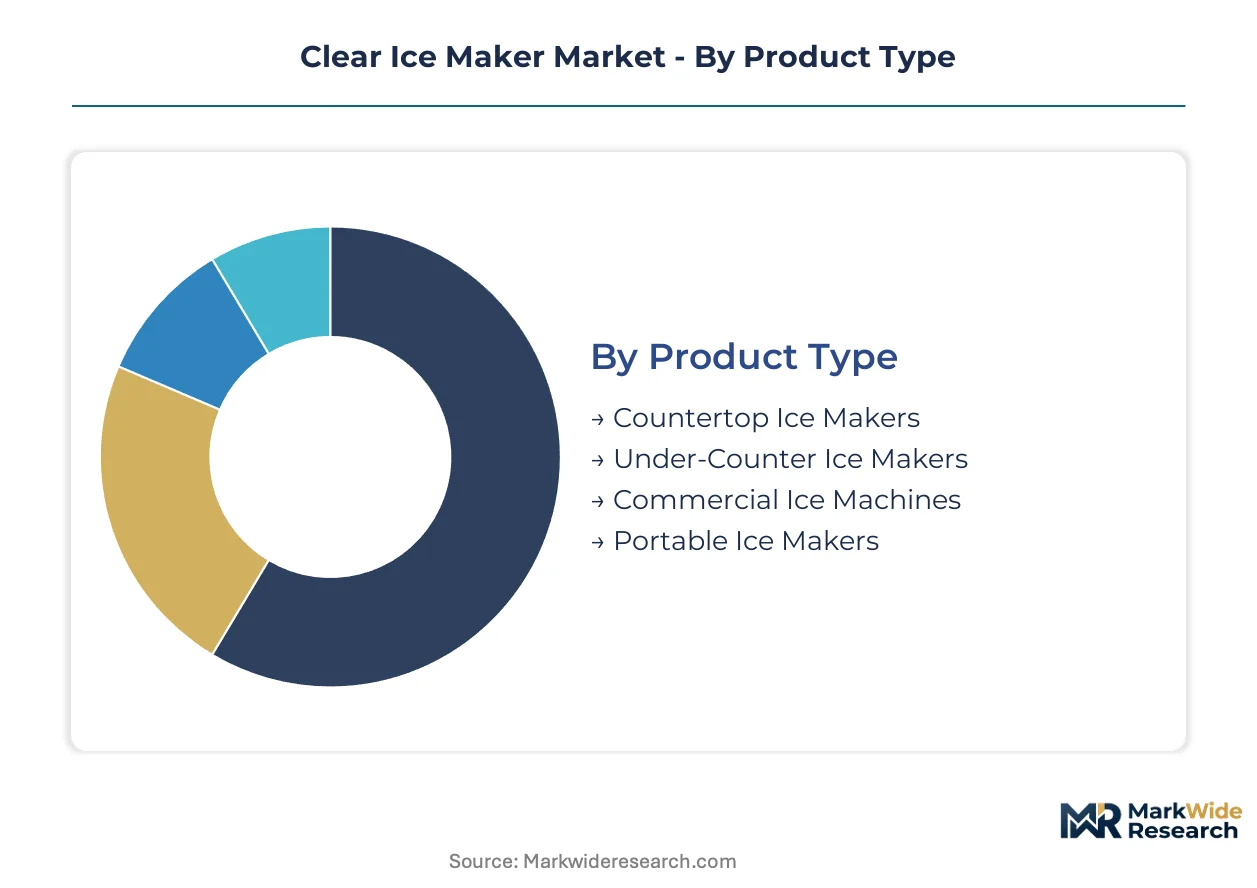
Clear ice maker segmentation reveals how certification burdens, installation complexity, and connectivity specifications fragment procurement patterns across commercial and residential channels. Equipment categories face divergent compliance timelines under EPA Energy Star and state-level appliance regulations.
Product Type:
EPA Energy Star certification applies differentially across product types, with under-counter and commercial units facing the most stringent efficiency thresholds and refrigerant transition mandates.
- Under-Counter Ice Makers:Permanent installation systems with integrated plumbing connections and directional freezing architectures. Demand concentrates in California, Texas, and Florida metropolitan markets where high-end cocktail bars and craft beverage establishments prioritize visual ice presentation and slower melt rates.
- Commercial Ice Machines:High-capacity circulating water systems operating at precise negative twelve to negative six degrees Celsius temperature gradients. Hotel chains in premium hospitality segments drive procurement consolidation through multi-property service agreements that capture operational efficiency gains.
- Countertop Ice Makers:Compact units targeting residential users with limited installation requirements.
- Portable Ice Makers:Convenience-focused mobile units competing primarily on accessibility metrics for home users.
Under-counter ice makers sit at the top of the volume ranking, with commercial ice machines climbing the fastest.
End User:
Customer type determines pricing tolerance and service contract attachment rates, with commercial operators accepting premium positioning for total cost of ownership advantages.
- Restaurants:Full-service establishments requiring consistent ice quality for beverage programs and food display applications. California, Texas, and Florida metropolitan corridors concentrate replacement cycles as EPA Energy Star thresholds accelerate equipment upgrades.
- Hotels:Premium hospitality brands seeking property-wide ice quality standardization through brand-level procurement agreements. Smart diagnostics integration reduces service dispatch costs across multi-property portfolios.
- Bars:Craft cocktail establishments prioritizing directional freezing systems for visual presentation.
- Home Users:Residential buyers trading clarity performance for convenience in portable alternatives.
Restaurants command the largest installed base, with hotels expanding most quickly through chain standardization mandates.
Distribution Channel:
Channel selection correlates with customer scale and technical support requirements, fragmenting margin structures across transaction types.
- Wholesale Distributors:Primary channel for commercial foodservice deployments requiring installation coordination and ongoing maintenance protocols. Hard-water regions with mineral-rich municipal supplies demand specialized scale-reduction service attachments.
- Direct Sales:Vendor relationships consolidated through multi-property agreements with restaurant chains and hospitality groups. Texas and Florida metropolitan markets concentrate procurement leverage for high-volume commercial deployments.
- Specialty Stores:Showroom-based channels targeting premium residential and small commercial buyers.
- Online Retailers:Convenience-focused channel for portable and countertop segments with limited technical support requirements.
Wholesale distributors maintain the deepest commercial penetration, with direct sales gaining share fastest through hospitality consolidation.
Feature:
Feature specification intensity varies by customer sophistication, with commercial operators prioritizing diagnostic capabilities and regulatory compliance.
- Smart Technology:Connectivity-enabled remote monitoring and voice-activated diagnostics. Restaurant and hotel operators in connected appliance ecosystems capture automated maintenance scheduling and reduced service dispatch costs.
- Energy-Efficient:EPA Energy Star qualification and DOE commercial refrigeration standard compliance. California Title 20 regulations and pending F-gas phase-down requirements force compressor redesigns and alternative refrigerant qualification cycles.
- Self-Cleaning:Automated maintenance protocols addressing scale accumulation in circulating water systems.
- Fast Ice Production:Accelerated batch-freeze capabilities for high-turnover commercial environments.
Energy-efficient specifications dominate commercial procurement, with smart technology gaining specification share fastest as connectivity rewrites evaluation criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers are relocating assembly operations to jurisdictions with streamlined refrigerant certification timelines, exploiting regulatory-arbitrage gaps between California's Title 20 mandates and more permissive state-level appliance standards elsewhere in the United States.
California
Los Angeles and San Francisco metropolitan corridors concentrate demand from craft cocktail bars and premium hospitality properties. The California Energy Commission enforces Title 20 appliance efficiency regulations that exceed federal EPA Energy Star thresholds. Directional freezing system deployments accelerate in Orange County and San Diego as hard-water scale-reduction protocols become standard specification requirements.
Texas
Houston and Dallas-Fort Worth hotel chains drive procurement consolidation through multi-property service agreements. The Texas Commission on Environmental Quality administers refrigerant handling certifications that align with federal EPA Section 608 requirements. Austin's expanding beverage program culture anchors under-counter installation growth in the central Texas corridor.
Florida
Miami and Tampa metropolitan markets experience elevated replacement cycles due to coastal humidity degradation of compressor components. The Florida Department of Environmental Protection enforces building electrification incentives that accelerate equipment refresh decisions. Orlando's hospitality density supports the highest per-capita commercial ice machine deployment rates in the southeastern United States.
New York
Manhattan and Brooklyn craft beverage establishments prioritize visual ice presentation for cocktail program differentiation. The New York State Department of Environmental Conservation implements refrigerant phase-down schedules that compress alternative chemistry qualification timelines. Upstate Rochester and Buffalo manufacturing facilities supply compressor components to OEMs serving the northeastern corridor.
Illinois
Chicago's restaurant density sustains wholesale distributor channel penetration for commercial foodservice deployments. The Illinois Environmental Protection Agency coordinates with federal DOE standards on commercial refrigeration equipment efficiency thresholds. Suburban Schaumburg and Naperville clusters host service technician training centers addressing smart diagnostics integration requirements.
Clear Ice Maker Market Competitive Landscape
Japanese producers anchor the premium-tier refrigeration engineering segment; United States specialists hold positions in scale-reduction system integration and regional service networks. Market structure consolidates around three to four vertically integrated OEMs with captive compressor technology, while assembly-dependent vendors face margin compression from refrigerant transition mandates. Strategic archetypes include: (1) integrated refrigeration engineers with in-house thermal systems capability, (2) regional service aggregators bundling installation and maintenance contracts, and (3) connectivity-platform licensors enabling smart diagnostics standardization. Dominant competitive moves encompass compressor redesign partnerships with alternative refrigerant suppliers and multi-year hospitality procurement agreements locking in replacement-cycle visibility.
Among Japanese refrigeration conglomerates, Hoshizaki Corporation exemplifies the integrated engineering archetype through its captive compressor technology and premium under-counter positioning. Scotsman Ice Systems occupies a position within the scale-reduction specialization tier, addressing hard-water degradation protocols in mineral-rich municipal supply regions. Manitowoc Ice anchors the commercial high-capacity segment, representing the hospitality-consolidation vector through chain-level procurement standardization capabilities.
| Leading Market Players |
|---|
| Hoshizaki Corporation |
| Manitowoc Ice |
| Scotsman Ice Systems |
| Ice-O-Matic |
| Cornelius Inc. |
| Maxx Ice |
| U-Line Corporation |
| NewAir |
| Welbilt Inc. |
| Others |
Value Network & Pricing Analysis
Captive compressor engineering at Japanese refrigeration conglomerates anchors both supply security and pricing power in premium under-counter segments. Hoshizaki Corporation's in-house thermal systems capability insulates margin structures from refrigerant transition volatility while assembly-dependent vendors absorb cost compression.
Pricing Analysis
Distributor margin layers in wholesale channels absorb the steepest cost compression as EPA Energy Star qualification cycles extend equipment refresh timelines. Three-tier pricing structure across premium directional freezing systems, standard circulating water architectures, and economy portable units stratifies by certification grade and after-sales service bundling. Price erosion runs through mid-tier commercial segments where hard-water scale-reduction protocols become mandatory specification requirements. Home users exhibit highest price sensitivity, trading clarity performance for convenience in portable alternatives, while hotel chains accept premium positioning for total cost of ownership advantages through multi-property service agreements.
Supply Chain Analysis
Regional distribution centers in Texas and Florida metropolitan markets concentrate inventory buffers against coastal humidity degradation risks for compressor components. Manufacturing gravity centers on Japan for captive refrigeration engineering, the United States for scale-reduction system integration, and China for component electronics. Raw material dependencies span copper tubing for refrigerant lines, specialized compressor alloys, and connectivity module chipsets. Single-source vulnerability concentrates in alternative refrigerant chemistry suppliers facing F-gas phase-down qualification bottlenecks. Distribution runs through wholesale distributors coordinating installation and maintenance protocols for commercial foodservice deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in this market rests on compressor miniaturization cost curves and premium hospitality procurement consolidation. Smart diagnostics integration commands pricing premiums while reducing service dispatch overhead.
For Market Incumbents:Cement captive refrigeration engineering advantages through alternative refrigerant qualification partnerships with chemistry suppliers. Deepen backward integration into compressor component manufacturing to offset supply chain risk from F-gas phase-down timelines. Consolidate multi-year hospitality procurement agreements locking in replacement-cycle visibility against emerging connectivity-platform licensors.
For New Entrants and Emerging Players:Begin with white-space targeting of residential smart kitchen convergence segments where voice-activated diagnostics and automated maintenance scheduling remain underdeveloped. Austin and Nashville metropolitan corridors offer penetrable geographic entry points with expanding craft beverage cultures and less entrenched incumbent service networks. Pursue direct-to-consumer online retail channels bypassing wholesale distributor margin layers for portable and countertop segments.
For Investors and Strategic Acquirers:Roll-up economics work for regional service aggregators because hard-water scale-reduction protocol expertise concentrates in fragmented local maintenance providers. Long-term viability over the next decade hinges on electrification compliance capabilities and connected appliance ecosystem integration. Monitor California Title 20 regulatory expansion into additional state jurisdictions as the primary inflection indicator for accelerated equipment refresh demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Refrigerant Qualification Partnership | Accelerates compressor redesign cycles ahead of EPA F-gas phase-down mandates. |
| Multi-Property Hospitality Service Agreement | Locks in replacement-cycle visibility with premium hotel chains in Texas and Florida. |
| Smart Diagnostics Platform Integration | Reduces service dispatch costs through connectivity-enabled remote monitoring capabilities. |
| Hard-Water Scale-Reduction System Patent | Captures lifecycle revenue in mineral-rich municipal supply regions like California and Texas. |
| Building Electrification Compliance Certification | Positions equipment for state-level decarbonization procurement mandates in California and New York. |
Research Methodology
Direct dialogue with commercial kitchen equipment procurement managers, refrigeration engineering directors, hospitality operations executives, and aftermarket service technicians grounded qualitative findings. Secondary validation drew from EPA Energy Star certification databases, DOE commercial refrigeration standard filings, California Energy Commission Title 20 regulatory records, and hospitality industry procurement surveys. Bottom-up equipment shipment data triangulated against top-down market size estimates derived from compressor manufacturer production disclosures.
Bottom-up segmentation modeling across product type, end user, distribution channel, and feature specifications generated volume and value outputs across the projection horizon. Analytical framework incorporated installation base depreciation curves, replacement cycle acceleration factors from regulatory compliance mandates, and smart technology specification adoption trajectories. CAGRs were derived from regression analysis of historical shipment trends against efficiency standard implementation timelines.
Several conditions sit outside the modeled scope, including potential refrigerant supply chain disruptions from geopolitical trade restrictions and unanticipated state-level building electrification mandate accelerations. Forecasts reflect documented assumptions regarding EPA Energy Star threshold evolution and F-gas phase-down implementation pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Airport Quick Service Restaurants Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Kuwait Food Service Market
Food Service
Commercial Ice Dispenser Market
Food Service
Commercial Cutlery Market
Food Service
Europe Food Away from Home Market
Food Service
Food Delivery Services Market
Food Service
Foodservice Coffee Market
Food Service
Flat Top Grills Market
Food Service
United Kingdom Foodservice Market
Food Service
Chile Food Delivery Market
Food Service
South Africa Fast Food Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Bahrain Food Service Market
Food Service
United States Foodservice Market