
 Plates Market | 2026-2036
Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Plates Market Outlook
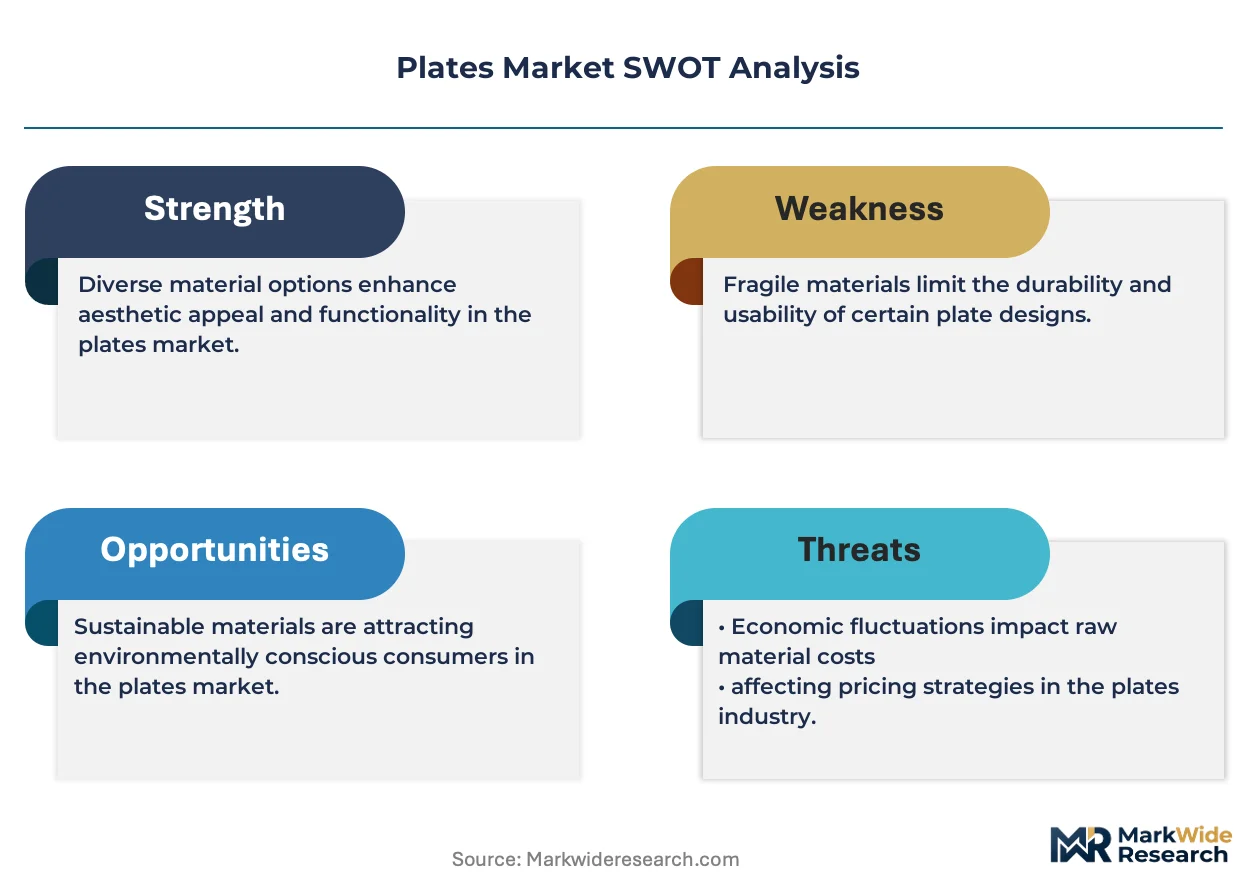
Vietnam is narrowing its cost advantage against Chinese ceramic plate exports as energy and logistics expenses rise across Southeast Asia. Meyer Corporation Group leverages vertical integration in stainless steel cookware to sustain margin stability across metal plate categories. Inter IKEA Group anchors flat-pack logistics expertise to dominate affordable dinnerware distribution in European retail. Waterford Wedgwood differentiates through heritage crystal and fine bone china positioning in luxury hospitality channels.
Plates are rigid, flat-surfaced vessels manufactured from ceramic clays, soda-lime glass, thermoformed polymers, or rolled metal alloys, with diameters typically spanning fifteen to thirty centimeters and designed to contain prepared food during service and consumption. Ceramic plates undergo bisque firing at approximately nine hundred degrees Celsius followed by glaze application, yielding non-porous, heat-resistant surfaces suitable for microwave and dishwasher exposure. Dinner plates and serving plates command the largest volume share within product type segmentation, though salad plates and dessert plates generate disproportionate margin contribution in premium retail. Plastic plates face structural compression from material bans and corporate sustainability procurement policies, while metal plates sustain niche demand in camping, institutional catering, and South Asian household segments.
FDA food-contact substance regulations govern polymer and coating safety for plates distributed in the United States, while the EU REACH framework restricts heavy metal migration from ceramic glazes sold across Europe. BIS certification requirements in India enforce lead and cadmium limits on imported ceramic tableware, creating compliance barriers for unvetted suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and material traceability mandates as these regulatory layers increasingly determine market access and procurement qualification criteria.
Market Dynamics
State-level single-use plastic prohibitions across the United States are forcing food service operators to accelerate procurement of reusable ceramic and melamine formats, compressing demand for disposable alternatives and rewiring supplier qualification criteria toward material traceability.
Growth Catalysts
- FDA food-contact substance regulations:Stringent polymer safety standards in the United States are disqualifying unvetted Asian suppliers and consolidating procurement toward certified domestic and European manufacturers with established compliance documentation.
- Urban middle-class household upgrading:Indian consumers are shifting from traditional metal thalis to branded ceramic dinnerware as disposable incomes rise and organized retail penetration expands in tier-1 and tier-2 cities.
- Dine-in volume recovery:North American restaurant chains are rebuilding ceramic plate inventories to pre-pandemic levels, creating immediate pull-through demand for kiln-fired tableware with dishwasher durability.
Market Restraints
- Natural gas price volatility:Ceramic firing operations depend on consistent energy inputs, and European kiln operators face margin compression from fluctuating utility costs that resist pass-through pricing.
- Fujian province supply concentration:Chinese ceramic plate manufacturing clusters in Dehua and Chaozhou create geographic vulnerability to regional logistics disruptions and energy rationing mandates.
- EU REACH heavy metal migration limits:Cadmium and lead leaching thresholds for ceramic glazes impose testing burdens that exclude small-scale artisan producers from European market access.
Strategic Opportunities
- Extended producer responsibility frameworks:French and German packaging waste regulations are creating first-mover advantage for plate manufacturers offering take-back programs and closed-loop material recovery.
- Camping and outdoor recreation segments:Lightweight titanium and anodized aluminum plates are capturing demand from backcountry equipment retailers as wilderness participation rates climb in Western states.
- BIS certification arbitrage:Indian import standards for lead and cadmium limits create defensive moats for domestic ceramic producers against uncertified Chinese competitors.
Industry Challenges
- Glaze chemistry specialization:Ceramic manufacturers face acute shortages of technicians capable of formulating lead-free, high-temperature glazes that meet simultaneous FDA and EU compliance requirements.
- Kiln infrastructure retrofitting:Transitioning from gas-fired to electric tunnel kilns demands capital deployment that mid-scale producers struggle to finance without strategic partnerships.
- Material traceability system integration:Blockchain-based provenance tracking mandated by major hospitality procurement departments requires IT infrastructure that legacy ceramic workshops lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plates Market |
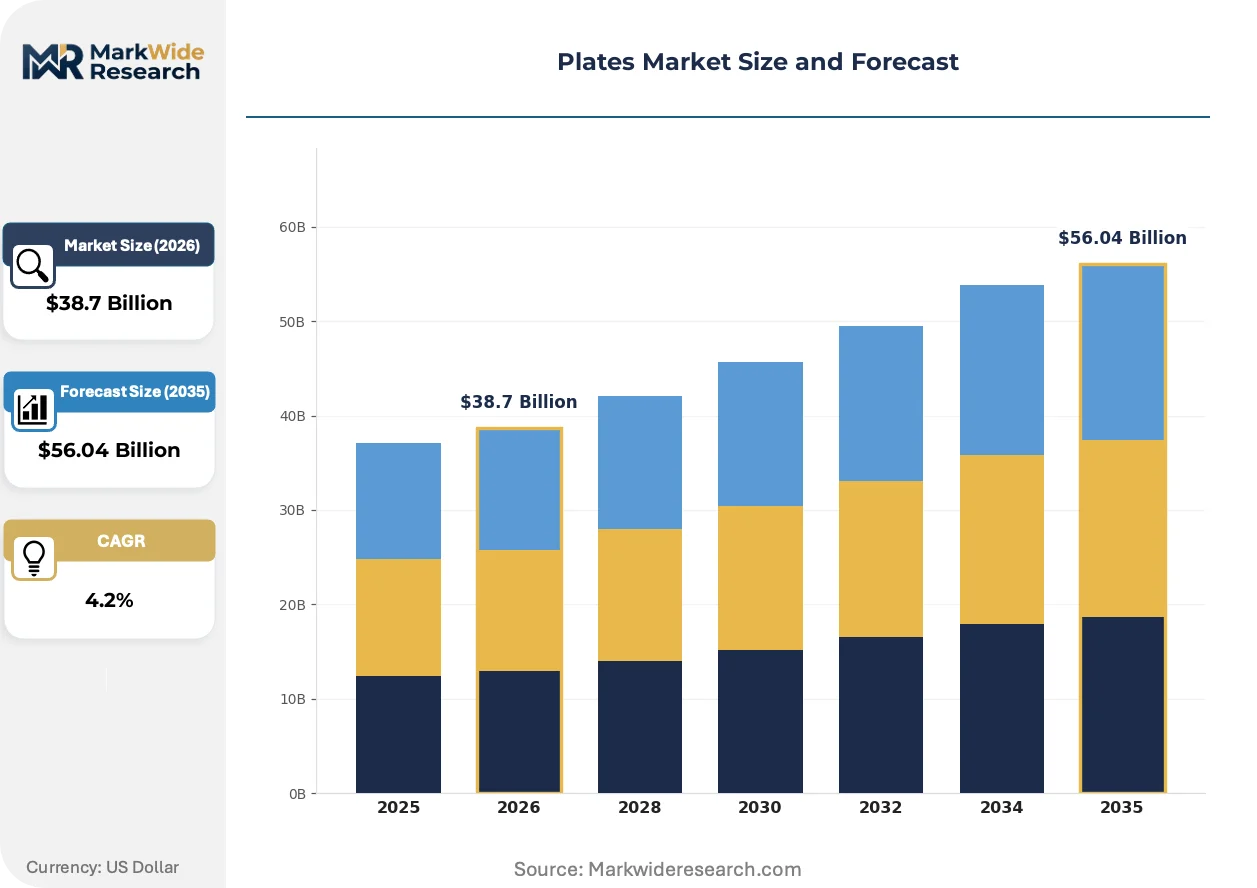
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Ceramic, Glass, Plastic, Metal Product Type: Dinner Plates, Serving Plates, Salad Plates, Dessert Plates End Use: Household, Commercial, Industrial, Food Service Design Style: Classic, Modern, Vintage, Artistic |
| Companies Covered | Tesco.com, Inter IKEA Group, Meyer Corporation Group, Bernardaud, Raynaud Limoges, Puiforcat, Waterford Wedgwood, Berry Global Inc., Dart Container Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plates Market Strategic Shifts
Digital manufacturing workflows and material science advances are compressing product development cycles while regulatory pressure on chemical safety is forcing reformulation across ceramic glaze chemistry. These forces are simultaneously elevating compliance costs and opening differentiation pathways for technically capable suppliers.
Advanced ceramic 3D printing is virtualizing traditional slip-casting and jiggering production methods for complex plate geometries and custom hospitality branding. Boutique hotel chains and Michelin-rated restaurant groups are adopting digitally fabricated tableware at pilot scale, attracted by rapid prototyping capabilities and elimination of mold storage costs. This technology is virtualizing the economics of short-run production, enabling batch sizes below fifty units to achieve unit economics previously requiring thousand-piece minimums.
EU REACH Annex XVII restrictions on cadmium and lead migration are compelling glaze reformulation across ceramic export facilities serving European hospitality and retail channels. Manufacturers in Portugal and Italy are investing in boron-alternative flux systems and zircon-based opacifiers to maintain surface aesthetics under tightened leaching thresholds. Fine dining establishments in France and Germany are responding by demanding third-party migration testing documentation as a standard procurement qualification step.
Direct-to-hospitality procurement platforms are compressing traditional distributor markups and accelerating specification cycles for institutional buyers. Restaurant groups in California and New York are bypassing legacy tableware distributors to negotiate volume contracts directly with Portuguese and Japanese ceramic manufacturers, extracting price concessions in exchange for multi-year exclusivity commitments. This channel disintermediation is most pronounced in the premium independent restaurant segment where chef-owners prioritize provenance storytelling over distributor convenience.
Plates Market Segmentation
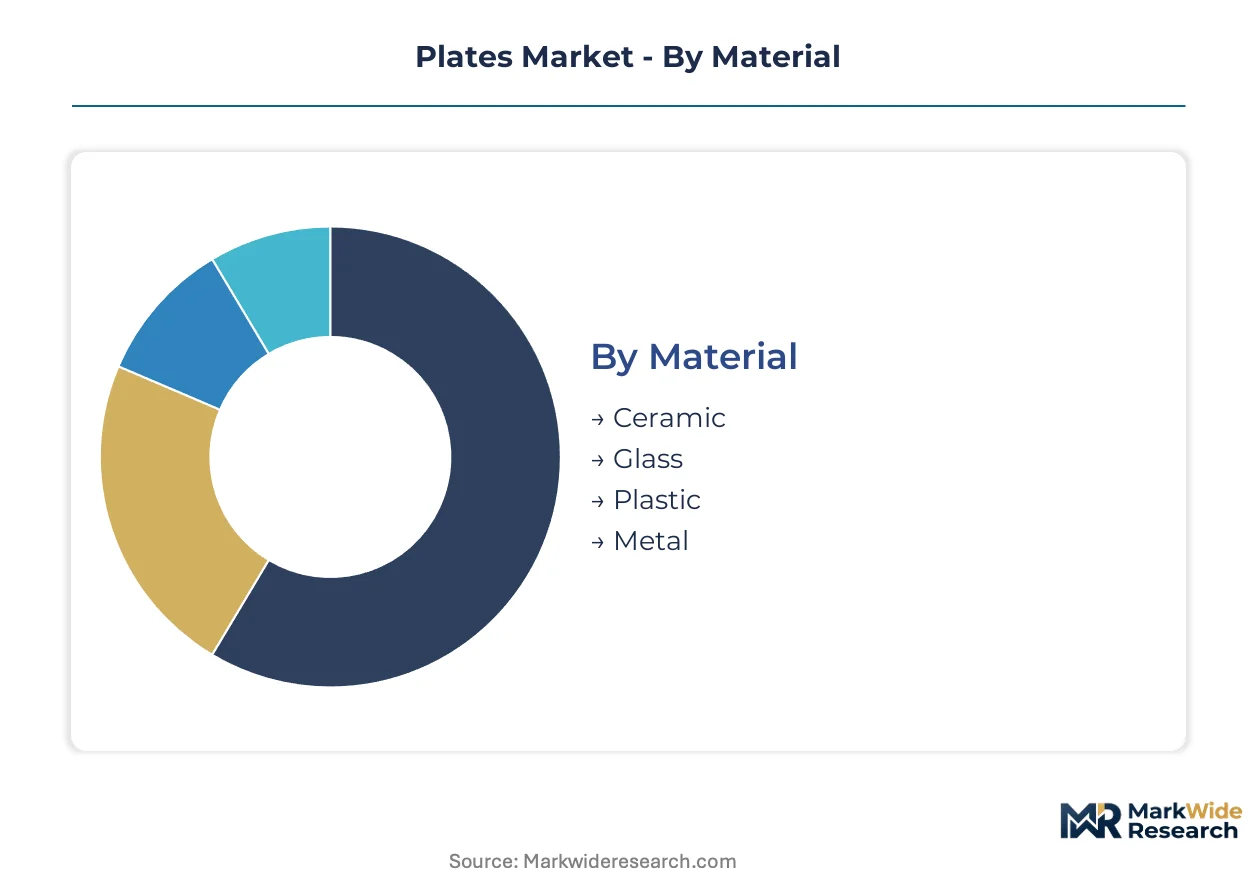
Segmentation in the Plates Market reveals how material chemistry, dimensional specifications, and end-use durability requirements create distinct procurement channels. Each dimension carries regulatory and cost implications that reshape supplier qualification criteria across hospitality, retail, and institutional buyers.
Material:
Cost tier determines thermal performance, regulatory compliance burden, and replacement cycle economics across procurement segments.
- Ceramic:Fired clay bodies with silica-based glazes deliver microwave-safe, dishwasher-durable surfaces. Demand concentrates in Indian and Chinese urban households upgrading from metal thalis, driven by rising disposable incomes and organized retail penetration.
- Glass:Soda-lime or tempered formulations offer transparency and chemical inertness. European hospitality channels favor glass for presentation aesthetics, though fragility limits volume in high-turnover food service operations.
- Plastic:Thermoformed polymers and melamine resins provide lightweight, unbreakable utility. State-level single-use plastic bans across the United States are compressing disposable formats while elevating reusable melamine in institutional catering.
- Metal:Rolled stainless steel, aluminum, and titanium alloys withstand extreme temperatures and mechanical stress. Camping equipment retailers in Western states are capturing titanium plate demand as backcountry participation climbs.
Ceramic holds installed capacity. Metal is rotating up the share rankings.
Product Type:
Application scope defines dimensional standards, portion alignment, and margin structure across tableware procurement.
- Dinner Plates:Twenty-five to thirty centimeter diameters accommodate entree presentation. North American restaurant chains are rebuilding inventories to pre-pandemic levels, creating immediate pull-through demand for kiln-fired durability.
- Serving Plates:Larger formats for shared dishes and buffet presentation command premium positioning. Michelin-rated restaurant groups in France and Germany specify custom dimensions for provenance storytelling.
- Salad Plates:Eighteen to twenty-two centimeter formats bridge appetizer and side service. Boutique hotel chains are adopting digitally fabricated short runs for property-specific branding.
- Dessert Plates:Compact fifteen to eighteen centimeter designs generate disproportionate margin contribution in premium retail. Fine dining establishments demand third-party glaze migration documentation as standard qualification.
Dinner Plates anchor volume throughput. Dessert Plates are climbing the fastest on margin contribution.
End Use:
Customer type dictates durability specifications, replacement frequency, and compliance documentation intensity.
- Household:Consumer procurement emphasizes aesthetic coordination and dishwasher compatibility. Indian tier-1 and tier-2 cities are shifting from traditional metal thalis to branded ceramic dinnerware as organized retail expands.
- Commercial:Hospitality and retail channels require batch consistency and supply reliability. California and New York restaurant groups are bypassing legacy distributors to negotiate direct contracts with Portuguese and Japanese manufacturers.
- Industrial:Canteen and institutional feeding operations prioritize cost minimization and breakage resistance. EU REACH heavy metal migration limits impose testing burdens that exclude small-scale artisan producers from European market access.
- Food Service:High-turnover restaurants and catering operations demand rapid replacement and stackability. FDA food-contact substance regulations are disqualifying unvetted Asian suppliers and consolidating procurement toward certified domestic and European manufacturers.
Household commands absolute unit volume. Food Service is expanding most quickly on dine-in recovery.
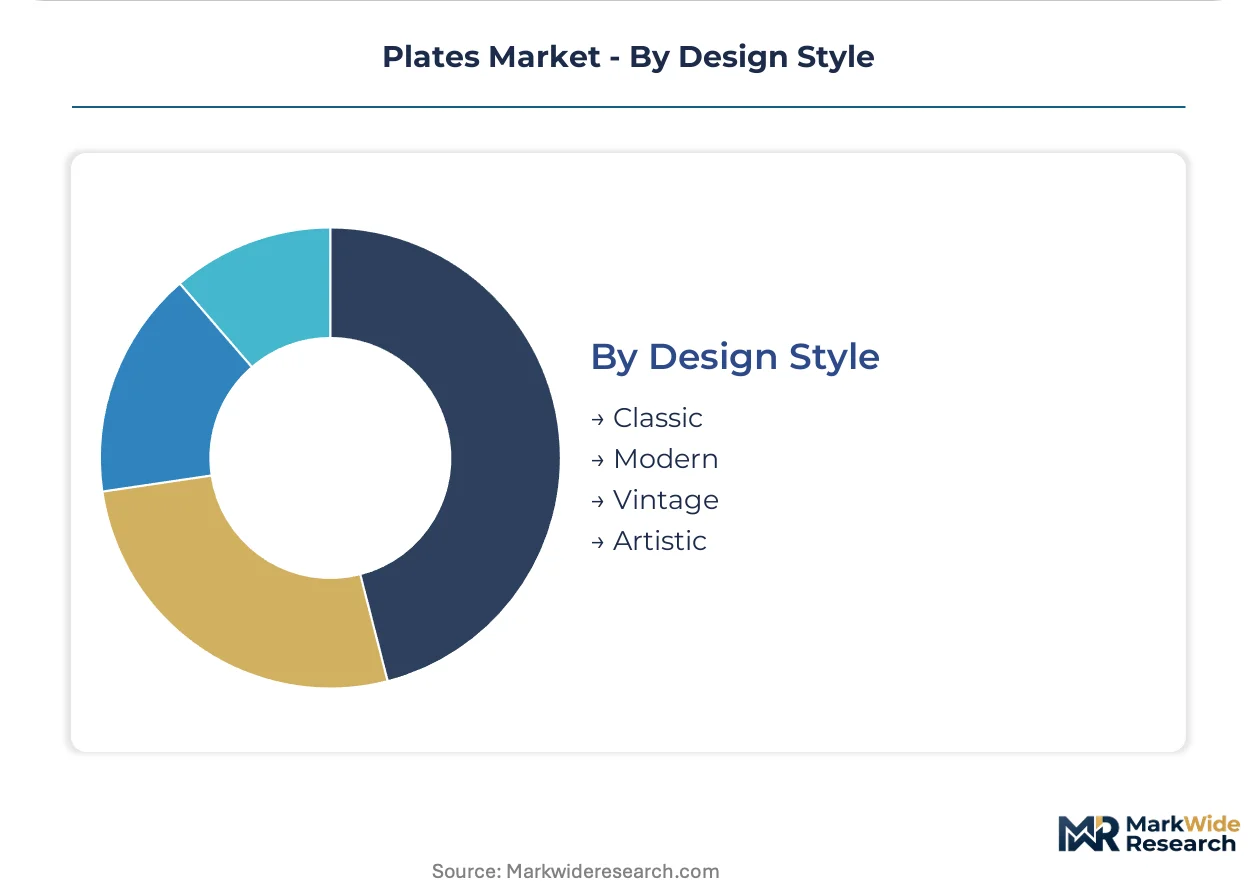
Design Style:
Maturity and aesthetic positioning separate commodity procurement from premium differentiation and heritage pricing.
- Classic:Traditional rim shapes and neutral palettes emphasize timeless coordination. Heritage crystal and fine bone china positioning in luxury hospitality channels sustains pricing power.
- Modern:Minimalist geometries and matte finishes align with contemporary interior design. Advanced ceramic 3D printing enables rapid prototyping for boutique hotel chains seeking property-specific differentiation.
- Vintage:Reproduction patterns and distressed glazes target nostalgia-driven consumer segments. Artisan workshops in Portugal and Italy are investing in boron-alternative flux systems to maintain aesthetics under tightened EU leaching thresholds.
- Artistic:Limited editions and hand-painted surfaces command collector premiums. Direct-to-hospitality procurement platforms are compressing traditional distributor markups for chef-owners prioritizing provenance storytelling.
Classic retains the largest installed base. Modern is gaining share fastest on digital manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households favor ceramic and melamine for daily dining while Indian consumers upgrade from metal thalis to branded dinnerware, creating divergent procurement patterns across geographies.
United States
California and New York restaurant groups are bypassing legacy distributors to negotiate direct contracts with Portuguese and Japanese ceramic manufacturers. FDA food-contact substance regulations disqualify unvetted Asian suppliers and consolidate procurement toward certified domestic and European manufacturers with established compliance documentation. Dehua and Chaozhou manufacturing clusters in China's Fujian province supply volume to mass-market retailers.
China
Urban middle-class households in tier-1 and tier-2 cities are upgrading from traditional metal thalis to branded ceramic dinnerware as organized retail penetration expands. The country's national standards regulator enforces GB standards on ceramic glaze safety for domestic and export markets. Dehua and Chaozhou ceramic manufacturing clusters face geographic vulnerability to regional logistics disruptions and energy rationing mandates.
India
Tier-1 and tier-2 cities are shifting from traditional metal thalis to branded ceramic dinnerware as disposable incomes rise and organized retail expands. BIS certification requirements enforce lead and cadmium limits on imported ceramic tableware, creating compliance barriers for unvetted suppliers. Domestic ceramic producers in Gujarat and Rajasthan leverage certification arbitrage against uncertified Chinese competitors.
Germany
French and German packaging waste regulations are creating first-mover advantage for plate manufacturers offering take-back programs and closed-loop material recovery. EU REACH Annex XVII restrictions on cadmium and lead migration compel glaze reformulation across ceramic export facilities serving European hospitality channels. Fine dining establishments in Berlin and Munich demand third-party migration testing documentation as standard procurement qualification.
France
Michelin-rated restaurant groups in France specify custom plate dimensions for provenance storytelling and heritage crystal positioning. EU REACH heavy metal migration limits impose testing burdens that exclude small-scale artisan producers from European market access. Limoges maintains concentration in fine bone china and heritage crystal manufacturing for luxury hospitality channels.
Plates Market Competitive Environment
Capability concentration sits with heritage manufacturers possessing glaze chemistry expertise; scale advantage sits with vertically integrated retailers controlling flat-pack logistics and mass-market distribution. The market structures around three tiers: luxury heritage houses, mass-market retailers with captive supply chains, and specialized metalware producers. Strategic moves center on direct-to-hospitality procurement platform development and kiln infrastructure retrofitting from gas-fired to electric tunnel systems.
Among heritage luxury manufacturers, Waterford Wedgwood and Bernardaud exemplify fine bone china and crystal positioning in hospitality channels. Inter IKEA Group anchors affordable dinnerware distribution through flat-pack logistics expertise in European retail. Meyer Corporation Group occupies a position in metal plate categories leveraging stainless steel cookware integration.
| Leading Market Players |
|---|
| Tesco.com |
| Inter IKEA Group |
| Meyer Corporation Group |
| Bernardaud |
| Raynaud Limoges |
| Puiforcat |
| Waterford Wedgwood |
| Berry Global Inc. |
| Dart Container Corporation |
| Others |
Value Chain & Pricing Dynamics
Dehua and Chaozhou ceramic manufacturing clusters in China's Fujian province concentrate global kiln-fired plate capacity, granting established exporters pricing leverage over buyers lacking alternative qualified suppliers. This geographic density enables coordinated glaze chemistry investments that smaller competitors cannot replicate, compressing margins for unvetted entrants while sustaining premium positioning for heritage manufacturers with FDA and EU REACH documentation.
Pricing Analysis
Long-term offtake contracts dominate procurement between North American restaurant chains and Portuguese ceramic manufacturers, insulating buyers from spot volatility in natural gas-fired kiln operations. Price differentiation rests on FDA food-contact certification tier and dishwasher durability guarantees, with California hospitality groups paying premiums for third-party migration testing. Cost compression in standard-grade ceramic intensifies as Vietnamese producers narrow the gap against Chinese exports on energy and logistics. Institutional catering operations exhibit highest price sensitivity, while Michelin-rated establishments prioritize provenance storytelling over unit economics.
Supply Chain Analysis
EU REACH heavy metal migration limits function as de facto export controls, restricting ceramic glaze chemistry flows to certified facilities in Portugal, Italy, and Japan. Raw material dependencies center on kaolin clay deposits, zircon-based opacifiers, and boron-alternative flux systems reformulated under tightened leaching thresholds. Single-source vulnerability concentrates in Fujian province energy rationing mandates. Distribution runs through direct-to-hospitality procurement platforms that disintermediate legacy tableware distributors for premium independent restaurant segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where FDA and EU REACH compliance documentation creates switching costs that lock in qualified suppliers and exclude artisan competitors lacking testing infrastructure.
For Market Incumbents: Harden glaze chemistry specialization advantages by investing in lead-free, high-temperature formulation R&D that simultaneous FDA and EU compliance demands. Expand kiln infrastructure retrofitting partnerships to mid-scale producers seeking capital for electric tunnel kiln transitions, capturing capacity control before energy rationing mandates deepen. Threat of Vietnamese cost convergence intensifies margin pressure in standard-grade segments.
For New Entrants and Emerging Players: India's tier-2 cities present underpenetrated demand as organized retail expands and BIS certification arbitrage protects domestic producers against uncertified Chinese competition. Camping and outdoor recreation segments in Western states offer white-space entry through lightweight titanium and anodized aluminum plate formats. Go-to-market through backcountry equipment retailers bypasses established hospitality distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic 3D printing specialists with digitally fabricated short-run capabilities for boutique hotel chains and chef-owned restaurants. Long-term viability hinges on extended producer responsibility framework readiness across French and German packaging waste regulations. Signal to monitor: blockchain-based material traceability mandates from major hospitality procurement departments forcing IT infrastructure investments that legacy workshops cannot finance.
| Strategic Initiative | Industry Significance |
|---|---|
| Glaze Chemistry Reformulation Investment | EU REACH Annex XVII compliance secures access to French and German hospitality channels. |
| Direct-to-Hospitality Platform Launch | Bypassing legacy distributors extracts price concessions from California restaurant groups. |
| Electric Tunnel Kiln Retrofit Partnership | Gas-to-electric transition hedges against Fujian province energy rationing disruption. |
| BIS Certification Arbitrage Expansion | Domestic Indian producers leverage lead and cadmium testing barriers against Chinese imports. |
| Titanium Plate Line Introduction | Backcountry participation growth in Western states captures premium outdoor recreation demand. |
Study Parameters
Initial hypotheses were tested against primary input from ceramic plant managers, hospitality procurement directors, glaze chemistry technicians, and retail category buyers, then refined through secondary validation against customs trade records, BIS certification databases, EU REACH Annex XVII regulatory filings, and SEC disclosures from vertically integrated cookware manufacturers. Bottom-up demand modeling across household, commercial, industrial, and food service end uses triangulated against top-down macroeconomic indicators.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation modeling across material chemistry, product type, end use, and design style dimensions. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and dine-in volume recovery patterns. Forecast inputs incorporated kiln capacity utilization rates, natural gas price volatility scenarios, and state-level single-use plastic ban implementation timelines.
Practitioners should monitor extended producer responsibility framework adoption and blockchain traceability mandate expansion for early signals of supplier qualification disruption. Forecasts reflect documented assumptions on ceramic firing energy costs and logistics corridor stability. Material shifts in EU REACH heavy metal migration thresholds or Fujian province energy policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Wok Market
Food Service
United States Food Truck Market
Food Service
Integrated Stove Market
Food Service
Full-Service Restaurants Market
Food Service
GCC Food Service Market
Food Service
Nigeria Food Service Market
Food Service
North America Food Service Disposable Market
Food Service
Egypt Food Service Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Commercial Sink Market
Food Service
India Quick Service Restaurant Market
Food Service
Self-Heating Hot Pot Market
Food Service
Bar Refrigeration Market
Food Service
Bottled Water Cooler Market
Food Service
Global Meal Kit Market
Food Service
Food Delivery Services Market