
 Switzerland Food Service Market | 2026-2036
Switzerland Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Food Service Market Insights
The EU Green Deal is pivoting procurement standards across Swiss contract catering. McDonald's Corporation leverages its supply chain scale to secure certified sustainable beef volumes for its Swiss franchise network. Valora anchors the convenience-led quick service segment through its dense kiosk and bakery footprint at transit nodes. Coop Gruppe Genossenschaft dominates institutional catering via its vertical integration from wholesale distribution to on-site kitchen operations.
Food service encompasses the commercial preparation and delivery of meals outside residential kitchens, spanning centralized production facilities, on-site cooking stations, and temperature-controlled logistics networks designed to serve portions exceeding fifty covers per hour. Quick Service and Full-Service Restaurants command the largest revenue pools, while Caterers serving Corporate and Healthcare clients capture the most stable margin structures due to long-term contractual pricing and predictable volume commitments.
Swissmedic oversees food safety compliance for prepared meals distributed through healthcare channels, while the Federal Food Safety and Veterinary Office enforces hazard analysis protocols across all commercial kitchens. The EU Green Deal's embodied carbon reporting requirements, adopted into Swiss commercial law through bilateral agreements, now oblige food service operators to document supply chain emissions or forfeit public sector contracts. Stakeholders must decide whether to build in-house procurement compliance teams or outsource carbon verification to specialized auditors before the next federal procurement cycle tightens.
Market Dynamics
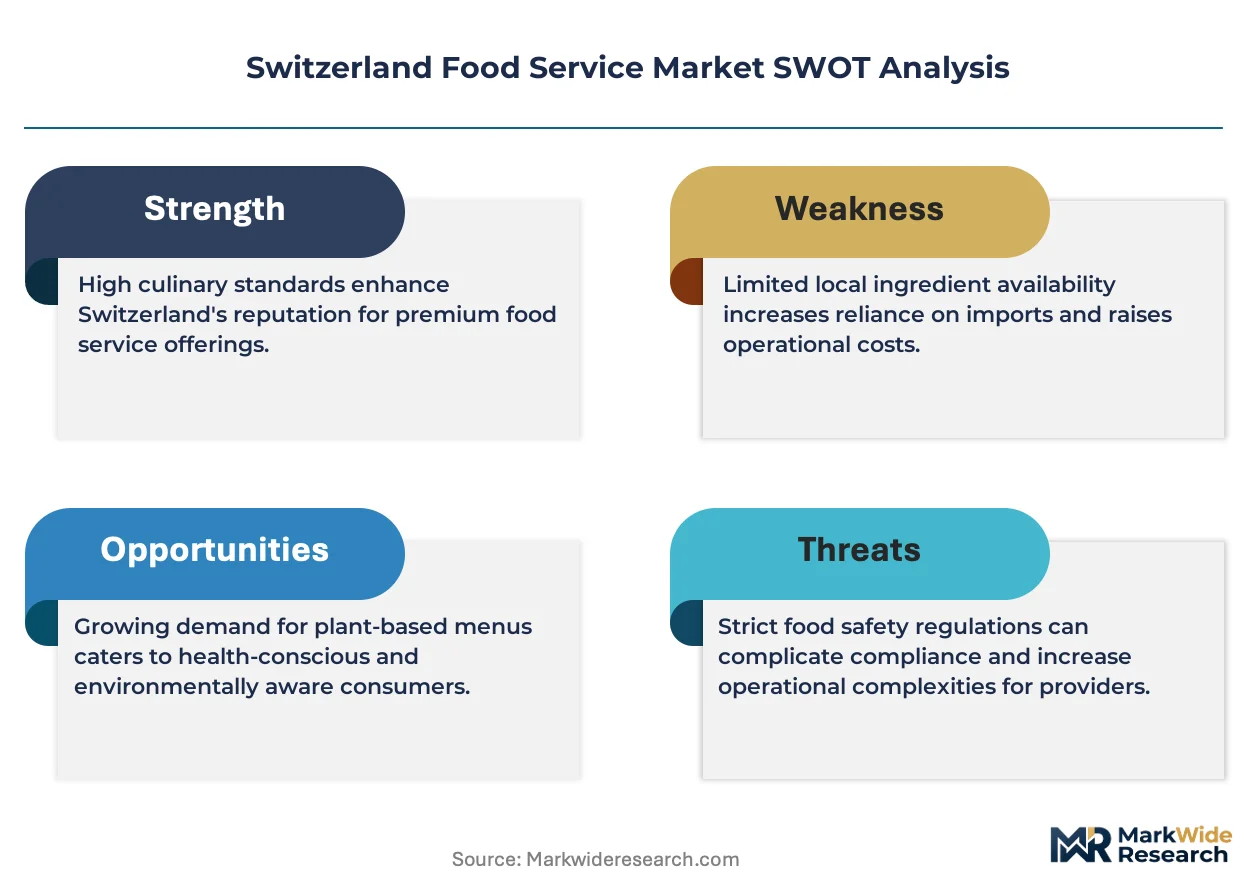
The EU Green Deal's embodied carbon reporting requirements are restructuring procurement standards across Swiss contract catering, forcing operators to document supply chain emissions or lose access to public sector contracts.
Growth Catalysts
- Employee wellness mandates:Swiss banking and pharmaceutical headquarters are expanding corporate dining contracts as firms prioritize on-site nutrition programs.
- Local sourcing incentives:The EU Green Deal's carbon accounting framework pressures caterers to reduce food miles through regional procurement networks.
- Healthcare channel expansion:Swissmedic oversight of prepared meal safety is standardizing production protocols for hospital and eldercare facilities.
Market Restraints
- Alpine logistics costs:Temperature-controlled distribution across Switzerland's mountainous terrain inflates per-unit delivery expenses versus flatland European markets.
- Labor pool constraints:The country's tight hospitality labor market limits kitchen staffing for high-volume catering operations.
- Import dependency for proteins:Domestic agricultural capacity cannot satisfy demand for certified sustainable beef volumes required by large-scale contracts.
Strategic Opportunities
- Ticino corridor penetration:The Italian-speaking southern region remains underdeveloped for premium corporate catering relative to the Zurich-Geneva axis.
- Carbon verification services:Federal procurement cycles tightening emission documentation rules create demand for specialized third-party auditing partnerships.
- Healthcare integration:Swissmedic's expanding jurisdiction over therapeutic nutrition opens specialized production niches for clinical meal providers.
Industry Challenges
- Compliance timeline compression:The Federal Food Safety and Veterinary Office's hazard analysis protocol updates require rapid kitchen system reconfigurations.
- Legacy equipment retrofitting:Existing centralized production facilities face capital-intensive upgrades to meet real-time carbon tracking requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Food Service Market |
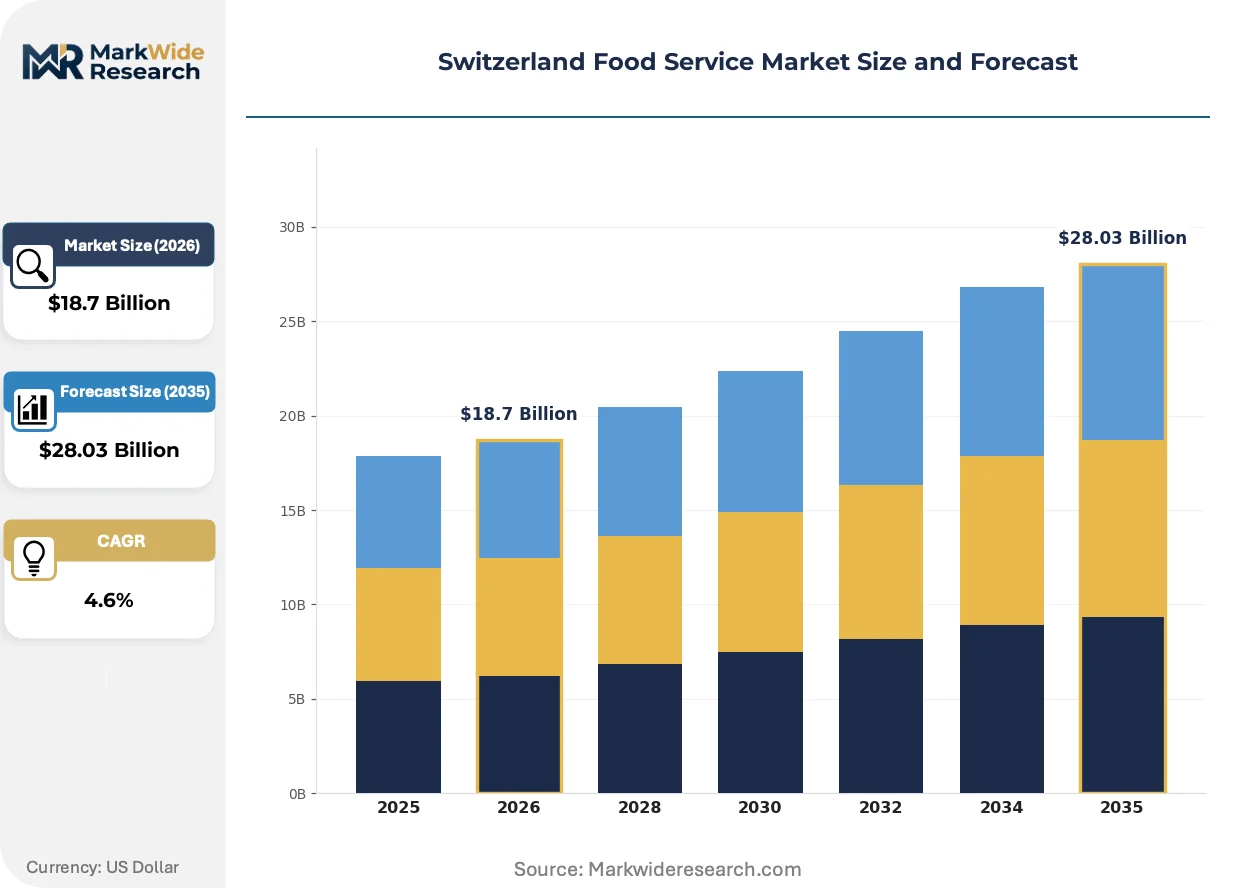
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Quick Service, Cafes, Caterers Customer Type: Residential, Corporate, Healthcare, Educational Distribution Channel: Online Delivery, Dine-In, Takeaway, Food Trucks Menu Type: Vegetarian, Vegan, Organic, Gluten-Free |
| Companies Covered | McDonald's Corporation, Valora, Candrian Catering AG, Gategroup, Future Kitchens AG, Coop Gruppe Genossenschaft, Starbucks Corporation, Wendy's, SV Group AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Food Service Market Trends and Innovations
Electrification of kitchen equipment and automated production systems are compressing operational costs while regulatory pressure on supply chain transparency accelerates technology adoption across Swiss food service operations.
Induction cooking and battery-powered cold chain logistics are electrifying commercial kitchen energy profiles. Large-scale caterers serving corporate headquarters in Zurich and Geneva are replacing gas infrastructure with all-electric systems to satisfy emission reporting requirements. This shift is compressing utility cost volatility while enabling operators to qualify for federal sustainability procurement preferences.
The EU Green Deal's embodied carbon reporting requirements, adopted into Swiss commercial law through bilateral agreements, now mandate documented supply chain emissions for all public sector food contracts. Operators must trace ingredient origins from farm to fork or face automatic disqualification from institutional tenders. Healthcare catering channels under Swissmedic jurisdiction are experiencing the steepest compliance costs as therapeutic meal protocols intersect with carbon accounting rules.
Corporate procurement teams are consolidating vendor relationships around single-source catering partners capable of delivering integrated wellness programming and emission transparency. Full-service restaurant groups are losing share to specialized contract caterers with in-house nutritionists and carbon verification capabilities. This concentration is most visible among banking headquarters clustered along Lake Zurich, where multi-year exclusive agreements now predominate.
Switzerland Food Service Market Segmentation
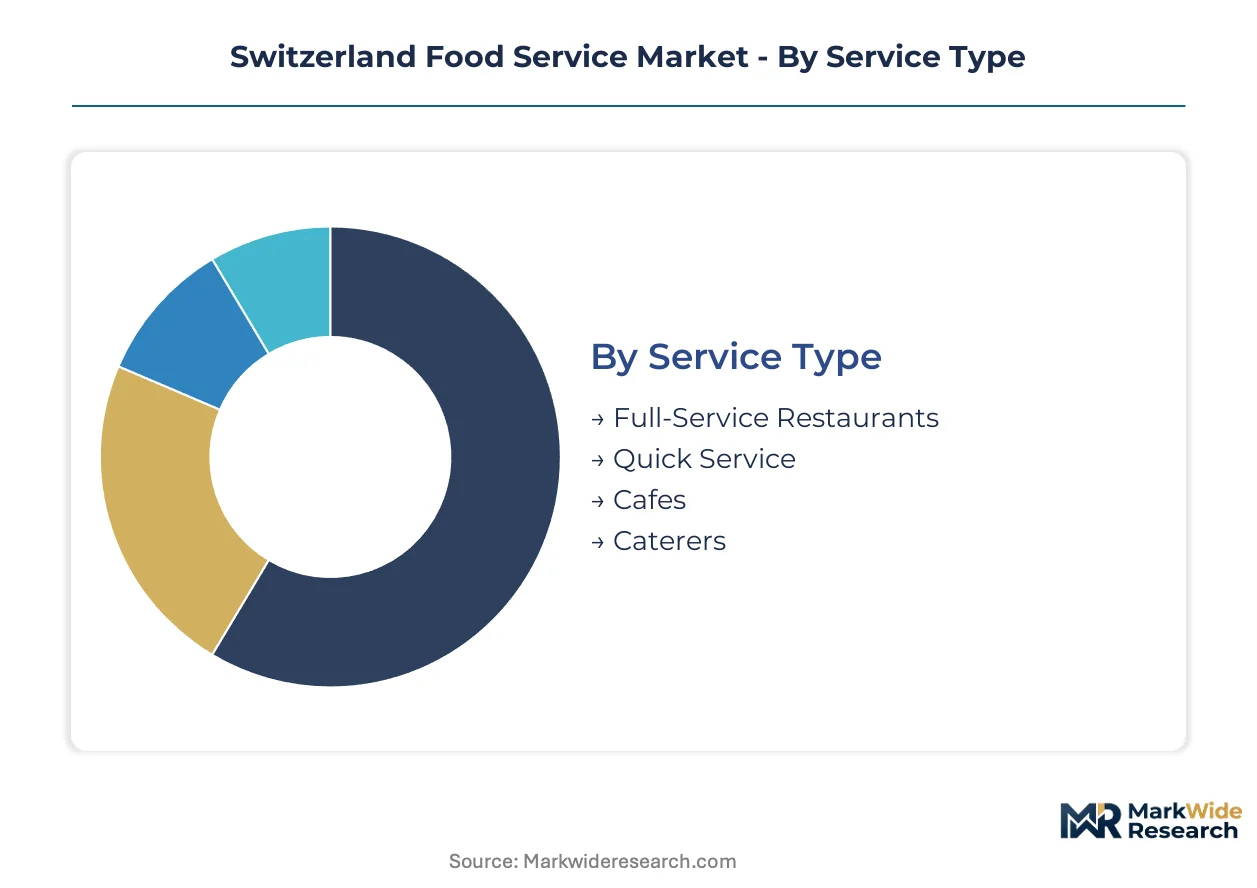
Switzerland's food service market segments reflect distinct operational models and procurement pathways. Service type determines kitchen infrastructure investment and staffing ratios. Customer type dictates contract duration and margin stability. Distribution channel shapes real estate requirements and technology platforms. Menu type influences supply chain certification needs and pricing power.
Service Type:
Standalone operations dominate the Swiss landscape, while embedded systems within corporate campuses and healthcare facilities are expanding fastest.
- Full-Service Restaurants:Table service with on-site cooking and trained front-of-house staff. Zurich and Geneva banking districts sustain premium independent operators despite labor cost pressures from Switzerland's hospitality wage floors.
- Quick Service:Standardized menus with limited service interaction and high throughput design. Valora's kiosk network at SBB transit nodes captures commuter volume with sub-three-minute service cycles.
- Cafes:Beverage-centric operations with light food preparation. Demand clusters in urban cores where remote workers seek WiFi-enabled spaces for extended stays.
- Caterers:Centralized production with off-site delivery to institutional clients. Long-term corporate dining contracts at Novartis and Roche headquarters provide revenue predictability unmatched by restaurant formats.
Quick Service leads volumes today; Caterers are gaining share fastest.
Customer Type:
Contract-based relationships generate superior margin stability compared to walk-in traffic dependent operations.
- Corporate:Multi-year dining service agreements with employee wellness components. UBS and Credit Suisse headquarters in Zurich drive demand for nutritionist-designed menus and carbon-transparent sourcing.
- Healthcare:Therapeutic meal production under Swissmedic oversight. University Hospital Zurich and Geneva University Hospitals require HACCP-certified facilities with allergen segregation protocols.
- Residential:Individual consumer spending at restaurants and delivery platforms. Alpine tourism corridors in Graubünden and Valais experience seasonal demand spikes.
- Educational:Canteen services for universities and secondary schools. ETH Zurich and EPFL Lausanne operate large-scale captive facilities with student pricing mandates.
Corporate leads volumes today; Healthcare is expanding most quickly.
Distribution Channel:
Digital intermediaries are compressing margins for traditional dine-in operators while creating new asset-light entry points.
- Dine-In:On-premise consumption with full service or self-service models. Lake Geneva waterfront locations command rent premiums for tourism exposure.
- Online Delivery:Platform-mediated ordering with third-party logistics. Smood and Uber Eats dominate Swiss urban markets with sub-30-minute delivery guarantees.
- Takeaway:Customer-collected orders with no table service. Coop Restaurant formats at railway stations capture rail passenger flows with grab-and-go convenience.
- Food Trucks:Mobile kitchen units serving temporary locations. Basel's Messeplatz and Zurich's Kasernenareal host rotating vendors for lunch crowds.
Dine-In leads volumes today; Online Delivery shows the steepest expansion trajectory.
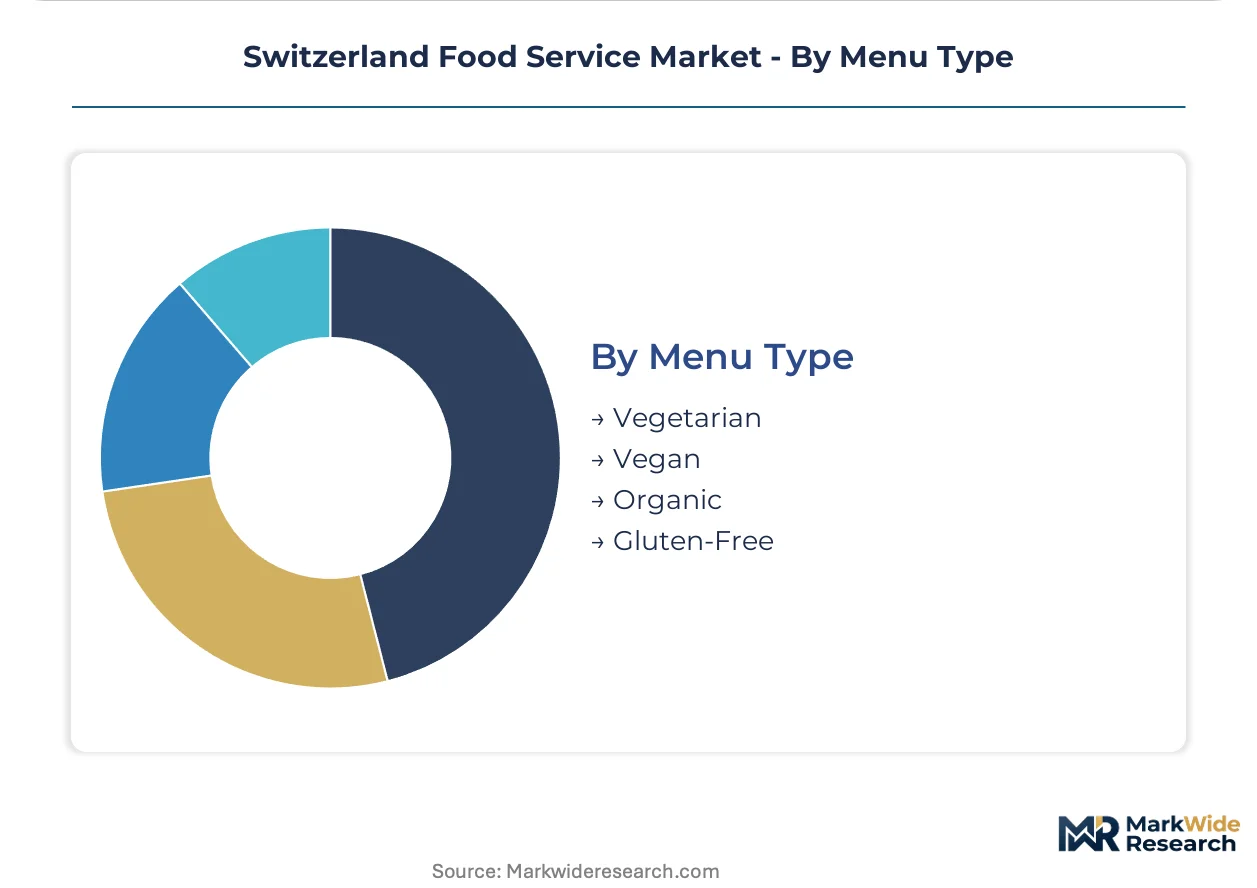
Menu Type:
Certification requirements separate premium-positioned offerings from conventional alternatives.
- Organic:Bio Suisse bud-certified ingredients with full traceability. Federal procurement preferences under the EU Green Deal bilateral agreements favor certified organic suppliers for institutional contracts.
- Vegetarian:Plant-forward menus with optional dairy and egg inclusion. ETH Zurich's Polyterrasse cafeteria reports majority vegetarian selection rates among student populations.
- Vegan:Exclusion of all animal-derived ingredients with protein substitution protocols. Hiltl in Zurich operates the world's oldest vegetarian restaurant with expanding vegan offerings.
- Gluten-Free:Celiac-safe preparation with dedicated kitchen zones. University Hospital Basel's dietary department maintains separate production lines for gluten-free therapeutic meals.
Vegetarian leads volumes today; Vegan is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland's food service industry traces its modern foundations to the post-war expansion of corporate dining facilities in Zurich and Geneva. The sector now operates across distinct linguistic and economic corridors shaped by regional regulatory frameworks and local sourcing requirements.
German-Speaking Region
Corporate headquarters concentration drives premium contract catering demand across Zurich, Basel, and Bern. The Federal Food Safety and Veterinary Office enforces hazard analysis protocols that elevate kitchen certification standards. Zurich's Paradeplatz banking district hosts multi-year exclusive dining agreements with integrated wellness programming and carbon-transparent sourcing mandates.
Romandy
Geneva's international organization cluster generates institutional catering volumes unmatched elsewhere in Switzerland. EU Green Deal bilateral agreements adopted into cantonal procurement law require documented supply chain emissions for all public contracts. The Geneva-Lausanne corridor concentrates pharmaceutical headquarters expanding therapeutic nutrition programs under Swissmedic oversight.
Ticino
Cross-border Italian supply chains reduce food miles for Mediterranean-menu operators in Lugano and Locarno. Cantonal sustainability incentives favor regional procurement networks over northern Swiss distribution hubs. The underdeveloped premium corporate segment presents expansion opportunities relative to saturated German-speaking markets.
Central Alps
Tourism-dependent food service in Graubünden and Valais experiences pronounced seasonal demand volatility. Temperature-controlled logistics across mountainous terrain inflate per-unit delivery costs versus flatland European benchmarks. Alpine hotel chains are consolidating vendor relationships around single-source partners capable of emission-transparent sourcing.
Northwestern Corridor
Basel's chemical and pharmaceutical cluster sustains high-volume institutional catering with long-term contract stability. Swissmedic's expanding jurisdiction over prepared meal safety standardizes production protocols across hospital and eldercare channels. The city's Messeplatz exhibition grounds generate temporary food service demand through rotating mobile kitchen operations.
Switzerland Food Service Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Switzerland's bifurcated food service structure. Full-service restaurant groups and centralized production caterers occupy distinct competitive spaces with minimal overlap. Three archetypes dominate: integrated retail-catering hybrids, specialized contract operators, and global quick-service franchise networks. Consolidation pressures favor multi-capability providers capable of spanning wellness programming, carbon verification, and therapeutic nutrition compliance.
Within the integrated retail tier, Coop Gruppe Genossenschaft and Valora exemplify backward integration strategies extending from wholesale distribution through captive on-site operations. McDonald's Corporation anchors the global quick-service archetype with supply chain scale securing certified sustainable protein volumes. Candrian Catering AG and SV Group AG occupy positions among specialized contract operators serving corporate and healthcare channels with long-term pricing stability.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Valora |
| Candrian Catering AG |
| Gategroup |
| Future Kitchens AG |
| Coop Gruppe Genossenschaft |
| Starbucks Corporation |
| Wendy's |
| SV Group AG |
| Others |
Pricing and Supply Chain Analysis
Federal procurement cycles tightening emission documentation rules are forcing caterers to reconfigure supplier relationships, compressing margins for operators lacking in-house carbon verification capabilities while rewarding those with backward integration into certified organic networks.
Pricing Analysis
Contract-based pricing with multi-year corporate dining agreements dominates the Swiss market, separating premium wellness-integrated caterers from standard providers through nutritionist-designed menus and carbon-transparent sourcing credentials. Price differentiation hinges on Bio Suisse bud certification levels and volume scale commitments from banking headquarters clusters. Cost compression in mid-tier catering is intensifying because legacy operators face capital-intensive kitchen electrification mandates. Healthcare channels under Swissmedic jurisdiction show least price sensitivity due to therapeutic nutrition requirements, while residential dining segments face greatest pressure from delivery platform intermediation.
Supply Chain Analysis
Hub-and-spoke distribution from centralized production facilities in Zurich and Geneva feeds embedded kitchen operations across corporate campuses and healthcare institutions. Geographic supply concentration draws from France for dairy proteins, Italy for Mediterranean produce, and Germany for equipment and packaging inputs. Raw material dependencies center on imported certified sustainable beef volumes, temperature-controlled logistics fleets, and specialized therapeutic nutrition formulations. Single-source vulnerability runs through Alpine temperature-controlled corridors where winter weather disruptions cascade through delivery schedules. Distribution runs through captive wholesale networks controlled by integrated retail-catering hybrids and third-party logistics partnerships for smaller operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification of kitchen infrastructure and carbon verification capabilities are expanding margin capture for operators with capital discipline, as federal procurement preferences reward emission-transparent sourcing with contract stability and pricing power.
For Market Incumbents: Hedge against compliance cost inflation by securing long-term renewable energy supply agreements for centralized production facilities and acquiring specialized carbon auditing capabilities before the next federal procurement cycle. Threat substitution from asset-light delivery platforms demands reinforcing channel control through exclusive multi-year corporate wellness contracts at Novartis and Roche headquarters. Priority lever rests on backward integration into Bio Suisse certified organic procurement networks that lock in supply security and federal contract eligibility. For New Entrants and Emerging Players: Specialized carbon verification service providers offer the most penetrable entry point, as established caterers outsource emission documentation to meet EU Green Deal bilateral requirements. White-space targets include Ticino corridor premium corporate catering and Swissmedic-compliant therapeutic nutrition production for eldercare expansion. Go-to-market angle should anchor on rapid certification acquisition and partnerships with ETH Zurich or EPFL for nutrition science credibility. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale contract caterers possessing integrated wellness programming and existing carbon verification infrastructure. Long-term viability across the projection horizon favors operators with demonstrated compliance execution in healthcare channels under expanding Swissmedic jurisdiction. Acquisition target archetype combines centralized production scale with federal contract relationships. Signal to watch is consolidation velocity among banking district caterers as UBS and Credit Suisse procurement teams consolidate vendor panels.| Strategic Initiative | Industry Significance |
|---|---|
| Kitchen Electrification Program | All-electric systems at Zurich headquarters qualify operators for federal sustainability procurement preferences. |
| Carbon Verification Partnership | Third-party auditing relationships satisfy EU Green Deal bilateral requirements for institutional contract eligibility. |
| Healthcare Channel Expansion | Swissmedic-certified therapeutic nutrition production captures eldercare demand with regulatory moat protection. |
| Ticino Corridor Penetration | Underdeveloped premium corporate segment offers expansion runway relative to saturated German-speaking markets. |
| Organic Procurement Integration | Bio Suisse bud-certified supply chains secure federal contract preferences and pricing power in institutional tenders. |
Research Methodology
Direct dialogue with contract catering executives, corporate procurement officers at pharmaceutical headquarters, Swissmedic regulatory affairs leads, and temperature-controlled logistics operators grounded the qualitative foundation. Secondary validation drew from Federal Food Safety and Veterinary Office hazard analysis protocols, EU Green Deal bilateral agreement texts, Bio Suisse certification databases, and Swiss Federal Statistics Office food service employment data. Bottom-up segment sizing triangulated against top-down macroeconomic consumption benchmarks.
Bottom-up modeling built volume and value estimates from individual service type and customer type segments, cross-referenced against top-down GDP elasticity and consumer expenditure patterns across the projection horizon. Segmentation dimensions modeled include service format, client relationship type, distribution channel, and menu certification tier. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and procurement cycle timing. Industry-specific forecast inputs incorporated Swissmedic jurisdiction expansion timelines and federal procurement rule implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement stringency and Alpine logistics cost inflation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Qatar Food Service Market
Food Service
US Food Trucks Services Market
Food Service
Online Catering Market
Food Service
Steam Stew Pot Market
Food Service
Commercial Grills Market
Food Service
Gas Floor Fryers Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
GCC Online Grocery Market
Food Service
Electric Tiffin Market
Food Service
Wok Market
Food Service
Global Digital Food Delivery Market
Food Service
Galley Equipment Market
Food Service
Singapore Food Service Market
Food Service
Instant Grocery Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
West Africa Food Services Market