
 Healthy Takeout Market | 2026-2036
Healthy Takeout Market Size, Share, and Industry Trends Forecast 2026-2036
Healthy Takeout Market Foresight
Modular bowl customization is recalibrating how consumers assemble meals from base proteins through toppings. Sweetgreen leverages its vertically integrated supply chain to control ingredient provenance across coastal markets. Cava anchors its growth in Mediterranean-format fast-casual with a build-your-own assembly model. Chipotle competes through scaled burrito-bowl production with antibiotic-residue protocols.
Healthy takeout comprises prepared meals engineered for controlled macronutrient profiles, typically featuring whole grains, lean proteins, and fresh vegetables with transparent calorie disclosure. Manufacturing emphasizes cold-chain integrity from commissary kitchen through last-mile delivery to preserve texture and nutrient density. Grain bowls occupy the largest margin pool given protein upsell attach rates and operational simplicity. Subscription services represent the fastest-expanding delivery model as employers fund recurring meal allowances. Salads remain the most mature product type with established supply contracts but compressed differentiation.
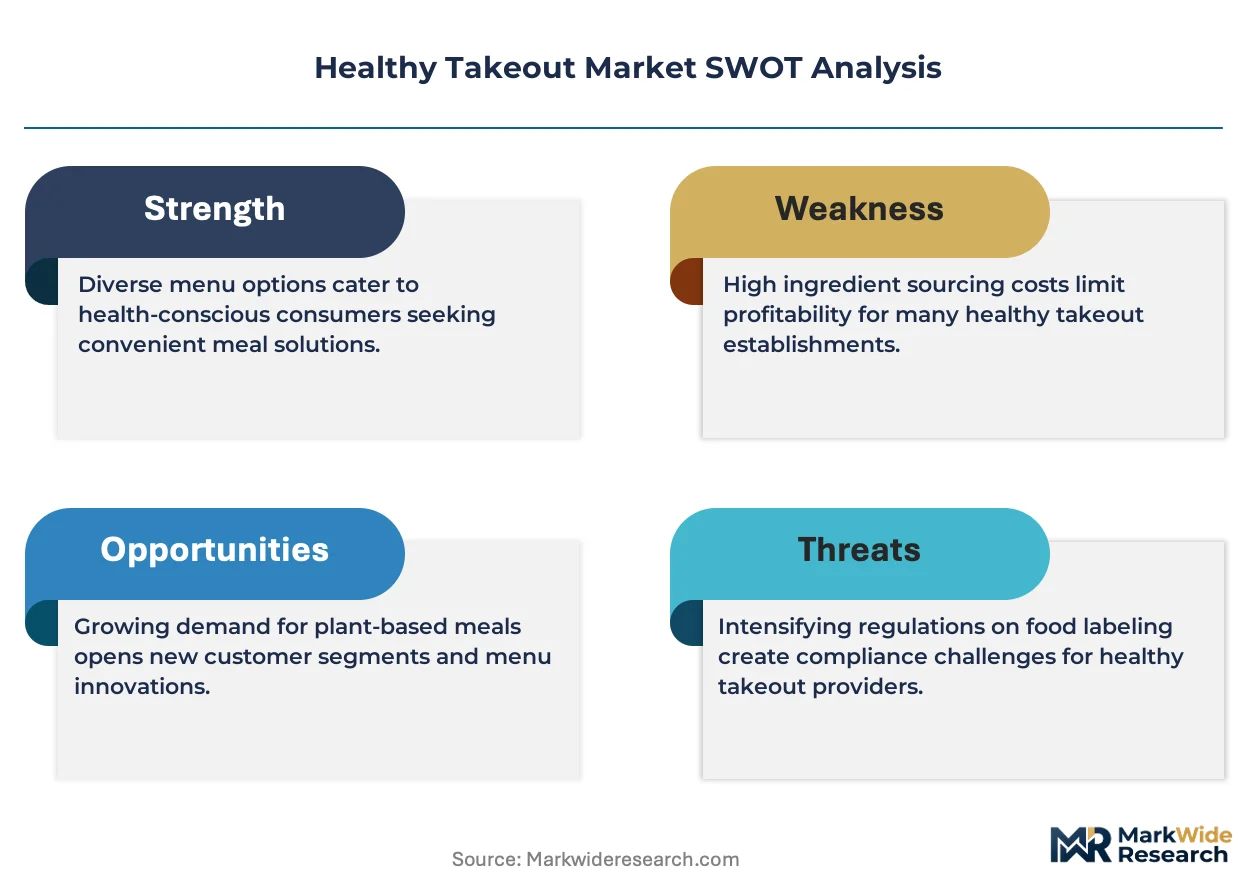
FDA menu labeling mandates and local health department grading systems shape product transparency requirements and kitchen audit frequency. Municipal sodium reduction targets in cities including New York and Philadelphia are forcing reformulation of prepared proteins and dressings. Stakeholders must monitor evolving employer wellness subsidy structures and their impact on per-order economics.
Market Dynamics
Employer-funded wellness subsidies are restructuring demand concentration toward recurring subscription models, while municipal sodium caps and FDA menu labeling mandates force simultaneous reformulation across coastal commissary networks.
Growth Catalysts
- Corporate wellness subsidies:Employers in the United States are expanding meal allowances for remote workers, creating recurring revenue pools that stabilize per-unit economics for prepared meal providers.
- FDA menu labeling rules:Transparency mandates are compressing information asymmetry between consumers and operators, accelerating trust-based purchasing decisions in urban corridors.
- Build-your-own assembly models:Modular bowl customization is elevating protein upsell attach rates while reducing kitchen labor complexity through standardized prep stations.
Market Restraints
- Perishable cold-chain costs:Temperature-controlled logistics from commissary through last-mile delivery compresses margins, particularly in secondary metropolitan zones lacking density.
- Coastal supply concentration:Vertically integrated produce sourcing clusters in California and Florida create geographic vulnerability to climate-driven crop disruption.
- Municipal sodium caps:New York and Philadelphia reduction targets are forcing costly reformulation of prepared proteins and dressings without guaranteed consumer acceptance of altered taste profiles.
Strategic Opportunities
- Underpenetrated inland metros:Secondary cities in Texas and Ohio show widening demand gaps as coastal operators delay expansion beyond proven density corridors.
- Subscription channel innovation:Employer-funded recurring meal allowances represent an emerging procurement model distinct from individual direct-to-consumer acquisition.
- Antibiotic-residue protocols:Premium protein sourcing standards are creating differentiation wedges that command pricing power in employer-subsidized segments.
Industry Challenges
- Commissary kitchen certification timelines:Local health department grading systems impose variable audit frequencies that delay market entry and complicate multi-jurisdiction scaling.
- Legacy POS integration friction:Enterprise wellness platforms require API connectivity that many established operators lack, creating technical debt in subsidy-eligible segments.
- Texture preservation protocols:Cold-chain engineering for grain bowl components demands specialized packaging capex that strains mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthy Takeout Market |
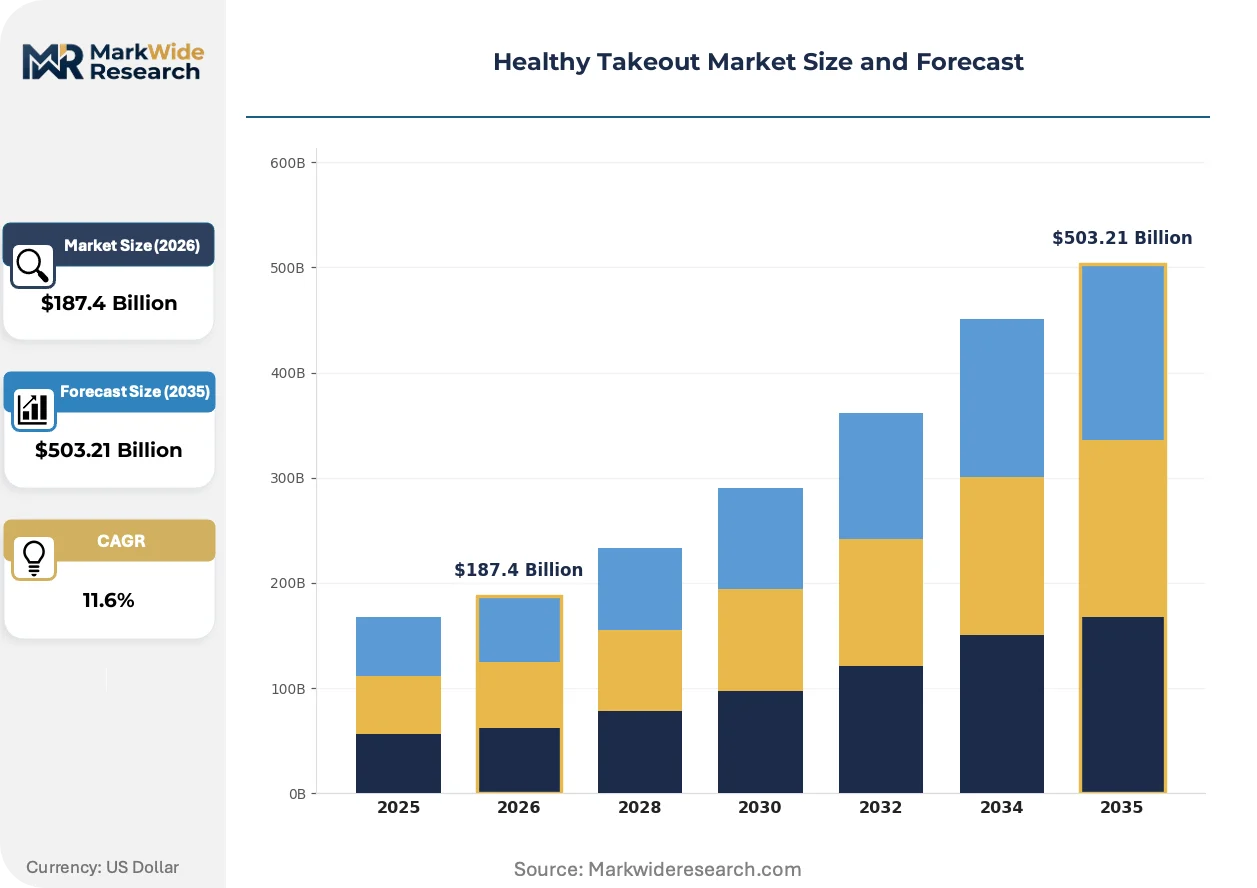
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $503.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salads, Smoothie Bowls, Grain Bowls, Wraps Customer Type: Health Enthusiasts, Busy Professionals, Families, Students Delivery Model: Third-Party Apps, Direct Website Ordering, Subscription Services, In-Store Pickup Meal Type: Lunch, Dinner, Snacks, Breakfast |
| Companies Covered | Playa Bowls, Saladworks, Sweetgreen, Coolgreens, Protein Bar & Kitchen, Cava, Tropical Smoothie Cafe, Grabbagreen, Chipotle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthy Takeout Market Shifts & Advancements
Automation in commissary production and algorithmic demand forecasting are compressing preparation-to-consumption windows, while regulatory transparency mandates and shifting employer procurement models reshape competitive positioning.
Cloud-connected kitchen display systems paired with predictive inventory algorithms are decentralizing production scheduling authority from centralized commissary managers to line-level operators. Fast-casual chains with 50-plus locations are adopting these systems fastest, typically achieving full deployment within 18 months. Real-time demand sensing is decentralizing batch-size decisions, enabling smaller production runs that reduce waste while maintaining availability during peak windows.
FDA menu labeling mandates finalized under the Affordable Care Act implementation rules are forcing standardized calorie disclosure across all covered establishments with 20 or more locations. This regulatory pressure is compressing formulation secrecy, pushing proprietary recipes toward transparent macronutrient profiles that consumers can compare directly. Chains operating in New York and Philadelphia face additional sodium reduction timelines that are accelerating clean-label reformulation investments ahead of federal requirements.
Employer-funded wellness allowances are displacing individual direct-to-consumer acquisition as the dominant procurement model in coastal metropolitan corridors. Benefits administrators at technology and professional services firms are consolidating vendor relationships, replacing fragmented employee reimbursement with centralized platform contracts. This concentration is most visible in Seattle, San Francisco, and Boston, where subsidy-eligible orders now represent a meaningful share of weekly volume for established operators.
Healthy Takeout Market Segmentation
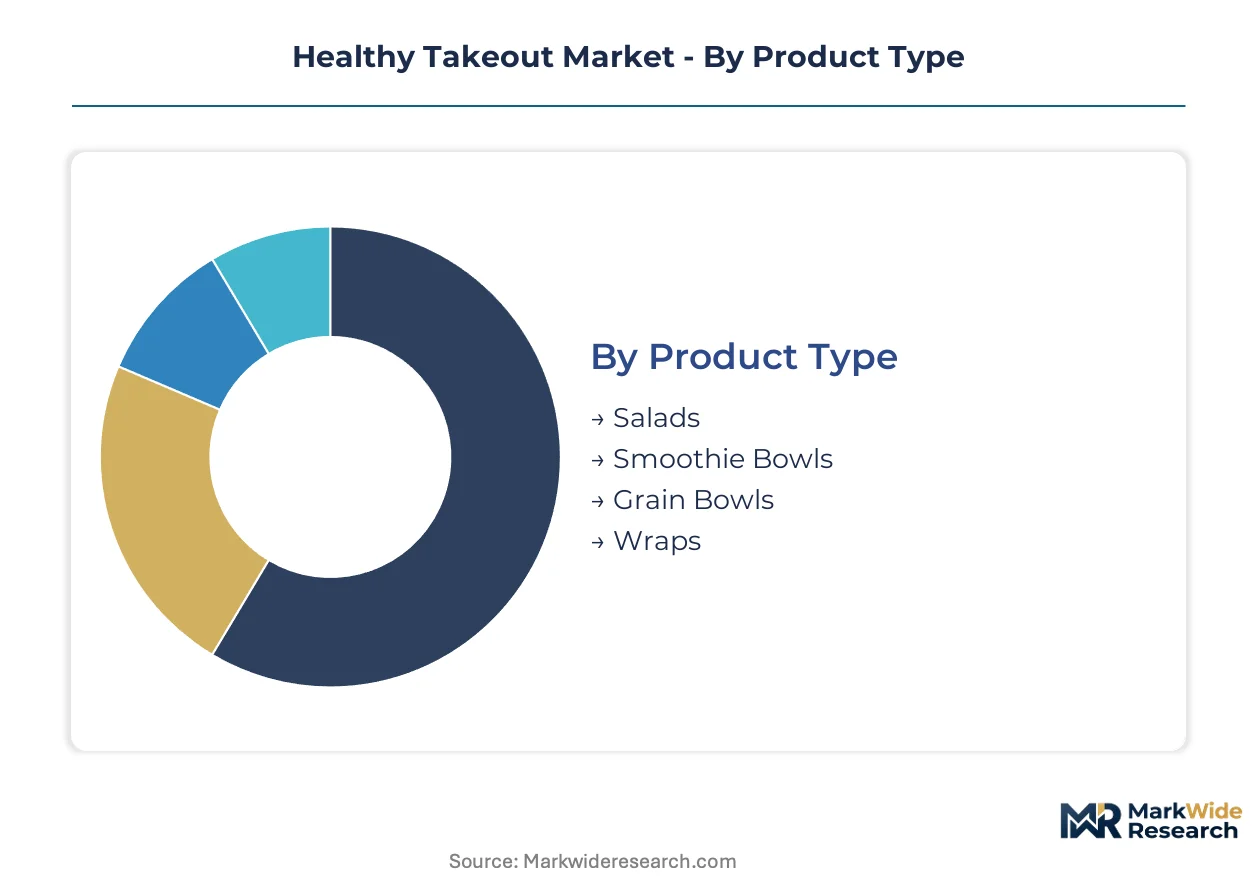
Segmentation in healthy takeout reveals how procurement concentration and consumption occasions fragment addressable demand. Each dimension exposes distinct margin structures and operational requirements that shape competitive positioning across coastal and inland corridors.
Product Type:
Buyers prioritize macronutrient transparency and assembly speed when selecting format categories.
- Salads:Composed of raw leafy bases with modular protein and dressing options. Demand concentrates among health enthusiasts in urban coastal offices where established supply contracts support rapid fulfillment. FDA calorie disclosure mandates have compressed differentiation, forcing operators toward premium ingredient sourcing.
- Grain Bowls:Built on warm whole-grain bases with customizable protein and vegetable layers. Busy professionals in Seattle and San Francisco drive volume given protein upsell economics and operational simplicity at scale. Cold-chain engineering requirements for texture preservation strain mid-cap balance sheets.
- Smoothie Bowls:Blended fruit bases with granola and seed toppings requiring frozen supply chains. Students and younger demographics in university-adjacent metros show concentrated adoption.
- Wraps:Folded flatbreads with compressed ingredient layers optimized for handheld consumption. Families prioritize this format for car-friendly logistics and portion control.
Grain bowls lead on scale; smoothie bowls lead on momentum.
Customer Type:
Employer subsidy structures and household composition determine purchasing frequency and price elasticity.
- Busy Professionals:Time-constrained workers with employer-funded meal allowances. Corporate wellness programs in technology and professional services firms drive recurring subscription volume in Boston and San Francisco corridors.
- Health Enthusiasts:Consumers prioritizing macronutrient tracking and ingredient provenance. This segment commands premium pricing in coastal metros with vertically integrated supply chains.
- Families:Multi-person households seeking portion-scaled options with simplified decision-making. Secondary metros in Texas show widening demand gaps as operators delay expansion.
- Students:Price-sensitive younger consumers with campus-proximate purchasing patterns. University meal plan integrations represent an emerging procurement channel.
Busy professionals dominate current revenue; students show steepest expansion trajectory as campus partnerships proliferate.
Delivery Model:
Channel selection reflects tradeoffs between convenience premium and data ownership.
- Subscription Services:Recurring meal allowances funded by employer wellness programs. Benefits administrators consolidate vendor relationships, replacing fragmented reimbursement with centralized platform contracts.
- Third-Party Apps:Aggregator-mediated discovery with high customer acquisition cost and commission structures. Density-dependent economics favor coastal metropolitan zones.
- Direct Website Ordering:First-party channels capturing customer data and margin. Legacy POS integration friction creates technical debt for established operators.
- In-Store Pickup:Scheduled retrieval bypassing delivery logistics. Commissary kitchen certification timelines complicate multi-jurisdiction scaling for this channel.
Subscription services capture fastest growth; third-party apps retain volume concentration.
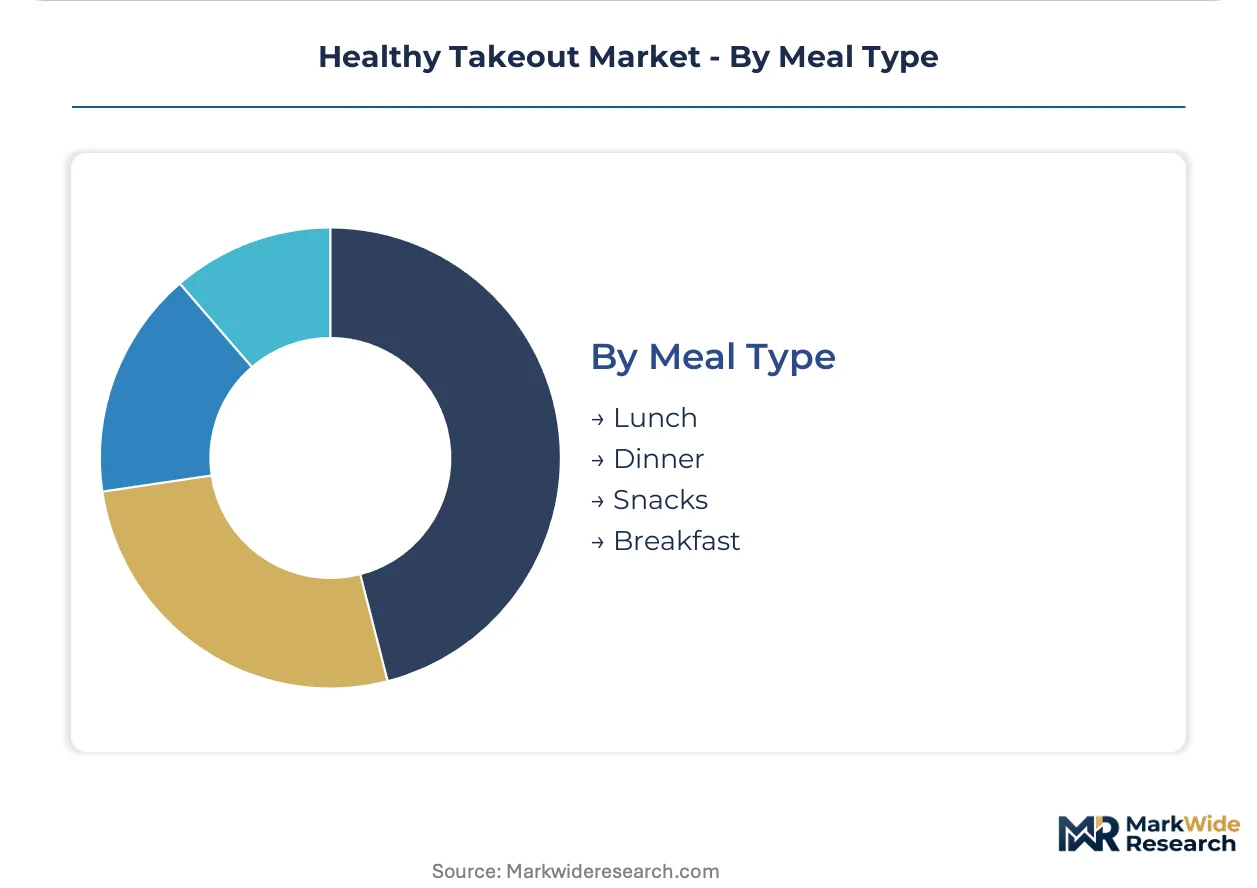
Meal Type:
Daypart concentration shapes production batch sizing and ingredient rotation schedules.
- Lunch:Midday consumption with compressed ordering windows and corporate procurement concentration. Urban office density drives peak throughput requirements.
- Dinner:Evening meals with expanded family-oriented portion economics and relaxed fulfillment timelines. Residential delivery logistics increase cold-chain cost exposure.
- Breakfast:Morning daypart with coffee attachment opportunities and commuter-route proximity requirements. Airport and transit-adjacent locations show concentrated demand.
- Snacks:Between-meal occasions with smaller average ticket and impulse-driven purchase patterns. Protein-forward mini-bowls are gaining share fastest in this segment.
Lunch commands volume dominance; snacks demonstrate the most rapid share expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The healthy takeout category achieved commercial scale in the United States through coastal urban density corridors, with employer wellness subsidies and FDA transparency mandates establishing the foundational demand architecture that other markets now adapt.
United States
Corporate wellness programs at technology and professional services firms in Seattle, San Francisco, and Boston drive recurring subscription volume. FDA menu labeling rules finalized under Affordable Care Act implementation compress information asymmetry between consumers and operators. Vertically integrated supply chains cluster in California and Florida, creating geographic concentration vulnerable to climate-driven crop disruption.
Canada
Urban professionals in Toronto and Vancouver demonstrate employer-subsidized meal allowance adoption patterns similar to US coastal corridors. Health Canada nutrition labeling regulations enforce standardized calorie disclosure across chains with twenty or more locations. Cold-chain logistics networks concentrate in Ontario and British Columbia, serving metropolitan density zones with temperature-controlled delivery infrastructure.
United Kingdom
London's financial and technology sectors fund corporate meal programs modeled on US wellness subsidy structures. EFSA nutrition and health claims regulations shape permissible marketing language around macronutrient transparency. Commissary kitchen networks cluster in Greater London and Manchester, with expansion into secondary metros constrained by certification timeline variability.
Germany
Busy professionals in Berlin and Munich demonstrate demand for modular bowl customization with transparent ingredient provenance. BSI food safety management standards and municipal health department grading systems impose audit frequencies that complicate multi-city scaling. Production capacity concentrates in North Rhine-Westphalia and Bavaria, serving urban office density corridors.
Australia
Sydney and Melbourne health enthusiasts drive demand for premium protein sourcing with antibiotic-residue protocols. FSANZ food standards code mandates nutrition information panels that accelerate trust-based purchasing decisions. Cold-chain engineering for grain bowl texture preservation strains mid-cap operator balance sheets in secondary metropolitan zones.
Healthy Takeout Market Competitive Landscape
Premium-margin players sit above commodity-margin players across supply chain control and protein sourcing certification tiers. The vendor base fragments between vertically integrated coastal specialists and regional franchise operators lacking commissary ownership. Three archetypes dominate: build-your-own assembly chains with scalable production stations, subscription-platform integrators serving employer wellness contracts, and legacy fast-casual converters retrofitting menus for macronutrient transparency. Capacity expansion through commissary kitchen certification and strategic partnerships with benefits administration platforms represent the dominant competitive moves.
Among US-based operators, Sweetgreen, Cava, and Chipotle exemplify contrasting scale and specialization strategies. Sweetgreen anchors the premium-tier vector through coastal urban density concentration. Cava occupies a position within Mediterranean-format fast-casual with build-your-own assembly infrastructure. Chipotle represents scale-driven commodity-margin production with antibiotic-residue protocol implementation.
| Leading Market Players |
|---|
| Playa Bowls |
| Saladworks |
| Sweetgreen |
| Coolgreens |
| Protein Bar & Kitchen |
| Cava |
| Tropical Smoothie Cafe |
| Grabbagreen |
| Chipotle |
| Others |
Supply & Pricing Matrix
Leafy greens commodity indices in California's Salinas Valley and Florida's Winter Haven corridor cascade through coastal commissary networks into three-tier pricing structures that separate premium antibiotic-residue proteins from standard-grade alternatives. Cold-chain logistics costs from produce sourcing through last-mile delivery compress margins differentially across urban density zones.
Pricing Analysis
Subscription-based pricing with employer wellness subsidies anchors the dominant revenue model, separating premium coastal operators with vertically controlled supply from franchise-dependent regional players. Price differentiation rests on protein certification grade and commissary ownership depth. Cost compression in standard-tier grain bowls is intensifying as municipal sodium caps force reformulation investments. Students and price-sensitive inland consumers exhibit highest elasticity, while employer-subsidized professionals show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with California and Florida produce corridors that feed coastal commissary networks. Raw material dependencies center on leafy greens, antibiotic-free poultry, and ancient grain varieties. Tariff exposure on imported olive oils and Mediterranean specialty ingredients creates margin volatility. Distribution runs through temperature-controlled logistics partnerships serving metropolitan density clusters, with secondary metros lacking sufficient route density for economic cold-chain fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The healthy takeout category reads as a late-cycle quality story where employer procurement concentration and regulatory transparency mandates are elevating premium specifications over commodity convenience.
For Market Incumbents: Deepen backward integration into produce sourcing to defend margin position against climate-driven crop disruption in California and Florida corridors. Invest in API connectivity with benefits administration platforms to secure employer-subsidized subscription volumes. Certification timelines for multi-jurisdiction commissary scaling represent the critical defensive lever against emerging regional competitors. For New Entrants and Emerging Players: Capture underpenetrated inland metros in Texas and Ohio where coastal operators delay expansion due to cold-chain density thresholds. Campus meal plan integrations offer the most penetrable procurement channel for price-sensitive student segments. Algorithmic demand forecasting partnerships with university food service operators provide a differentiated go-to-market angle against established coastal brands. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap operators lack commissary ownership and struggle with texture-preservation packaging capex. Long-term viability favors vertically integrated players with employer platform connectivity and antibiotic-residue certification infrastructure. Watch employer wellness subsidy expansion rates into secondary metropolitan zones as the signal for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Commissary Kitchen Certification | FDA and municipal health department compliance unlocks multi-jurisdiction scaling for subscription volume capture. |
| Employer Platform Integration | API connectivity with benefits administrators consolidates fragmented reimbursement into recurring revenue pools. |
| Antibiotic-Residue Protocol Implementation | Premium protein sourcing standards command pricing power in employer-subsidized coastal corridors. |
| Cold-Chain Packaging Investment | Specialized grain bowl texture preservation enables operational expansion beyond proven density zones. |
| Inland Metro Geographic Expansion | Secondary city penetration in Texas and Ohio addresses widening demand gaps with first-mover positioning. |
Research Methodology
Coverage spans North American coastal corridors and European metropolitan zones, with primary inputs from each region combined through stakeholder interviews and secondary validation. Conversations with commissary kitchen operators, benefits administration platform executives, municipal health department inspectors, and fast-casual chain procurement directors informed demand-side and supply-side dynamics. Secondary sources included FDA menu labeling rulemakings, municipal sodium reduction ordinances, employer wellness program disclosures, and cold-chain logistics operator filings. Bottom-up location-level volume estimates triangulated against top-down employer subsidy expenditure data.
Granularity-level modeling operated at product type, customer segment, delivery channel, and meal occasion dimensions across the projection horizon. CAGRs derived from employer wellness program expansion trajectories, regulatory compliance timeline assumptions, and cold-chain infrastructure buildout patterns. Segment-specific growth rates incorporated protein upsell attach rate economics and subscription renewal probability differentials by metropolitan density tier.
Climate-driven crop disruption in California and Florida, employer subsidy policy reversals, and consumer acceptance of sodium-reduced formulations are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about regulatory implementation pacing and procurement model evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Philippines Quick Service Restaurants Market
Food Service
France Foodservice Market
Food Service
Global Virtual Restaurant and Ghost Kitchens Market
Food Service
Instant Grocery Market
Food Service
India Inflight Catering Market
Food Service
Supermarkets Market
Food Service
Tabletop Pizza Oven Market
Food Service
Food Contract Manufacturing Market
Food Service
Bangladesh Food Service Market
Food Service
Japan Foodservice Market
Food Service
Smart Food Logistics Market
Food Service
Wok Market
Food Service
United States Full Service Restaurants Market
Food Service
Commercial Ice Dispenser Market
Food Service
Thailand Food Service Market
Food Service
Asia-Pacific Cloud Kitchen Market