
 Ship Catering Service Market | 2026-2036
Ship Catering Service Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Catering Service Market Insights
Buyer concentration among cruise lines is shifting as major operators consolidate fleet procurement under centralized catering contracts while cargo ship owners fragment across regional suppliers. OSERV Catering leverages its Mediterranean port network to dominate turnaround provisioning for large cruise vessels. COLUMBIA Cruise Services anchors its competitive position through captive galley management across German-flagged fleets. Oceanic Catering specializes in research vessel logistics, sustaining contracts in polar and deep-water expedition segments where supply chain complexity excludes generalist competitors.
Ship catering service encompasses the end-to-end provision of prepared meals, provisions, and galley management aboard commercial and private vessels operating beyond shore-based supply reach, requiring compliance with HACCP maritime adaptations, cold-chain integrity across rolling seas, and storage optimization within confined galley footprints. The primary purpose centers on crew welfare compliance and passenger satisfaction under conditions where resupply intervals span days to weeks. Buffet and à la carte formats under catering type command the largest volume share, though snack service is accelerating fastest on short-haul ferry and coastal cruise routes where grazing patterns displace formal meal structures. Contractual service models concentrate margin pools through multi-year fleet agreements, while event-driven provisioning captures premium pricing around themed voyages and expedition charters.
FDA food safety regulations for foreign vessel operations, EU MLC enforcement through port state control in Mediterranean jurisdictions, and ISO 22000 maritime adaptations collectively shape galley certification requirements and supplier qualification barriers. The EU Green Deal's emerging scope on maritime food waste streams is redirecting procurement specifications toward traceable sourcing and packaging reduction. Stakeholders must monitor how MLC amendments on crew nutrition minimums and evolving port-state organic waste disposal rules will restructure provisioning economics and vendor selection criteria across operating regions.
Market Dynamics
Fleet procurement consolidation among cruise operators is compressing supplier margins while polar expedition vessels and research fleets fragment demand toward specialized maritime food service capabilities.
Growth Catalysts
- IMO MLC nutritional standards:Mandatory crew welfare compliance across flag states is expanding galley service contracts to cover nutritional auditing and menu certification as standard deliverables.
- Mediterranean cruise corridor expansion:Barcelona, Civitavecchia, and Piraeus are adding dedicated provisioning terminals that reduce turnaround times and attract long-haul itinerary deployments.
- Automated cold-chain monitoring:IoT-enabled temperature logging systems are reducing spoilage claims and enabling insurers to offer preferential coverage terms for certified operators.
Market Restraints
- Specialized marine refrigeration equipment:Galley-grade compressors and seawater-cooled condensers carry 40-60% premiums over shore-based equivalents, inflating capital replacement cycles.
- Port-state organic waste disposal rules:EU Green Deal mandates on maritime food waste streams are forcing provisioning adjustments and disposal cost pass-throughs in Mediterranean jurisdictions.
- Limited qualified galley engineers:The pool of technicians certified for HACCP maritime adaptations and MLC compliance remains concentrated in Northern European maritime training centers.
Strategic Opportunities
- UAE turnaround port infrastructure:Dubai Maritime City and Abu Dhabi Cruise Terminal are expanding dedicated food logistics zones with bonded warehousing for Red Sea and Indian Ocean itineraries.
- EU Green Deal traceable sourcing mandates:Procurement specifications shifting toward packaging reduction and waste-stream documentation favor suppliers with integrated farm-to-galley tracking systems.
- Research vessel logistics specialization:Polar and deep-water expedition segments exclude generalist competitors through ice-class certification requirements and extended supply intervals.
Industry Challenges
- MLC amendment implementation timelines:Crew nutrition minimums are expanding documentation burdens without corresponding contract value adjustments during renegotiation windows.
- Legacy galley footprint constraints:Retrofitting older vessels for automated inventory systems requires structural modifications that conflict with stability calculations and class society approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Catering Service Market |
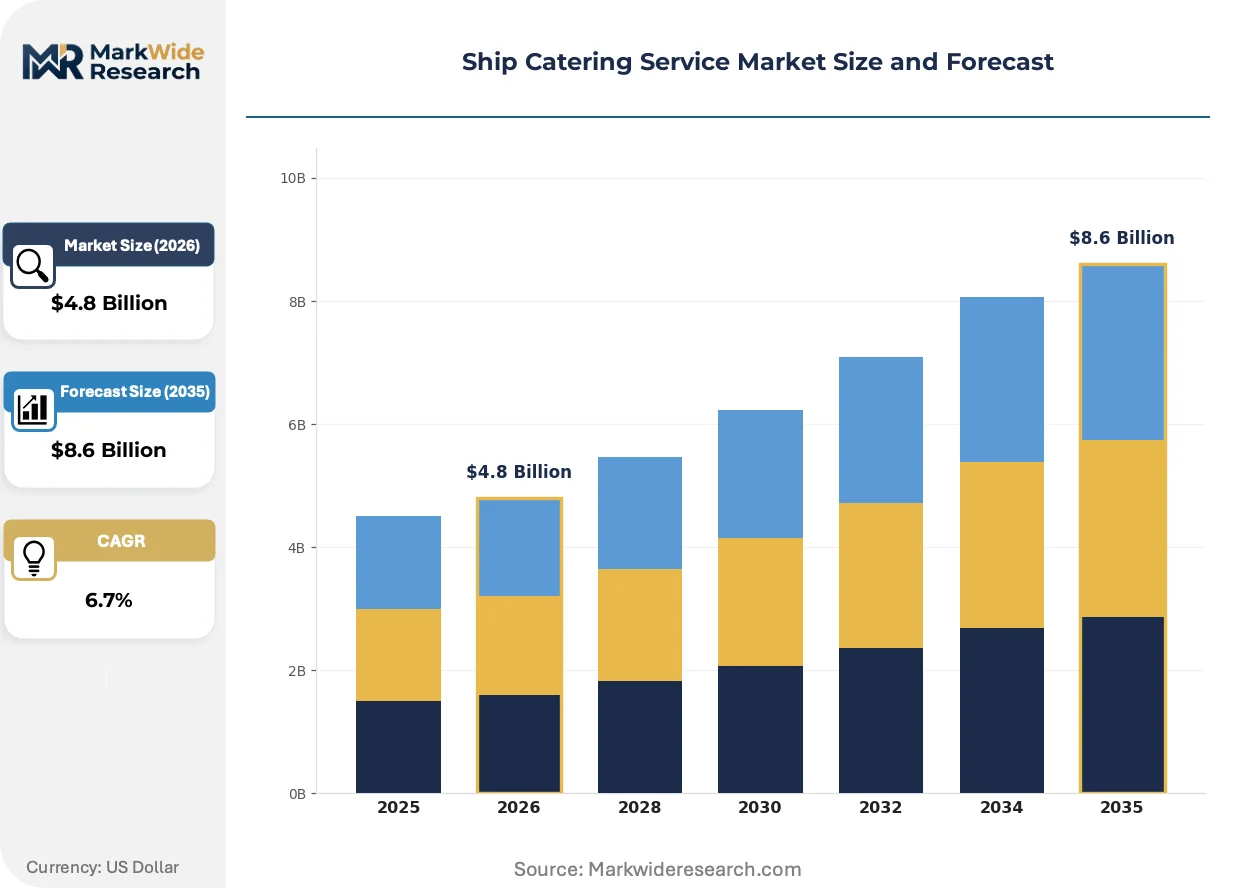
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Catering Type: Buffet, À La Carte, Set Menu, Snack Service Service Model: Onboard, Offshore, Contractual, Event-Driven End User: Cruise Lines, Cargo Ships, Yachts, Research Vessels Menu Style: International Cuisine, Regional Specialties, Vegetarian, Fast Food |
| Companies Covered | OSERV Catering, COLUMBIA Cruise Services, Oceanic Catering, The Apollo Group, Rieber GmbH & Co. KG, Admiral, SeaKing, Seachef, Belma Catering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Catering Service Market Trends and Innovations
Digital integration across provisioning chains is compressing order-to-delivery cycles while regulatory pressure on waste streams redirects procurement specifications toward circular sourcing models.
Galley management software platforms are unifying inventory tracking, menu planning, and nutritional compliance reporting into single-dashboard systems. Large cruise operators are mandating these platforms across fleet procurement contracts to standardize audit trails. This unification is compressing vendor qualification timelines and raising barriers for suppliers lacking API-compatible systems.
EU Green Deal emerging scope on maritime food waste is redirecting procurement specifications toward traceable sourcing and packaging reduction. Port-state control inspections in Mediterranean jurisdictions are expanding documentation checks for organic waste disposal compliance. Cruise lines operating Barcelona and Civitavecchia turnarounds are pre-qualifying suppliers based on farm-to-galley tracking capabilities.
Passenger grazing patterns on short-haul ferry and coastal cruise routes are displacing formal meal structures with continuous snack service formats. Ferry operators in the Baltic and Adriatic are reconfiguring galley layouts toward grab-and-go production lines. This consumption-pattern shift is visible most acutely in Scandinavian coastal routes where voyage durations under 24 hours dominate deployment schedules.
Ship Catering Service Market Segmentation
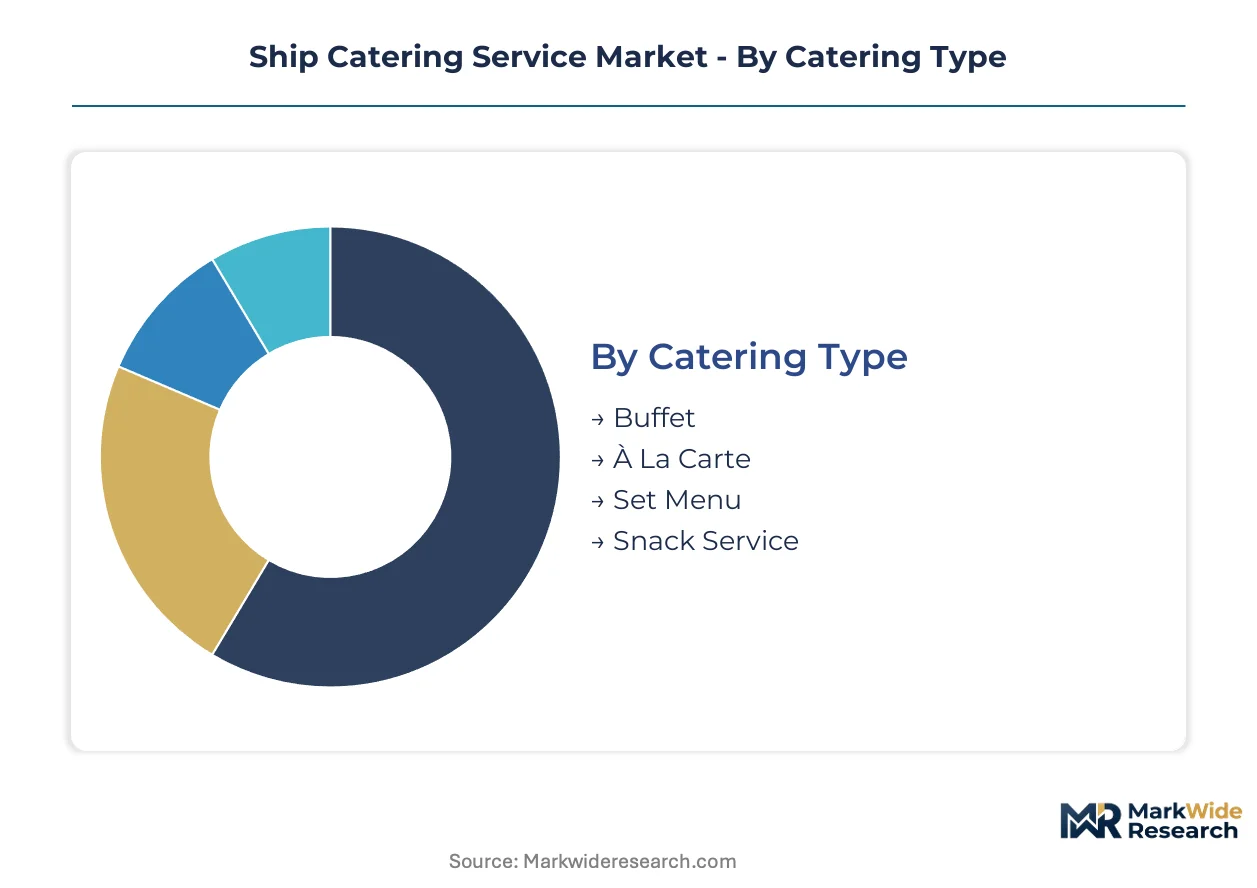
Ship catering service segmentation reflects divergent operational economics across vessel types and voyage profiles. Procurement managers weight cold-chain reliability, crew welfare compliance, and passenger satisfaction metrics differently depending on fleet configuration and itinerary structure.
Catering Type:
Menu format selection hinges on voyage duration, passenger demographics, and galley footprint constraints aboard specific vessel classes.
- Buffet:Self-service configurations dominate large cruise vessels with passenger volumes exceeding 2,000, minimizing labor costs during peak dining windows. Mediterranean and Caribbean itineraries concentrate demand where turnaround efficiency prioritizes throughput over customization.
- À La Carte:Table-service formats command premium positioning on expedition vessels and luxury yacht charters, where extended voyage durations justify higher crew-to-guest ratios. Polar expedition operators mandate this format to differentiate against mass-market alternatives.
- Set Menu:Pre-plated service structures prevail on cargo vessels and research fleets where crew complement stability enables batch production economics. IMO MLC nutritional auditing favors standardized portion control.
- Snack Service:Continuous grazing formats are displacing formal meals on Baltic and Adriatic ferry routes under 24 hours. Scandinavian operators reconfigure galleys toward grab-and-go production lines.
Buffet leads on scale; snack service leads on momentum.
Service Model:
Contract structure determines margin stability and capital commitment intensity for catering operators.
- Contractual:Multi-year fleet agreements concentrate revenue pools for large cruise operators consolidating procurement under centralized contracts. OSERV Catering dominates Mediterranean turnaround provisioning through this model.
- Onboard:Captive galley management generates recurring revenue streams with direct crew employment. COLUMBIA Cruise Services anchors German-flagged fleets through vertically integrated operations.
- Event-Driven:Themed voyage and expedition charter provisioning captures premium pricing around limited-duration deployments. Research vessel logistics exclude generalist competitors.
- Offshore:Platform and supply vessel catering serves energy sector contracts with helicopter resupply intervals spanning weeks. North Sea and Gulf of Mexico basins concentrate demand.
Contractual service leads on scale; event-driven leads on momentum.
End User:
Vessel operator type dictates compliance burden, payment terms, and galley specification requirements.
- Cruise Lines:Passenger-facing operations demand HACCP maritime adaptations, nutritional auditing, and buffet throughput engineering. Fleet procurement consolidation compresses supplier margins while expanding contract scope.
- Cargo Ships:Crew welfare compliance under MLC standards drives provisioning without passenger satisfaction metrics. Regional supplier fragmentation persists across bulk carrier and tanker segments.
- Research Vessels:Polar and deep-water expedition logistics require ice-class certification and extended supply intervals. Oceanic Catering sustains contracts where supply chain complexity excludes generalists.
- Yachts:Ultra-high-net-worth charter demand prioritizes customization and dietary accommodation over cost efficiency. Mediterranean and Caribbean hubs concentrate superyacht deployment.
Cruise lines lead on scale; research vessels lead on momentum.
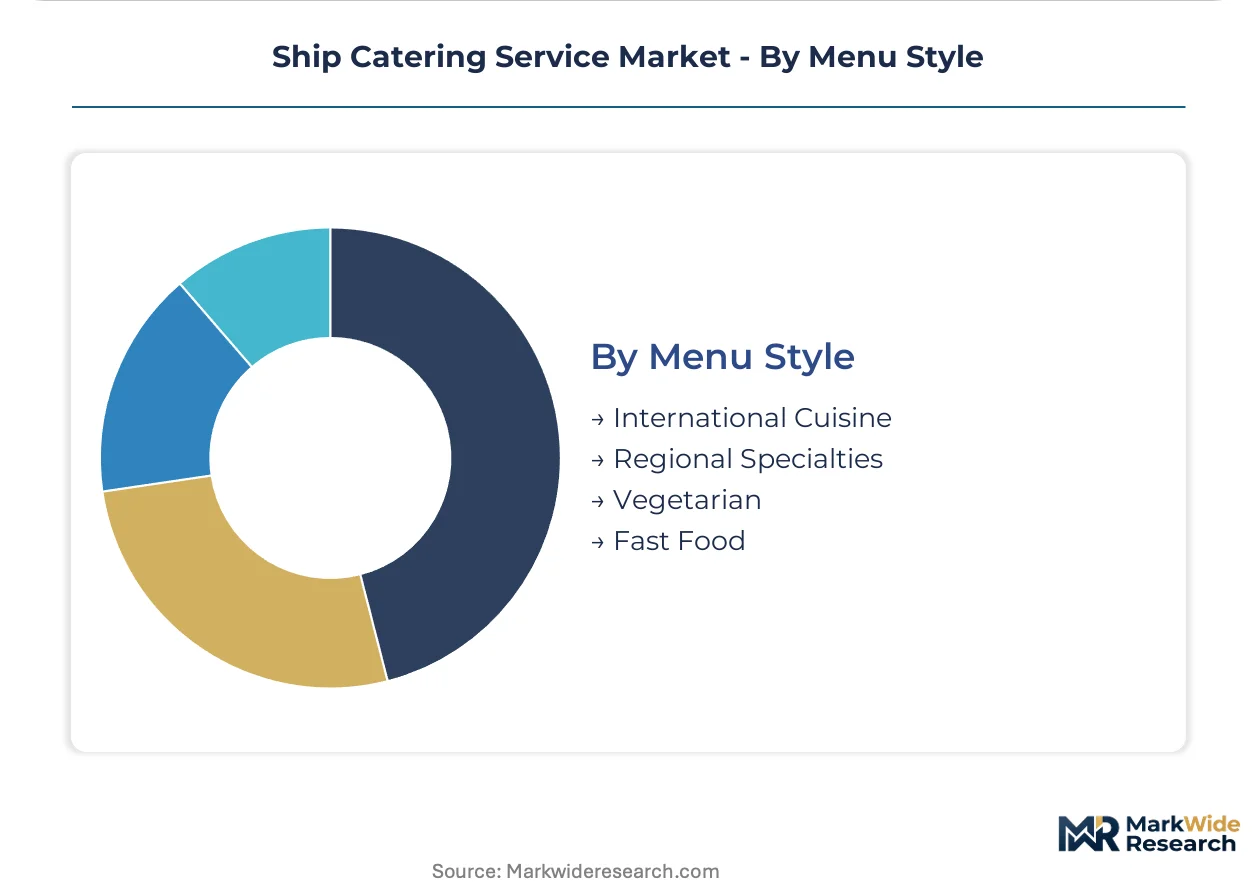
Menu Style:
Culinary positioning reflects passenger origin markets and voyage destination theming.
- International Cuisine:Standardized global menus dominate mass-market cruise fleets with heterogeneous passenger bases. Barcelona and Civitavecchia turnarounds source from multinational supplier networks.
- Regional Specialties:Destination-themed dining supports itinerary marketing for coastal and river cruise operators. EU Green Deal traceable sourcing mandates favor farm-to-galley documentation.
- Vegetarian:Plant-forward menu expansion responds to passenger dietary preference surveys and waste reduction targets. Mediterranean jurisdictions lead procurement specification shifts.
- Fast Food:Quick-service formats serve ferry and coastal routes where voyage duration compresses dining windows. Baltic Sea operators deploy grab-and-go configurations.
International cuisine leads on scale; regional specialties lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified galley engineers cluster in Northern European maritime training centers, anchoring specialized service capabilities for polar and deep-water expedition logistics.
Germany
Captive galley management contracts dominate German-flagged fleets, with operators consolidating procurement under vertically integrated service models. The country's Federal Maritime and Hydrographic Agency enforces stringent MLC compliance through port state control inspections. Hamburg and Bremerhaven serve as primary hubs where catering operators maintain bonded warehousing for North Sea and Baltic ferry routes.
Italy
Mediterranean turnaround provisioning concentrates at Civitavecchia and Genoa, where dedicated food logistics terminals reduce vessel resupply windows. EU Green Deal mandates on maritime organic waste disposal are reshaping supplier qualification criteria. The Port of Venice is expanding cold-chain infrastructure for Adriatic coastal cruise deployments.
United Arab Emirates
Dubai Maritime City and Abu Dhabi Cruise Terminal are constructing bonded food logistics zones for Red Sea and Indian Ocean itineraries. The country's national food safety regulator aligns port-state control with MLC nutritional auditing standards. Jebel Ali Free Zone attracts catering operators serving expedition charters and superyacht provisioning.
Greece
Piraeus anchors Eastern Mediterranean cruise corridor expansion, with dedicated provisioning terminals supporting long-haul itinerary deployments. The Hellenic Ministry of Maritime Affairs enforces MLC crew welfare standards through intensified galley inspections. Thessaloniki is emerging as a secondary hub for Aegean ferry route catering contracts.
Norway
Polar expedition vessel logistics demand ice-class certification and extended supply interval capabilities concentrated in Bergen and Tromsø. The Norwegian Maritime Authority implements strict cold-chain documentation requirements for Arctic route operations. Stavanger serves offshore platform catering contracts in the North Sea energy basin.
Ship Catering Service Market Competitive Landscape
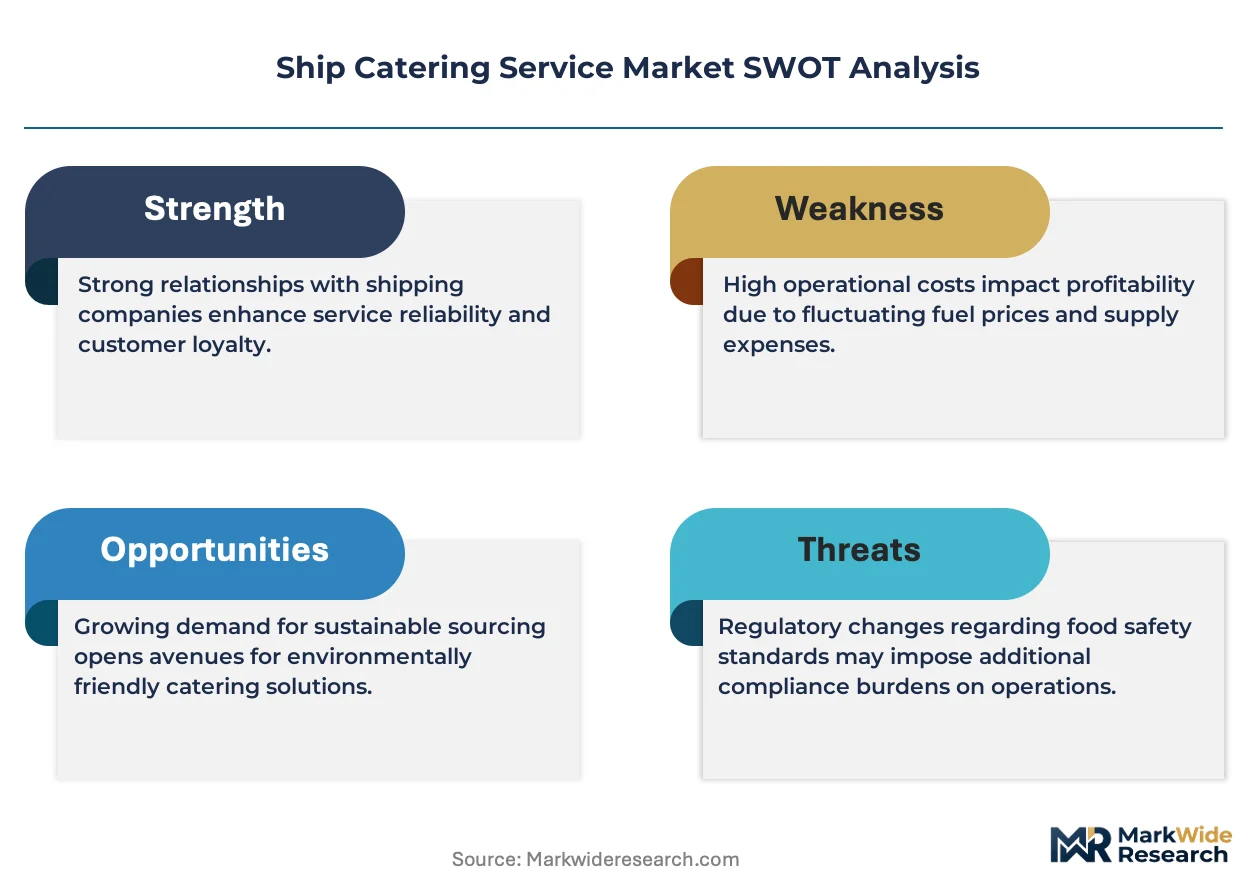
Diversified conglomerates compete with focused pure-play specialists across fragmented procurement channels. Fleet consolidation among major cruise operators is compressing supplier margins while polar expedition and research vessel segments sustain premium pricing for specialized capabilities. Three archetypes dominate: Mediterranean turnaround specialists, German-flagged captive operators, and polar logistics experts. Competitive moves center on multi-year fleet contract capture and automated cold-chain certification investments.
Within the Mediterranean turnaround tier, OSERV Catering exemplifies port-network dominance through centralized provisioning contracts. COLUMBIA Cruise Services occupies the captive galley management position across German maritime clusters. Oceanic Catering represents the polar specialization archetype, sustaining contracts where ice-class requirements and extended supply intervals exclude generalist competitors.
| Leading Market Players |
|---|
| OSERV Catering |
| COLUMBIA Cruise Services |
| Oceanic Catering |
| The Apollo Group |
| Rieber GmbH & Co. KG |
| Admiral |
| SeaKing |
| Seachef |
| Belma Catering |
| Others |
Pricing and Supply Chain Analysis
Automated cold-chain monitoring systems are compressing spoilage costs and concentrating procurement power among certified operators, reshaping margin economics across Mediterranean and Arabian Gulf provisioning corridors.
Pricing Analysis
The bundled-vs-unbundled service split separates fleet-wide catering contracts from standalone galley management or event-driven provisioning. Three-tier pricing structure across premium expedition logistics, standard cruise turnaround, and economy ferry routes reflects certification grade and cold-chain capability. Price differentiation centers on ISO 22000 maritime adaptation status and MLC nutritional auditing scope. Pricing pressure stems from fleet procurement consolidation among major cruise operators, compressing supplier margins while research vessel segments retain pricing power. Cargo ship owners exhibit highest price sensitivity due to fragmented regional supplier relationships, whereas polar expedition operators accept premium pricing for ice-class logistics capabilities.
Supply Chain Analysis
Workforce availability for HACCP maritime certification and MLC compliance training concentrates in Northern European maritime centers, particularly Germany and Norway, with secondary clusters in Italy and Greece. Galley-grade refrigeration equipment draws from specialized marine compressor manufacturers in Germany and Denmark, while fresh provisions source from Mediterranean agricultural networks and UAE bonded warehousing zones. Supply chain risk rests on single-source vulnerability for ice-class certified engineers capable of polar expedition logistics. Distribution runs through dedicated provisioning terminals at Barcelona, Civitavecchia, Piraeus, Dubai Maritime City, and Abu Dhabi Cruise Terminal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where IMO MLC nutritional standard amendments continuously expand mandatory service scope and documentation burdens, embedding recurring revenue streams for compliant operators.
For Market Incumbents: Lock in multi-year fleet contracts before MLC amendment renegotiation windows close, capturing centralized procurement consolidation among cruise operators. Invest in API-compatible galley management platforms to meet large operator dashboard standardization mandates. Counter margin compression by deepening backward integration into bonded warehousing at Dubai Maritime City and Abu Dhabi Cruise Terminal, reducing third-party logistics exposure.
For New Entrants and Emerging Players: Begin with research vessel logistics specialization where ice-class certification requirements and extended supply intervals exclude generalist competitors. Target polar expedition segments and deep-water scientific fleets as the most penetrable white space. Pursue farm-to-galley tracking capabilities aligned with EU Green Deal traceable sourcing mandates as the primary go-to-market angle for Mediterranean turnaround qualification.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional cargo ship catering suppliers fragmented across bulk carrier and tanker segments, overlooked relative to cruise line contract premiums. Long-term viability favors operators with captive galley management models generating recurring revenue through direct crew employment. Monitor MLC enforcement intensity through port state control inspection frequency as the signal indicating contract value adjustment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Cold-Chain Certification Investment | IoT-enabled temperature logging unlocks preferential insurance coverage terms from marine underwriters. |
| Bonded Warehousing Expansion | Dubai Maritime City and Abu Dhabi Cruise Terminal infrastructure reduces turnaround resupply windows. |
| Galley Management Platform Integration | API-compatible systems meet large cruise operator dashboard standardization mandates across fleet procurement. |
| Ice-Class Logistics Capability Buildout | Polar expedition contracts sustain premium pricing where supply chain complexity excludes generalist competitors. |
| Farm-to-Galley Tracking System Deployment | EU Green Deal traceable sourcing mandates reshape supplier qualification criteria at Mediterranean ports. |
Research Methodology
Multiple input streams — structured interviews with fleet procurement managers, galley operations directors, and maritime regulatory compliance officers; secondary validation through IMO MLC documentation, EU Green Deal regulatory filings, and port authority infrastructure announcements; customs and trade flow analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured contract structure evolution and pricing dynamics across Mediterranean, Arabian Gulf, and polar expedition corridors. Secondary sources encompassed flag state enforcement records, cold-chain equipment manufacturer disclosures, and cruise operator fleet deployment schedules.
Historical volume trajectories were cross-referenced against panel input from catering operators and maritime logistics specialists to construct projection frameworks. Segmentation modeling spanned catering type, service model, end user, and menu style dimensions across the analysis window. CAGRs were derived from fitted growth curves calibrated to fleet expansion schedules, itinerary lengthening patterns, and regulatory implementation timelines. Industry-specific forecast inputs incorporated MLC amendment adoption curves and EU Green Deal waste stream enforcement intensity.
Several conditions sit outside the modeled scope, including unscheduled MLC regulatory revisions, abrupt port state control enforcement shifts, and geopolitical disruptions to Mediterranean or Red Sea shipping corridors. Forecasts embed assumptions regarding continued fleet procurement consolidation and stable cold-chain equipment supply. Material deviation in MLC implementation timelines or EU Green Deal waste disposal rule enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United Arab Emirates Quick Service Restaurant Market
Food Service
India Online Grocery Market
Food Service
North America Online Grocery Delivery Market
Food Service
Onboard Rail Catering Market
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market
Food Service
Restaurants in Belgium Market
Food Service
Snack Subscription Box Service Market
Food Service
Steam Tables and Food Well Market
Food Service
Online Catering Market
Food Service
Contract Blending Services Market
Food Service
Street Vendors Market
Food Service
South Korea Foodservice Market
Food Service
Hospital Food Services Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Global Digital Grocery Market
Food Service
United Kingdom Full Service Restaurants Market