
 Halal Market | 2026-2036
Halal Market Size, Share, and Industry Trends Forecast 2026-2036
Halal Market Analysis
EU Green Deal sustainability benchmarks for food supply chains is expanding the addressable market for credentialed halal producers. Nestlé S.A. leverages its multi-country certification infrastructure to secure shelf space in European retail. Cargill Inc. anchors North American protein processing with dedicated halal-compliant production lines. BRF S.A. competes through scale advantages in Brazilian poultry exports to Middle Eastern buyers.
Halal denotes products and services permissible under Islamic law, encompassing food prepared with zabiha slaughter methods, alcohol-free cosmetics, and pharmaceuticals free from porcine derivatives or non-halal animal byproducts. The certification dimension stratifies market access, with Halal Certified products commanding premium placement in supermarkets and specialty stores while Halal Compliant tiers serve cost-sensitive segments through convenience stores. Food and beverages dominate current value pools, though cosmetics and pharmaceuticals represent faster-expanding categories as Muslim consumer spending on personal care and wellness rises.
Malaysia's Department of Islamic Development (JAKIM), Indonesia's Halal Product Assurance Organizing Body (BPJPH), and the UAE's Emirates Authority for Standardization and Metrology (ESMA) collectively set the compliance architecture governing cross-border trade. These frameworks mandate supply chain segregation, ingredient disclosure, and facility audits that raise barriers for uncertified competitors. Stakeholders must monitor certification reciprocity negotiations between Southeast Asian and Gulf regulators to anticipate shifts in market access conditions.
Market Dynamics
Certification reciprocity negotiations between JAKIM, BPJPH, and ESMA are restructuring cross-border halal trade flows, forcing supply chain reconfiguration and facility investment decisions across Southeast Asian and Middle Eastern processing hubs.
Growth Catalysts
- EU Green Deal alignment:Sustainability benchmarks for food supply chains are expanding the addressable market for credentialed halal producers seeking European retail placement.
- Urban corridor demand concentration:Indonesia's consumer corridors and Middle Eastern retail hubs are scaling procurement of certified products through food service provider networks.
- Traceability technology deployment:Blockchain-enabled supply chain tracking is satisfying tightening JAKIM standards for cross-border halal verification.
Market Restraints
- Input cost volatility:Feed grain price swings in Brazilian poultry supply chains compress margins for halal-compliant protein exporters.
- Facility segregation requirements:Dedicated production line mandates raise capital barriers for uncertified processors attempting market entry.
- Regulatory fragmentation:Non-reciprocal certification standards between Indonesia's BPJPH and Gulf regulators create duplicate audit burdens.
Strategic Opportunities
- Cosmetics and pharmaceuticals expansion:Muslim consumer spending on alcohol-free personal care and porcine-free wellness products is opening faster-expanding category white space.
- European retail channel penetration:Supermarket and specialty store placement for Halal Certified tiers remains underdeveloped relative to convenience store Halal Compliant distribution.
- Digital certification platforms:API-integrated halal verification systems are enabling real-time compliance checking for e-commerce cross-border transactions.
Industry Challenges
- Auditor capacity constraints:Qualified halal certification auditors face supply shortages relative to facility audit backlogs in Indonesia and Malaysia.
- Legacy system integration:ERP migration for supply chain segregation tracking creates implementation friction for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halal Market |
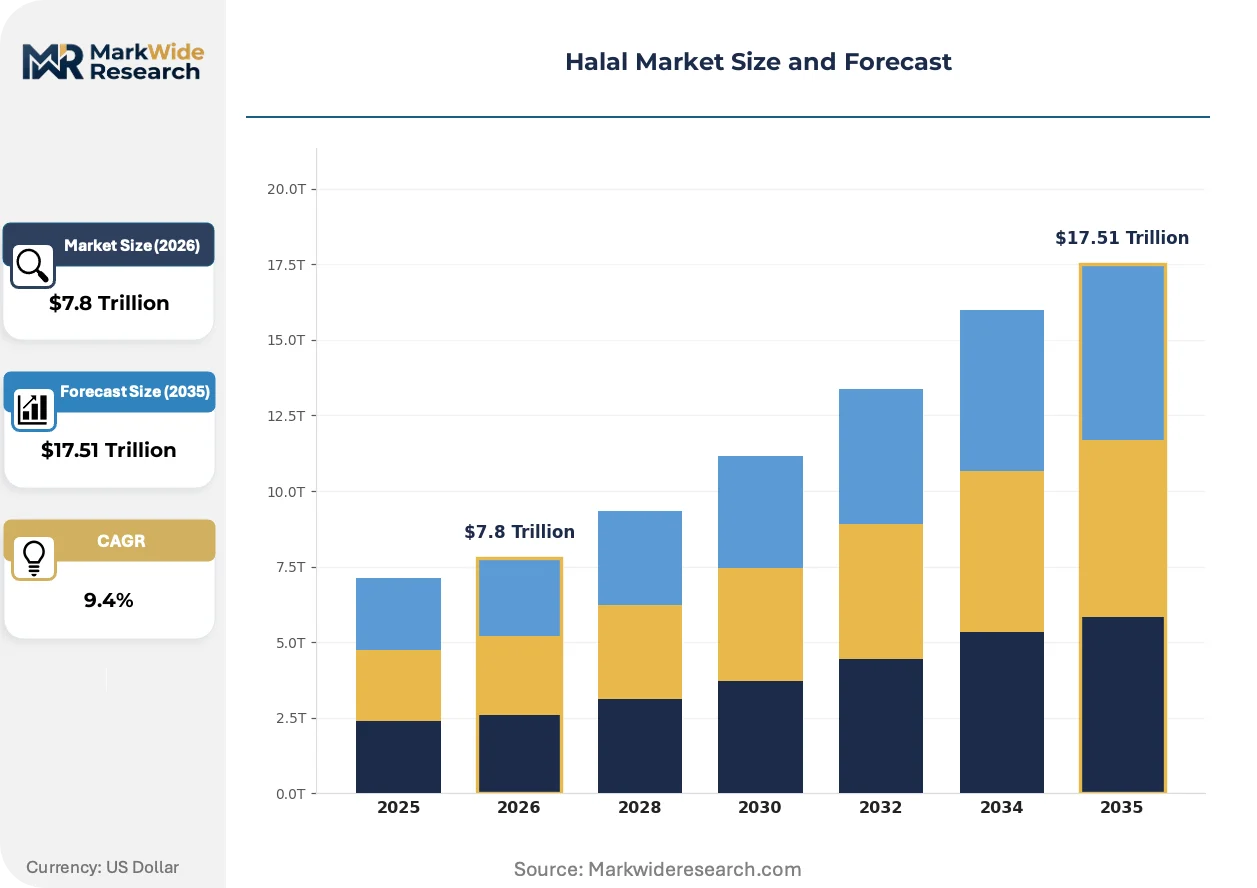
| Market Size in 2026 | $7.8 Trillion |
| Market Size in 2035 | $17.51 Trillion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Beverages, Cosmetics, Pharmaceuticals Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores Customer Type: Retail Consumers, Food Service Providers, Exporters, Manufacturers Certification: Halal Approved, Halal Certified, Halal Compliant, Others |
| Companies Covered | Nestlé S.A., Cargill Inc., BRF S.A., Al Islami Foods, QL Resources Sdn Bhd, Almarai, JBS S.A., Kawan Food Berhad, Midamar Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halal Market Emerging Trajectories
Digital traceability infrastructure and regulatory harmonization efforts are compressing certification timelines while reshaping how halal compliance is verified and monetized across food, cosmetics, and pharmaceutical value chains.
Blockchain-based supply chain verification is unifying previously siloed documentation systems across farm-to-fork halal networks. Major Southeast Asian food service providers are mandating platform adoption for tier-one suppliers. This technology is unifying audit trails that previously required manual cross-referencing between JAKIM, BPJPH, and ESMA databases.
EU Green Deal sustainability benchmarks are extending disclosure requirements into halal food supply chains. The regulation mandates carbon footprint reporting alongside existing religious compliance documentation. European retailers are responding by demanding dual-certified products that satisfy both Islamic law and environmental standards.
Specialty store buyers are consolidating procurement around Halal Certified premium tiers rather than diluting shelf space with Halal Compliant economy alternatives. This concentration is displacing convenience store-oriented distribution models in urban Middle Eastern markets. Dubai and Riyadh retail clusters exhibit the most pronounced certification-driven preference compression.
Halal Market Segmentation
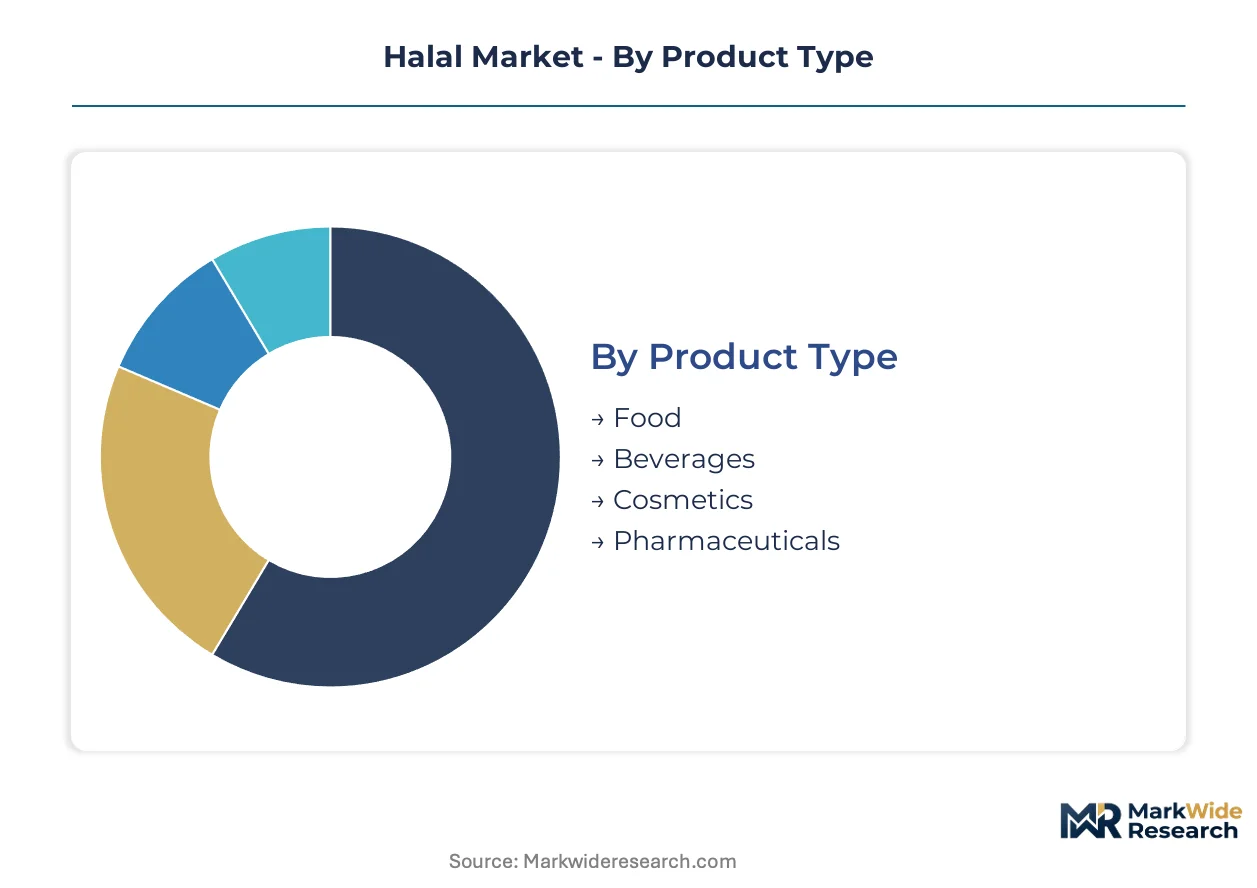
Certification tiers, product categories, and channel configurations stratify the halal market into distinct competitive arenas. Each segment carries unique compliance burdens and margin profiles that reshape procurement decisions across food service networks and retail procurement desks.
Product Type:
Specification intensity varies sharply across edible and non-edible categories, with religious compliance intersecting formulation chemistry in divergent ways.
- Food:Zabiha slaughter protocols and supply chain segregation dominate technical requirements. Demand concentrates in Indonesian urban corridors and Middle Eastern retail hubs where food service providers scale certified procurement under tightening JAKIM traceability mandates.
- Pharmaceuticals:Porcine-free formulation standards and excipient disclosure requirements define compliance architecture. Growth is accelerating fastest in Gulf markets where MOHAP and SFDA regulations mandate ingredient transparency for over-the-counter and prescription categories.
- Beverages:Alcohol-free verification and production line cleansing protocols apply. Manufacturers face audit backlogs in Southeast Asian processing hubs.
- Cosmetics:Alcohol-free personal care formulations and animal-derived ingredient screening apply. Muslim consumer spending on wellness products is opening faster-expanding white space relative to mature food categories.
Mature deployment sits with Food. Newer deployment is concentrated in Pharmaceuticals.
Distribution Channel:
Channel economics separate premium placement opportunities from high-volume, low-margin convenience penetration.
- Supermarkets:Halal Certified tier placement commands shelf space premiums and dual-facing opportunities alongside conventional products. European retail chains are expanding credentialed halal SKU counts under EU Green Deal sustainability alignment pressures.
- Specialty Stores:Consolidated procurement around premium certified tiers displaces economy alternatives. Dubai and Riyadh retail clusters exhibit pronounced certification-driven preference compression.
- Online Retail:API-integrated verification systems enable real-time compliance checking for cross-border transactions. Platform adoption is scaling fastest in markets with fragmented physical retail infrastructure.
- Convenience Stores:Halal Compliant economy tiers serve cost-sensitive segments with lower audit documentation requirements. Margins compress under input cost volatility in protein supply chains.
Volume concentration sits with Supermarkets. Margin expansion is concentrated in Specialty Stores.
Customer Type:
Procurement scale and compliance sophistication diverge sharply between institutional buyers and individual consumers.
- Food Service Providers:Blockchain-enabled supply chain tracking is becoming mandatory for tier-one supplier qualification. Southeast Asian food service networks are driving platform adoption to satisfy cross-border verification requirements.
- Retail Consumers:Individual purchase decisions gravitate toward visible certification marks in supermarkets and specialty stores. Digital verification apps are shifting trust mechanisms among younger demographics.
- Exporters:Dual-certification burdens for multiple regulatory regimes raise capital barriers. Brazilian poultry exporters to Middle Eastern buyers face margin pressure from feed grain price swings.
- Manufacturers:ERP migration for supply chain segregation tracking creates implementation friction at mid-scale. Qualified halal auditor shortages compound facility audit backlogs in Indonesia and Malaysia.
Compliance investment sits with Food Service Providers. Growth velocity is concentrated in Retail Consumers.
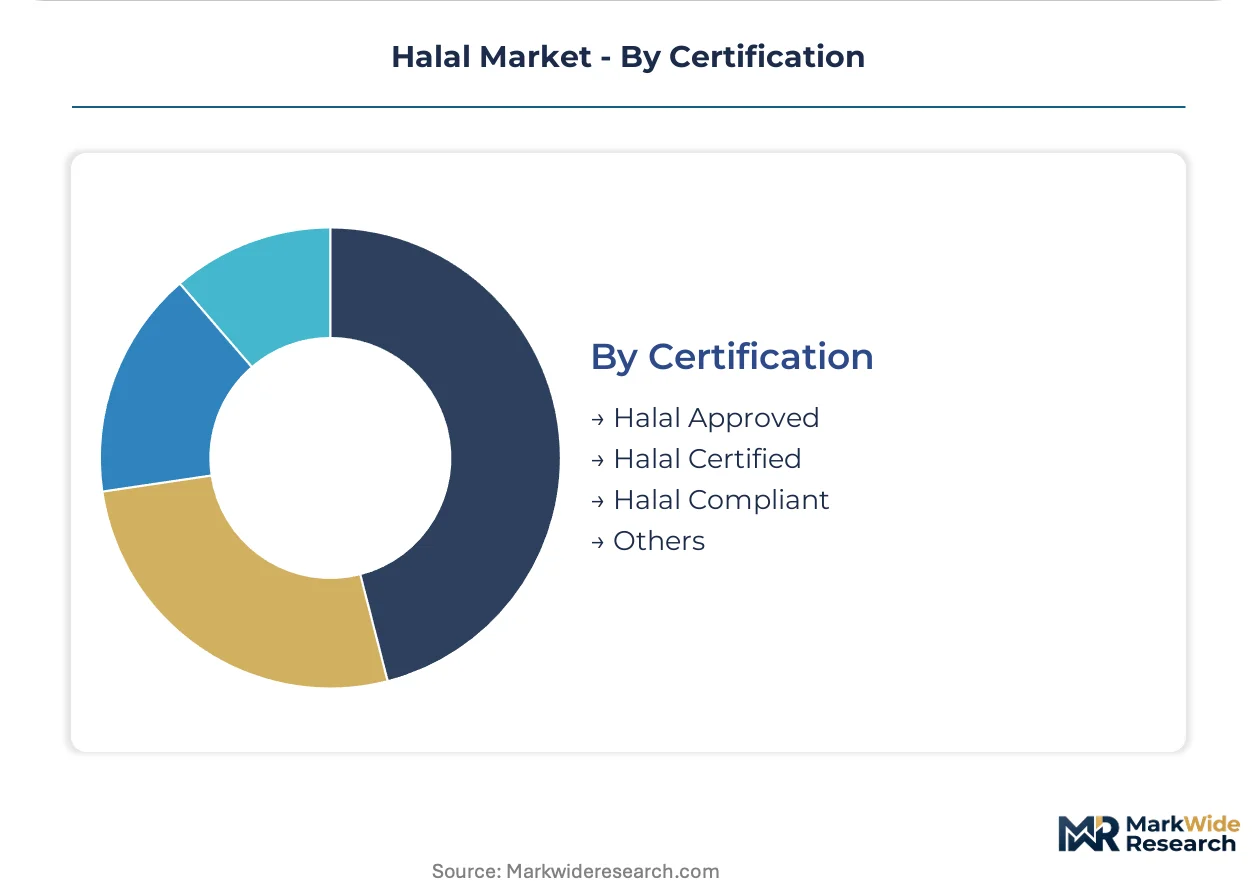
Certification:
Grade differentiation creates tiered market access with reciprocity negotiations restructuring cross-border trade flows.
- Halal Certified:Full JAKIM, BPJPH, or ESMA audit completion with facility segregation verification. Premium placement in European retail and Middle Eastern supermarket chains requires this tier.
- Halal Approved:Streamlined documentation for single-market access with reduced audit frequency. Smaller processors leverage this tier for domestic Indonesian or Malaysian distribution.
- Halal Compliant:Self-declared or third-party attestation without full regulatory body certification. Convenience stores and economy channels absorb this tier under price-sensitive procurement.
- Others:Niche or transitional certifications including religious authority letters and interim audit statuses. Limited commercial traction outside specific import clearance scenarios.
Regulatory reciprocity sits with Halal Certified. Cost-sensitive penetration is concentrated in Halal Compliant.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta's urban consumer corridors drive Southeast Asian halal procurement intensity, while Dubai anchors Middle Eastern retail certification standards and São Paulo's protein processing clusters supply cross-continental halal exports.
Indonesia
Food service providers in Jakarta and Surabaya are scaling certified product procurement under tightening traceability mandates. BPJPH certification requirements now mandate blockchain-enabled supply chain tracking for cross-border verification. The Jababeka industrial corridor outside Jakarta hosts expanding processing capacity for halal-compliant poultry and packaged foods.
Malaysia
JAKIM standards are restructuring facility audit protocols and raising barriers for uncertified competitors. The Department of Islamic Development mandates supply chain segregation documentation alongside ingredient disclosure for export clearance. Port Klang's logistics cluster is deploying digital certification platforms to accelerate halal cargo processing for Middle Eastern destinations.
United Arab Emirates
ESMA regulations govern shelf space allocation in Dubai and Riyadh retail clusters exhibiting certification-driven preference compression. The Emirates Authority for Standardization and Metrology requires dual-certified products satisfying both Islamic law and EU Green Deal sustainability benchmarks. Dubai's Jebel Ali free zone is consolidating specialty store procurement around premium Halal Certified tiers.
Saudi Arabia
SFDA regulations mandate ingredient transparency for over-the-counter pharmaceuticals and porcine-free wellness products. The Saudi Food and Drug Authority is accelerating audit timelines for cosmetics manufacturers targeting Gulf consumer spending on personal care. Riyadh's retail hubs are displacing convenience store-oriented distribution models with supermarket premium placement.
Brazil
Poultry exporters to Middle Eastern buyers face margin pressure from feed grain price volatility in São Paulo and Paraná processing clusters. Dedicated halal-compliant production lines raise capital barriers for mid-scale processors attempting market entry. The SIF agricultural inspection framework governs slaughter protocol certification for Brazilian protein shipments to Indonesian and Malaysian buyers.
Halal Market Vendor Landscape
The competitive structure tilts toward multi-national conglomerates with certification infrastructure spanning regulatory jurisdictions. Consolidation pressures favor players with dedicated facility segregation and cross-border audit reciprocity agreements. Three archetypes dominate: diversified food conglomerates leveraging multi-country certification, protein processors anchoring regional supply chains, and specialty halal brands capturing premium placement. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Within the diversified conglomerate tier, Nestlé S.A. and Cargill Inc. exemplify players with established multi-country certification infrastructure securing European retail shelf space. Among protein specialists, BRF S.A. occupies a position representing scale advantages in Brazilian poultry exports to Middle Eastern buyers. These three companies anchor the competitive landscape through compliance architecture that satisfies JAKIM, BPJPH, and ESMA requirements simultaneously.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Cargill Inc. |
| BRF S.A. |
| Al Islami Foods |
| QL Resources Sdn Bhd |
| Almarai |
| JBS S.A. |
| Kawan Food Berhad |
| Midamar Corporation |
| Others |
Supply Flow & Price Mechanics
BPJPH's blockchain-enabled traceability mandates for cross-border verification are forcing Southeast Asian processors to absorb facility segregation costs, compressing margins on Halal Compliant economy tiers while premium Halal Certified products capture shelf space premiums in Dubai and Riyadh retail clusters.
Pricing Analysis
Certification-grade anchoring dominates halal pricing architecture. Three-tier pricing structure across premium Halal Certified, mid-tier Halal Approved, and economy Halal Compliant levels stratifies market access. Price differentiation stems from JAKIM audit completion status and supply chain segregation documentation depth. Pricing pressure intensifies in Brazilian poultry exports as feed grain volatility squeezes processor margins. Food service providers demonstrate lowest price sensitivity due to mandatory tier-one supplier qualification requirements, while convenience store procurement absorbs maximum cost pressure.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian poultry processing clusters feeding Middle Eastern import demand. Geographic supply concentration centers on Indonesia's Jababeka corridor, Malaysia's Port Klang logistics hub, and São Paulo's protein processing clusters. Raw material dependencies include feed grains, zabiha-compliant slaughter equipment, and blockchain-enabled traceability infrastructure. Supply chain risk manifests as regulatory fragmentation between BPJPH and ESMA standards creating duplicate audit burdens. Distribution runs through supermarket chains in European retail and specialty store consolidation in Gulf markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The halal market is transitioning from paper-based certification to API-integrated digital verification platforms, with blockchain-enabled supply chain tracking replacing legacy manual audit documentation systems across Southeast Asian and Middle Eastern trade corridors.
For Market Incumbents: Anchor multi-jurisdiction certification infrastructure to defend against auditor capacity constraints threatening facility audit backlogs in Indonesia and Malaysia. Prioritize ERP migration for supply chain segregation tracking to satisfy tightening JAKIM traceability mandates. Backward integration into dedicated halal-compliant production lines raises capital barriers for mid-scale challengers attempting European retail placement. For New Entrants and Emerging Players: Enter via cosmetics and pharmaceuticals white space where Muslim consumer spending on alcohol-free personal care accelerates faster than mature food categories. Target online retail channels with API-integrated verification systems enabling real-time compliance checking for cross-border transactions. Lead with digital-native certification platforms rather than legacy paper-based audit documentation to bypass incumbent ERP migration friction. For Investors and Strategic Acquirers: The window for entry favors mid-scale processors with established BPJPH or JAKIM reciprocity agreements and underdeveloped European retail penetration. Long-term viability rests on regulatory harmonization momentum between Southeast Asian and Gulf authorities. Monitor certification reciprocity negotiations between JAKIM, BPJPH, and ESMA as the critical inflection signal for cross-border trade flow restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | BPJPH mandates are forcing tier-one supplier qualification around unified audit trail platforms. |
| Dual-Certification Investment | EU Green Deal alignment requires carbon footprint reporting alongside JAKIM religious compliance documentation. |
| Cosmetics Portfolio Expansion | Alcohol-free personal care formulations open faster-growing category white space relative to saturated food segments. |
| European Retail Channel Penetration | Supermarket placement for Halal Certified tiers remains underdeveloped relative to convenience store distribution density. |
| Auditor Capacity Buildout | Qualified halal certification auditor shortages compound facility audit backlogs in Indonesia and Malaysia processing hubs. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with halal certification auditors, food service procurement directors, cosmetics formulation chemists, and pharmaceutical regulatory affairs managers combined with secondary validation from JAKIM audit disclosures, BPJPH compliance databases, and ESMA standardization bulletins. Bottom-up facility-level capacity assessments triangulated against top-down trade flow estimates.
Data-stream reconciliation across certification tier volumes, product category trade flows, and channel distribution patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include certification grade, product type, distribution channel, and customer procurement sophistication. CAGRs derived from trend extrapolation of certification reciprocity negotiations and technology adoption curves for blockchain-enabled traceability infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory fragmentation scenarios or accelerated harmonization between BPJPH and ESMA standards. Forecasts reflect assumptions around auditor capacity expansion and ERP migration timelines without guaranteed execution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Organic Skin Care Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Algeria Couscous Market
Specialty Foods
CBD-Infused Ice Cream Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Free-From Food Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Saw Palmetto Market