
 Breakfast Takeout Market | 2026-2036
Breakfast Takeout Market Size, Share, and Industry Trends Forecast 2026-2036
Breakfast Takeout Market Outlook
REACH compliance is hardening material sourcing requirements for disposable containers across European breakfast takeout operations. McDonald's Corporation leverages its global supply chain scale to navigate these transitions ahead of smaller competitors. Starbucks Corporation anchors its position through in-house cup-to-recycling infrastructure that reduces third-party dependency. Dunkin' competes on speed-based formats that minimize packaging complexity without sacrificing throughput.
Breakfast takeout encompasses prepared morning meals engineered for immediate consumption outside traditional dine-in environments, typically featuring hot-held proteins, baked goods, and blended beverages designed for portability within temperature-stable packaging. The category serves commuters, remote workers, and institutional buyers seeking time-compressed nutrition solutions. Sandwiches and pastries dominate volume flows through drive-thru and mobile app channels where order-ahead functionality compresses wait times. Premium and mid-range price tiers capture disproportionate margin pools as consumers trade up on beverage attachments and protein upgrades. Budget tier demand concentrates around value-menu constructs in suburban and exurban trade areas.
FDA food code standards govern temperature control and cross-contamination protocols across US breakfast takeout operations, while EU F-Gas Regulation shapes refrigeration infrastructure decisions in European markets. OSHA workplace safety requirements influence early-morning staffing models and kitchen layout investments. Stakeholders must monitor packaging compliance timelines and labor automation thresholds as regulatory cost burdens diverge across operating geographies.
Market Dynamics
Hybrid work normalization has permanently altered morning consumption patterns, compressing peak demand windows and forcing operators to redesign throughput models around unpredictable commuter flows rather than predictable office-district density.
Growth Catalysts
- Mobile order-ahead infrastructure:Drive-thru lanes and app-based pre-payment systems reduce friction for time-constrained consumers. Deployment concentrates in suburban trade corridors where vehicle access dominates.
- REACH compliance deadlines:EU packaging material restrictions are accelerating investment in fiber-based alternatives and reusable cup schemes. Operators with advanced sourcing capabilities capture regulatory goodwill.
- Office worker segment expansion:Hybrid schedules normalize breakfast consumption outside traditional home preparation. This demographic exhibits higher attachment rates to premium beverage add-ons.
Market Restraints
- Input cost volatility in food-grade packaging:Pulp and biopolymer prices fluctuate with energy markets. Smaller operators lack hedging instruments available to scaled chains.
- Supply concentration in cold-chain equipment:European refrigeration infrastructure depends on limited F-Gas-compliant compressor suppliers. Lead times extend during retrofit cycles.
- Technical limitation in hot-hold duration:Protein and egg-based items degrade in quality beyond 20-minute transport windows. This constrains delivery radius economics.
Strategic Opportunities
- Underpenetrated suburban office parks:Exurban commercial zones in the United States lack dedicated breakfast infrastructure. Ghost kitchen models reduce real estate exposure in these markets.
- EU Green Deal procurement incentives:Public sector catering contracts increasingly mandate reusable packaging quotas. Operators with circular logistics capabilities qualify for preferential vendor status.
- Convergence of IoT sensors and dynamic pricing:Real-time demand forecasting enables surge pricing during compressed morning windows. Early adopters optimize labor deployment against predicted order flow.
Industry Challenges
- Certification timeline compression:FDA food code updates require HACCP plan revisions across multi-unit operations. Compliance documentation burdens strain quality assurance staffing.
- Integration complexity with legacy POS systems:Mobile order injection into kitchen display systems causes ticket sequencing errors. Franchise operators face upgrade costs without corporate subsidy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breakfast Takeout Market |
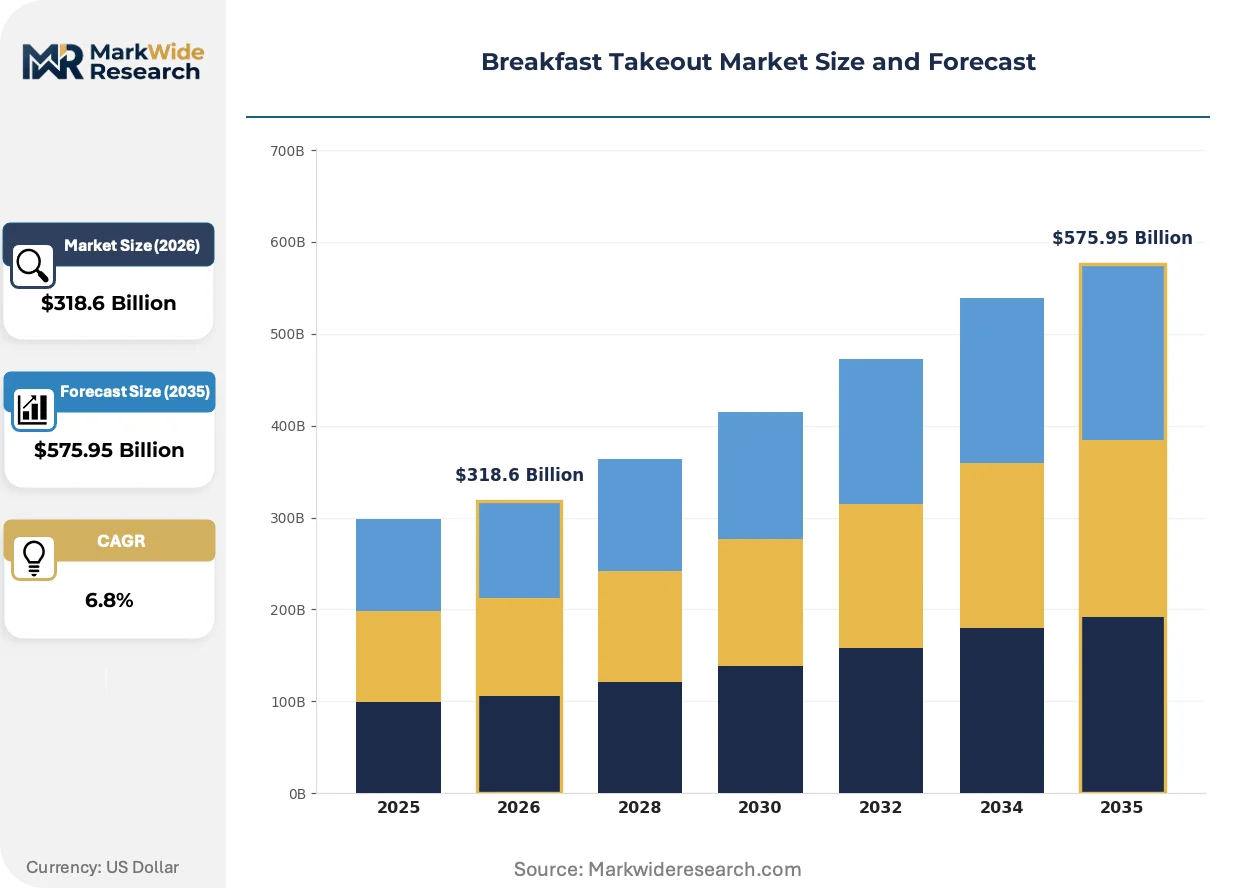
| Market Size in 2026 | $318.6 Billion |
| Market Size in 2035 | $575.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sandwiches, Smoothies, Oatmeal, Pastries End User: Office Workers, College Students, Families, Travelers Distribution Channel: Mobile Apps, Online Ordering, Drive-Thru, In-Store Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | McDonald's Corporation, Starbucks Corporation, Dunkin', Tim Hortons, Subway, Panera Bread, Wendy's, Burger King, Chipotle Mexican Grill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breakfast Takeout Market Strategic Shifts
Operational technology investments are converging around speed optimization and waste reduction, with competitive advantage flowing to operators who compress order-to-handoff intervals while maintaining temperature integrity across extended delivery radii.
Connected kitchen equipment is decentralizing production control across distributed locations. Cloud-based temperature monitoring and automated cooking timers enable remote oversight of breakfast protein holding cabinets. Franchise operators in the United States adopt these systems fastest, reducing district manager travel requirements. The technology is decentralizing quality assurance accountability from regional supervisors to individual unit managers.
EU F-Gas Regulation is forcing refrigeration infrastructure replacement across European breakfast operations. Operators must phase out hydrofluorocarbon-dependent equipment ahead of 2030 bans. Cold-chain retrofit costs concentrate in Germany and France where outlet density is highest. Affected chains are responding with modular equipment leasing to preserve capital flexibility.
Subscription-based morning meal programs are displacing transactional app usage among remote workers in suburban United States markets. Consumers pre-commit to weekly pickup schedules in exchange for price locks and priority queue access. Channel disruption is most visible in Texas and Florida exurbs where commute unpredictability is highest. Traditional loyalty point systems lose traction against this fixed-commitment model.
Breakfast Takeout Market Segmentation
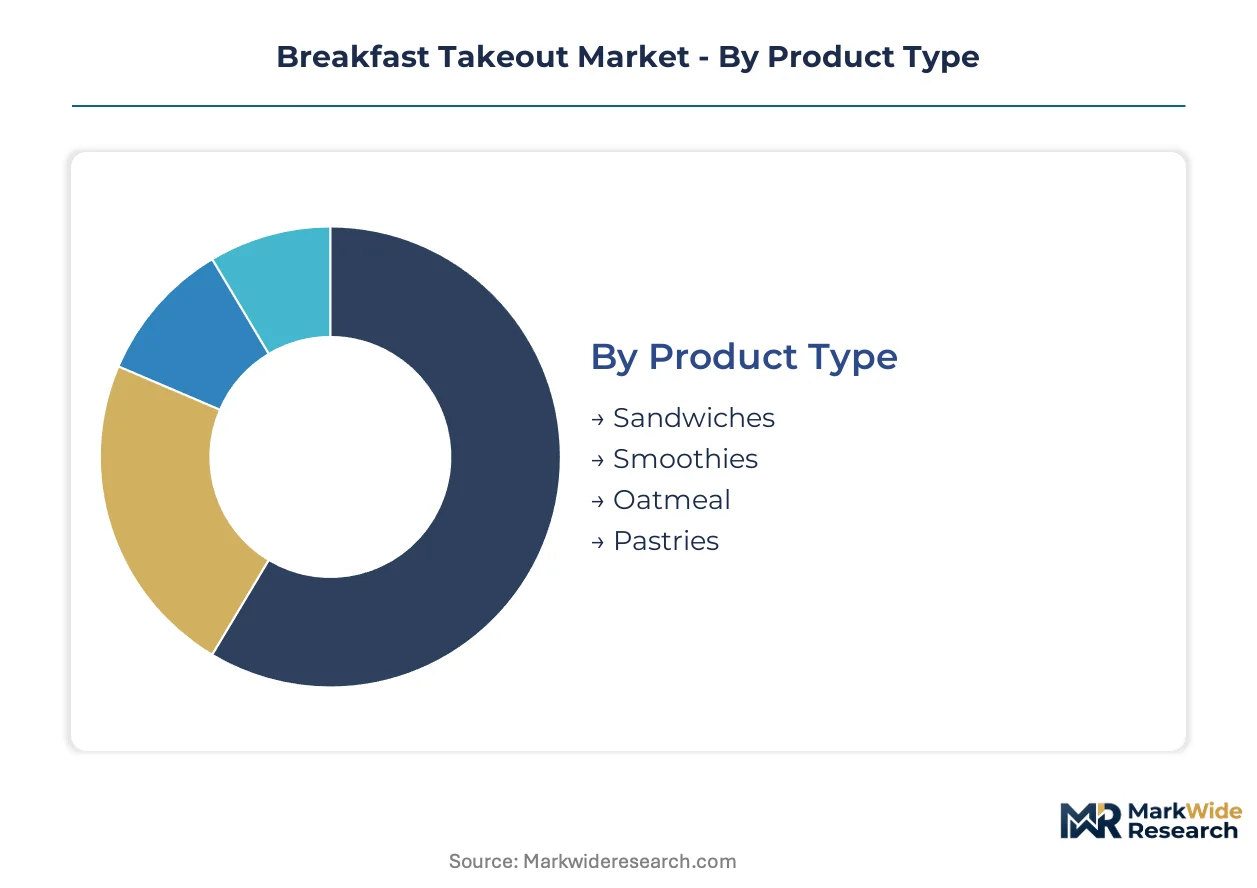
Breakfast takeout operators engineer product portfolios around distinct consumption moments and purchasing contexts. Segment boundaries blur as mobile order-ahead platforms let consumers toggle between price tiers and pickup formats within single transactions.
Product Type:
Formulation complexity and holding stability define competitive positioning across morning menu architectures.
- Sandwiches:Hot-held protein combinations in portable formats dominate drive-thru throughput. Office workers in suburban United States trade corridors attach premium beverage upgrades at higher rates than other product buyers.
- Smoothies:Blended fruit and protein beverages require refrigeration infrastructure and rapid consumption windows. College students in Florida and Texas exurbs favor subscription-based pickup commitments for this category.
- Oatmeal:Hot cereal formats with modular topping stations reduce kitchen labor intensity. Demand concentrates in health-positioned urban locations.
- Pastries:Ambient-stable baked goods enable extended holding without temperature control. European operators navigate REACH compliance in disposable packaging for this grab-and-go staple.
Mature deployment sits with Sandwiches. Newer deployment is concentrated in Smoothies.
End User:
Work-location flexibility has fragmented traditional commuter density patterns across buyer archetypes.
- Office Workers:Hybrid schedules compress consumption into unpredictable morning windows. This cohort exhibits steepest expansion trajectory for mobile order-ahead attachment.
- College Students:Campus-adjacent locations serve price-sensitive demand with value-menu constructs. Meal plan integration drives volume in United States university towns.
- Families:Multi-portion orders with dietary customization requirements strain kitchen sequencing systems. Suburban drive-thru lanes capture weekend clustering behavior.
- Travelers:Airport and highway corridor locations prioritize speed over customization. Limited menu formats reduce decision friction for transient customers.
Established infrastructure serves Office Workers. Emerging investment targets College Students.
Distribution Channel:
Technology integration depth separates capital-flexible chains from legacy operators.
- Mobile Apps:Native applications with stored payment and predictive reordering capture habitual usage. Franchise operators face POS integration costs without corporate subsidy.
- Online Ordering:Web-based platforms aggregate third-party delivery demand. Commission structures compress margins on protein-heavy orders.
- Drive-Thru:Dedicated vehicle lanes with dual-menu boards maximize throughput per labor hour. United States suburban infrastructure remains unmatched for this format.
- In-Store:Counter service with grab-and-go display cases serves walk-up urban demand. European operators redesign layouts around reusable cup schemes.
Volume concentration favors Drive-Thru. Capability investment flows to Mobile Apps.
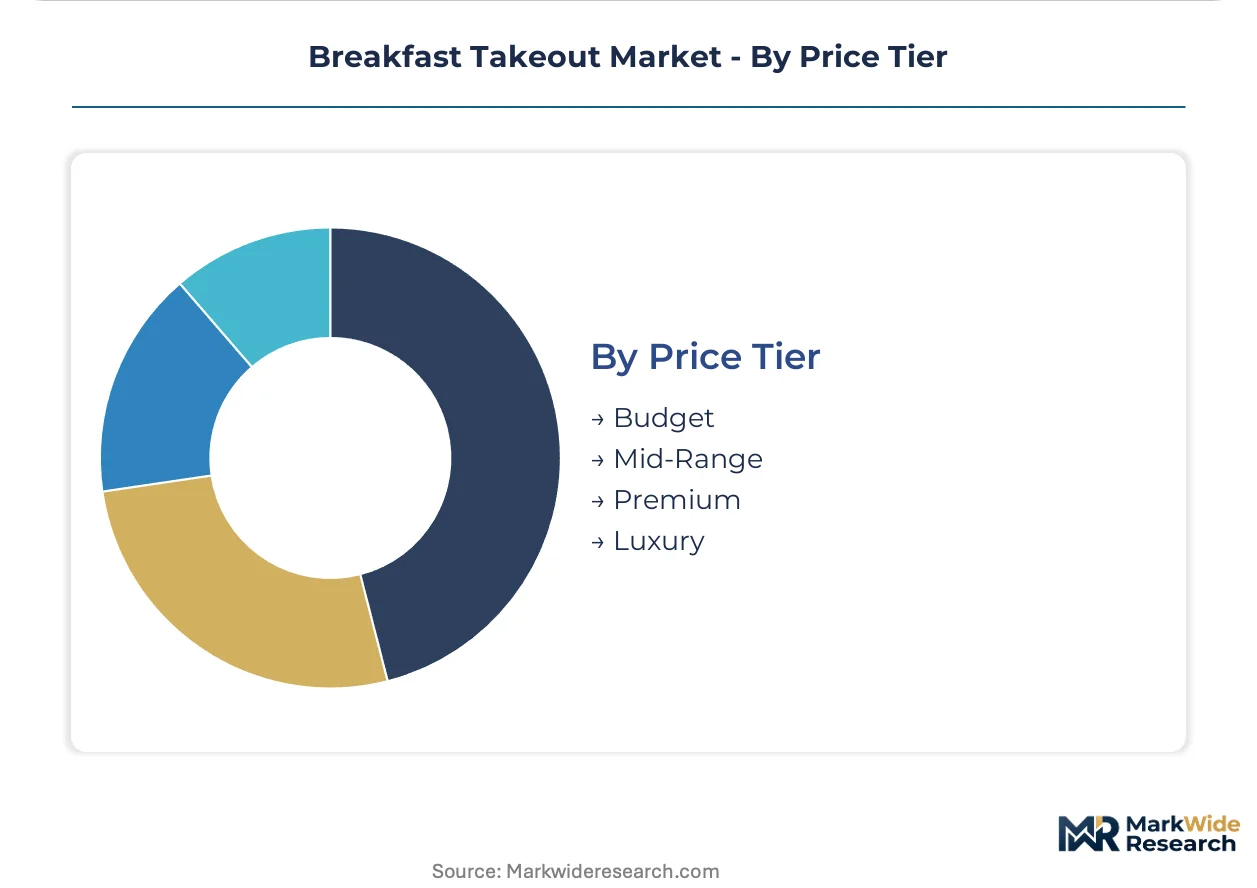
Price Tier:
Margin architecture stratifies across ingredient sourcing and service format premiums.
- Budget:Value-menu constructs with limited customization target exurban commute corridors. Price locks through subscription programs displace transactional loyalty.
- Mid-Range:Standard protein upgrades and beverage attachments capture mainstream demand. This tier absorbs quality trade-offs during input cost volatility.
- Premium:Specialty ingredients and ethical sourcing claims justify price elevation. Cold-chain integrity requirements constrain delivery radius economics.
- Luxury:Chef-designed formats with seasonal rotation serve affluent urban enclaves. Limited throughput scalability restricts location count.
Margin stability rests with Mid-Range. Positioning innovation clusters in Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States drive-thru infrastructure captures the dominant share of breakfast takeout volume, while European operators navigate packaging compliance deadlines and Asian markets expand mobile-first formats.
United States
Suburban office corridors and exurban commuter belts concentrate demand for speed-optimized formats. FDA food code standards govern temperature control protocols across multi-state operations. Texas and Florida exurbs lead adoption of subscription-based morning meal programs that displace traditional loyalty systems.
Germany
Urban centers in North Rhine-Westphalia and Bavaria drive demand for reusable packaging schemes. EU F-Gas Regulation mandates refrigeration infrastructure replacement ahead of 2030 bans. Berlin-Brandenburg operators deploy modular equipment leasing to preserve capital flexibility during cold-chain retrofits.
United Kingdom
London and Southeast England anchor grab-and-go density in transit-adjacent locations. REACH compliance deadlines accelerate fiber-based packaging transitions. Midlands ghost kitchen clusters serve underpenetrated suburban office parks with reduced real estate exposure.
France
Île-de-France commuter rail corridors sustain high-frequency morning consumption. ANSM and ECHA enforcement hardens material sourcing requirements for disposable containers. Lyon and Marseille operators redesign service formats around reusable cup quotas mandated by EU Green Deal procurement incentives.
Japan
Kanto and Kansai metropolitan areas concentrate demand for premium convenience formats. METI efficiency standards shape kitchen equipment selection in dense urban locations. Nagoya industrial corridors test IoT-enabled dynamic pricing during compressed morning demand windows.
Breakfast Takeout Market Competitive Environment
United States chains anchor the scale-driven tier; European specialists hold regulatory compliance advantages. The vendor base stratifies across three operational archetypes: global quick-service networks with captive supply chains, regional bakery-café formats with premium positioning, and emerging ghost kitchen operators with asset-light models. Competitive moves concentrate on mobile order-ahead infrastructure deployment and fiber-based packaging sourcing partnerships.
Within the global quick-service tier, McDonald's Corporation and Starbucks Corporation exemplify divergent strategic positions. McDonald's leverages global supply chain scale to navigate packaging transitions ahead of smaller competitors. Starbucks anchors its position through in-house circular infrastructure that reduces third-party dependency. Dunkin' occupies a speed-optimized niche that minimizes packaging complexity without sacrificing throughput.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Starbucks Corporation |
| Dunkin' |
| Tim Hortons |
| Subway |
| Panera Bread |
| Wendy's |
| Burger King |
| Chipotle Mexican Grill |
| Others |
Value Chain & Pricing Dynamics
Pulp futures and biopolymer feedstock indices cascade through breakfast takeout economics, compressing margin pools at the budget tier while REACH compliance costs concentrate in European premium positioning. Input volatility reshapes tier boundaries as operators hedge fiber-based packaging exposure against energy-linked resin prices.
Pricing Analysis
Volume concentrates in mid-range sandwich-and-beverage bundles where protein upgrades drive attachment economics, while premium tiers capture margin through ethical sourcing claims and cold-chain integrity premiums. Price differentiation hinges on certification grade for reusable packaging schemes and geographic delivery cost for extended-radius mobile orders. Pricing pressure stems from pulp input volatility squeezing fiber-based container economics. Budget-tier suburban commuters exhibit highest price sensitivity; premium urban office workers show lowest elasticity to beverage attachment pricing.
Supply Chain Analysis
EU domestic-content mandates for fiber-based packaging are reshaping sourcing patterns across breakfast takeout operations. Raw material flows concentrate in Sweden, Finland, and Portugal for molded pulp feedstocks; biopolymer resins source from Germany and the Netherlands. Cold-chain equipment draws from limited F-Gas-compliant compressor suppliers in Germany and Italy, creating single-source vulnerability during retrofit cycles. Distribution runs through centralized commissary networks feeding suburban drive-thru clusters and urban ghost kitchen satellites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Breakfast takeout operates as a cost-of-compliance market where EU REACH deadlines and FDA food code updates erect barrier-to-entry moats favoring scaled operators with dedicated regulatory affairs infrastructure.
For Market Incumbents: Cement supply chain resilience through backward integration into fiber-based packaging molding capacity in Nordic pulp-producing regions. Lock in F-Gas-compliant refrigeration supplier relationships ahead of 2030 phase-out deadlines. Ghost kitchen entrants threaten suburban office park density; defend through exclusive mobile app subscription programs that pre-commit habitual usage. For New Entrants and Emerging Players: EU Green Deal procurement incentives in France and Germany open a window for circular logistics specialists to capture public-sector catering contracts with reusable cup quota compliance. Target underpenetrated Texas and Florida exurbs where subscription-based morning meal programs displace traditional loyalty systems. Enter through asset-light ghost kitchen models with IoT-enabled dynamic pricing capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional chains with established mobile order-ahead infrastructure in United States suburban corridors. Long-term viability hinges on regulatory compliance scalability across multi-state FDA jurisdiction and EU member state packaging mandates. Watch F-Gas retrofit completion rates as inflection indicator for European operator capital flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Packaging | Nordic pulp sourcing secures REACH-compliant container supply ahead of competitor transitions. |
| Mobile Order-Ahead Infrastructure Deployment | Native app ecosystems with predictive reordering capture habitual suburban commuter usage patterns. |
| F-Gas-Compliant Refrigeration Retrofit | Modular equipment leasing preserves capital flexibility during EU-mandated cold-chain upgrades. |
| Subscription-Based Morning Meal Programs | Weekly pre-commitment models displace transactional loyalty in Texas and Florida exurban markets. |
| Reusable Cup Circular Logistics | EU Green Deal procurement qualification opens public-sector catering contract access in France and Germany. |
Study Parameters
Multi-period observation of mobile order-ahead penetration rates, packaging material cost indices, and hybrid work normalization patterns anchored the trend analysis, supplemented by interviews with quick-service operations directors, supply chain procurement leads, franchise development executives, and regulatory compliance officers. Secondary validation drew from FDA food code update dockets, ECHA REACH implementation timelines, EU F-Gas Regulation guidance documents, and quick-service chain SEC filings. Bottom-up unit economics modeling triangulated against top-down market sizing across geographic clusters.
Segment-weighting approaches distributed value and volume across product type, end user archetype, distribution channel technology depth, and price tier positioning. CAGRs derived from trend extrapolation of mobile order-ahead adoption curves, pulp and biopolymer price trajectory assumptions, and labor automation threshold modeling. Forecast inputs incorporated IoT sensor deployment rates for dynamic pricing capabilities and reusable packaging return-loop logistics maturation.
The model assumes a particular technology adoption path for connected kitchen equipment and cloud-based temperature monitoring; alternative pathways for AI-driven demand forecasting would alter the outlook for labor deployment optimization. Forecasts reflect assumptions on regulatory timeline adherence and commodity price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Instant Grocery Market
Food Service
Gas Fryers Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Cutting Boards Market
Food Service
South Africa Fast Food Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Beverage Coaster Market
Food Service
Virtual Kitchen Market
Food Service
Global Digital Food Delivery Market
Food Service
Australia Foodservice Market
Food Service
Commercial Burger Grill Market
Food Service
Charbroiler Market
Food Service
Commercial Cutlery Market
Food Service
Europe Pizza Oven Market
Food Service
Plates Market
Food Service
South America Free from Food Market