
 Global Sushi Restaurants Market | 2026-2036
Global Sushi Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sushi Restaurants Market Outlook
FSSC 22000 certification for seafood cold-chain management is reorganizing competitive access in the Global Sushi Restaurants Market. Sushiro leverages automated plate-tracking systems to sustain operational efficiency across its conveyor-belt network. Hana Group anchors North American expansion through centralized fish procurement and commissary kitchens. Kura Sushi competes on gamified dining technology that reduces labor dependency per cover.
Sushi restaurants are foodservice establishments specializing in vinegared rice combined with raw or cooked seafood, vegetables, and seasonings, requiring precise temperature control at 0-4°C for raw fish storage to prevent histamine formation and parasitic risk. Their primary commercial purpose centers on delivering prepared-to-order Japanese cuisine through skilled itamae craftsmanship or mechanized service systems. The dine-in segment dominates revenue capture through premium omakase experiences and social dining occasions, while delivery is accelerating fastest as insulated packaging innovations preserve rice texture during transport. Mid-range pricing occupies the largest volume pool, though luxury tiers command disproportionate margin concentration through scarcity-driven reservation models.
Japan's Ministry of Health, Labour and Welfare enforces strict Anisakis screening protocols for raw seafood service, while the FDA in the United States mandates parasite destruction through freezing or sourcing from approved suppliers under the Fish and Fishery Products Hazards and Controls Guidance. The EU's General Food Law Regulation requires full traceability documentation for tuna and salmon supply chains entering European sushi kitchens. Stakeholders must monitor evolving national standards on raw fish handling as cross-border supply chain complexity intensifies certification burdens.
Market Dynamics
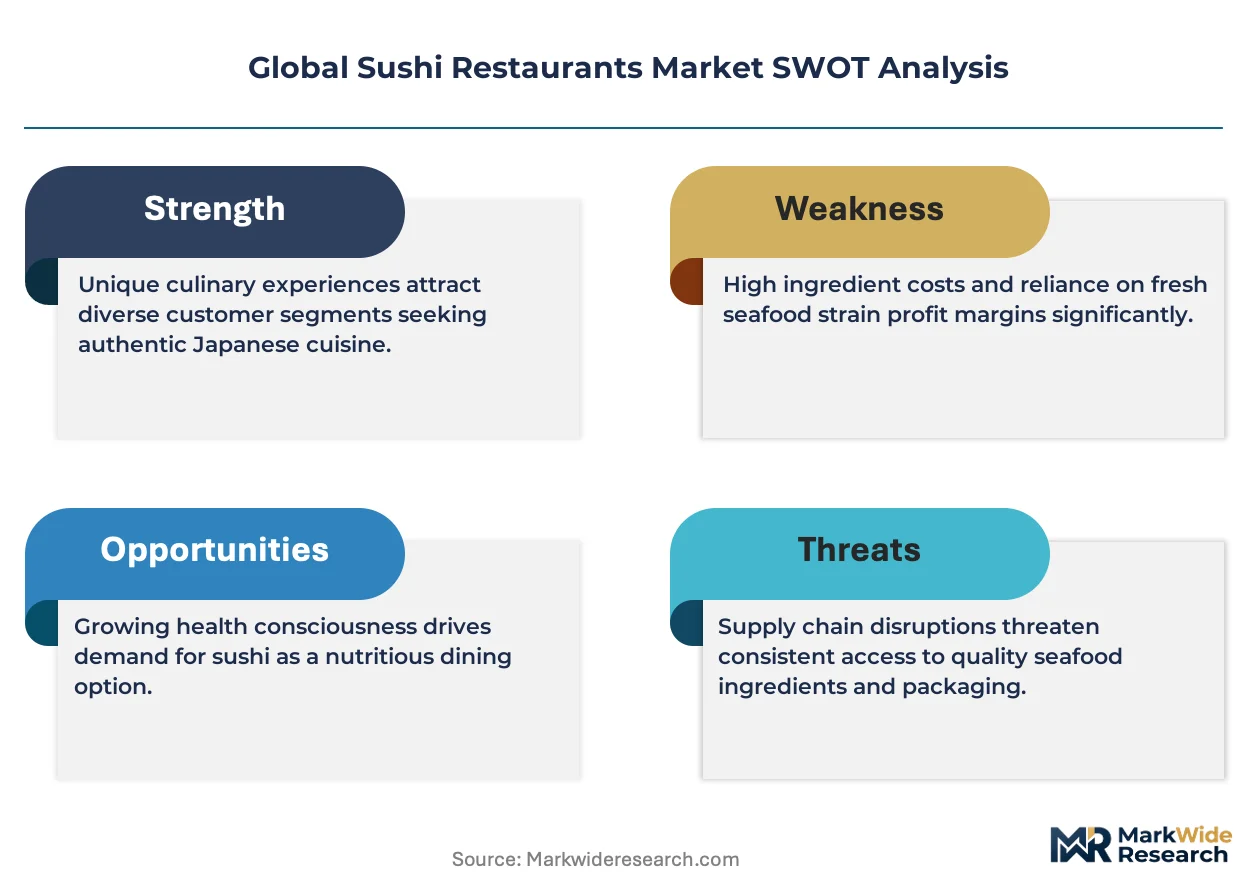
FSSC 22000 cold-chain certification is consolidating competitive access across the Global Sushi Restaurants Market, forcing smaller operators toward commissary partnerships or exit as compliance costs escalate.
Growth Catalysts
- Omakase Experiential Demand:Affluent professionals in Tokyo, Los Angeles, and London are driving reservation scarcity models that capture disproportionate margin concentration through chef-curated tasting menus.
- FDA Parasite Destruction Protocols:Approved supplier frameworks under Fish and Fishery Products Hazards and Controls Guidance are professionalizing raw seafood sourcing and reducing liability exposure for multi-unit operators.
- Insulated Packaging Innovation:Rice texture preservation during transport is accelerating delivery segment expansion beyond traditional dine-in capture.
Market Restraints
- Bluefin Tuna Supply Concentration:Auction gravity at Tokyo's Toyosu Market creates price volatility and procurement risk for operators outside Japan's centralized distribution networks.
- Itamae Skill Scarcity:Ten-year apprenticeship requirements limit labor pool expansion and constrain unit economics for craft-dependent omakase concepts.
- EU General Food Law Traceability Burden:Full documentation requirements for tuna and salmon supply chains impose administrative overhead that disadvantages independent operators.
Strategic Opportunities
- Gamified Conveyor-Belt Expansion:Automated plate-tracking and prize-dispensing systems reduce labor dependency per cover while attracting family dining segments in suburban United States markets.
- Centralized Commissary Kitchens:North American operators can replicate Hana Group's procurement consolidation model to achieve scale advantages in fish sourcing and rice preparation standardization.
- Japan's METI Export Promotion:Government-backed washoku cultural certification programs create brand leverage for authentic Japanese concepts entering European and North American markets.
Industry Challenges
- Anisakis Screening Compliance:Japan's Ministry of Health, Labour and Welfare protocols require specialized freezing equipment and training that extends new-store opening timelines.
- Cross-Border Cold-Chain Integrity:Maintaining 0-4°C storage through multi-hop logistics from Tsukiji-adjacent suppliers to distant markets demands capital-intensive reefers and real-time monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sushi Restaurants Market |
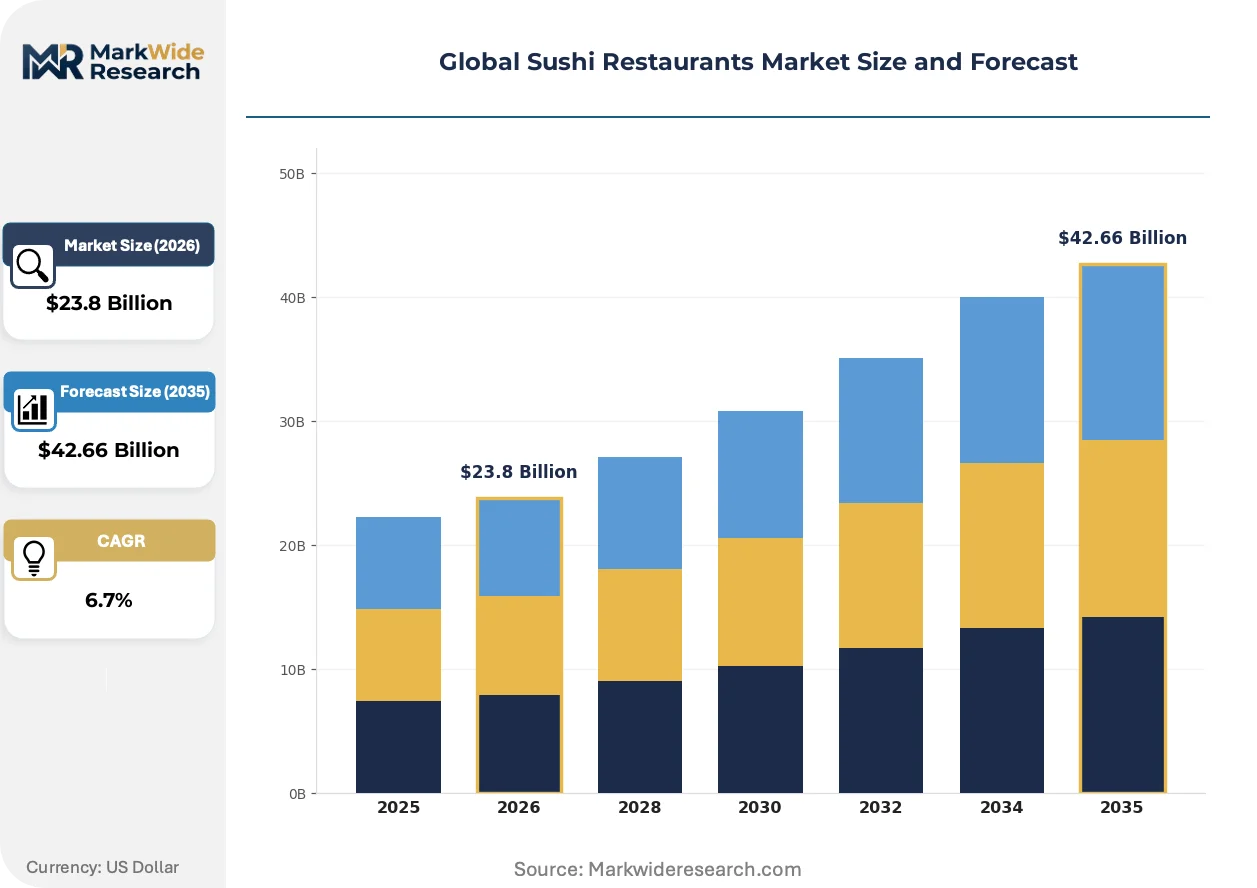
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-in, Takeout, Delivery, Catering Customer Type: Families, Couples, Professionals, Tourists Price Tier: Budget, Mid-range, Premium, Luxury Menu Type: Traditional, Fusion, Vegetarian, Vegan |
| Companies Covered | SUMO, Sushiro, YO!SUSHI, The Araki, Izumi, Hana Group, Genki Sushi, Sasaya, Kura Sushi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sushi Restaurants Market Strategic Shifts
Automation and certification convergence are restructuring operational models across service tiers, compressing the viable middle while amplifying returns at both premium craft and mechanized scale extremes.
Automated plate-tracking systems with RFID-enabled inventory management are bifurcating the conveyor-belt segment. Sushiro-type operators deploy these technologies to sustain throughput with reduced floor staffing, while independent kaiten-zushi concepts lacking capital for retrofitting face margin compression and market exit. The technology is enabling centralized kitchen models that separate rice preparation from front-of-house service entirely.
Japan's FSSC 22000 food safety certification requirements are tightening cold-chain standards for raw fish handling. Operators must demonstrate continuous temperature logging and hazard analysis protocols that exceed legacy local health department inspections. Premium omakase kitchens in Tokyo and London are responding by investing in dedicated reefers with blockchain-traceable supply documentation.
Consumer preference is rotating toward reservation-scarcity dining experiences that signal cultural capital. Young professionals in flagship markets are displacing spontaneous walk-in patronage with prepaid tasting-menu commitments secured months in advance. This behavioral shift is most visible in Los Angeles, where omakase-only concepts are capturing share from traditional à la carte sushi bars through Instagram-native discovery channels.
Global Sushi Restaurants Market Segmentation
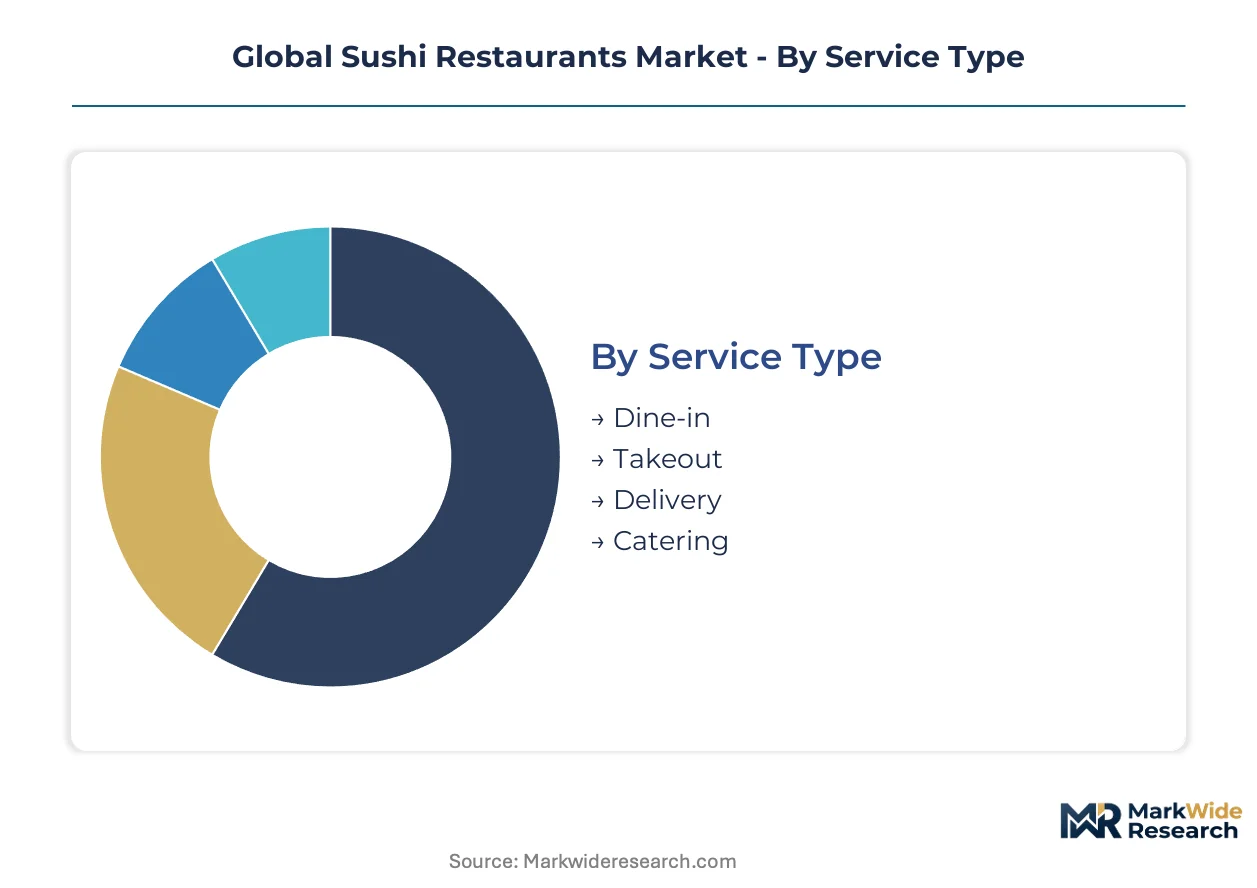
Segmentation in the Global Sushi Restaurants Market reveals how operational format and customer occasion dictate cold-chain investment, labor intensity, and real estate requirements. Operators configure service systems, pricing architecture, and menu engineering around distinct demand clusters that respond differently to FSSC 22000 compliance costs and itamae scarcity constraints.
Service Type:
Dine-in formats command the highest fixed-cost base but capture experiential premium, while off-premise channels leverage insulated packaging to extend reach beyond traditional trade areas.
- Dine-in:Full-service formats encompass omakase counters, conveyor-belt systems, and à la carte dining rooms requiring precise temperature-controlled display cases and trained itamae presence. Tokyo's Ginza district and Los Angeles's West Hollywood corridor concentrate reservation-scarcity omakase concepts where chef-curated tasting menus justify premium pricing through theatrical preparation rituals.
- Delivery:Insulated packaging with phase-change materials preserves rice texture and fish integrity during 30-60 minute transport windows, enabling suburban penetration beyond traditional restaurant density. Demand concentrates among young professionals in London's Zone 2-3 residential clusters where convenience outweighs experiential trade-offs.
- Takeout:Pre-rolled maki and chirashi bowls in refrigerated grab-and-go cases serve office districts and transit hubs with minimal labor interaction. Japan's railway station ecosystems and Manhattan's Midtown corridors represent mature deployment zones.
- Catering:Large-format platters for corporate events and private celebrations require batch production protocols and specialized transport logistics that diverge from standard restaurant operations. Wedding venues in California's Orange County and corporate campuses in Singapore's One-North district drive occasional high-volume demand.
By volume, Dine-in leads. By growth pace, Delivery is expanding most quickly.
Customer Type:
Different patron cohorts exhibit divergent tolerance for price, wait times, and authenticity signaling, shaping how concepts calibrate menu breadth and service ceremony.
- Families:Conveyor-belt formats with gamified plate-tracking and portion flexibility dominate this segment, particularly in suburban United States markets where children's engagement extends meal duration and per-cover spending. Kura Sushi-type operators optimize for this cohort through prize-dispensing mechanics and reduced itamae dependency.
- Professionals:Power-lunch and after-work occasions in financial districts favor speed, discretion, and status-appropriate environments. Mid-range à la carte concepts in London's Square Mile and Tokyo's Marunouchi district configure counter seating for solo diners with 45-minute service targets.
- Couples:Date-night occasions prioritize intimacy and discovery, driving demand for chef's table configurations and seasonal menu rotations in Los Angeles's Arts District and Brooklyn's Williamsburg. This cohort shows highest willingness to prepay for reservation-scarcity experiences.
- Tourists:Cultural authenticity seeking and price transparency preferences concentrate demand near landmarks and hospitality corridors. Tsukiji-adjacent operators in Tokyo and Shibuya's scramble crossing zone capture walk-in volume through visible preparation theaters and multilingual menu systems.
By volume, Families lead. By margin concentration, Professionals generate the highest per-visit yield.
Price Tier:
Cost stratification determines supply chain sourcing depth, certification tier, and real estate positioning across the market's vertical structure.
- Luxury:Omakase-only concepts with chef-proprietor ownership and Toyosu Market direct procurement occupy the apex, typically seating 8-12 guests across 2-3 nightly seatings. Los Angeles's Sushi Ginza Onodera and Tokyo's Sukiyabashi Jiro represent this tier's scarcity-driven reservation economics.
- Premium:Full-service restaurants with trained itamae teams and documented supply provenance occupy downtown and affluent suburban locations. This tier bears FSSC 22000 compliance costs most directly through dedicated reefers and blockchain traceability systems.
- Mid-range:Hybrid formats combining some craft preparation with standardized components capture the largest addressable volume. Hana Group's North American commissary model enables this tier's cost structure through centralized fish procurement and rice preparation.
- Budget:Automated conveyor-belt systems and pre-packaged retail formats minimize labor and real estate costs per cover. Sushiro's global network exemplifies this tier's capital-intensive, labor-light operational template.
By unit count, Budget leads. By revenue concentration, Luxury commands disproportionate returns.
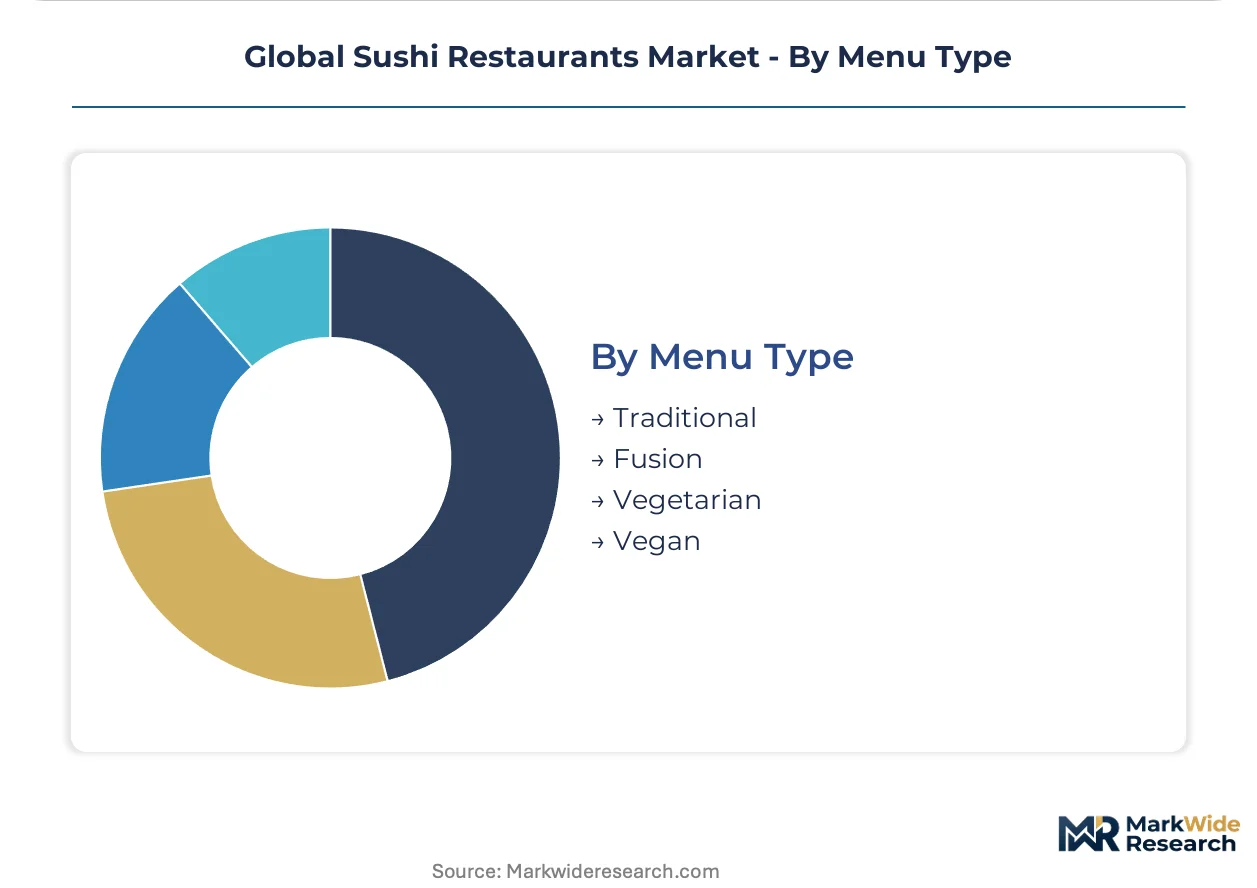
Menu Type:
Ingredient philosophy and cultural positioning determine supply chain complexity, allergen management protocols, and cross-selling potential.
- Traditional:Edomae-style preparation emphasizing seasonal fish, aged vinegared rice, and minimal garnish requires highest itamae skill density and Japan-sourced specialty ingredients. Concepts in Tokyo's Kagurazaka and New York's East Village anchor this segment's authenticity signaling.
- Fusion:Cross-cultural ingredient combinations and technique hybrids attract experimental diners in cosmopolitan gateway cities. Los Angeles's Little Tokyo and London's Soho districts concentrate this segment's menu innovation and social media visibility.
- Vegetarian:Plant-forward maki and nigiri utilizing seasonal vegetables, aged tofu, and egg-based preparations serve dietary-restricted diners without raw fish liability. This segment expands fastest in European markets with strong flexitarian consumer bases.
- Vegan:Elimination of all animal products including fish sauce and egg requires complete supply chain reconfiguration and dedicated preparation zones to prevent cross-contamination. Berlin's Kreuzberg and Portland's Hawthorne district host pioneering concepts in this emerging tier.
By volume, Traditional leads. By growth pace, Vegan is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI washoku export promotion programs are accelerating authentic concept expansion into European and North American markets, while FDA and EU food safety protocols reshape operational compliance costs for cross-border operators.
United States
Affluent professionals in Los Angeles and New York drive reservation-scarcity omakase demand through prepaid tasting-menu models. FDA parasite destruction protocols under Fish and Fishery Products Hazards and Controls Guidance professionalize raw seafood sourcing for multi-unit chains. California's Orange County wedding venues and corporate campuses generate high-volume catering demand for large-format platter specialists.
Japan
Domestic consumers sustain premium dine-in culture through chef-proprietor concepts in Tokyo's Ginza and Kagurazaka districts. Ministry of Health, Labour and Welfare Anisakis screening protocols require specialized freezing equipment that extends new-store timelines. Toyosu Market auction gravity concentrates bluefin tuna procurement networks, creating price volatility for operators outside centralized distribution systems.
United Kingdom
Young professionals in London's Zone 2-3 residential clusters accelerate delivery segment expansion through convenience-prioritized ordering. EU General Food Law traceability requirements impose administrative overhead for tuna and salmon supply chains entering British sushi kitchens. The Square Mile financial district anchors power-lunch demand for speed-optimized counter seating configurations.
Germany
Flexitarian consumer bases in Berlin's Kreuzberg and Hamburg drive plant-forward menu innovation across vegetarian and vegan tiers. EFSA food safety standards govern raw fish service protocols for imported seafood entering European distribution networks. Bavaria's affluent suburban markets attract family-oriented conveyor-belt concepts with gamified dining technology.
Singapore
Corporate campuses in One-North district and tourism corridors near Marina Bay sustain high-margin catering and walk-in demand. The country's national food agency enforces strict cold-chain documentation for imported seafood transiting through regional distribution hubs. Orchard Road hospitality clusters concentrate mid-range hybrid concepts targeting business travelers and expatriate professionals.
Global Sushi Restaurants Market Competitive Environment
Listed leaders compete with private specialists across capital access and operational agility dimensions. The vendor base organizes around scale-driven conveyor-belt networks, chef-proprietor omakase studios, and commissary-dependent regional chains. Three archetypes dominate: automation-heavy kaiten-zushi operators, authenticity-signaling craft concepts, and centralized procurement consolidators. Competitive moves concentrate on geographic licensing partnerships and cold-chain infrastructure investments.
Within the automation tier, Kura Sushi and Sushiro exemplify capital-intensive, labor-light operational templates that reduce floor staffing through RFID-enabled plate tracking. Hana Group anchors the commissary-consolidation archetype for North American expansion. Chef-proprietor concepts like The Araki occupy the scarcity-driven premium tier where reservation economics command disproportionate returns through theatrical preparation rituals and documented Toyosu Market sourcing.
| Leading Market Players |
|---|
| SUMO |
| Sushiro |
| YO!SUSHI |
| The Araki |
| Izumi |
| Hana Group |
| Genki Sushi |
| Sasaya |
| Kura Sushi |
| Others |
Value Chain & Pricing Dynamics
Seven-to-fourteen-day cold-chain lead times from Tsukiji-adjacent suppliers to North American kitchens compress margin buffers and amplify pricing power for operators with captive reefers. Toyosu Market auction gravity concentrates bluefin tuna procurement networks, forcing distant buyers into premium bidding positions or secondary sourcing tiers.
Pricing Analysis
Certification level (FSSC 22000/Anisakis-screened/FDA-approved) creates the primary spread between luxury omakase studios and budget conveyor-belt networks. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain investment depth and itamae density per cover. Pricing pressure stems from EU General Food Law traceability burdens that inflate administrative overhead for mid-range independents. Budget-tier family diners exhibit highest price sensitivity, while reservation-scarcity omakase patrons show near-zero elasticity.
Supply Chain Analysis
Japan and Norway anchor global salmon and tuna supply for premium sushi kitchens, with Chile and Scotland contributing farmed salmon volumes for mid-range operators. Raw fish sourcing draws from Toyosu Market auctions, specialized freezing facilities for parasite destruction, and blockchain-traceable documentation systems. Single-source vulnerability concentrates in Tokyo's auction gravity for bluefin tuna, disrupting price stability for non-Japanese operators. Distribution runs through regional commissary hubs in North America and direct air freight to European flagships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Sushi Restaurants Market sits in early-cycle expansion as insulated packaging innovations unlock suburban delivery penetration beyond traditional trade-area constraints.
For Market Incumbents: Consolidate procurement scale through centralized commissary investments that replicate Hana Group's North American model, neutralizing FSSC 22000 compliance cost escalation that threatens smaller competitors. Deepen backward integration into dedicated reefer fleets and blockchain-traceable supplier relationships to defend margin position against raw material volatility at Toyosu Market. For New Entrants and Emerging Players: Suburban family dining gaps in secondary US metros present white-space targets where gamified conveyor-belt concepts can displace aging independents lacking capital for RFID plate-tracking retrofit. Plant-forward vegan and vegetarian tiers in European flexitarian markets offer the most penetrable entry vector, with Berlin and Portland hospitality corridors supporting dedicated preparation-zone concepts absent cross-contamination liability. For Investors and Strategic Acquirers: Carve-out targets emerge from hospitality conglomerates divesting non-core sushi assets amid post-pandemic portfolio rationalization. Long-term viability favors automation-heavy kaiten-zushi networks and chef-proprietor omakase studios with documented Toyosu sourcing relationships. The signal to watch is FDA enforcement intensity on parasite destruction protocols, which would accelerate professionalization and consolidation among under-capitalized independents.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | Dedicated reefers with real-time temperature logging satisfy Japan's FSSC 22000 certification requirements. |
| Centralized Commissary Expansion | Hana Group's procurement consolidation model enables mid-range cost structures through rice preparation standardization. |
| Gamified Dining Technology Deployment | Kura Sushi-type RFID plate-tracking reduces labor dependency per cover in suburban family markets. |
| Plant-Forward Menu Innovation | Vegan and vegetarian tiers capture flexitarian demand in European markets without raw fish liability exposure. |
| Chef-Proprietor Omakase Licensing | METI washoku certification programs create brand leverage for authentic Japanese concepts entering Western markets. |
Study Parameters
Cross-validation between primary interviews with itamae chefs, restaurant operators, and cold-chain logistics specialists and secondary validation through FDA Fish and Fishery Products Hazards and Controls Guidance filings, EU General Food Law traceability databases, and Japan's Ministry of Health, Labour and Welfare Anisakis screening protocols anchors the qualitative findings. Bottom-up unit economics modeling triangulates with top-down market sizing from hospitality industry associations and foodservice equipment trade data.
Sensitivity analysis across the analysis window tests demand elasticity for reservation-scarcity omakase versus convenience-prioritized delivery channels. Segmentation dimensions modeled include service type, customer occasion, price tier, and menu philosophy. CAGRs derive from trend extrapolation of dine-in recovery patterns and insulated packaging adoption curves in suburban delivery corridors.
Material uncertainties — regulatory enforcement intensity on raw fish handling, Toyosu Market auction volatility, and itamae apprenticeship pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions about cold-chain technology diffusion and consumer rotation toward experiential dining. Recalibration cycles align with material shifts in FDA protocol updates and METI export promotion program expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Steam Tables and Food Well Market
Food Service
Vietnam Food Service Market
Food Service
Global Digital Grocery Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
Shaker Bottles Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Commercial Ice Dispenser Market
Food Service
Light Meal Market
Food Service
Europe Food Service Market
Food Service
Hospital Food Services Market
Food Service
Chinese Takeout Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
United States Online Food Delivery Market