
 Europe Food Coating Ingredients Market | 2026-2036
Europe Food Coating Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Coating Ingredients Market Foresight
Foodservice distribution channels across Europe is reconfiguring as quick-service chains and contract caterers consolidate procurement around pre-coated protein and vegetable platforms. Kerry Group plc leverages its savory taste and texture portfolio to anchor supply relationships with industrial fryer operators. Cargill Incorporated competes through its integrated oil and starch supply chain, extending cost advantages into batter and breading formulations. Bowman Ingredients specializes in gluten-free and allergen-managed coating systems, occupying a defensible niche in British and Irish manufacturing.
Europe food coating ingredients encompass functional mixtures of starches, flours, breadcrumbs, batters, and adhesion agents applied to food surfaces to control moisture retention, texture, and appearance during frying or baking. These systems typically operate at hydration ratios between 1.5:1 and 3:1 water-to-dry-ingredient, with viscosity measured in Brookfield units to ensure uniform pick-up on conveyor lines. Breadcrumbs and batters command the largest volume positions across snack and frozen food applications, where standardization of crunch retention and oil uptake drives specification. Powder and liquid forms diverge in margin structure: powders freight efficiently and store without refrigeration, while liquid batters reduce dust exposure and allow inline viscosity adjustment at processor sites.
EFSA establishes maximum residue thresholds and additive authorizations that directly constrain hydrocolloid and modified starch selections in coating recipes. REACH compliance and EU Green Deal sourcing mandates push manufacturers toward domestically produced wheat and potato starches with traceable supply chains. The EU F-Gas Regulation indirectly shapes frozen food demand by phasing down hydrofluorocarbon cooling, altering cold-chain economics for coated products. Stakeholders must monitor evolving ECHA classifications on food-contact substances and position formulation pipelines ahead of anticipated restriction expansions.
Market Dynamics
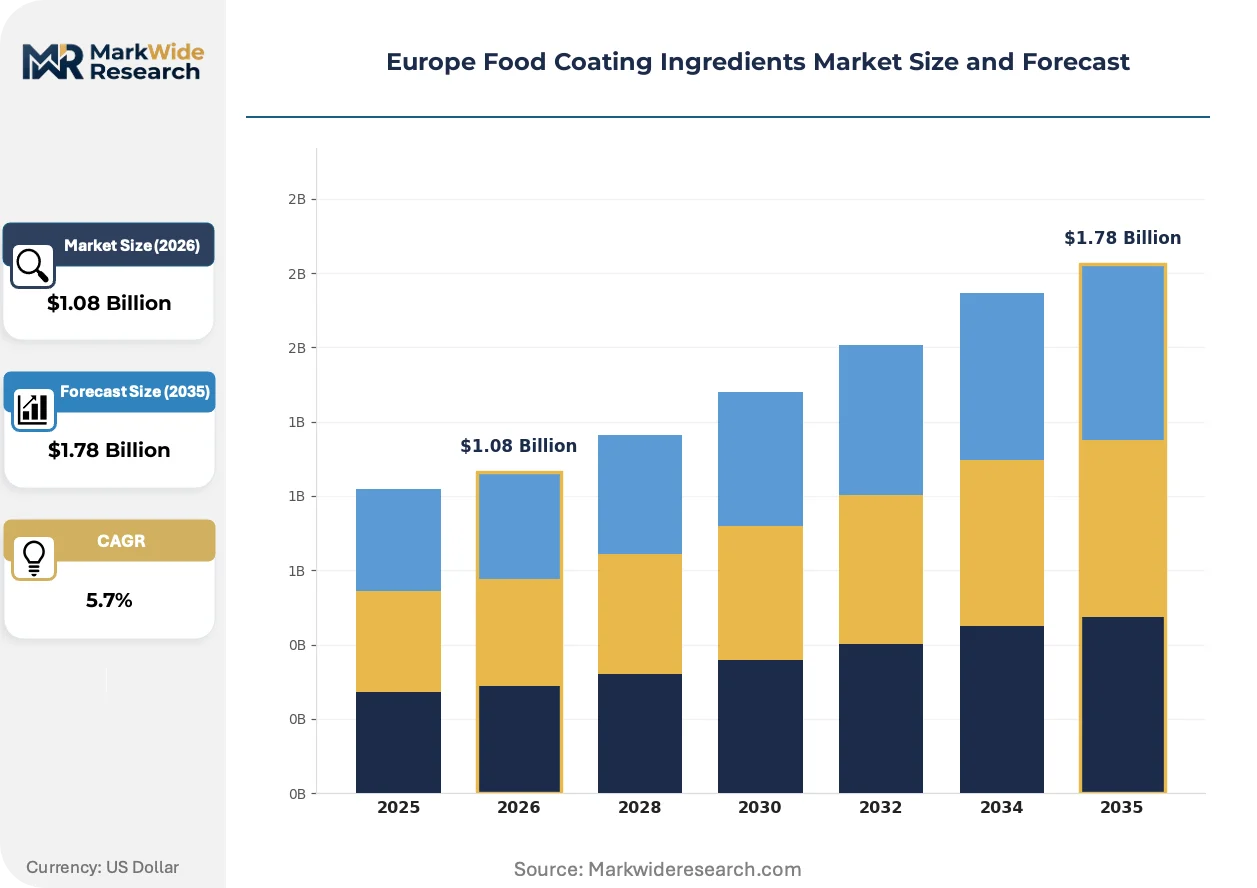
EFSA clean-label rulings are forcing frozen food processors across Germany and France to reformulate coating systems toward natural starches and modified flours, compressing legacy additive portfolios while opening specification windows for domestic wheat and potato derivatives.
Growth Catalysts
- EU Green Deal sourcing mandates:Traceable supply chain requirements favor domestically produced wheat and potato starches over imported alternatives, locking in regional millers and starch processors.
- Frozen prepared-meal manufacturing:Western European processors are replacing conventional breading with breadcrumb and batter systems that deliver yield and adhesion control on high-speed conveyor lines.
- Quick-service consolidation:Foodservice chains and contract caterers are standardizing procurement around pre-coated protein and vegetable platforms, concentrating volume with specialized ingredient suppliers.
Market Restraints
- REACH compliance costs:ECHA classifications on food-contact substances create friction in hydrocolloid selection, extending reformulation timelines and raising qualification expenses for coating developers.
- Wheat starch concentration:Supply dependence on Black Sea and North American grain corridors exposes formulators to input cost volatility and origin verification burdens under EU deforestation regulations.
- Modified starch technical ceilings:Natural starch alternatives face performance gaps in freeze-thaw stability and oil uptake control compared to chemically modified legacy systems.
Strategic Opportunities
- Polish and Romanian processing expansion:Underpenetrated Central European frozen food capacity offers first-mover positioning for coating ingredient suppliers ahead of EU structural fund investments.
- EU F-Gas Regulation tailwind:Hydrofluorocarbon phase-down alters cold-chain economics, favoring coated products with extended shelf stability that reduce refrigeration intensity in distribution.
- Inline viscosity adjustment systems:Liquid batter technologies are converging with Industry 4.0 process control, enabling real-time coating specification at processor sites without powder handling infrastructure.
Industry Challenges
- Food-contact substance certification timelines:ECHA restriction expansions require pre-positioning formulation pipelines 18-24 months ahead of anticipated rulings, compressing R&D cycle returns.
- Legacy fryer operator integration:Industrial coating transitions demand retrofitting adhesion and hydration protocols on established production lines without interrupting throughput commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Coating Ingredients Market |
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.78 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breadcrumbs, Batters, Flours, Starch Application: Snacks, Frozen Foods, Meat Products, Bakery Form: Powder, Liquid, Granular, Paste Distribution Channel: Online, Supermarkets, Wholesalers, Foodservice |
| Companies Covered | Cargill Incorporated, Tate & Lyle, Archer Daniels Midland Company, Kerry Group plc, Ingredion Incorporated, DSM Nutritional Products, Givaudan, Ashland Inc, Bowman Ingredients, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Coating Ingredients Market Shifts & Advancements
Digital formulation platforms and regulatory compliance automation are compressing development cycles for coating systems while clean-label mandates reshape ingredient hierarchies across European frozen food manufacturing.
Enzymatic starch modification is virtualizing the functional performance of chemically treated alternatives. German and Dutch ingredient developers are deploying these biocatalytic processes at commercial scale for batter viscosity control. The technology is virtualizing specification barriers that previously locked natural starches out of high-performance frying applications.
REACH authorization reviews are tightening hydrocolloid selections in coating recipes. ECHA's evolving classifications on food-contact substances extend qualification timelines and favor domestically traceable wheat and potato derivatives. Frozen food processors in France and Benelux are responding by consolidating supplier relationships around REACH-compliant starch portfolios with pre-submitted safety dossiers.
Buyer concentration among quick-service chains and contract caterers is consolidating procurement decisions at centralized technical specification levels. Pre-coated protein and vegetable platforms are displacing in-house breading operations across British and Irish foodservice distribution. This concentration is most visible in German QSR networks, where fryer operator contracts now bundle coating supply with oil management and equipment maintenance services.
Europe Food Coating Ingredients Market Segmentation
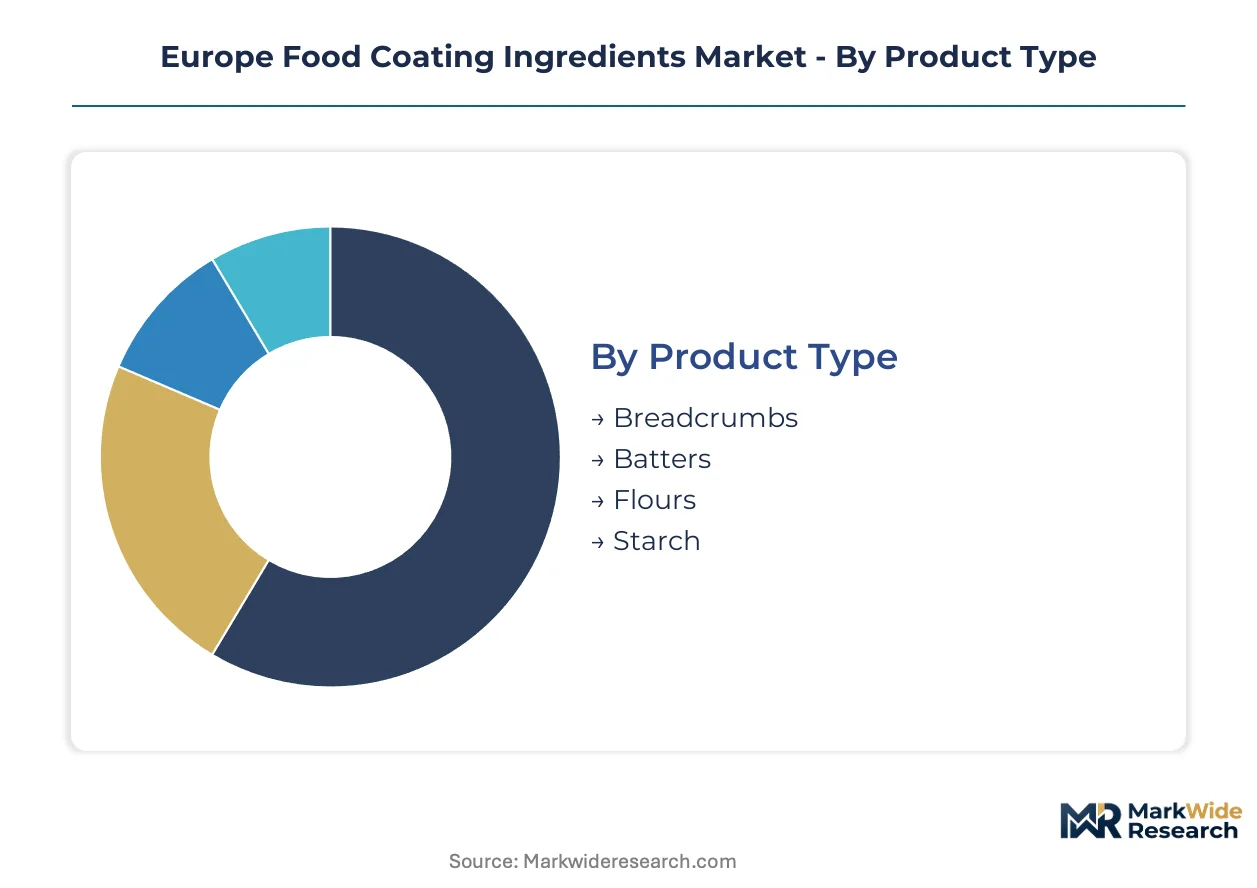
Coating ingredient specifications diverge sharply across frozen food, meat processing, and bakery applications, with viscosity control and adhesion performance driving procurement decisions. Technical service intensity varies by segment—liquid batters demand inline calibration support while powder systems require dust management protocols.
Product Type:
After-sales technical service intensity peaks with modified starch and batter systems, where processors require viscosity troubleshooting and fryer line integration support.
- Breadcrumbs:Crumb structures range from Japanese-style panko to fine grind, with porosity calibrated for oil uptake and crunch retention. German and French frozen food processors dominate procurement, driven by clean-label reformulation mandates from EFSA rulings.
- Batters:Hydrated suspensions operate at 1.5:1 to 3:1 water-to-dry ratios, with Brookfield viscosity specifications ensuring uniform pick-up on high-speed conveyor lines. Western European prepared-meal manufacturers are standardizing procurement around pre-mixed liquid systems that reduce dust exposure and enable real-time viscosity adjustment.
- Flours:Wheat and rice flour bases provide substrate adhesion and browning control across breading operations. Polish and Romanian processing expansion is opening specification windows for domestically milled alternatives.
- Starch:Native and modified potato and wheat derivatives manage moisture migration and freeze-thaw stability. REACH compliance timelines favor suppliers with pre-submitted ECHA safety dossiers.
Breadcrumbs hold the largest share; momentum sits with batters as quick-service chains consolidate procurement around pre-coated platforms.
Application:
Cost tier differentiation separates commodity snack coating from premium meat and frozen meal systems, with specification stringency climbing toward prepared-meal manufacturing.
- Snacks:High-volume breadcrumb and starch applications prioritize oil uptake control and extended crunch retention. German and Dutch snack processors are adopting enzymatically modified starches to meet clean-label targets without sacrificing fryer performance.
- Frozen Foods:Coated vegetables, fish, and poultry demand freeze-thaw stable adhesion systems that withstand distribution cold chains altered by EU F-Gas Regulation phase-downs. French and Benelux manufacturers lead specification development for extended shelf stability formats.
- Meat Products:Breading and batter adhesion on processed chicken, pork, and alternative proteins requires protein-binding hydrocolloids. British and Irish foodservice distribution is displacing in-house breading with pre-coated platforms.
- Bakery:Toppings and decorative coatings emphasize visual appeal and texture contrast rather than functional adhesion. Italian and Spanish artisan bakeries sustain niche demand for specialty crumb grades.
Frozen foods command the dominant volume position; bakery is expanding most quickly as clean-label decoration trends penetrate premium segments.
Form:
Volume economics favor powder formats for freight efficiency and ambient storage, while liquid systems capture margin through technical service bundling and inline process integration.
- Powder:Dry blends freight efficiently and store without refrigeration, dominating commodity snack and breadcrumb applications. Black Sea and North American wheat starch supply corridors expose formulators to origin verification burdens under EU deforestation regulations.
- Liquid:Pre-hydrated batters reduce dust exposure and enable real-time viscosity adjustment at processor sites. German QSR networks are bundling liquid coating supply with oil management and fryer maintenance services.
- Granular:Intermediate moisture formats bridge powder handling efficiency and liquid dispersion uniformity. Central European processors are piloting granular systems for mid-scale frozen vegetable operations.
- Paste:High-viscosity coatings deliver thick adhesion layers for specialty meat and alternative protein applications. Niche positioning limits penetration beyond premium British and Irish manufacturing.
Powder maintains volume leadership; liquid is gaining share fastest through foodservice channel consolidation and Industry 4.0 process control convergence.
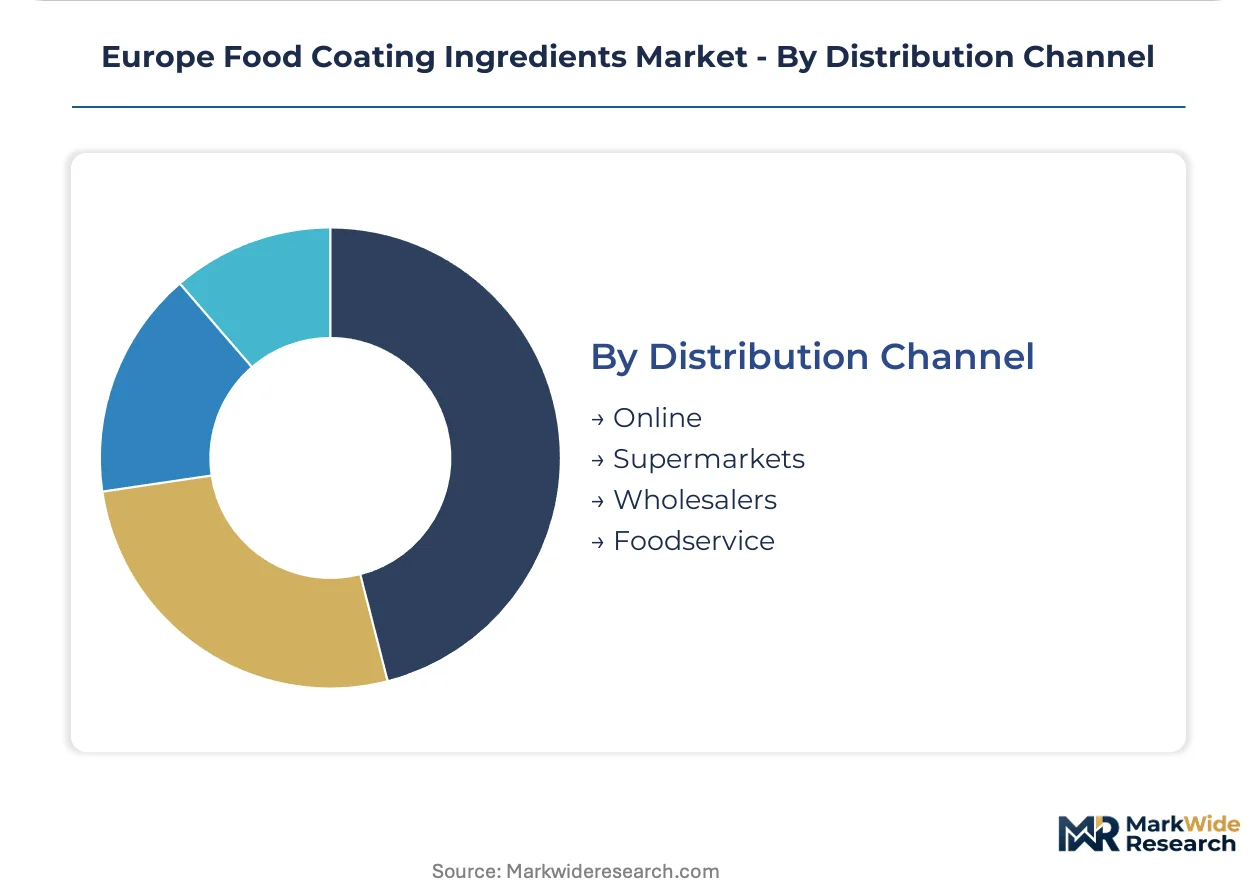
Distribution Channel:
Customer type fragmentation separates industrial processor direct procurement from fragmented foodservice and retail intermediation, with margin structure inversely correlating to channel concentration.
- Online:Digital platforms serve small-scale processors and specialty ingredient seekers with fragmented order patterns. Dutch and German ingredient marketplaces are aggregating REACH-compliant starch portfolios for mid-tier buyers.
- Supermarkets:Retail-packaged coatings for home cooking occupy peripheral shelf space, with limited penetration beyond breadcrumb commodities. French and British retail consolidation is compressing SKU counts.
- Wholesalers:Broadline distribution captures mid-scale frozen food and meat processors without direct supplier relationships. Polish and Romanian wholesale networks are expanding alongside regional processing capacity.
- Foodservice:Quick-service chains and contract caterers concentrate procurement decisions at centralized technical specification levels. Pre-coated protein and vegetable platforms are displacing in-house breading across British, Irish, and German foodservice distribution.
Foodservice holds the largest share; online is climbing the fastest as digital procurement platforms aggregate REACH-compliant supply for mid-tier processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German and French coating ingredient suppliers, who command specification premiums through REACH-compliant portfolios, while Polish and Romanian processors absorb cost advantages from expanding domestic starch milling capacity.
Germany
EFSA clean-label rulings are forcing frozen food processors in Baden-Württemberg and Bavaria to reformulate coating systems toward enzymatically modified starches. The EU Green Deal sourcing mandates favor traceable domestic wheat derivatives over Black Sea imports. Industrial fryer operators in the Stuttgart and Munich corridors are consolidating procurement around pre-coated protein platforms bundled with technical service contracts.
France
Prepared-meal manufacturers in Île-de-France and Hauts-de-France are displacing conventional breading with breadcrumb and batter systems engineered for yield control. ECHA restriction expansions on food-contact substances extend qualification timelines for hydrocolloid selections. The Benelux-adjacent processing belt around Lille anchors specification development for extended shelf-stability formats responding to EU F-Gas Regulation cold-chain economics.
United Kingdom
British and Irish foodservice distribution is shifting procurement toward pre-coated vegetable and protein platforms, displacing in-house breading operations. REACH compliance costs create friction for mid-tier processors sourcing modified starches. Greater London and the Midlands industrial zones concentrate demand for allergen-managed coating systems from specialized suppliers.
Poland
Underpenetrated frozen food processing capacity in the Łódź and Wrocław corridors offers first-mover positioning for coating ingredient suppliers. EU structural fund investments are expanding regional milling infrastructure for domestically traceable wheat starches. Wholesale distribution networks are scaling alongside manufacturing capacity to serve Central European processors.
Netherlands
Dutch ingredient developers near Rotterdam and Eindhoven are commercializing biocatalytic starch modification at scale for batter viscosity control. Digital procurement platforms aggregate REACH-compliant portfolios for mid-tier buyers across the Randstad. The port logistics cluster enables efficient freight distribution of powder coating systems to German and Belgian processors.
Europe Food Coating Ingredients Market Competitive Landscape
Integrated ingredient conglomerates and specialized coating system developers split the market along capability lines, with the former commanding supply-chain scale and the latter occupying defensible niches in allergen management and clean-label formulation. The vendor base organizes into three strategic archetypes: diversified agribusiness operators with captive starch supply, savory taste-and-texture specialists bundling coating with flavor systems, and regional specialists in gluten-free and allergen-managed formulations. Competitive moves center on backward integration into domestic starch milling and technology licensing for enzymatic modification processes.
Within the diversified agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through integrated oil and starch supply chains. Kerry Group plc anchors the savory taste-and-texture specialist archetype, bundling coating supply with fryer operator technical services. Bowman Ingredients occupies a position in the British and Irish manufacturing corridor as a regional specialist in allergen-managed systems.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tate & Lyle |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Ingredion Incorporated |
| DSM Nutritional Products |
| Givaudan |
| Ashland Inc |
| Bowman Ingredients |
| Others |
Supply & Pricing Matrix
Black Sea and North American wheat starch corridors anchor input cost structures for European coating formulators, concentrating margin pools with domestic millers in Germany and Poland who command origin-premiums under EU deforestation regulations. REACH compliance timelines and EFSA clean-label mandates amplify specification premiums for traceable supply chains, shifting procurement economics toward vertically integrated regional processors.
Pricing Analysis
Configured-to-order pricing for enzymatically modified starches commands spreads over standard native starch grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by REACH certification status and technical service bundling. Cost compression in commodity breadcrumb tiers intensifies because Black Sea supply volatility exposes buyers to origin verification burdens. Quick-service chains show lowest price sensitivity due to fryer-line integration dependencies, while mid-tier Polish processors absorb highest sensitivity from wholesale distribution exposure.
Supply Chain Analysis
Contract-manufacturing concentration sits with German and Dutch industrial fryer operators who bundle coating supply with equipment maintenance services. Geographic supply concentration centers on Germany, France, and Poland for wheat derivatives, with Benelux anchoring starch modification capacity. Raw material dependencies rest on Black Sea wheat, North American potato starch, and domestic enzymatic processing inputs. Single-source vulnerability runs through hydrocolloid selections facing ECHA restriction expansions. Distribution runs through foodservice channel consolidation and direct-procurement relationships with frozen meal manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH-compliant portfolios creates defensive moats for incumbent coating suppliers, as ECHA qualification timelines lock processors into pre-certified relationships. Switching costs escalate from fryer-line calibration protocols and inline viscosity system integration.
For Market Incumbents: Harden specification lock-in by deepening captive wheat starch milling in Poland and Romania ahead of EU structural fund deployment. Anchor fryer operator contracts with Industry 4.0 viscosity control integration that raises replacement costs. Threat of enzymatic modification commoditization demands accelerated biocatalytic patent positioning. Leverage EFSA pre-submission dossiers to compress competitor qualification windows. For New Entrants and Emerging Players: Pursue Central European frozen vegetable processors in Łódź and Wrocław corridors where incumbent technical service coverage remains thin. Target granular coating formats for mid-scale operations underserved by liquid batter infrastructure. Go-to-market angle centers on REACH-compliant starch portfolios aggregated through Dutch digital procurement platforms, bypassing direct ECHA submission burdens. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German savory taste specialists holding fryer operator maintenance contracts. Long-term viability hinges on enzymatic modification scale and regulatory dossier depth rather than commodity volume. Acquisition target archetype: regional allergen-managed coating developers in British and Irish corridors with pre-certified EFSA portfolios. Signal to watch is ECHA restriction expansion velocity on food-contact substances, which would accelerate consolidation around compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Starch Milling | Captures EU Green Deal traceability premiums and insulates against Black Sea supply volatility. |
| Enzymatic Modification Technology Licensing | Virtualizes clean-label performance barriers that previously locked natural starches out of high-specification frying. |
| Foodservice Channel Technical Service Bundling | Locks German QSR networks into integrated coating-oil-equipment contracts with elevated switching costs. |
| REACH-Compliant Portfolio Pre-Submission | Compresses competitor qualification timelines and anchors specification relationships with French and Benelux processors. |
| Central European Processing Capacity Expansion | Positions ahead of EU structural fund investments in Polish and Romanian frozen food manufacturing corridors. |
Research Methodology
Operator-level perspectives from coating formulators, industrial fryer operators, frozen food procurement directors, and EFSA regulatory consultants anchored the qualitative base. Primary interviews combined with secondary validation from ECHA restriction databases, EU Green Deal sourcing mandate filings, and customs trade data on wheat starch flows. Bottom-up segment modeling triangulated against top-down market sizing across product type, application, and form dimensions.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation modeled by coating system type, end-use manufacturing vertical, distribution channel concentration, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating frozen food capacity expansion trajectories and quick-service procurement consolidation patterns. Industry-specific inputs included EFSA clean-label ruling implementation timelines and EU F-Gas Regulation cold-chain economics.
Macroeconomic conditions sit as an overlay; deviation in wheat commodity volatility, energy costs for enzymatic processing, or ECHA restriction expansion velocity would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation cadence and processor adoption curves. Quarterly review of ECHA food-contact substance classifications and Black Sea supply corridor stability is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Bakery Stabilizers Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Lake Food Colors Market