
 United States Wheat Protein Market | 2026-2036
United States Wheat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Wheat Protein Market Analytics
Asset-light toll manufacturing and third-party leasing of spray-drying capacity is rewriting competitive entry dynamics in wheat protein processing. MGP Ingredients Inc. leverages its Kansas-based distillery infrastructure to co-locate protein recovery operations, sustaining cost advantages in isolate production. Cargill Incorporated anchors Midwest supply security through backward integration into regional grain origination networks. Archer Daniels Midland Company dominates rail-served processing hubs, controlling logistics corridors that shape delivered pricing to coastal food manufacturers.
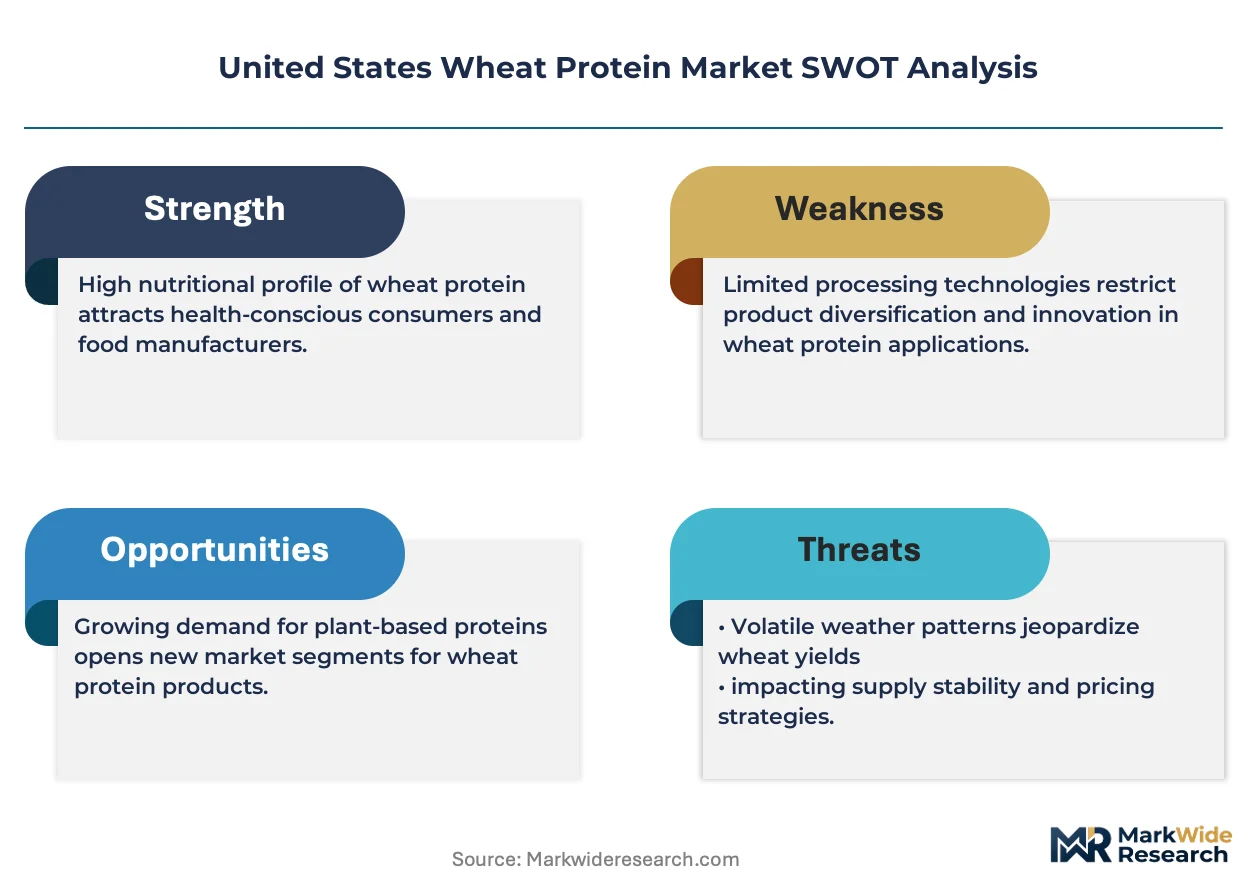
Wheat protein encompasses gluten fractions, albumins, globulins, and residual starches extracted via wet-processing or dry-milling of hard red winter and spring wheats, yielding functional ingredients with viscoelastic properties measured by extensograph and farinograph performance indices. These proteins bind moisture, provide structure, and replace animal-derived ingredients in formulated foods. The isolate and concentrate forms capture margin pools as food manufacturers demand higher protein purity for meat alternatives and sports nutrition applications, while textured wheat protein sustains volume leadership in commercial meat extenders and analog production. Hydrolyzed variants are accelerating in dietary supplements as peptide bioavailability claims attract functional food investment.
The FDA governs allergen labeling under FALCPA and protein content substantiation through its Food Labeling Guide, while the USDA Agricultural Marketing Service sets grade standards for wheat procurement that cascade into protein content premiums paid to growers. State-level food safety regulations in California and New York impose additional testing protocols for heavy metals and mycotoxins in plant proteins destined for infant and senior nutrition categories. Stakeholders must monitor how EPA biofuel mandates competing for starch streams reshape wet-mill coproduct economics and protein availability.
Market Dynamics
Plant-based meat formulators in California and Texas are displacing soy-dominant recipes with wheat protein isolates, tightening procurement specifications and rewiring supplier relationships across the Midwest grain belt.
Growth Catalysts
- FALCPA allergen labeling mandates:FDA disclosure requirements for wheat proteins in infant and senior nutrition categories are forcing manufacturers toward certified isolate grades with verified purity documentation.
- Hard red winter wheat milling clusters:Kansas and Nebraska gluten-rich feedstock concentration enables toll processors to achieve scale economies in isolate recovery without captive grain origination.
- Spray-drying capacity leasing:Asset-light third-party infrastructure is lowering capital barriers for new entrants seeking isolate production without distillery co-location.
Market Restraints
- EPA biofuel mandates:Starch stream competition from ethanol processors is compressing wet-mill coproduct economics and constraining protein isolate availability for food-grade applications.
- Midwest supply concentration:Kansas and Nebraska milling dominance creates origination risk from drought or disease pressure in the southern Plains hard red winter belt.
- Gluten functionality ceiling:Wheat protein's viscoelastic performance indices plateau below some animal-derived binders, limiting complete substitution in high-moisture meat analogs.
Strategic Opportunities
- Texas meat alternative manufacturing:Underpenetrated isolate supply relative to booming plant-based production in the Dallas-Fort Worth corridor creates white space for regional toll processing.
- Peptide bioavailability positioning:Hydrolyzed wheat protein variants targeting sports nutrition and dietary supplements command premium positioning through enzymatic hydrolysis technology.
- Rail-served coastal distribution:Direct unit-train logistics from Midwest processing hubs to California and Northeast food manufacturers bypasses intermediate warehousing and compresses delivered cost.
Industry Challenges
- Extensograph and farinograph technician scarcity:Specialized wheat protein functionality testing expertise is concentrated among aging millers, constraining quality control scale-up.
- Heavy metals and mycotoxin certification:California and New York state-level testing protocols for infant nutrition applications extend compliance timelines by four to six months.
- Legacy starch-protein separation equipment:Wet-mill retrofit requirements for isolate-grade purity demand capital outlays that conflict with ethanol-margin-driven maintenance deferrals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Wheat Protein Market |
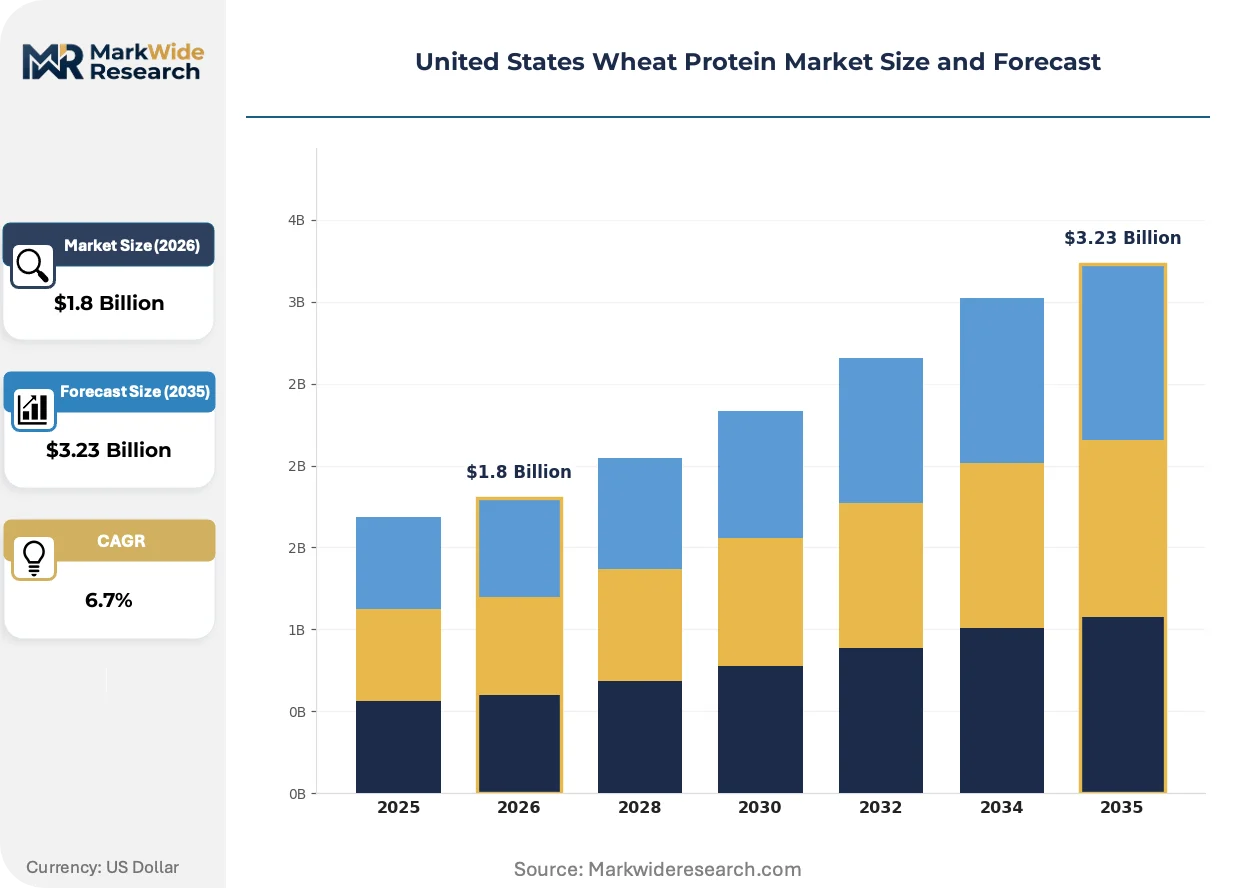
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Baking, Snacks, Confectionery, Meat Alternatives Form: Textured, Isolate, Concentrate, Hydrolyzed End User: Food Manufacturers, Dietary Supplements, Retail, Foodservice Distribution Channel: Online, Direct Sales, Retail Stores, Wholesale |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, MGP Ingredients Inc., Kerry Group PLC, Roquette Frères, Südzucker Group, The Scoular Company, Manildra Group, Tereos, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Wheat Protein Market Evolving Landscape
Digital process control and enzymatic modification technologies are compressing batch-to-batch variability in protein isolate production while regulatory scrutiny of allergen cross-contact intensifies documentation requirements.
Near-infrared spectroscopy coupled with machine learning algorithms is digitizing real-time protein content prediction during wheat receival and conditioning. Kansas toll processors are adopting these systems to reduce laboratory testing bottlenecks and accelerate batch release. This digitizing of quality assurance is compressing working capital cycles and enabling just-in-time isolate delivery to California meat alternative manufacturers.
FDA's tightening interpretation of FALCPA "contains wheat" disclosure thresholds is forcing reformulation of multi-protein blends and triggering investment in dedicated wheat-free production lines. The agency's draft guidance on protein content claims is requiring nitrogen conversion factor adjustments that disadvantage some legacy suppliers. Infant nutrition processors in New York are responding with third-party allergen validation protocols that exceed federal minimums.
Formulators are consolidating supplier relationships around single-source isolate contracts with guaranteed farinograph stability specifications, displacing spot purchasing of commodity gluten. This specification-driven procurement compression is favoring toll processors with captive laboratory capabilities and certified food safety management systems. The shift is most visible in Texas, where meat alternative startups are bypassing traditional distributors for direct mill relationships.
United States Wheat Protein Market Segmentation
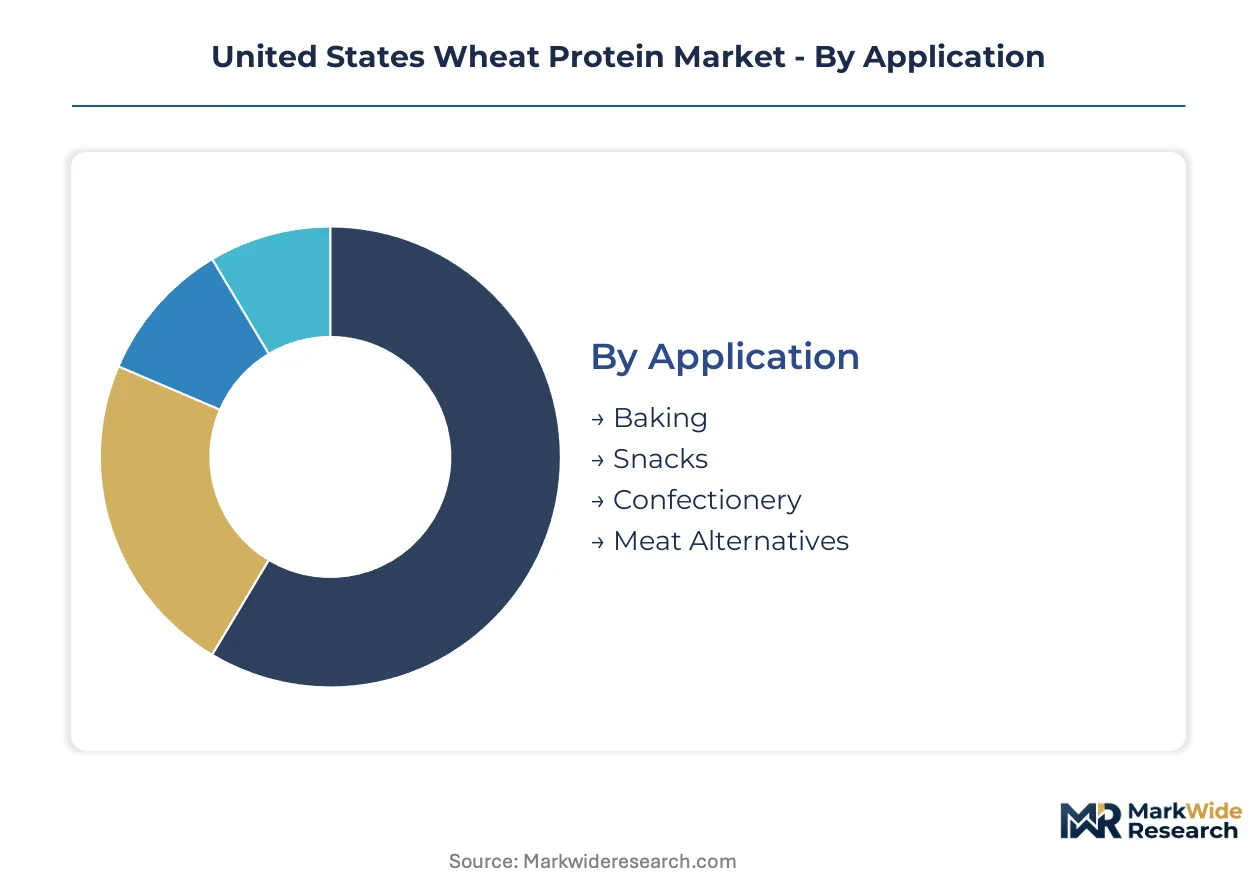
Wheat protein procurement patterns diverge sharply across application and form dimensions, with meat alternative manufacturers demanding certified isolates on compressed lead times while baking customers accept longer-cycle commodity gluten contracts.
Application:
Cycle times compress most dramatically in meat alternatives, where California and Texas formulators rotate suppliers quarterly, versus baking's annual contracting rhythm.
- Meat Alternatives:High-purity isolates with verified farinograph stability specifications displace soy-dominant formulations. Dallas-Fort Worth and Los Angeles manufacturers enforce 30-day payment terms and third-party allergen validation. Demand concentrates in isolates exceeding 90% protein content.
- Baking:Vital wheat gluten provides viscoelastic structure in artisan and commercial bread production. Kansas and Nebraska millers supply volume contracts to Midwest commercial bakeries with 12-18 month pricing locks.
- Snacks:Textured proteins extend meat in extruded products.
- Confectionery:Limited use in aerated confections and gelling applications.
Baking anchors the volume base while meat alternatives gains share at the steepest rate.
Form:
Cost tiers separate sharply, with hydrolyzed variants commanding enzymatic processing premiums above standard isolates.
- Isolate:Protein fractions exceeding 90% purity recovered via wet-processing of hard red winter wheat. California meat alternative manufacturers and New York infant nutrition processors drive specification tightening around heavy metals certification.
- Hydrolyzed:Enzymatically cleaved peptides with enhanced bioavailability claims. Sports nutrition brands in Texas and dietary supplement manufacturers prioritize these variants for rapid absorption positioning.
- Textured:Extruded fibers for meat extension and analog structuring.
- Concentrate:Intermediate purity grades for cost-sensitive baking applications.
Textured forms sustain the highest shipment volumes while hydrolyzed climbs the fastest on peptide bioavailability positioning.
End User:
Customer sophistication determines margin capture, with dietary supplements accepting lot premiums for certified peptide content.
- Food Manufacturers:Large-scale baking and meat alternative producers negotiate toll-processing contracts directly with Kansas and Nebraska mill clusters.
- Dietary Supplements:Sports nutrition and wellness brands source hydrolyzed isolates with enzymatic verification documentation.
- Foodservice:Regional distributors supply textured proteins to commercial kitchens.
- Retail:Packaged vital wheat gluten for home baking represents minimal value capture.
Food manufacturers dominate procurement volume while dietary supplements expands most quickly on premium peptide demand.
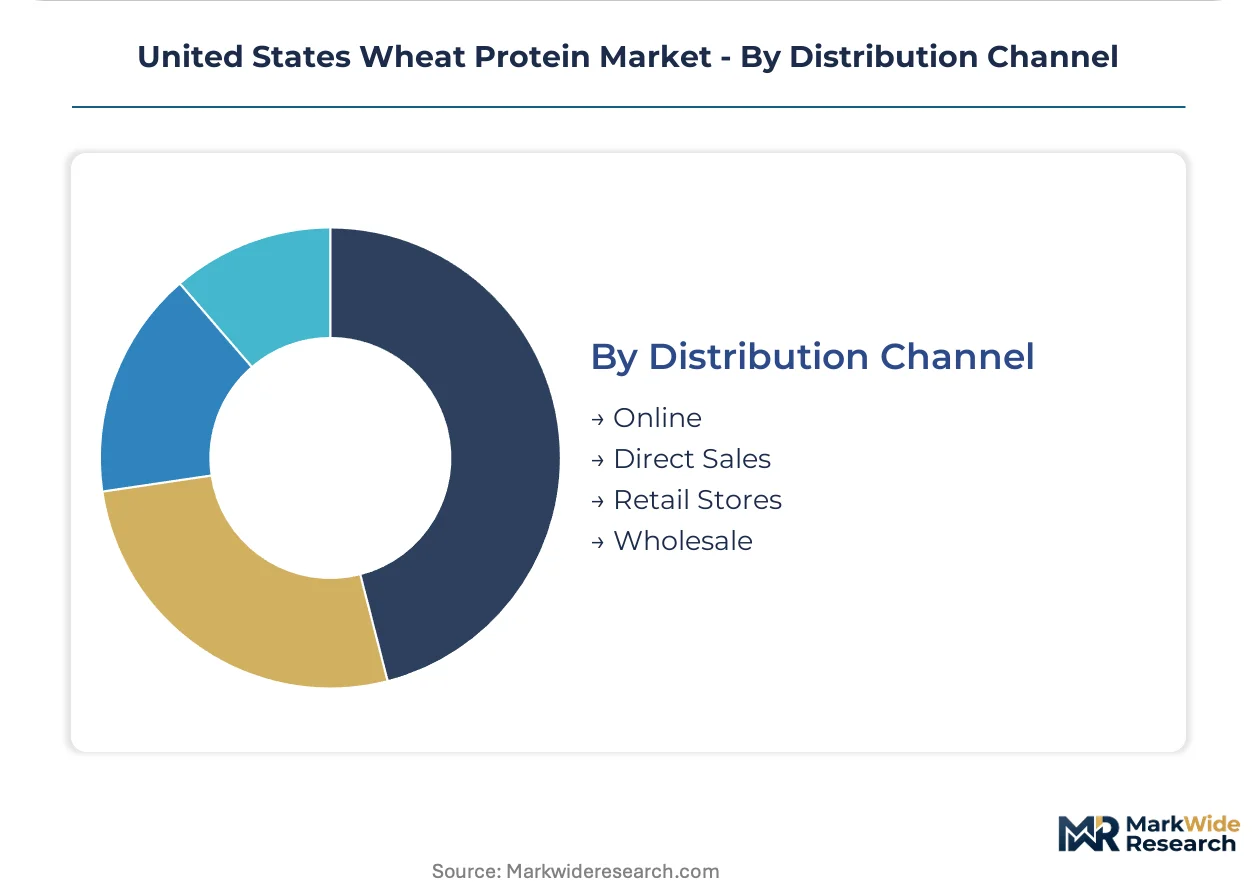
Distribution Channel:
Supply concentration dictates channel efficiency, with direct rail shipments bypassing intermediate handling for coastal manufacturers.
- Direct Sales:Unit-train logistics from Midwest processing hubs to California and Northeast food manufacturers compress delivered costs and enable just-in-time isolate delivery.
- Wholesale:Regional distributors aggregate textured protein volumes for Texas meat alternative startups and Midwest commercial bakeries.
- Online:Small-lot isolate and concentrate sales to specialty food manufacturers.
- Retail Stores:Consumer-packaged vital wheat gluten through grocery channels.
Direct sales carries the heaviest tonnage while online demonstrates the steepest expansion trajectory on small-batch procurement flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling mandates and USDA procurement standards are redistributing wheat protein demand across state-level manufacturing clusters, with coastal formulators tightening specifications faster than Midwest supply infrastructure can adapt.
California
Meat alternative manufacturers in Los Angeles and Oakland enforce 90-day isolate certification cycles for heavy metals compliance. California's Proposition 65 warning requirements for chemical exposures extend to wheat protein imports, forcing third-party laboratory validation. The Central Valley food tech corridor hosts precision fermentation startups that blend wheat isolates with novel protein sources.
Texas
Dallas-Fort Worth plant-based meat production is scaling faster than regional isolate supply, creating procurement bottlenecks for toll processors. The Texas Department of State Health Services imposes additional mycotoxin screening beyond federal minimums for infant nutrition applications. Houston petrochemical infrastructure supports hydrolyzed peptide production for sports nutrition brands.
Kansas
Hard red winter wheat milling clusters around Wichita supply gluten-rich feedstocks to toll processors achieving scale economies without captive grain origination. Kansas Department of Agriculture grading standards cascade into protein premiums paid to growers. The state's distillery infrastructure enables MGP Ingredients to co-locate protein recovery with ethanol production.
Nebraska
Omaha-based grain handlers anchor backward integration into regional origination networks, securing supply security for isolate processors. Nebraska Department of Agriculture enforces identity preservation protocols for certified wheat varieties. The Platte River valley concentration of rail-served elevators enables unit-train logistics to California manufacturers.
New York
Infant nutrition processors in the Hudson Valley demand four-to-six-month compliance timelines for allergen validation exceeding federal FALCPA thresholds. New York State Department of Agriculture and Markets mandates additional testing protocols for plant proteins in senior nutrition categories. Brooklyn-based food tech accelerators are piloting enzymatic modification technologies for peptide bioavailability enhancement.
United States Wheat Protein Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: grain-originating multinationals with captive milling infrastructure, toll processors leasing third-party spray-drying capacity, and specialized isolate refiners targeting premium nutrition segments. Competitive moves center on backward integration into Kansas and Nebraska grain origination networks, and direct rail-served logistics contracts that bypass intermediate warehousing for coastal manufacturers.
Among the named processors, Archer Daniels Midland Company and Cargill Incorporated represent the grain-originating multinational archetype with Midwest infrastructure dominance, while MGP Ingredients Inc. exemplifies the distillery-co-location model for isolate recovery. Kerry Group PLC and Roquette Frères occupy positions within the specialized nutrition ingredients tier, with Roquette Frères representing European-based capabilities adapted to US regulatory requirements.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| MGP Ingredients Inc. |
| Kerry Group PLC |
| Roquette Frères |
| Südzucker Group |
| The Scoular Company |
| Manildra Group |
| Tereos |
| Others |
Value Network & Pricing Analysis
Kansas and Nebraska hard red winter wheat milling clusters concentrate upstream supply, anchoring margin capture downstream at California and Texas meat alternative manufacturers who pay premiums for certified isolate grades with verified farinograph stability.
Pricing Analysis
Certification level creates the primary spread between commodity vital wheat gluten and food-grade isolates, with FDA allergen documentation and heavy metals validation driving three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on farinograph performance indices and enzymatic hydrolysis depth, with sports nutrition brands least sensitive and Midwest commercial bakeries most cost-conscious. Pricing pressure stems from EPA biofuel mandates competing for starch streams, compressing wet-mill coproduct economics and tightening isolate availability.
Supply Chain Analysis
Toll processors including MGP Ingredients and Archer Daniels Midland hold captive spray-drying and distillery-co-location capacity across Kansas and Nebraska. Geographic supply concentration in the southern Plains hard red winter belt draws from regional grain origination networks, with wet-processing equipment and enzymatic modification technology as critical component dependencies. Single-source vulnerability runs through drought-exposed Plains wheat belts. Distribution runs through rail-served unit-train logistics bypassing intermediate warehousing for coastal manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward meat alternative manufacturers in California and Texas as these formulators consolidate supplier relationships around single-source isolate contracts with guaranteed specifications, fragmenting procurement options for legacy gluten suppliers.
For Market Incumbents: Pre-empt toll processor encroachment by securing backward integration into Nebraska and Kansas grain origination networks before asset-light competitors lease third-party spray-drying capacity. Invest in enzymatic hydrolysis capabilities to capture sports nutrition premium pools. Defend against FDA nitrogen conversion factor adjustments by accelerating certified laboratory accreditation. For New Entrants and Emerging Players: Build out regional toll processing capacity in the Dallas-Fort Worth corridor where underpenetrated isolate supply faces booming plant-based meat production demand. Target hydrolyzed peptide segments for dietary supplements with enzymatic verification documentation as the most penetrable white space. Establish direct mill relationships bypassing traditional distributors to secure volume commitments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed toll processors holding leased spray-drying infrastructure without captive grain origination. Long-term viability favors processors with laboratory capabilities and rail-served logistics contracts across the analysis window. Watch EPA biofuel mandate adjustments as the inflection signal for wet-mill coproduct economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Secures supply security for Kansas and Nebraska isolate processors against drought risk. |
| Enzymatic Hydrolysis Capacity Addition | Captures premium positioning in Texas sports nutrition peptide markets. |
| Rail-Served Logistics Partnership | Compresses delivered cost to California meat alternative manufacturers via unit-train contracts. |
| Certified Laboratory Accreditation | Accelerates batch release for FDA allergen documentation requirements. |
| Toll Processing Joint Venture | Shares spray-drying capital burden for asset-light entrants in underpenetrated regions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA Agricultural Marketing Service grade standards, FDA Food Labeling Guide documentation, and EPA biofuel mandate filings. Primary interviews engaged wheat protein procurement managers at meat alternative manufacturers, quality control directors at Kansas toll processors, grain origination specialists at Nebraska elevators, and regulatory affairs leads at infant nutrition processors. Secondary validation drew from SEC 10-K disclosures of listed ingredient processors, FERC rail tariff filings, and state-level agriculture department enforcement records. Bottom-up volume modeling triangulated against top-down value estimates.
Forecast inputs include hard red winter wheat protein content premiums, spray-drying capacity utilization rates, and rail logistics cost indices across the analysis window. Segmentation dimensions modeled encompass application type, protein form, end-user sophistication, and distribution channel structure. CAGRs derived from historical procurement pattern analysis and projected capacity expansion timelines. Industry-specific inputs incorporate FALCPA enforcement trajectory and enzymatic modification technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by grain-originating multinationals would shift outcomes beyond projected ranges. Quarterly review of EPA renewable fuel standard adjustments and Plains drought severity indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
North America Prebiotic Ingredients Market
Ingredients
Peanut Flour Market
Ingredients
Global Amaranth Oil Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Oat Ingredients Market
Ingredients
Asparagus Extract Market
Ingredients
Aroma Ingredients Market
Ingredients
Marine Ingredients Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Bouillon Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
France Protein Market