
 United States Quick Service Restaurants Market | 2026-2036
United States Quick Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
United States Quick Service Restaurants Market Insights
Young professionals is rotating toward digital-first ordering channels, displacing traditional counter-service patterns among suburban families. McDonald's sustains manufacturing scale through its consolidated supply network and automated kitchen systems. Chick-fil-A dominates drive-thru throughput with dual-lane architecture and predictive staffing algorithms. Chipotle differentiates through vertical ingredient sourcing and in-house preparation protocols that reduce third-party dependency.
Quick service restaurants are commercial foodservice establishments characterized by limited menus, standardized preparation methods, and service times under three minutes, operating through high-volume production lines with frozen-to-finished temperature controls. Their primary purpose is delivering consistent, low-cost meals via speed-optimized workflows designed for repeat transactions and operational replication. Drive-thru service generates the highest margin contribution due to labor efficiency and ticket-size optimization, while mobile ordering represents the fastest-expanding channel as integration with loyalty programs deepens purchase frequency. Burgers remain the largest product category by volume, though salads capture premium pricing power among health-positioned customer segments.
FDA menu labeling enforcement and municipal single-use packaging bans in California and New York are elevating compliance costs while accelerating packaging innovation investments. The USDA's bioengineered food disclosure standard and state-level wage regulations across Illinois and Massachusetts further complicate national operating models. Stakeholders must monitor friction between federal preemption efforts and proliferating local ordinances that fragment standardization strategies.
Market Dynamics
Off-premise consumption through mobile ordering platforms is restructuring unit economics and real estate footprints across the United States quick service restaurants market. Labor deployment models, kitchen workflows, and parking lot configurations are all being recalibrated to serve digital-native customers who rarely interact with physical counters.
Growth Catalysts
- Drive-thru optimization:Dual-lane architecture and predictive staffing algorithms are compressing service times below three minutes. Texas and Florida urban corridors are seeing the densest deployment of these high-throughput formats.
- FDA menu labeling enforcement:The updated rules are standardizing nutritional transparency requirements nationwide. Chains with existing compliance infrastructure are capturing market access advantages over smaller competitors facing retrofit costs.
- Young professional demand:Digital-first ordering channels are displacing traditional counter-service patterns among suburban families. Mobile app integration with loyalty programs is deepening purchase frequency in Sun Belt metropolitan areas.
Market Restraints
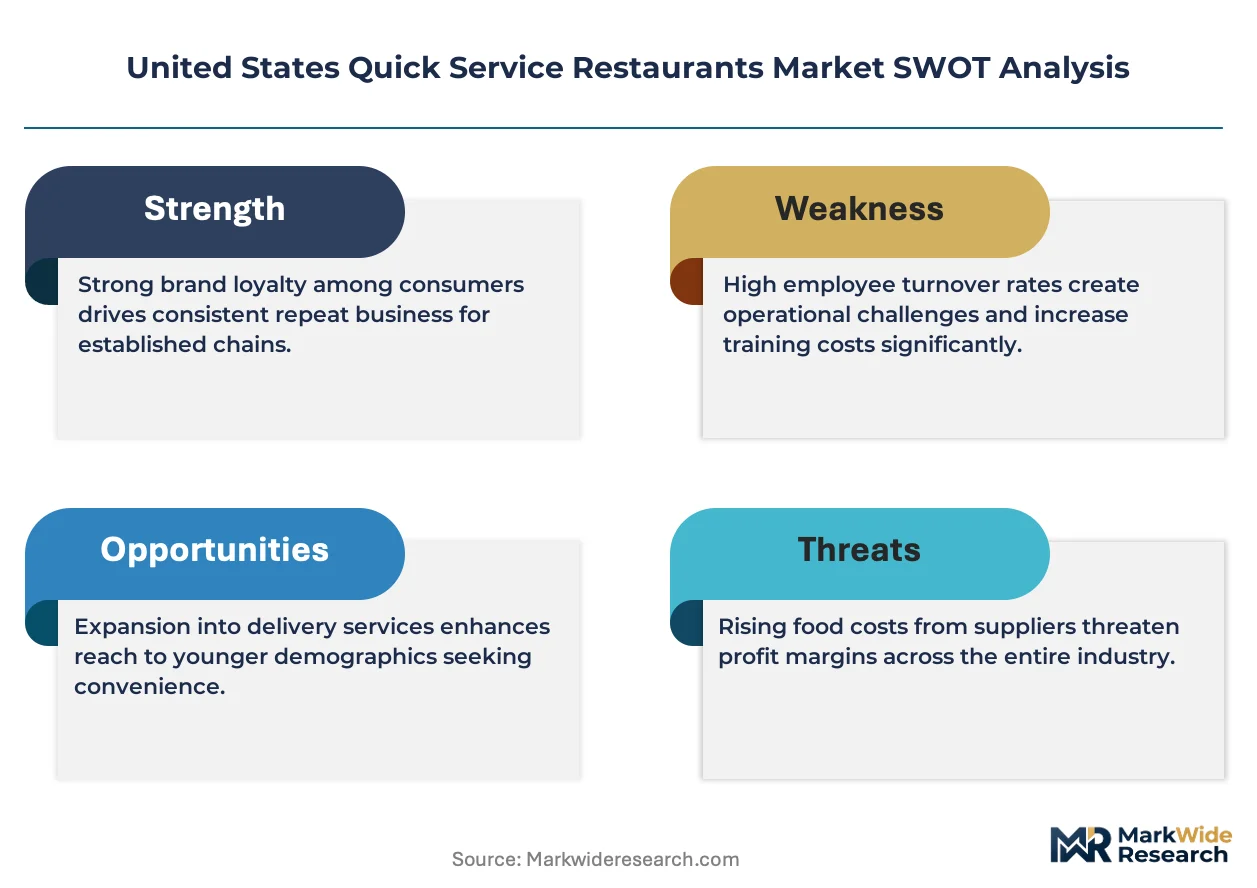
- Protein input volatility:Beef and poultry price swings compress margin predictability. Chains without backward integration into protein processing face quarterly P&L instability.
- Packaging compliance fragmentation:Municipal single-use packaging bans in California and New York are elevating compliance costs. National operators must maintain multiple packaging SKUs rather than standardized formats.
- Labor cost divergence:State-level wage regulations across Illinois and Massachusetts create operational asymmetries. Uniform pricing strategies become untenable when labor costs vary by twenty percent or more across state lines.
Strategic Opportunities
- Central kitchen consolidation:Off-premise volume growth justifies dedicated production facilities separate from retail footprints. Real estate arbitrage between industrial zones and high-rent retail corridors improves unit economics.
- USDA bioengineered food disclosure standard:Early compliance with labeling requirements creates positioning space around ingredient transparency. Chains with clean-label supply chains can capture premium positioning before mandates tighten.
- Voice-ordering integration:Convergence of natural language processing with drive-thru audio systems is reducing order error rates. Early adopters are seeing ticket size increases through automated upsell prompts.
Industry Challenges
- Kitchen automation capex cycles:Robotic assembly and automated frying systems require eighteen-to-twenty-four-month payback validation. Franchisee resistance to corporate-mandated equipment upgrades slows rollout timelines.
- Third-party delivery margin erosion:Commission structures from aggregator platforms consume fifteen-to-thirty percent of order value. Chains must rebuild direct digital channels or accept permanent profitability compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Quick Service Restaurants Market |
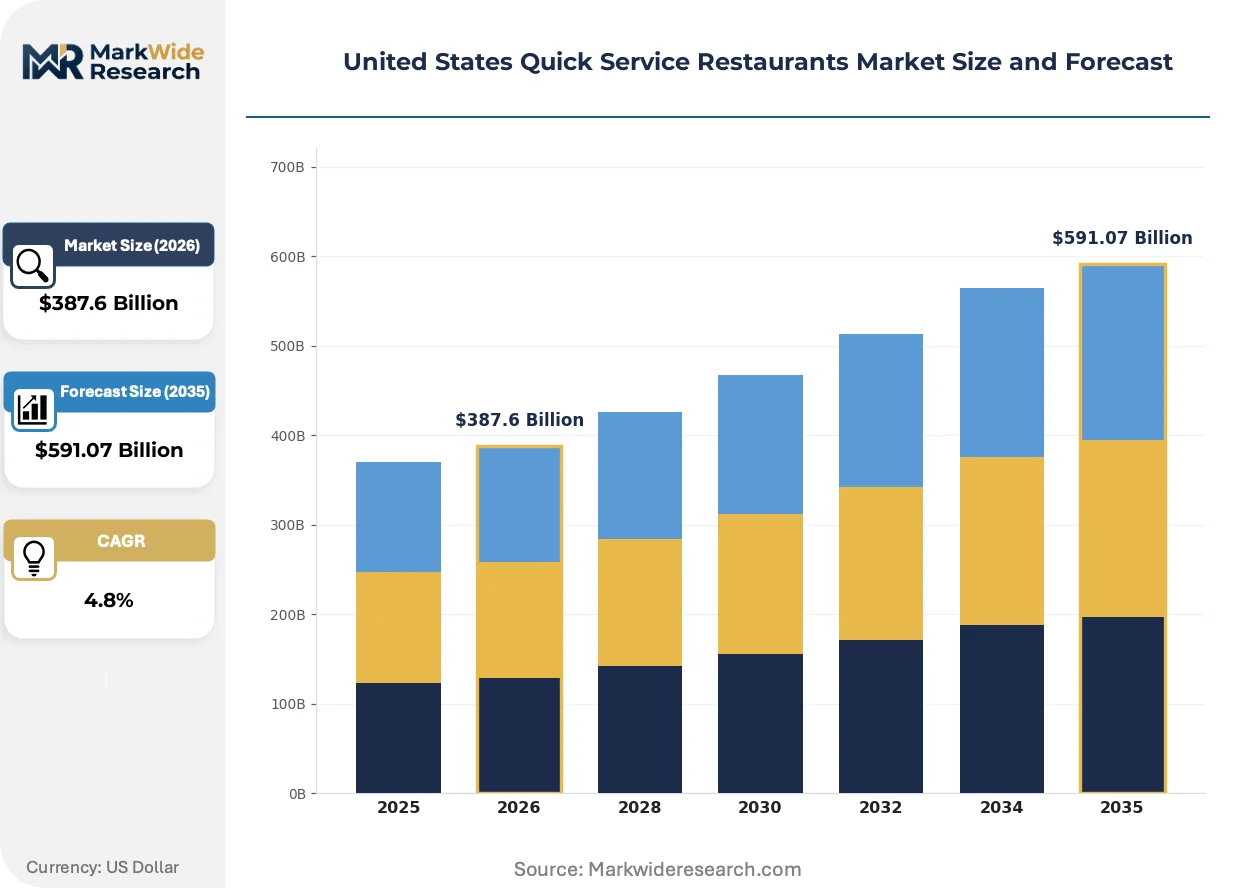
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-in, Drive-thru, Takeaway, Delivery Product Type: Burgers, Sandwiches, Salads, Desserts Customer Type: Families, Students, Professionals, Tourists Technology: Mobile Ordering, Self-Service Kiosks, Contactless Payment, Digital Loyalty Programs |
| Companies Covered | Taco Bell, Dunkin', McDonald's, Burger King, Chipotle, Starbucks, Wendy's, Subway, Chick-fil-A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Quick Service Restaurants Market Trends and Innovations
Operational technology investments are converging with regulatory compliance requirements to reshape capital allocation priorities across the United States quick service restaurants market. Chains are being forced to simultaneous modernization of customer-facing digital infrastructure and back-of-house production systems.
Automated kitchen equipment is displacing manual preparation steps in high-volume protein and fry stations. Chains with over five hundred units are deploying robotic patty flippers and automated basket systems at pace. This technology is displacing traditional line-cook staffing models while compressing throughput variance during peak hours.
The FDA's updated menu labeling rules are mandating calorie and nutritional disclosure across all menu boards and digital ordering platforms. Chains must retrofit point-of-sale systems and third-party delivery integrations to maintain compliance. Health-positioned customer segments in California and Massachusetts are already using this data to filter restaurant selection.
Young professionals are rotating consumption patterns toward subscription-based meal programs and bundled ordering platforms. Traditional impulse-driven counter visits are being replaced by scheduled pickup windows and subscription loyalty tiers. This behavioral shift is most visible in Austin, Denver, and Nashville metropolitan corridors where digital-native demographics concentrate.
United States Quick Service Restaurants Market Segmentation
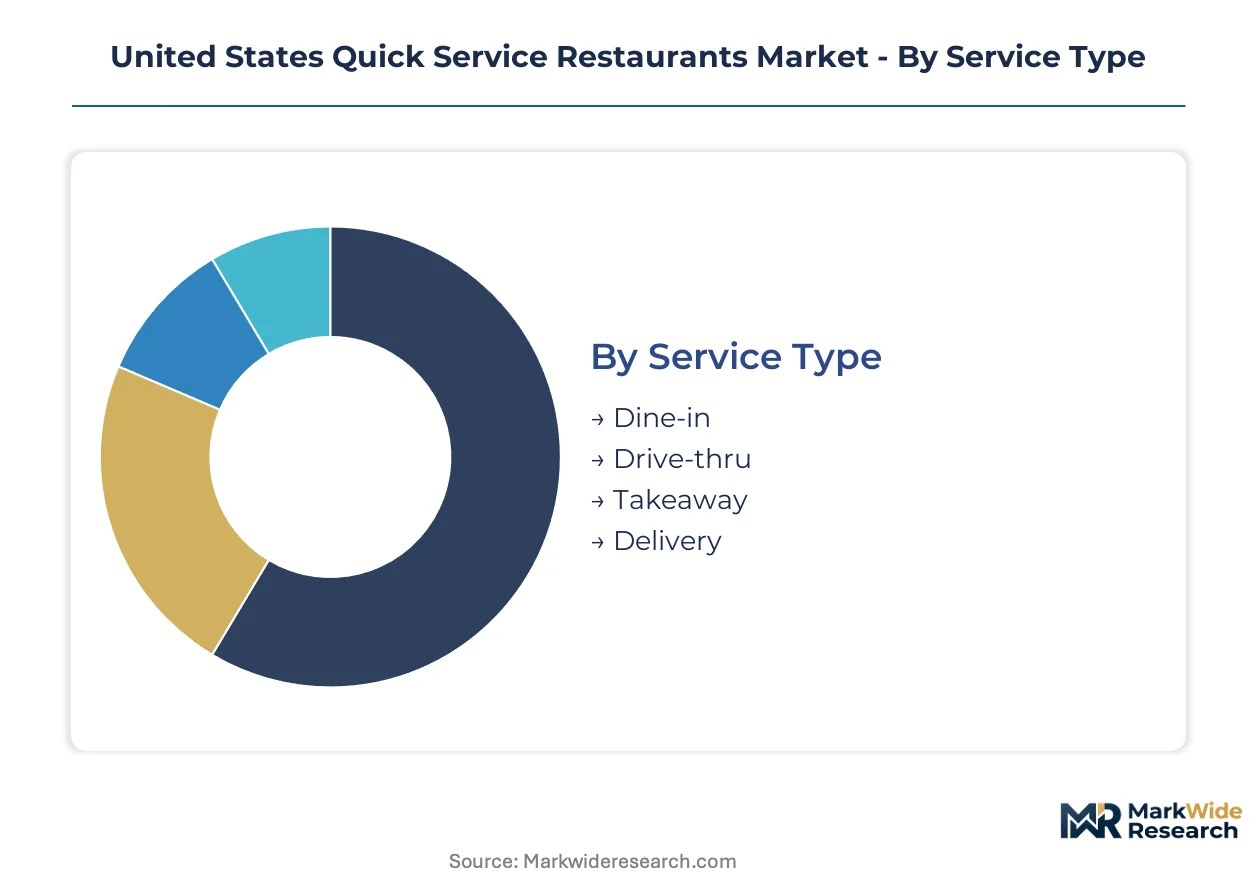
Service format and product mix determine margin capture in the United States quick service restaurants market. Technology deployment and customer targeting separate operators achieving unit economics scale from those trapped in commodity competition.
Service Type:
Margin pools concentrate in formats minimizing labor interaction while maximizing throughput velocity.
- Drive-thru:Dual-lane configurations with predictive staffing algorithms compress service times below three minutes. Texas and Florida urban corridors deploy these formats most densely, capturing suburban commuter traffic with optimized ticket sizes.
- Delivery:Third-party aggregator integration expands reach but compresses profitability through fifteen-to-thirty percent commission structures. Chains rebuilding direct digital channels are recovering margin lost to platform dependency.
- Takeaway:Mobile order-ahead with dedicated pickup shelves reduces customer dwell time and parking friction.
- Dine-in:Footprint reduction continues as operators reallocate square footage to kitchen production and pickup staging.
The dominant share belongs to Drive-thru, while Delivery is closing the gap fastest.
Product Type:
Volume concentration versus pricing power splits strategic positioning across menu categories.
- Burgers:Standardized patty production with frozen-to-finished temperature controls enables replication at scale. Sun Belt metropolitan areas sustain highest per-capita consumption through value-menu penetration.
- Salads:Vertical ingredient sourcing and in-house preparation protocols support premium positioning. Health-conscious customer segments in California and Massachusetts filter selections using FDA-mandated nutritional disclosure data.
- Sandwiches:Protein input volatility creates quarterly margin instability for operators lacking backward integration into processing.
- Desserts:Limited-time offerings drive impulse attachment with minimal kitchen complexity.
Burgers maintains volume leadership, though Salads commands the steepest expansion trajectory among health-positioned segments.
Customer Type:
Digital-native demographics are displacing traditional family-oriented traffic patterns.
- Professionals:Subscription-based meal programs and bundled ordering platforms replace impulse counter visits. Austin, Denver, and Nashville corridors show highest concentration of scheduled pickup behavior.
- Families:Value bundling and play-area amenities retain relevance in suburban markets with lower mobile ordering penetration.
- Students:Price sensitivity drives loyalty toward value-menu tiers and promotional app exclusives.
- Tourists:Location-based discovery through mapping platforms influences capture rates near transportation hubs and entertainment districts.
Professionals now generates the highest purchase frequency, while Families retains the largest absolute transaction base.
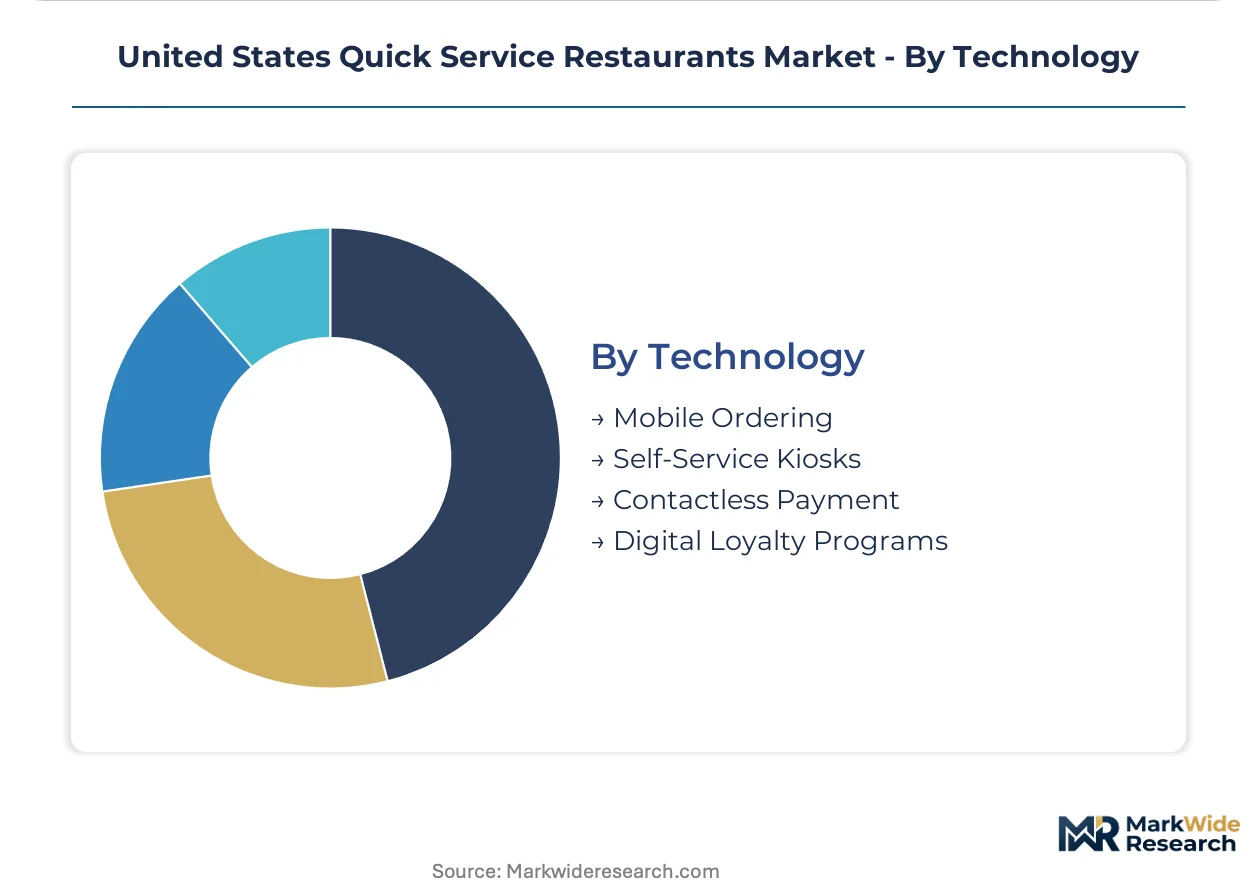
Technology:
Capital allocation prioritizes customer-facing digital infrastructure alongside back-of-house automation.
- Mobile Ordering:Integration with loyalty programs deepens repeat purchase behavior. Young professionals in Sun Belt metros demonstrate highest adoption velocity.
- Self-Service Kiosks:Order accuracy improvements and upsell automation justify retrofit investments in high-traffic locations.
- Contactless Payment:Tap-to-pay infrastructure reduces transaction friction and cash handling costs.
- Digital Loyalty Programs:Data capture enables personalized promotion targeting with measurable redemption rates.
Mobile Ordering leads deployment spending, while Self-Service Kiosks is gaining share fastest in legacy location renovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Unit deployment concentrates in Sun Belt metropolitan corridors where population growth and commuter density sustain drive-thru economics. Texas and Florida urban markets anchor national expansion velocity. State-level regulatory fragmentation complicates standardized operating models.
Texas
Houston and Dallas-Fort Worth corridors generate the densest drive-thru deployment through suburban commuter traffic. Municipal zoning in Austin favors quick-service pad sites near highway interchanges. San Antonio operators leverage dual-lane architecture to compress service times below three minutes during peak morning intervals.
Florida
Miami-Dade and Orlando metropolitan areas sustain off-premise volume growth through tourism and residential density. State-level preemption of local wage ordinances creates labor cost advantages over California and New York counterparts. Tampa Bay operators are retrofitting locations with dedicated mobile order pickup infrastructure.
California
Los Angeles and San Francisco Bay Area markets face the steepest packaging compliance costs from municipal single-use bans. Cal/OSHA workplace safety mandates elevate training overhead above national averages. Sacramento operators pilot central kitchen consolidation to escape high-rent retail corridors.
New York
New York City density supports delivery-centric formats despite third-party commission erosion. State wage regulations and predictive scheduling laws compress margin flexibility upstate. Buffalo and Rochester operators emphasize value-menu penetration to offset labor cost premiums.
Illinois
Chicago metropolitan traffic patterns favor drive-thru optimization along expressway commercial strips. State-level minimum wage escalation creates asymmetric cost structures versus Indiana and Wisconsin neighbors. Springfield and Peoria operators test voice-ordering integration to reduce labor interaction at the point of sale.
United States Quick Service Restaurants Market Competitive Landscape
Concentration sits with national chains possessing consolidated supply networks and automated kitchen systems. The market structure shows tiered consolidation: a handful of operators control manufacturing scale, while regional players compete on localized menu adaptation. Strategic archetypes include scale-driven integrators, premium-positioned specialists, and value-focused franchise aggregators. Dominant competitive moves center on backward integration into protein processing and technology licensing for predictive staffing algorithms.
Among scale-driven integrators, McDonald's and Chick-fil-A exemplify the manufacturing-efficiency archetype through consolidated procurement and throughput optimization. Chipotle occupies a position within the premium-positioned specialist tier, differentiating through vertical ingredient sourcing that reduces third-party dependency. These operators anchor competitive intensity in the drive-thru and mobile ordering vectors where capital deployment determines market access.
| Leading Market Players |
|---|
| Taco Bell |
| Dunkin' |
| McDonald's |
| Burger King |
| Chipotle |
| Starbucks |
| Wendy's |
| Subway |
| Chick-fil-A |
| Others |
Pricing and Supply Chain Analysis
FDA menu labeling enforcement gates both supplier qualification and price differentiation simultaneously, as chains must retrofit point-of-sale infrastructure to maintain compliance while health-positioned competitors capture premium positioning through transparent nutritional disclosure.
Pricing Analysis
FDA menu labeling rules dictate the pricing tier structure across the United States quick service restaurants market. Three-tier pricing structure across premium, standard, and economy levels separates health-positioned salad specialists from value-menu burger chains and commodity sandwich operators. Cost compression in the standard tier is intensifying because protein input volatility compresses margin predictability for operators lacking backward integration. Students demonstrate highest price sensitivity through value-menu loyalty, while professionals in Austin and Denver corridors show lowest sensitivity to premium positioning.
Supply Chain Analysis
Just-in-time inventory preferences dominate protein and produce procurement, though strategic stockpiling of frozen patties and shelf-stable packaging materials buffers against supply disruption. The United States quick service restaurants market draws from domestic beef processing corridors in Texas and Nebraska, poultry concentration in Georgia and Arkansas, and packaging manufacturing hubs in Ohio and Illinois. Single-source vulnerability runs through consolidated beef packer networks. Distribution runs through national broadline distributors with regional cold-chain consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghost kitchen operators and subscription meal platforms pose acute substitution threats that incumbent quick service chains must navigate through digital channel reinforcement and speed-of-service differentiation.
For Market Incumbents: Compound manufacturing scale advantages through automated kitchen equipment deployment across Sun Belt corridors where labor cost divergence creates asymmetric pressure. Capture voice-ordering integration early to reduce error rates and drive ticket size through automated upsell prompts. Defend against ghost kitchen substitution by rebuilding direct digital channels that recover margin lost to third-party aggregator dependency.
For New Entrants and Emerging Players: Lead with central kitchen consolidation models that exploit real estate arbitrage between industrial zones and high-rent retail corridors in California and New York. Target health-positioned customer segments in Massachusetts and California where FDA nutritional disclosure data already filters restaurant selection. Deploy USDA bioengineered food disclosure compliance as a clean-label go-to-market angle before mandates tighten.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with franchise aggregators trapped in commodity competition without backward integration into protein processing. Five-to-ten year viability hinges on technology licensing revenue from predictive staffing algorithms and kitchen automation patents. Watch voice-ordering adoption velocity as the inflection indicator for which operators escape third-party delivery margin erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Drive-thru Dual-lane Deployment | Texas and Florida operators compress service times below three minutes through predictive staffing algorithms. |
| Central Kitchen Consolidation | Sacramento and Austin chains escape high-rent retail corridors via dedicated off-premise production facilities. |
| Voice-ordering Integration | Illinois operators reduce labor interaction at point of sale while automated upsell prompts expand ticket size. |
| Direct Digital Channel Rebuild | National chains recover fifteen-to-thirty percent margin lost to third-party aggregator commission structures. |
| USDA Bioengineered Compliance | Early adopters capture premium positioning through ingredient transparency before federal mandates tighten. |
Research Methodology
Cross-validation between franchisee operations data and municipal regulatory filings anchors the qualitative findings across the United States quick service restaurants market. Primary interviews with quick service franchise operators, supply chain procurement managers, municipal zoning officials, and restaurant technology vendors combined with secondary validation from FDA guidance documents, USDA disclosure standards, state labor department filings, and municipal packaging ordinances. Bottom-up unit economics modeling and top-down market sizing triangulation produced convergent estimates.
Sensitivity analysis tested forecast robustness across protein price volatility scenarios and regulatory implementation timelines over the projection horizon. Segmentation dimensions modeled include service format, product category, customer demographic, and technology deployment intensity. CAGRs derived from historical transaction velocity trends and digital adoption curves. Industry-specific inputs incorporated drive-thru throughput benchmarks and mobile ordering penetration rates by metropolitan corridor.
Forecasts assume regulatory continuity in FDA menu labeling and USDA bioengineered disclosure regimes; material policy shifts would require re-modeling. Specific risk factors include state-level wage regulation divergence and municipal packaging ban fragmentation. Revision becomes warranted when third-party delivery commission structures or protein input volatility cross thresholds that compress unit economics below franchisee investment return requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Online Grocery Delivery Market
Food Service
Spain Food Service Market
Food Service
Global Vending Machine Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Gas Fryers Market
Food Service
Full-Service Restaurants Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Peer-To-Peer Dining Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Restaurant Griddle Market
Food Service
Hyperlocal Grocery Delivery Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
US Food Service Market
Food Service
China Inflight Catering Market
Food Service
Countertop Pressure Fryer Market
Food Service
Bahrain Food Service Market