
 GLP-1 Receptor Agonist Market | 2026-2036
GLP-1 Receptor Agonist Market Size, Share, and Industry Trends Forecast 2026-2036
GLP-1 Receptor Agonist Market Intelligence
Active pharmaceutical ingredient sourcing is shifting from single-source fermentation contracts toward multi-source peptide manufacturing agreements across the GLP-1 receptor agonist supply base. Novo Nordisk anchors European production capacity through in-house recombinant DNA fermentation at its Danish facilities. Eli Lilly and Company leverages external synthesis partnerships for tirzepatide peptide supply while building internal fill-finish capacity. Sanofi competes through retained manufacturing expertise from its legacy diabetes portfolio.
GLP-1 receptor agonists are synthetic peptide analogs of glucagon-like peptide-1 that activate pancreatic beta-cell insulin secretion in a glucose-dependent manner, typically comprising 30-40 amino acid sequences with fatty acid acylation for extended half-life. Their primary commercial purpose spans glycemic control in type 2 diabetes, obesity pharmacotherapy, and emerging cardiovascular risk modification. Semaglutide dominates prescription volume across both diabetes and obesity indications, while oral delivery formulations represent the fastest-growing delivery mode segment as patient convenience preferences reshape competitive dynamics. Injectable liraglutide occupies a mature position with established payer formularies and declining net pricing.
FDA cardiovascular outcome trial requirements and EMA MDR pharmacovigilance standards shape clinical development pathways and post-market surveillance obligations for GLP-1 developers. The EU AI Act and FDA guidance on real-world evidence are creating new regulatory interfaces for digital companion tools and adherence monitoring technologies. Stakeholders must monitor evolving prior authorization criteria from CMS and national health technology assessment bodies as indication expansions strain budget impact thresholds.
Market Dynamics
Supply-side concentration in recombinant peptide manufacturing is reshaping competitive positioning across the GLP-1 receptor agonist value chain, as fermentation capacity constraints force developers into multi-source sourcing strategies and external synthesis partnerships.
Growth Catalysts
- EMA MDR pharmacovigilance standards:Post-market surveillance requirements for cardiovascular outcomes are expanding addressable patient populations through label indications for cardiometabolic risk reduction.
- Oral delivery formulation technology:Non-injectable peptide absorption platforms are unlocking patient segments with needle aversion, accelerating prescription volume in primary care settings.
- United States Medicare reimbursement:Coverage expansion for obesity pharmacotherapy under Part D and employer health plan formularies is concentrating demand volume in the world's largest pharmaceutical market.
Market Restraints
- Fermentation capacity scarcity:Single-source recombinant DNA production contracts in Denmark and limited multi-source peptide synthesis alternatives are creating supply bottlenecks for fatty acid acylated analogs.
- FDA cardiovascular outcome trial mandates:Mandatory CVOT requirements for cardiovascular indications extend development timelines and inflate clinical program costs beyond mid-cap developer resources.
- High-purity peptide synthesis costs:Solid-phase peptide synthesis reagents and chromatography purification media face volatile pricing from specialty chemical suppliers concentrated in Switzerland and Germany.
Strategic Opportunities
- Underpenetrated Japanese metabolic disease management:PMDA obesity indication approvals and METI reimbursement reform are opening access to a population with elevated type 2 diabetes prevalence and limited prior pharmacotherapy utilization.
- Digital companion tool convergence:Integration of GLP-1 adherence monitoring with FDA-cleared software medical devices creates differentiated value propositions for payers implementing outcomes-based contracting.
- Multi-source API manufacturing partnerships:External synthesis agreements with Indian CDMOs and South Korean peptide houses are diversifying supply risk while reducing cost-of-goods for 30-40 amino acid sequences.
Industry Challenges
- Peptide process engineering talent scarcity:Fermentation scale-up expertise and analytical method development for complex biologics are concentrated among legacy insulin manufacturers, constraining new entrant hiring pipelines.
- EU AI Act compliance complexity:Algorithmic dosing recommendation tools and real-world evidence platforms face dual regulatory interfaces with EMA medical device frameworks and artificial intelligence governance requirements.
- Cold chain distribution infrastructure gaps:Temperature-controlled logistics for injectable formulations with 2-8°C stability requirements strain last-mile capabilities in emerging markets with limited specialty pharmacy networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GLP-1 Receptor Agonist Market |
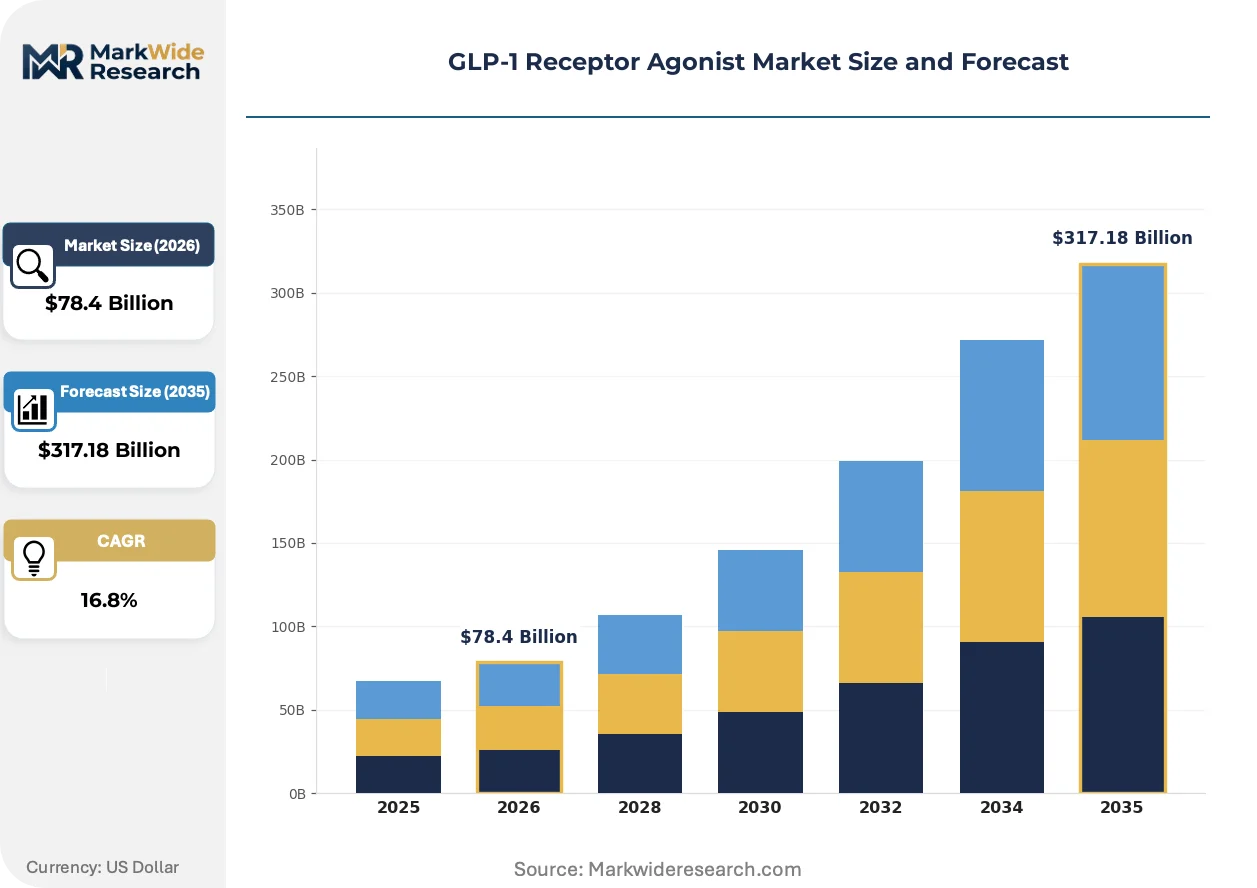
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $317.18 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liraglutide, Semaglutide, Dulaglutide, Exenatide Indication: Type 2 Diabetes, Obesity, Cardiovascular Disease, Weight Management Delivery Mode: Injectable, Oral, Inhalable, Continuous End User: Individuals, Healthcare Providers, Hospitals, Outpatient Clinics |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Sanofi, AstraZeneca, Pfizer, Amgen, Boehringer Ingelheim, Teva Pharmaceutical Industries, Innovent Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GLP-1 Receptor Agonist Market Strategic Shifts & Innovations
Peptide engineering and delivery technology convergence is fragmenting the historical injectable-dominant paradigm, creating competitive openings for oral formulations, combination molecules, and digitally integrated therapeutic ecosystems.
Dual glucose-dependent insulinotropic polypeptide and GLP-1 receptor agonist molecules are modularizing the traditional single-mechanism obesity and diabetes treatment architecture. Endocrinology practices and integrated health systems are adopting these bifunctional peptides at accelerating velocity for patients with inadequate response to semaglutide monotherapy. The technology is modularizing prescriber decision trees into mechanism-stacking protocols rather than linear dose-escalation pathways.
EU AI Act algorithmic risk classification requirements are imposing documentation burdens on machine learning-enabled adherence prediction tools deployed alongside GLP-1 therapies. Developers must now maintain technical files demonstrating conformity with CE marking procedures for software-as-medical-device functionalities. Diabetes management platforms with integrated dosing algorithms face the steepest compliance costs, particularly those marketed across German, French, and Dutch health technology assessment jurisdictions.
Hospital system procurement committees are consolidating GLP-1 purchasing through centralized specialty pharmacy contracts rather than decentralized physician office dispensing. This channel compression is displacing traditional wholesale distribution relationships and concentrating volume with integrated delivery networks possessing in-house 340B pricing capabilities. The shift is most pronounced in United States markets where Medicare Advantage plans and self-insured employers dominate formulary design.
GLP-1 Receptor Agonist Market Segmentation
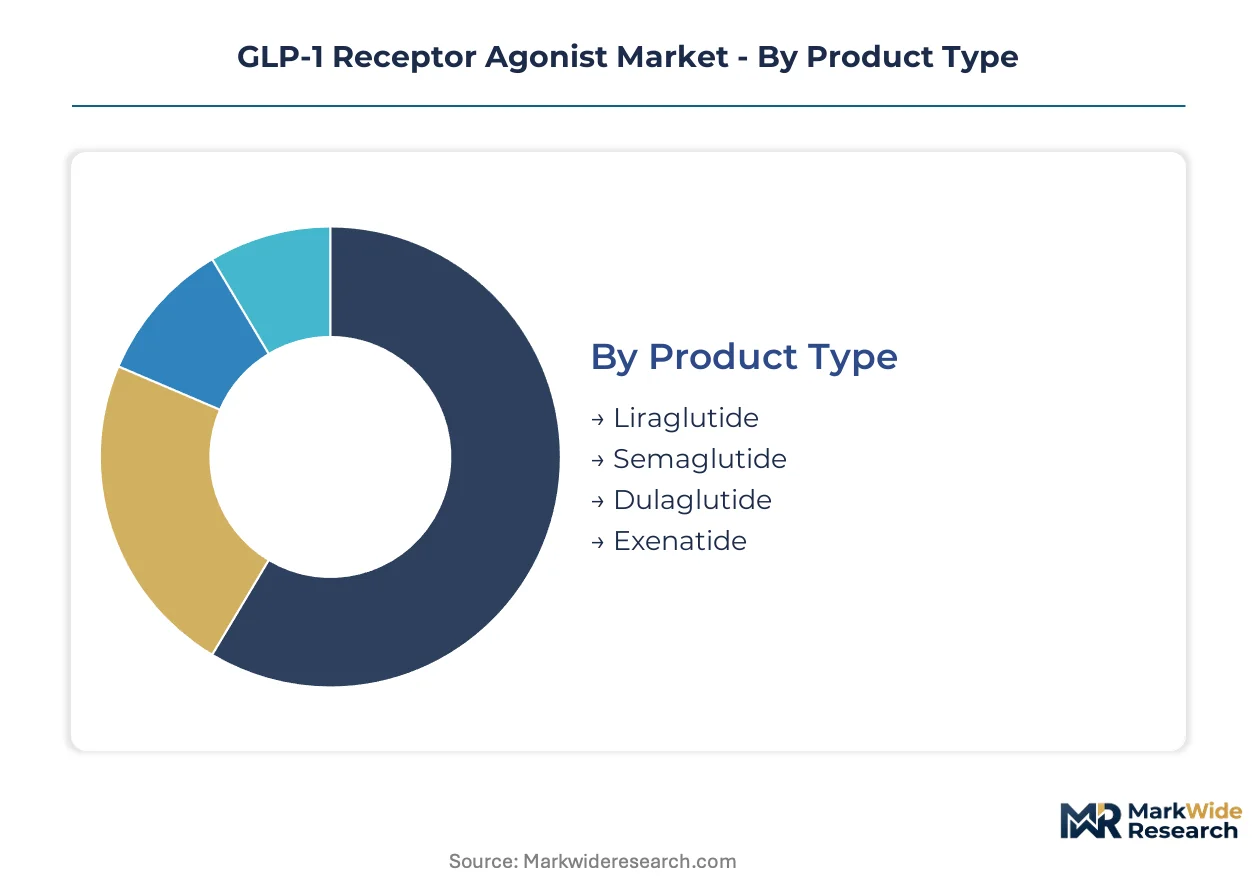
GLP-1 receptor agonist supply chains fragment across peptide engineering specifications, therapeutic indications, and delivery technologies. Each segmentation axis carries distinct manufacturing requirements, reimbursement pathways, and patient access constraints that reshape competitive positioning.
Product Type:
Fermentation capacity allocation and fatty acid acylation complexity concentrate supply-side leverage among recombinant DNA manufacturers with legacy insulin production expertise.
- Semaglutide:A 31-amino acid peptide with C18 fatty diacid modification enabling weekly subcutaneous dosing or daily oral absorption via SNAC co-formulation. Demand concentrates in United States Medicare Part D formularies and employer-sponsored obesity coverage where prior authorization requirements favor established cardiovascular outcomes data.
- Liraglutide:31-amino acid GLP-1 analog with C16 palmitic acid acylation requiring daily injection via prefilled pen devices. Volume clusters in European hospital formularies with EMA-approved cardiovascular risk reduction labeling and mature generic substitution pressures.
- Dulaglutide:Human GLP-1 analog fused to immunoglobulin G4 fragment crystallizable region for extended half-life.
- Exenatide:Synthetic 39-amino acid exendin-4 derivative from Gila monster saliva with twice-daily or extended-release weekly formulations.
Semaglutide absorbs the bulk of installed capacity; oral semaglutide formulations are expanding most quickly.
Indication:
Regulatory label expansions and payer coverage decisions reallocate manufacturing output across metabolic disease applications with diverging clinical evidence requirements.
- Type 2 Diabetes:Original approved indication with glucose-dependent insulin secretion mechanism and established HbA1c reduction endpoints. Prescription volume concentrates in United States endocrinology practices and primary care settings with American Diabetes Association guideline alignment.
- Obesity:Body mass index threshold-driven pharmacotherapy with FDA REMS requirements and EMA cardiovascular outcome trial mandates for sustained weight maintenance claims. Demand accelerates in employer health plans and United States commercial payers with emerging Medicare Part D coverage expansion.
- Cardiovascular Disease:Risk reduction indication requiring dedicated CVOT evidence and FDA/EMA label amendments.
- Weight Management:Lifestyle intervention adjunct with less stringent regulatory pathways than obesity pharmacotherapy.
Type 2 Diabetes retains the largest share of peptide manufacturing output; obesity pharmacotherapy is climbing the fastest.
Delivery Mode:
Patient convenience preferences and cold chain infrastructure capabilities fragment distribution strategies across administration technologies with distinct stability profiles.
- Injectable:Subcutaneous pen devices with 2-8°C cold chain requirements and disposable needle components. Volume concentrates in specialty pharmacy distribution networks and hospital outpatient settings with established refrigeration infrastructure.
- Oral:Tablet formulations employing absorption enhancers for gastrointestinal permeability of peptide macromolecules. Adoption accelerates in primary care prescribing where needle aversion limits injectable uptake and patient self-administration compliance.
- Inhalable:Pulmonary delivery platforms with device engineering complexity and local tolerability considerations.
- Continuous:Pump-based or implantable delivery systems for steady-state pharmacokinetics.
Injectable formulations dominate current manufacturing capacity; oral delivery is gaining share fastest among new patient initiations.
End User:
Procurement centralization and reimbursement channel design concentrate volume with institutional purchasers possessing 340B pricing capabilities or outcomes-based contracting authority.
- Healthcare Providers:Physician practices and integrated delivery networks with centralized specialty pharmacy contracts and electronic health record-integrated prescribing workflows. Demand concentrates in United States Medicare Advantage and commercial risk-bearing organizations with formulary control.
- Hospitals:Inpatient and outpatient facilities with 340B drug pricing program eligibility and clinical pharmacy oversight of metabolic disease protocols. Volume clusters in academic medical centers with bariatric surgery programs and cardiology service line integration.
- Individuals:Cash-pay patients and direct-to-consumer channels with limited insurance coverage.
- Outpatient Clinics:Ambulatory care settings with diabetes educator support and remote monitoring capabilities.
Healthcare providers channel the majority of prescription volume; hospital systems are expanding their share fastest through specialty pharmacy consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Medicare reimbursement policies and employer health plan formularies concentrate prescription volume in the world's largest pharmaceutical market, while manufacturing capacity clusters in Denmark and Switzerland shape supply-side geography.
United States
CMS Part D coverage expansion for obesity pharmacotherapy and American Diabetes Association guideline alignment drive prescription acceleration. FDA REMS requirements for weight management indications create compliance infrastructure demands. Volume clusters in Medicare Advantage plans and self-insured employer networks with centralized specialty pharmacy contracts.
Germany
EMA cardiovascular outcome trial mandates and G-BA health technology assessment procedures shape reimbursement access for cardiometabolic indications. Federal Joint Committee (G-BA) benefit assessment protocols require comparative effectiveness evidence. Manufacturing expertise concentrates in Baden-Württemberg and Bavaria among legacy peptide engineering facilities.
Japan
METI reimbursement reform and PMDA obesity indication approvals unlock access for a population with elevated type 2 diabetes prevalence. Pharmaceutical and Medical Devices Agency (PMDA) pharmacovigilance standards align with EMA MDR frameworks. Tokyo and Osaka metropolitan areas anchor endocrinology practice networks with integrated diabetes educator support.
China
NMPA regulatory pathways for innovative biologics and expanding private health insurance coverage accelerate market access. National Medical Products Administration (NMPA) clinical trial data requirements for imported peptide therapies create development timeline constraints. Shanghai and Suzhou biotech clusters host domestic CDMO partnerships for multi-source API manufacturing.
Switzerland
Swissmedic pharmacovigilance standards and proximity to German and French markets position the country as a regulatory reference point. Swissmedic alignment with EMA centralized procedures streamlines cross-border market authorization. Basel and Zurich anchor specialty chemical suppliers for solid-phase peptide synthesis reagents and chromatography purification media.
GLP-1 Receptor Agonist Market Key Industry Players
Capacity expansion dominates the current landscape as fermentation constraints force developers into multi-source sourcing strategies and external synthesis partnerships. The vendor base concentrates among legacy insulin manufacturers with recombinant DNA expertise and emerging peptide engineering specialists. Two strategic archetypes define positioning: vertically integrated biologics developers with captive fermentation assets, and platform-agnostic innovators leveraging contract manufacturing for fill-finish flexibility. Portfolio diversification into oral delivery formulations and cardiovascular indication expansions represent the dominant competitive vectors.
Within the integrated biologics tier, Novo Nordisk and Eli Lilly and Company exemplify divergent capacity strategies. Novo Nordisk anchors European production through Danish in-house recombinant DNA fermentation, while Eli Lilly and Company occupies a position leveraging external synthesis partnerships for peptide supply alongside internal fill-finish buildout. Sanofi sits within the retained expertise archetype, drawing on legacy diabetes portfolio manufacturing infrastructure. These three entities represent the concentration of installed fermentation capacity and fatty acid acylation capabilities across the GLP-1 value chain.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Pfizer |
| Amgen |
| Boehringer Ingelheim |
| Teva Pharmaceutical Industries |
| Innovent Biologics |
| Others |
Cost & Logistics Intelligence
Private-equity-backed CDMO roll-ups in Indian and South Korean peptide synthesis are consolidating multi-source API contracts while tightening pricing discipline for 30-40 amino acid sequences across the GLP-1 value chain. This ownership concentration enables volume-based contracting leverage with specialty chemical suppliers in Switzerland and Germany, directly compressing cost-of-goods for developers seeking alternatives to Danish single-source fermentation.
Pricing Analysis
Volume concentration in United States Medicare Part D and employer health plans splits pricing power between high-margin obesity pharmacotherapy and commoditizing diabetes indications. Three-tier pricing structure across innovator cardiovascular-risk-labeled products, standard metabolic indications, and economy-positioned legacy molecules reflects FDA REMS compliance costs and EMA pharmacovigilance documentation burdens. Pricing pressure stems from G-BA health technology assessment reference pricing in Germany and emerging generic substitution pressures on daily-injection formats. Cash-pay direct-to-consumer channels exhibit highest price sensitivity; hospital systems with 340B pricing capabilities demonstrate lowest sensitivity due to federal cost recovery mechanisms.
Supply Chain Analysis
FDA and EMA current good manufacturing practice certification requirements gate entry for peptide API suppliers, concentrating qualified capacity in Denmark, Switzerland, and emerging Indian CDMO clusters. Solid-phase peptide synthesis reagents, recombinant DNA fermentation media, and chromatography purification resins constitute critical input dependencies with volatile pricing from German and Swiss specialty chemical houses. Single-source vulnerability pervades C18 fatty diacid modification capabilities anchored at Novo Nordisk's Danish facilities. Distribution runs through temperature-controlled specialty pharmacy networks with 2-8°C cold chain requirements, concentrating last-mile control with integrated delivery networks possessing in-house refrigeration infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GLP-1 receptor agonist sector occupies a technology-transition phase as oral absorption platforms displace injectable-dominant delivery paradigms, with SNAC co-formulation chemistry and dual GIP/GLP-1 bifunctional molecules replacing legacy single-mechanism analogs.
For Market Incumbents: To counter fermentation capacity scarcity and multi-source API competition from Indian CDMOs, Novo Nordisk and Eli Lilly must accelerate backward integration into peptide synthesis reagent supply and secure captive fill-finish capacity in United States markets with 340B pricing concentration. Priority levers include EMA MDR-compliant pharmacovigilance infrastructure investment and digital companion tool CE marking to defend formulary positioning against outcomes-based contracting pressure. For New Entrants and Emerging Players: Oral formulation technology-first wedges open primary care prescribing channels where needle aversion limits incumbent injectable penetration. Underpenetrated Japanese metabolic disease management offers the most accessible geography given METI reimbursement reform and PMDA obesity indication pathways. Go-to-market execution should target hospital system specialty pharmacy consolidation with 340B-eligible integrated delivery networks seeking cardiovascular risk reduction protocols. For Investors and Strategic Acquirers: FDA label expansion for cardiovascular indications without dedicated CVOT requirements is the leading indicator that regulatory efficiency arbitrage opportunities exist for mid-cap developers with existing metabolic disease data packages. Long-term viability across the analysis window favors platform-agnostic innovators with external synthesis partnerships rather than capital-intensive fermentation asset ownership. Acquisition targets should display peptide engineering talent density and algorithmic dosing software with EU AI Act technical file readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | External synthesis partnerships with Indian CDMOs diversify supply risk beyond Danish fermentation concentration. |
| Regulatory Approval Pathway | PMDA obesity indication submissions unlock Japanese employer health plan reimbursement expansion. |
| Pipeline Diversification | Dual GIP/GLP-1 bifunctional molecules capture semaglutide non-responders in endocrinology practices. |
| Software Companion Development | FDA-cleared adherence monitoring tools enable outcomes-based contracting with Medicare Advantage plans. |
| Reimbursement Strategy | CMS Part D coverage expansion for obesity pharmacotherapy concentrates volume in United States commercial payers. |
Research Approach
FDA filings, EMA centralized procedure submissions, and ClinicalTrials.gov protocol registrations formed the secondary backbone, cross-referenced with formulary database audits from United States Medicare Advantage plans and German G-BA benefit assessment documents. Primary interviews with drug development executives at peptide engineering specialists, regulatory affairs leads navigating EU AI Act compliance, hospital procurement managers with 340B pricing authority, and payer access specialists at CMS and commercial insurers validated quantitative assumptions. Bottom-up prescription volume modeling and top-down manufacturing capacity analysis were triangulated against customs data for solid-phase peptide synthesis reagent imports.
Bottom-up patient-flow analysis across type 2 diabetes, obesity, and cardiovascular risk reduction indications was reconciled with top-down fermentation capacity constraints and fatty acid acylation throughput limits. Segmentation dimensions encompassed product type by molecular structure, indication by regulatory label status, delivery mode by administration technology, and end user by procurement channel concentration. CAGRs were derived from installed capacity expansion timelines, payer coverage decision velocity, and epidemiological prevalence modeling without year-specific anchoring. Forecast inputs incorporated EMA MDR pharmacovigilance implementation costs and NMPA clinical trial data requirements for imported biologics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA cardiovascular outcome trial mandate modifications or CMS Medicare Part D formulary restriction shifts. Model assumptions reflect documented regulatory pathways, disclosed manufacturing partnerships, and published health technology assessment criteria. A model refresh is warranted upon material change in EMA centralized procedure timelines or United States 340B drug pricing program eligibility expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Global Heparin Sodium Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Throat Sprays Market