
 Global Anticoagulant Reversal Drugs Market | 2026-2036
Global Anticoagulant Reversal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anticoagulant Reversal Drugs Market Foresight
Plasma-derived prothrombin complex concentrates is rebalancing cost structures against recombinant alternatives in emergency bleeding protocols. Boehringer Ingelheim GmbH anchors its position through proprietary idarucizumab manufacturing and deep clinical validation for dabigatran reversal. CSL Limited dominates the plasma-derived segment with vertical control over fractionation networks across multiple continents. Fresenius Kabi AG competes on hospital formulary access through integrated infusion therapy portfolios.
Anticoagulant reversal drugs comprise biologic and synthetic agents engineered to neutralize the hemorrhagic effects of anticoagulant medications, with formulations typically requiring cold-chain storage at two to eight degrees Celsius and intravenous administration under monitored conditions. These agents serve the critical therapeutic purpose of restoring hemostatic capacity in patients experiencing life-threatening bleeding or requiring urgent surgical intervention. Andexanet alfa occupies the highest-margin tier among product types due to its specificity for factor Xa inhibitors and complex recombinant production requirements. Emergency care leads application demand as stroke and trauma protocols mandate immediate reversal capability, while cardiac surgery sustains predictable volume through scheduled procedures. Intravenous administration controls the route landscape owing to the need for rapid bioavailability in critical settings.
The FDA maintains stringent lot-release testing for plasma-derived concentrates, while the EMA's MDR framework imposes enhanced vigilance obligations on biologic reversal agents distributed across European hospital networks. Health Canada and TGA align with ICH Q5A guidelines for viral safety validation, creating harmonized but rigorous entry barriers for new manufacturers. Stakeholders must monitor evolving pharmacoeconomic assessments from national health technology bodies as these increasingly determine formulary inclusion for premium-priced reversal agents.
Market Dynamics
Medicare reimbursement compression is forcing hospital formulary committees to weigh plasma-derived concentrates against recombinant biologics in emergency bleeding protocols. This cost-accountability pressure is reshaping procurement patterns across integrated delivery networks.
Growth Catalysts
- Factor Xa inhibitor prevalence:The surge in apixaban and rivaroxaban prescriptions for atrial fibrillation has created a parallel demand for targeted reversal capability in emergency departments.
- FDA Breakthrough Therapy designation:Accelerated approval pathways compress clinical trial timelines for novel reversal agents, shortening the gap between development and commercial availability.
- Trauma center certification requirements:Level I trauma centers in the United States must maintain stocked reversal agents to meet ACS verification standards, embedding demand into facility infrastructure.
Market Restraints
- Plasma supply concentration:Fractionation capacity clusters in the United States, Germany, and Australia, exposing the market to geographic supply disruptions and viral safety scares.
- Cold-chain infrastructure costs:Maintenance of two-to-eight-degree Celsius storage through hospital pharmacy and emergency department distribution adds twenty to thirty percent to landed product costs.
- Recombinant production complexity:Andexanet alfa's multi-step mammalian cell culture process limits manufacturing scale-up speed and creates batch-to-batch variability constraints.
Strategic Opportunities
- Pre-hospital administration protocols:Emergency medical services in the United States are piloting field-administered reversal for suspected intracranial hemorrhage, expanding the addressable setting beyond hospital walls.
- Japan's geriatric anticoagulation burden:PMDA fast-track reviews for reversal agents targeting the country's aging atrial fibrillation population offer expedited market entry.
- Lyophilized formulation development:Room-temperature stable presentations would eliminate cold-chain dependency and enable stockpiling in rural and military medical facilities.
Industry Challenges
- Hematology-transfusion medicine staffing gaps:Hospitals struggle to recruit specialists capable of managing complex coagulopathy reversal protocols in high-acuity settings.
- Lot-release testing bottlenecks:FDA's extended viral marker validation timelines for plasma-derived concentrates delay product release and strain hospital inventory management.
- Formulary committee evidence requirements:Pharmacy and therapeutics committees increasingly demand real-world effectiveness data beyond registration trials, lengthening adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anticoagulant Reversal Drugs Market |
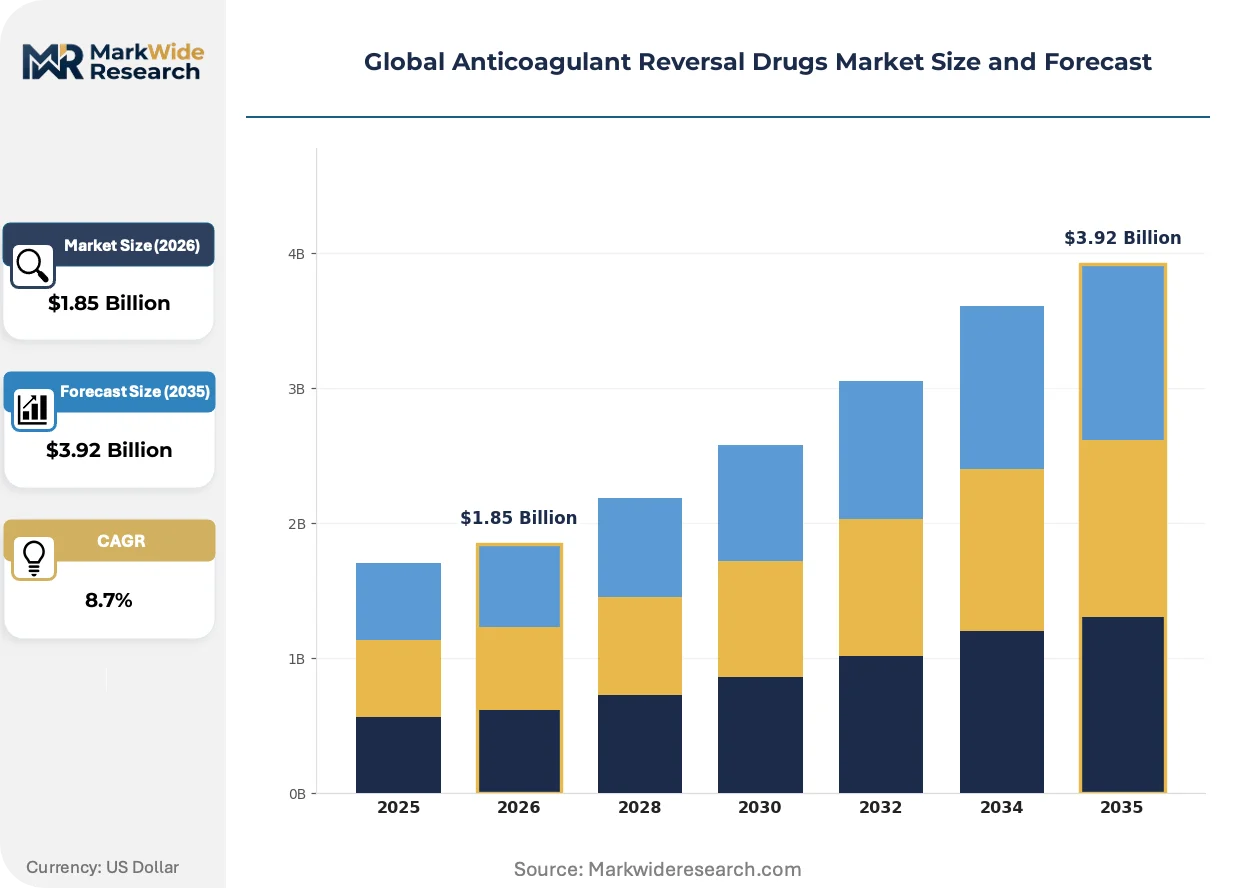
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Idarucizumab, Andexanet Alfa, Prothrombin Complex Concentrates, Factor VIIa Application: Cardiac Surgery, Trauma Management, Gastrointestinal Bleeding, Emergency Care Route of Administration: Intravenous, Subcutaneous, Oral, Intramuscular End User: Hospitals, Emergency Departments, Outpatient Clinics, Rehabilitation Centers |
| Companies Covered | Pfizer Inc, AstraZeneca, Boehringer Ingelheim GmbH, Bausch Health Companies, Teva Pharmaceutical Industries Ltd, Dr. Reddy's Laboratories Ltd, Endo International plc, Fresenius Kabi AG, CSL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anticoagulant Reversal Drugs Market Shifts & Advancements
Reversal agent development is pivoting toward specificity and speed, with manufacturers engineering molecules that outpace the pharmacokinetics of the anticoagulants they target. This arms-race dynamic is compressing development timelines and raising the bar for clinical differentiation.
Recombinant peptide engineering is converging with monoclonal antibody fragment technology to create smaller, faster-clearing reversal agents. Emergency medicine departments in the United States are adopting these agents for stroke protocols requiring rapid anticoagulation neutralization. The structural consequence is a bifurcation between high-specificity biologics commanding premium positioning and plasma-derived alternatives competing on cost.
The EMA's MDR framework imposes enhanced post-market surveillance obligations on biologic reversal agents distributed across European hospital networks. Manufacturers must now maintain active registries tracking hemostatic outcomes and thrombotic events. Cardiac surgery units in Germany and France are responding by consolidating purchasing through group purchasing organizations to share liability and compliance costs.
Hospital formulary committees are unbundling reversal agent procurement from anticoagulant vendor contracts, ending the era of bundled rebates. Integrated delivery networks in the United States are instead sourcing through specialty pharmacy distributors with 340B pricing access. This shift is most visible in the Southeast, where hospital systems are consolidating pharmacy benefit management under centralized governance structures.
Global Anticoagulant Reversal Drugs Market Segmentation
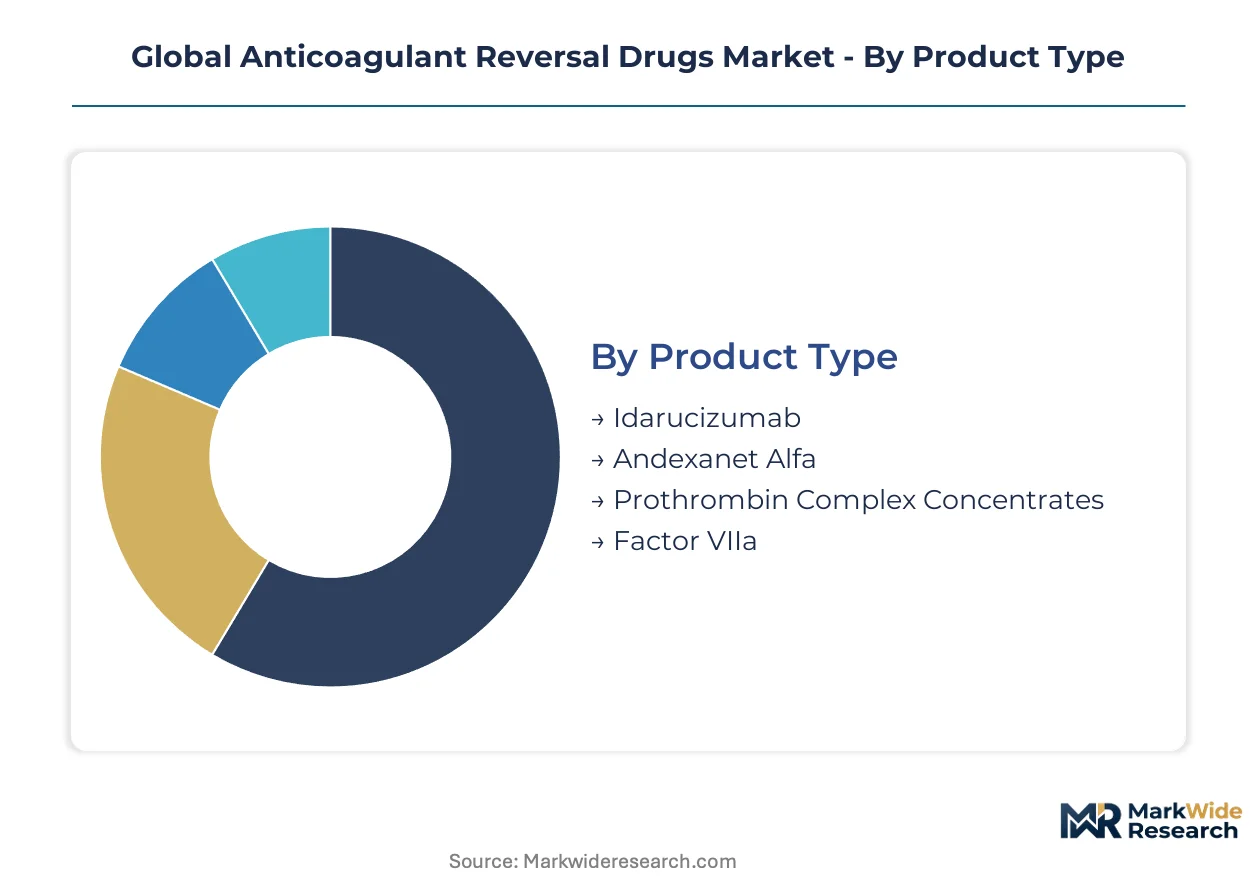
Anticoagulant reversal drugs fragment across four dimensions that determine procurement logic, margin capture, and competitive positioning. Each category reflects distinct buyer priorities ranging from clinical specificity to logistical infrastructure requirements.
Product Type:
Hospital formulary committees differentiate products based on target anticoagulant specificity versus cost containment imperatives under Medicare reimbursement pressure.
- Andexanet Alfa:A recombinant modified factor Xa decoy protein engineered through multi-step mammalian cell culture. Demand concentrates in United States Level I trauma centers managing apixaban and rivaroxaban-associated bleeding, where FDA breakthrough therapy designation enabled rapid formulary adoption despite premium pricing.
- Idarucizumab:A humanized monoclonal antibody fragment binding dabigatran with high affinity. German and Australian emergency departments stock this agent for rapid dabigatran neutralization, driven by Boehringer Ingelheim's proprietary manufacturing and deep clinical validation datasets.
- Prothrombin Complex Concentrates:Plasma-derived factor concentrates offering broad-spectrum reversal capability. United States integrated delivery networks favor these for cost-accountable bleeding protocols.
- Factor VIIa:Recombinant activated coagulation factor for refractory hemorrhage. Japanese cardiac surgery units maintain this for salvage scenarios.
Volume sits with Prothrombin Complex Concentrates; growth tilts toward Andexanet Alfa.
Application:
Clinical urgency and reimbursement pathway structure create divergent procurement patterns across bleeding scenarios.
- Emergency Care:Stroke and trauma protocols mandate immediate reversal capability with hard time-to-treatment windows. United States emergency departments drive demand through ACS verification requirements for Level I trauma centers.
- Cardiac Surgery:Scheduled procedures enable predictable inventory planning and group purchasing organization consolidation. German and French cardiac units source through centralized procurement to share EMA MDR compliance costs.
- Trauma Management:Field-administered reversal pilots in United States emergency medical services are expanding addressable settings beyond hospital walls.
- Gastrointestinal Bleeding:Endoscopy suite requirements favor agents with rapid onset and short half-life for procedural control.
Cardiac Surgery holds current volume leadership; Emergency Care is climbing the fastest as pre-hospital protocols mature.
Route of Administration:
Speed of bioavailability and monitoring infrastructure determine route selection in critical care environments.
- Intravenous:Direct vascular access enables immediate peak plasma concentration. Controls the landscape through emergency department and operating room dominance where seconds determine outcomes.
- Subcutaneous:Emerging for stable patients requiring gradual reversal in outpatient transition settings.
- Oral:Limited utility given urgency constraints; explored for vitamin K antagonist reversal in non-critical scenarios.
- Intramuscular:Minimal adoption due to unpredictable absorption kinetics in hemodynamically unstable patients.
Intravenous administration captures absolute volume; Subcutaneous development programs target the steepest expansion trajectory for post-acute care transitions.
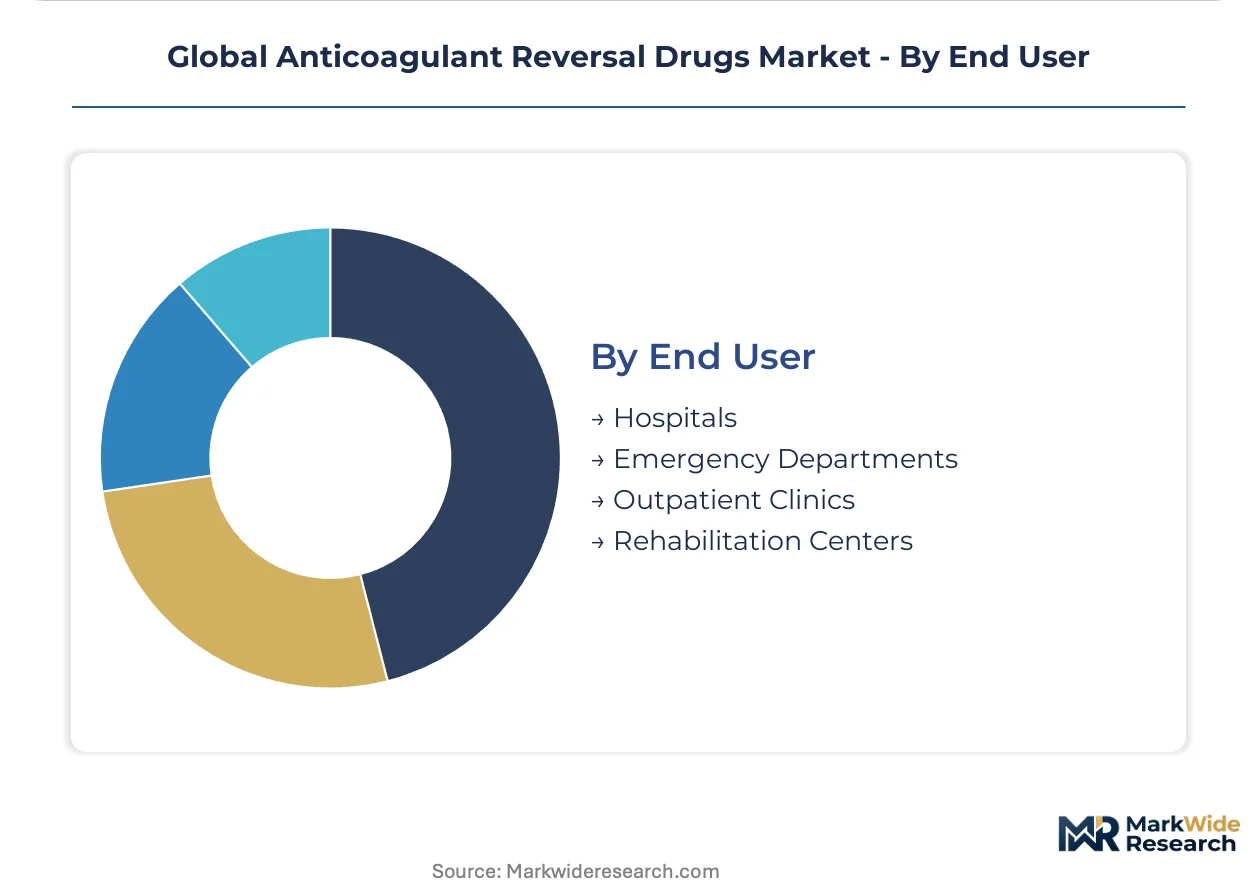
End User:
Facility acuity level and reimbursement classification shape product mix and pricing tolerance.
- Hospitals:Inpatient settings with 340B pricing access and centralized pharmacy governance. United States hospital systems in the Southeast are consolidating benefit management under specialty pharmacy distributors.
- Emergency Departments:Highest-margin consumption site with immediate need justification bypassing traditional formulary delays.
- Outpatient Clinics:Anticoagulation management centers requiring reversal capability for procedural bridging.
- Rehabilitation Centers:Long-term care facilities with limited reversal stocking due to transfer protocols for acute events.
Emergency Departments command premium positioning; Outpatient Clinics are gaining share fastest as anticoagulation monitoring shifts to ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement power concentrates in the United States, where Medicare reimbursement frameworks and trauma center certification requirements embed reversal agents into emergency infrastructure. Germany and Japan follow as distinct demand poles shaped by regulatory acceleration pathways and aging cardiovascular populations.
United States
Level I trauma centers in Texas, California, and Florida drive volume through American College of Surgeons verification mandates requiring stocked reversal capability. FDA breakthrough therapy designations compress approval timelines for novel agents targeting factor Xa inhibitors. The Southeast hospital corridor from Atlanta to Miami consolidates pharmacy benefit management under specialty distributors with 340B pricing access.
Germany
Cardiac surgery units in Bavaria and North Rhine-Westphalia anchor European demand through centralized procurement consortia sharing EMA MDR compliance costs. Boehringer Ingelheim's idarucizumab manufacturing base in Ingelheim supplies domestic emergency departments with rapid dabigatran reversal. Berlin's university hospital networks pilot outcome-based reimbursement for bleeding management protocols.
Japan
PMDA fast-track reviews accelerate market entry for agents addressing the country's geriatric atrial fibrillation burden concentrated in Tokyo and Osaka metropolitan areas. The Kanto region's stroke centers maintain stringent hemostasis protocols requiring immediate reversal stockpiles. Japanese cardiac surgeons in Nagoya favor recombinant activated factor VII for refractory hemorrhage salvage scenarios.
Australia
CSL Limited's fractionation network in Melbourne and plasma collection infrastructure across Victoria and New South Wales supply Asia-Pacific markets with prothrombin complex concentrates. TGA alignment with ICH Q5A viral safety guidelines creates harmonized entry barriers for imported biologics. Sydney's trauma institutes participate in field-administered reversal pilots for suspected intracranial hemorrhage.
United Kingdom
NHS England's specialized commissioning frameworks concentrate high-cost biologic reversal in London's major teaching hospitals and Manchester's regional trauma centers. The MHRA's post-Brexit regulatory autonomy maintains equivalence with EMA standards while streamlining emergency use authorizations. Scottish emergency departments in Glasgow and Edinburgh prioritize plasma-derived concentrates under cost-accountability pressure.
Global Anticoagulant Reversal Drugs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with proprietary biologic developers commanding premium positioning in emergency care while plasma fractionators compete on scale and cost containment. The market structure tilts toward consolidation at the top tier, where vertical control over manufacturing and clinical validation datasets creates defensive moats. Three archetypes dominate: recombinant biologic specialists with FDA breakthrough designations, integrated plasma fractionators with continental supply networks, and infusion therapy conglomerates leveraging hospital formulary access. Competitive moves center on M&A for fractionation capacity and strategic partnerships for lyophilized formulation development.
Among integrated plasma specialists, CSL Limited and Fresenius Kabi AG occupy positions exemplifying the scale-driven archetype, with geographic naming conventions suggesting Australian and German origins respectively. Boehringer Ingelheim GmbH anchors the proprietary biologic tier through its GmbH structure indicating German corporate formation. These three entities represent distinct competitive vectors: fractionation network control, hospital supply chain integration, and targeted monoclonal antibody development.
| Leading Market Players |
|---|
| Pfizer Inc |
| AstraZeneca |
| Boehringer Ingelheim GmbH |
| Bausch Health Companies |
| Teva Pharmaceutical Industries Ltd |
| Dr. Reddy's Laboratories Ltd |
| Endo International plc |
| Fresenius Kabi AG |
| CSL Limited |
| Others |
Supply & Pricing Matrix
Medicare reimbursement compression in United States hospital systems is forcing formulary committees toward plasma-derived concentrates over recombinant biologics, compelling suppliers to reconfigure manufacturing scale and cold-chain logistics around cost-accountable procurement patterns.
Pricing Analysis
Volume concentrates in plasma-derived prothrombin complex concentrates while margins cluster with andexanet alfa and idarucizumab. Price differentiation hinges on target specificity versus broad-spectrum capability, with FDA breakthrough designation commanding premium positioning. Cost compression in the plasma-derived tier is intensifying because integrated delivery networks leverage 340B pricing access. Emergency departments show least price sensitivity due to immediate-need justification, while outpatient clinics face strict budget caps.
Supply Chain Analysis
Regional distribution centers in Melbourne, Ingelheim, and Kansas City maintain hub-and-spoke patterns feeding hospital pharmacy networks. Manufacturing concentrates in the United States, Germany, and Australia, with fractionation capacity drawing from Victorian and New South Wales plasma collection infrastructure. Raw material dependencies include source plasma, mammalian cell culture media, and recombinant protein purification resins. Single-source vulnerability around Boehringer Ingelheim's proprietary idarucizumab production exposes buyers to allocation risk. Distribution runs through specialty pharmacy distributors with cold-chain custody verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation is accelerating as Medicare reimbursement pressure and EMA MDR compliance costs force sub-scale fractionators and development-stage biologics firms toward exit or acquisition.
For Market Incumbents: Hedge against biosimilar encroachment by securing backward integration into plasma collection networks across multiple continents. Accelerate lyophilized formulation programs to eliminate cold-chain dependency and unlock rural military stockpiling contracts. Defensive patent estate expansion around modified factor Xa decoy architectures will delay generic entry. For New Entrants and Emerging Players: Begin with pre-hospital administration protocols in United States emergency medical services, where field-administered reversal for suspected intracranial hemorrhage remains white space. Japan's PMDA fast-track pathway offers expedited entry for agents addressing geriatric atrial fibrillation. Partner with trauma center certification bodies to embed product requirements into ACS verification standards. For Investors and Strategic Acquirers: The window for entry favors integrated plasma fractionators with continental supply networks and established viral safety validation datasets. Long-term viability rests on vertical control over collection-through-distribution infrastructure rather than single-product biologic developers. Watch for FDA lot-release testing bottleneck resolution as signal of supply elasticity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilized Formulation Development | Room-temperature stability eliminates cold-chain costs and enables military stockpiling in remote facilities. |
| Plasma Collection Network Expansion | CSL Limited's Victorian infrastructure demonstrates how geographic diversification mitigates viral safety scares. |
| Pre-Hospital Protocol Partnerships | EMS field-administration pilots in Texas trauma systems extend addressable settings beyond hospital walls. |
| EMA MDR Compliance Registry | Active hemostatic outcome tracking satisfies enhanced vigilance obligations for European hospital network access. |
| 340B Pricing Access Consolidation | Southeast United States hospital systems leverage specialty pharmacy distributors for cost-accountable procurement. |
Research Methodology
Document review covered FDA breakthrough therapy designations, EMA MDR technical documentation, and ClinicalTrials.gov registries, complemented by interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Secondary validation drew from CMS Medicare reimbursement databases, hospital procurement records, and plasma fractionator SEC filings. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to constrain forecast variance.
Cross-reference between historical approval timelines and expert panel input on regulatory acceleration pathways shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type specificity, application urgency tier, administration route, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and pricing trajectory consensus. Forecast inputs incorporated trauma center certification mandates and PMDA fast-track review velocity assumptions.
Underlying measurement precision varies by segment; emergency care and cardiac surgery applications carry tighter precision than emerging pre-hospital protocols due to established procedure coding. Forecasts reflect assumptions around Medicare reimbursement stability and plasma supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Latin America Biguanide Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Mitotane Market
Pharmaceuticals
Japanese Encephalitis Vaccine Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market