
 Cardiometabolic Disease Market | 2026-2036
Cardiometabolic Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiometabolic Disease Market Intelligence
FDA's accelerated approval framework for combination cardiometabolic therapies is hardening the evidence threshold for new entrants. Novo Nordisk A/S leverages its GLP-1 manufacturing scale to dominate obesity-linked cardiometabolic indications. Eli Lilly and Company anchors its position through deep R&D investment in dual-hormone agonists. Boehringer Ingelheim differentiates via SGLT2 inhibitor specialization across heart failure and chronic kidney disease extensions.
Cardiometabolic disease encompasses interconnected cardiovascular and metabolic pathologies including type 2 diabetes, dyslipidemia, hypertension, and obesity, typically managed through pharmacological modulation of glucose homeostasis, lipid metabolism, and vascular tone using small-molecule and biologic agents. Antidiabetics and lipid-lowering agents represent the largest revenue pools, while anticoagulants and angiotensin receptor blockers command premium pricing in acute coronary syndrome prevention. Hospitals and specialty clinics absorb the majority of infused and injectable volumes, whereas retail drug stores and online pharmacies capture oral maintenance therapy refills.
FDA, EMA, and WHO standards govern clinical trial endpoints, manufacturing quality, and bioequivalence requirements for cardiometabolic therapies, with FDA's cardiovascular outcomes trial mandates directly extending development costs and timelines. The EU MDR and FDA's evolving real-world evidence frameworks are reshaping post-market surveillance obligations for device-drug combinations. Stakeholders must monitor how CMS coverage determinations and NICE technology appraisals will split risk between manufacturers and payers for next-generation combination regimens.
Market Dynamics
GLP-1 receptor agonist manufacturing capacity constraints are compressing supply timelines while hospital systems accelerate integrated cardiometabolic screening protocols, creating a structural mismatch between preventive demand and biologic production throughput.
Growth Catalysts
- FDA Accelerated Approval Pathways:The framework for combination cardiometabolic therapies compresses development timelines for dual-hormone agonists, pulling forward revenue recognition for sponsors who meet cardiovascular outcomes thresholds.
- Integrated Care Networks:United States hospital systems are bundling diabetes, obesity, and cardiovascular screening into single encounters, driving volume for preventive pharmacological interventions at the point of diagnosis.
- SGLT2 Inhibitor Label Extensions:Chronic kidney disease and heart failure indications are expanding the addressable population beyond glycemic control, creating new prescriber segments in nephrology and cardiology.
Market Restraints
- Peptide API Concentration:Active pharmaceutical ingredient production for GLP-1 analogs concentrates among contract manufacturers in Denmark and Ireland, exposing sponsors to single-source supply risk.
- Cardiovascular Outcomes Trial Mandates:FDA requirements for large-scale safety endpoints extend development costs and timelines, erecting capital barriers for mid-cap entrants without existing cardiovascular infrastructure.
- Reimbursement Compression:CMS national coverage determinations and NICE technology appraisals are tightening cost-effectiveness thresholds for combination regimens, squeezing net pricing power.
Strategic Opportunities
- Real-World Evidence Frameworks:FDA and EMA post-market surveillance pathways enable label expansion through observational data, reducing reliance on prospective randomized trials for indication extensions.
- Retail Clinic Integration:CVS Health and Walgreens are embedding cardiometabolic screening into primary care workflows, creating direct-to-consumer channels that bypass traditional specialty referral.
- Dual-Hormone Agonist Convergence:GLP-1/GIP and GLP-1/glucagon combinations are opening obesity-linked cardiovascular endpoints previously unattainable with single-mechanism agents.
Industry Challenges
- Biostatistician Talent Scarcity:Cardiovascular outcomes trial design requires specialized expertise in adaptive trial methodologies and surrogate endpoint validation, with limited personnel pools.
- Cold Chain Complexity:Injectable peptide therapies require continuous temperature-controlled distribution, comifying last-mile delivery to retail pharmacies and patient homes.
- Legacy EHR Integration:Hospital systems struggle to merge cardiometabolic risk scores across disparate diabetes, cardiology, and renal modules, fragmenting care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiometabolic Disease Market |
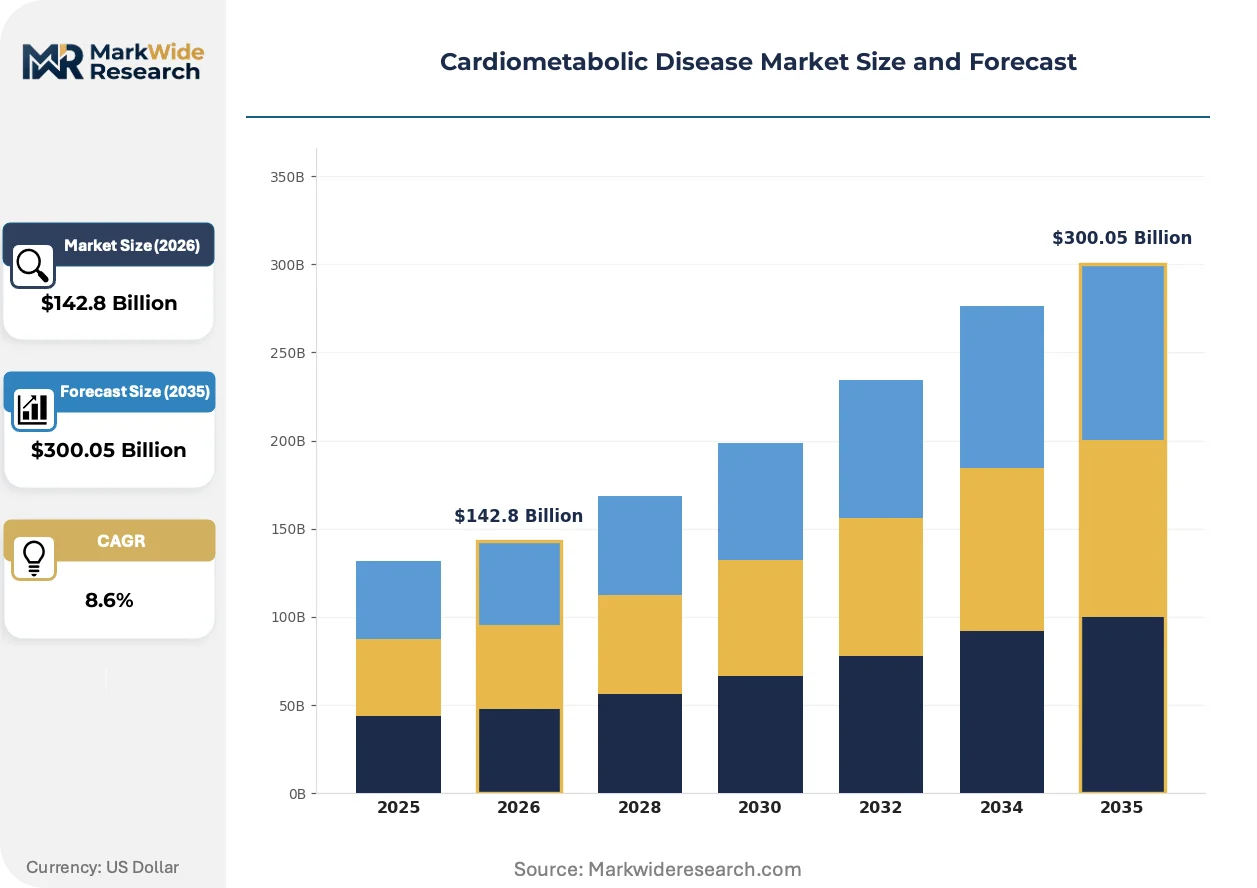
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $300.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihypertensives, Lipid-Lowering Agents, Antidiabetics, Anticoagulants, Angiotensin Receptor Blockers Therapy Area: Type 2 Diabetes, Hypertension, Obesity, Dyslipidemia, Metabolic Syndrome End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Cardiology Centers, Primary Care Facilities Distribution Channel: Pharmacies, Online Pharmacies, Hospital Pharmacies, Retail Drug Stores, Direct Sales |
| Companies Covered | Novartis AG, Boehringer Ingelheim, Novo Nordisk A/S, Merck & Co., Inc., Sanofi, Eli Lilly and Company, Bayer AG, GSK plc, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiometabolic Disease Market Strategic Shifts & Innovations
Digital biomarker integration and decentralized trial infrastructure are compressing evidence-generation cycles, while manufacturing technology shifts promise to loosen peptide supply constraints that currently throttle market expansion.
Continuous glucose monitoring systems paired with automated insulin delivery are modularizing diabetes management into closed-loop ecosystems. Endocrinology practices in the United States and Germany are adopting these integrated platforms at accelerating rates. The technology is modularizing prescriber workflows by collapsing multiple device prescriptions into single-platform decisions.
EMA's Medical Device Regulation is tightening clinical evidence requirements for drug-device combinations incorporating connected delivery systems. Manufacturers must now submit standalone technical documentation for smart pens and patch pumps, extending regulatory timelines. Cardiometabolic sponsors with device-naive histories are responding by acquiring or partnering with dedicated delivery technology firms.
Hospital procurement committees are consolidating vendor relationships for cardiometabolic injectables, favoring sole-source agreements with integrated supply and patient-support services. Specialty distributors are losing share to direct manufacturer-to-health-system contracts. This concentration is most visible in United States integrated delivery networks where pharmacy benefit managers and hospital formularies have merged decision rights.
Cardiometabolic Disease Market Segmentation
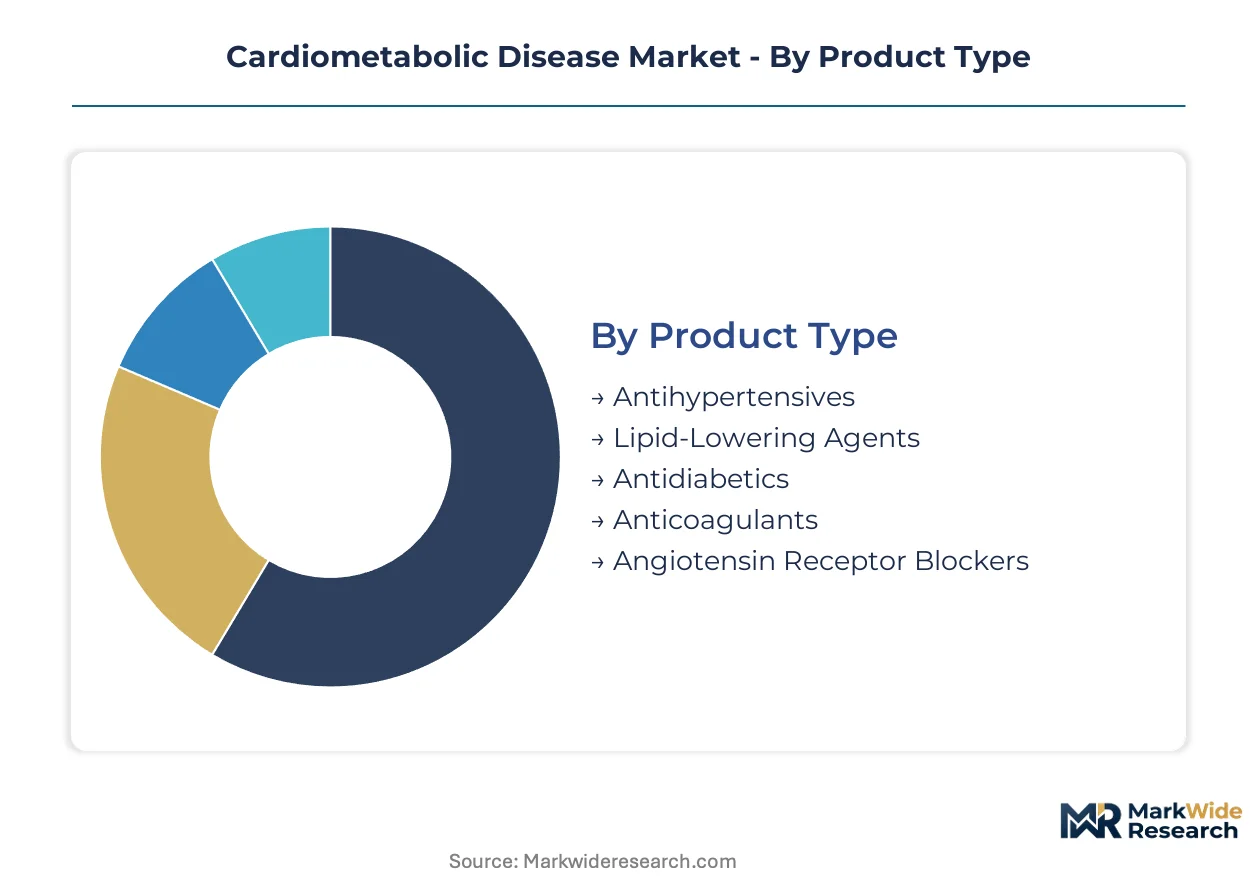
Cardiometabolic disease management fragments across pharmacological mechanisms, care settings, and distribution pathways. Each segmentation dimension reveals distinct margin structures, regulatory burdens, and patient access barriers that shape commercial strategy.
Product Type:
Prescriber familiarity and reimbursement tiering drive selection within this category, with mechanism-of-action differentiation commanding premium access in integrated formularies.
- Antidiabetics:GLP-1 receptor agonists and SGLT2 inhibitors dominate prescribing patterns for glycemic control with cardiovascular benefit claims. Hospital systems in the United States prioritize these agents in bundled diabetes-cardiovascular protocols despite cold chain requirements.
- Lipid-Lowering Agents:PCSK9 inhibitors and statin combinations target residual cardiovascular risk in high-risk populations. Demand concentrates in specialty lipid clinics where prior authorization workflows favor established high-potency statin backbones.
- Antihypertensives:Fixed-dose combinations of ACE inhibitors, calcium channel blockers, and diuretics anchor first-line therapy in primary care settings.
- Anticoagulants:Direct oral anticoagulants displace warfarin in atrial fibrillation stroke prevention and venous thromboembolism management.
- Angiotensin Receptor Blockers:Telmisartan and valsartan formulations serve as foundational agents in hypertension and heart failure with reduced ejection fraction.
Volume sits with Antihypertensives; growth tilts toward Antidiabetics.
Therapy Area:
Comorbidity clustering reshapes addressable populations, with overlapping diagnostic criteria expanding eligible patient pools beyond single-disease labels.
- Type 2 Diabetes:Hyperglycemia with established cardiovascular or renal disease drives preferential use of SGLT2 inhibitors and GLP-1 agonists. United States endocrinology practices adopt these agents earlier in disease progression following ADA guideline updates.
- Obesity:Pharmacological weight management intersects with cardiovascular risk reduction as semaglutide and tirzepatide demonstrate outcome benefits. Demand surges in integrated metabolic-bariatric programs where reimbursement hinges on BMI thresholds and comorbidity documentation.
- Hypertension:Resistant hypertension subpopulations access mineralocorticoid receptor antagonists and renal denervation adjuncts.
- Dyslipidemia:Familial hypercholesterolemia and atherosclerotic cardiovascular disease populations require aggressive LDL-C lowering.
- Metabolic Syndrome:Clustered risk factors drive polypharmacy approaches targeting multiple pathways simultaneously.
Patient volume clusters in Type 2 Diabetes; Obesity claims the steepest expansion trajectory.
End User:
Care coordination intensity and infusion capability determine site-of-service economics, with site-of-care shifts altering drug margin capture.
- Hospitals:Acute coronary syndrome, stroke, and decompensated heart failure admissions trigger inpatient cardiometabolic protocol initiation. United States integrated delivery networks capture downstream ambulatory pharmacy revenue through discharge prescription workflows.
- Specialty Clinics:Endocrinology and cardiology subspecialists manage complex multi-morbidity patients requiring biologic injectables. Germany's office-based specialist sector absorbs significant GLP-1 agonist volume through statutory health insurance reimbursement.
- Primary Care Facilities:Hypertension and initial type 2 diabetes management occur in high-volume, lower-margin encounters.
- Cardiology Centers:Device-implanted patients and post-ACS populations receive intensive lipid and anticoagulation management.
- Diagnostic Laboratories:Point-of-care HbA1c, lipid panel, and NT-proBNP testing drives therapy initiation and monitoring.
Prescription volume concentrates in Primary Care Facilities; Specialty Clinics capture the fastest-growing biologic-administration revenue.
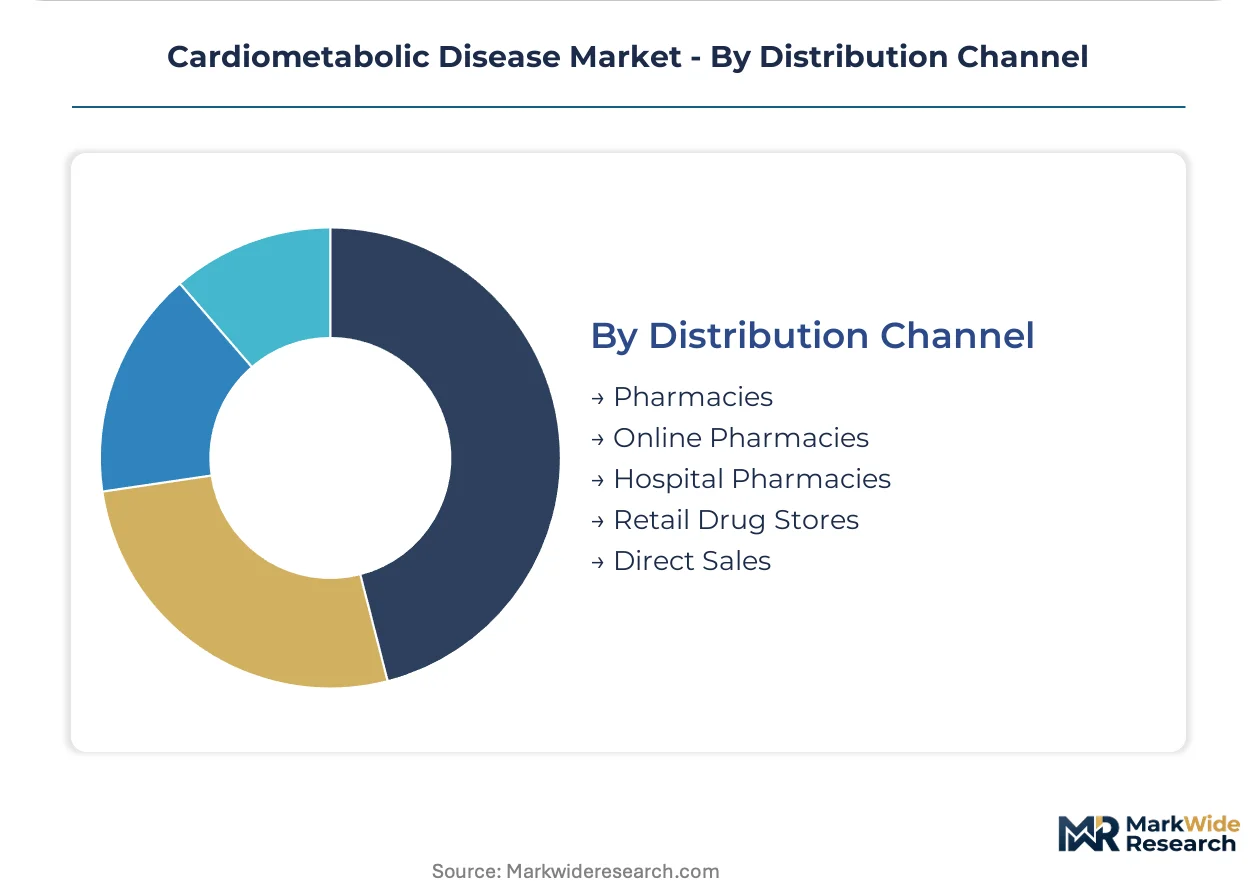
Distribution Channel:
Patient convenience and payer channel control dictate routing, with mail-order and specialty pharmacy carve-outs fragmenting traditional retail dominance.
- Hospital Pharmacies:Inpatient-to-outpatient transitions and 340B pricing advantages anchor specialty drug dispensing. United States health systems expand captive pharmacy capabilities to retain margin on physician-administered cardiometabolic agents.
- Retail Drug Stores:CVS Health and Walgreens capture maintenance oral therapy refills through 90-day supply programs and adherence packaging. Chronic disease medication synchronization programs drive foot traffic and front-of-store revenue.
- Online Pharmacies:Amazon Pharmacy and capsule services penetrate cash-pay obesity medication segments.
- Pharmacies:Independent and chain community pharmacies serve Medicare Part D and commercial insured populations.
- Direct Sales:Manufacturer-to-health-system contracts bypass wholesale distribution for high-value injectables.
Transaction volume flows through Retail Drug Stores; Hospital Pharmacies gain share fastest in specialty injectables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's Copenhagen-Medicon Valley corridor concentrates GLP-1 peptide API manufacturing capacity, attracting contract development organizations serving North American and European sponsors. This tax-advantaged cluster anchors biologic production for cardiometabolic therapies.
United States
Integrated delivery networks in Texas and Florida bundle diabetes-cardiovascular screening into single encounters, driving demand for preventive pharmacological interventions. FDA accelerated approval pathways for combination therapies compress development timelines for sponsors meeting cardiovascular outcomes thresholds. The Research Triangle Park cluster in North Carolina hosts clinical trial infrastructure supporting cardiometabolic outcomes studies.
Germany
Statutory health insurance reimbursement anchors office-based specialist prescribing of GLP-1 agonists in Bavaria and Baden-Württemberg. EMA Medical Device Regulation tightens clinical evidence requirements for drug-device combinations incorporating connected delivery systems. The Mannheim-Heidelberg medical technology corridor concentrates smart pen and patch pump manufacturing for diabetes management platforms.
Switzerland
Basel's pharmaceutical cluster houses legacy cardiovascular infrastructure supporting dual-hormone agonist development programs. Swissmedic maintains stringent bioequivalence standards for biosimilar cardiometabolic therapies entering European markets. The Zurich metropolitan area attracts specialized biostatistician talent for adaptive cardiovascular outcomes trial design.
China
NMPA reform of clinical trial approval processes accelerates cardiometabolic therapy registration for domestic sponsors in Shanghai and Suzhou. The country's national pharmaceutical regulator mandates local cardiovascular outcomes data for label claims involving heart failure endpoints. The Yangtze River Delta biotech corridor expands peptide manufacturing capacity to address regional GLP-1 supply constraints.
Cardiometabolic Disease Market Key Industry Players
Danish producers anchor one tier through concentrated peptide API manufacturing; United States and Swiss specialists hold development-stage positions through cardiovascular outcomes infrastructure. The market structure reflects a bifurcation between manufacturing-scale incumbents and R&D-intensive challengers. Three archetypes dominate: integrated biologic manufacturers with captive supply chains, dual-hormone agonist developers pursuing obesity-cardiovascular convergence, and SGLT2 inhibitor specialists extending into renal and heart failure indications. Competitive moves concentrate on backward integration into peptide production and strategic partnerships for real-world evidence generation.
Within the manufacturing-scale tier, Novo Nordisk A/S and Eli Lilly and Company occupy positions defined by production capacity and clinical trial infrastructure. Boehringer Ingelheim exemplifies the SGLT2 specialization archetype, while AstraZeneca and Sanofi represent European contenders with cardiovascular legacy portfolios. Merck & Co., Inc. and Bayer AG sit within the established pharmaceutical conglomerate tier, leveraging existing hospital system relationships. Novartis AG and GSK plc occupy positions reflecting diversified therapeutic footprints with selective cardiometabolic exposure.
| Leading Market Players |
|---|
| Novartis AG |
| Boehringer Ingelheim |
| Novo Nordisk A/S |
| Merck & Co., Inc. |
| Sanofi |
| Eli Lilly and Company |
| Bayer AG |
| GSK plc |
| AstraZeneca |
| Others |
Cost & Logistics Intelligence
Peptide active pharmaceutical ingredient costs cascade through three distinct pricing tiers as GLP-1 agonist manufacturers balance Danish and Irish contract manufacturing premiums against spot-market API alternatives from emerging Asian producers. Cold chain logistics expenses compound this stratification, with temperature-controlled distribution commanding premium positioning for patient-home delivery while hospital-direct contracts negotiate volume-based concessions.
Pricing Analysis
Short lead-time peptide API procurement commands 15-30% premiums over standard contract schedules as Novo Nordisk and Eli Lilly compete for finite fermentation capacity. Pricing stratifies across premium branded GLP-1 formulations, standard SGLT2 inhibitor portfolios, and economy-tier generic statin backbones, with FDA cardiovascular outcomes trial certification serving as the primary quality differentiator. Cost compression in the oral maintenance therapy tier is intensifying because CMS national coverage determinations are tightening cost-effectiveness thresholds for combination regimens. Primary care facilities exhibit highest price sensitivity due to formulary budget constraints, while integrated delivery networks leverage captive pharmacy capabilities to capture margin on physician-administered injectables.
Supply Chain Analysis
Direct-to-health-system contracts bypass wholesale distribution for high-value GLP-1 agonists, with United States integrated delivery networks and German statutory health insurance funds absorbing the majority of specialty injectable volume. Peptide API production concentrates in Denmark, Ireland, and China's Yangtze River Delta biotech corridor, with fermentation capacity expansion lagging demand acceleration by 18-24 months. Supply chain architecture rests on single-source contract manufacturing dependencies for GLP-1 analogs, creating vulnerability to facility contamination or regulatory inspection delays. Distribution runs through three parallel channels: hospital captive pharmacies for inpatient-to-outpatient transitions, specialty distributors for clinic-based administration, and direct-to-patient cold chain delivery for home-use obesity medications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA cardiovascular outcomes trial mandates function as a cost-of-compliance moat, erecting capital barriers that protect incumbent sponsors with existing cardiovascular infrastructure while excluding mid-cap entrants lacking adaptive trial expertise and biostatistician talent pools.
For Market Incumbents: Anchor manufacturing-scale advantages through backward integration into peptide API production, securing fermentation capacity in Denmark-Medicon Valley or China's Yangtze River Delta before contract manufacturer queues extend beyond 36 months. Defend against SGLT2 inhibitor commoditization by embedding real-world evidence generation partnerships with United States integrated delivery networks, converting clinical trial infrastructure into post-market surveillance capabilities that accelerate label expansion. For New Entrants and Emerging Players: Begin with renal denervation device-drug combinations or metabolic syndrome diagnostic platforms, segments where EMA Medical Device Regulation compliance requirements remain less stringent than GLP-1 agonist cardiovascular outcomes thresholds. Target United States retail clinic networks operated by CVS Health and Walgreens, where cardiometabolic screening integration creates direct-to-consumer channels bypassing traditional specialty referral bottlenecks. Pursue licensing arrangements with established peptide manufacturers rather than greenfield API investment. For Investors and Strategic Acquirers: FDA breakthrough therapy designation grants for dual-hormone agonists are the leading indicator that obesity-cardiovascular convergence endpoints will command premium reimbursement positioning within 24-36 months. Five-to-ten year viability favors sponsors with captive supply chains and adaptive cardiovascular outcomes trial infrastructure. Acquisition target archetype: mid-cap biotechs with Phase II dual-hormone agonist assets and existing relationships with Copenhagen-Medicon Valley contract manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide API Manufacturing Scale-Up | Captive fermentation capacity in Denmark insulates sponsors from single-source contract manufacturer risk. |
| Real-World Evidence Partnership | FDA post-market surveillance pathways enable label expansion through observational data from United States integrated delivery networks. |
| Retail Clinic Integration | CVS Health and Walgreens cardiometabolic screening workflows create direct-to-consumer channels for preventive pharmacological interventions. |
| Dual-Hormone Agonist Pipeline Advancement | GLP-1/GIP combinations open obesity-linked cardiovascular endpoints previously unattainable with single-mechanism agents. |
| Cold Chain Distribution Optimization | Temperature-controlled logistics partnerships with specialty distributors ensure last-mile delivery integrity for patient-home injectables. |
Research Approach
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with formulary database audits and CMS national coverage determination records. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated quantitative assumptions. Bottom-up patient-volume modeling across therapy areas triangulated against top-down pharmaceutical revenue estimates from SEC 10-K disclosures and statutory health insurance reimbursement data.
Bottom-up segmentation analysis modeled treatment line, dosage form, administration route, and regional regulatory cluster variations across the projection horizon. Top-down macroeconomic factors incorporated demographic diabetes prevalence projections and cardiovascular disease incidence trends. CAGRs derived from historical volume-price relationships and forward-looking reimbursement scenario analysis, with sensitivity testing for FDA accelerated approval pathway utilization rates and EMA Medical Device Regulation implementation timelines.
Underlying measurement precision varies by segment; GLP-1 agonist volume estimates carry tighter precision due to manufacturer disclosure practices than SGLT2 inhibitor projections where generic erosion accelerates. Forecasts reflect assumptions regarding regulatory pathway efficiency, reimbursement stability, and peptide API capacity expansion timelines. Periodic stress-testing of base assumptions is recommended against cardiovascular outcomes trial completion rates and CMS national coverage determination precedents for combination regimens.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Pericarditis Market
Cardiovascular
Antihypertensive Market
Cardiovascular
Ischemia Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Stroke Management Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Endocarditis Therapeutics Market