
 Germany Bariatric Surgery Market | 2026-2036
Germany Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Bariatric Surgery Market Foresight
A shortage of certified bariatric surgeons is redrawing competitive dynamics across German metropolitan hospital networks. Medtronic PLC leverages its integrated surgical platform to sustain deep relationships with university-affiliated centers in Berlin and Munich. Johnson & Johnson anchors its position through specialized stapling systems that dominate high-volume gastric bypass workflows. B. Braun Melsungen AG differentiates via comprehensive instrument trays tailored to ambulatory surgical center protocols.
Bariatric surgery encompasses metabolic and gastrointestinal procedures that alter digestive anatomy to induce sustained weight reduction, typically involving laparoscopic ports, stapling devices, and adjustable implant systems. Sleeve gastrectomy now leads procedure type adoption due to shorter operative times and reduced nutritional complication profiles compared to gastric bypass alternatives. Among healthcare facility segments, specialty clinics capture disproportionate margin pools through bundled pricing for pre-operative counseling, surgical intervention, and long-term dietary monitoring services.
MDR compliance requirements enforced by German notified bodies shape device market access timelines and certification costs for manufacturers seeking European commercialization. KBA registration protocols for novel implantable devices add a secondary layer of national scrutiny beyond CE marking standards. Stakeholders must monitor evolving BfArM guidance on reimbursement eligibility for adolescent bariatric procedures, as statutory health insurance coverage determinations will directly shift patient demographic segment growth trajectories across federal states.
Market Dynamics
MDR compliance timelines and KBA registration protocols are compressing device certification cycles while concentrating procurement authority within integrated hospital networks across North Rhine-Westphalia and Bavaria.
Growth Catalysts
- Metabolic disease burden:Morbid obesity prevalence in Baden-Württemberg is expanding eligible patient pools for sleeve gastrectomy procedures.
- MDR harmonization:Streamlined CE marking pathways under updated EU Medical Device Regulation are accelerating market access for novel stapling platforms.
- Ambulatory migration:Bavarian specialty clinics are building dedicated bariatric units with same-day discharge protocols.
Market Restraints
- Titanium alloy supply concentration:German device manufacturers face input cost volatility from concentrated Asian raw material suppliers.
- Surgeon certification scarcity:DGAV certification bottlenecks limit procedural capacity expansion in university hospitals.
- Reimbursement rigidity:Statutory health insurance (GKV) coverage restrictions on adolescent bariatric procedures cap demographic expansion.
Strategic Opportunities
- East German penetration gap:Saxony and Thuringia show underdeveloped bariatric infrastructure relative to western federal states.
- Digital pre-operative pathways:Telehealth-enabled screening protocols are reducing consultation backlogs in rural Bavaria.
- Robot-assisted surgery convergence:Integration of haptic feedback systems with laparoscopic platforms is opening premium procedure segments.
Industry Challenges
- Notified body capacity constraints:BfArM-recognized auditors face backlog pressures extending MDR certification timelines to 18-24 months.
- Legacy EMR integration:Hospital information systems in municipal networks require costly middleware development for bariatric workflow modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Bariatric Surgery Market |
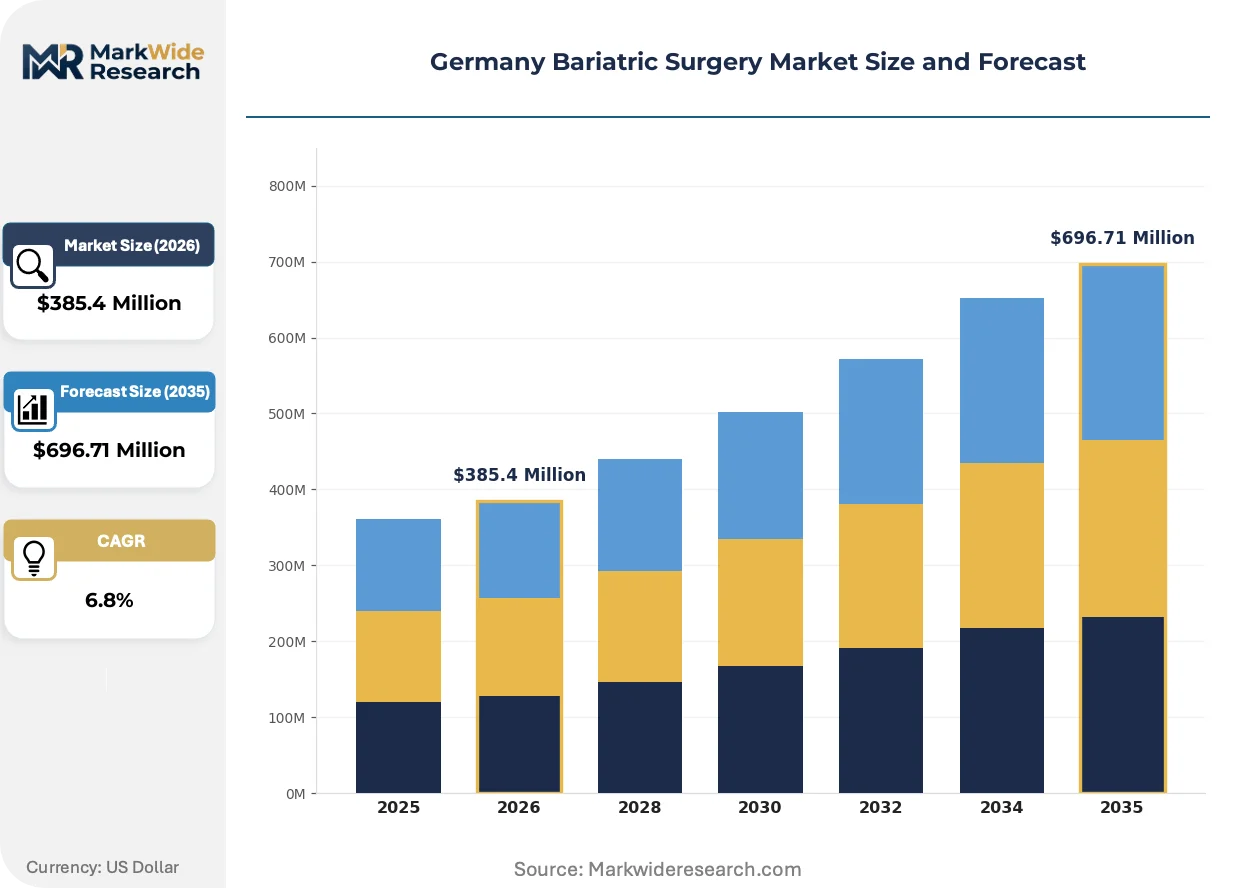
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Banding, Biliopancreatic Diversion Patient Demographic: Adults, Adolescents, Seniors, Morbidly Obese, Overweight Healthcare Facility: Specialty Clinics, Multispecialty Hospitals, Private Hospitals, Ambulatory Surgical Centers Funding Source: Public Insurance, Private Insurance, Self-Pay, Employer-Sponsored Plans |
| Companies Covered | Medtronic PLC, Johnson & Johnson, Apollo Endosurgery, Inc, Olympus Corporation, Intuitive Surgical Inc, MEDIMEX GmbH & Co., Allergan, B. Braun Melsungen AG, USGI Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Bariatric Surgery Market Shifts & Advancements
Device miniaturization and intelligent stapling systems are redefining operative efficiency benchmarks while regulatory digitization compresses compliance overhead for manufacturers.
Single-use powered stapling platforms with integrated tissue sensing are bifurcating the instrument market. University-affiliated centers in Berlin and Munich are adopting these systems for complex revisional procedures. The technology is bifurcating procurement budgets toward disposable platforms and away from reusable instrument trays.
KBA registration protocols for novel implantable devices now mandate real-world performance data submission alongside traditional technical documentation. German notified bodies are enforcing stricter post-market surveillance obligations under MDR Article 83. High-volume gastric bypass centers in Hamburg are restructuring quality management systems to accommodate enhanced vigilance reporting.
Hospital purchasing consortia are consolidating device procurement across multi-site networks. Independent specialty clinics in Baden-Württemberg are losing direct supplier relationships as Rhön-Klinikum and Sana Kliniken centralize contracting authority. This concentration is most visible in stapler and port system categories where annual volume commitments now determine pricing tiers.
Germany Bariatric Surgery Market Segmentation
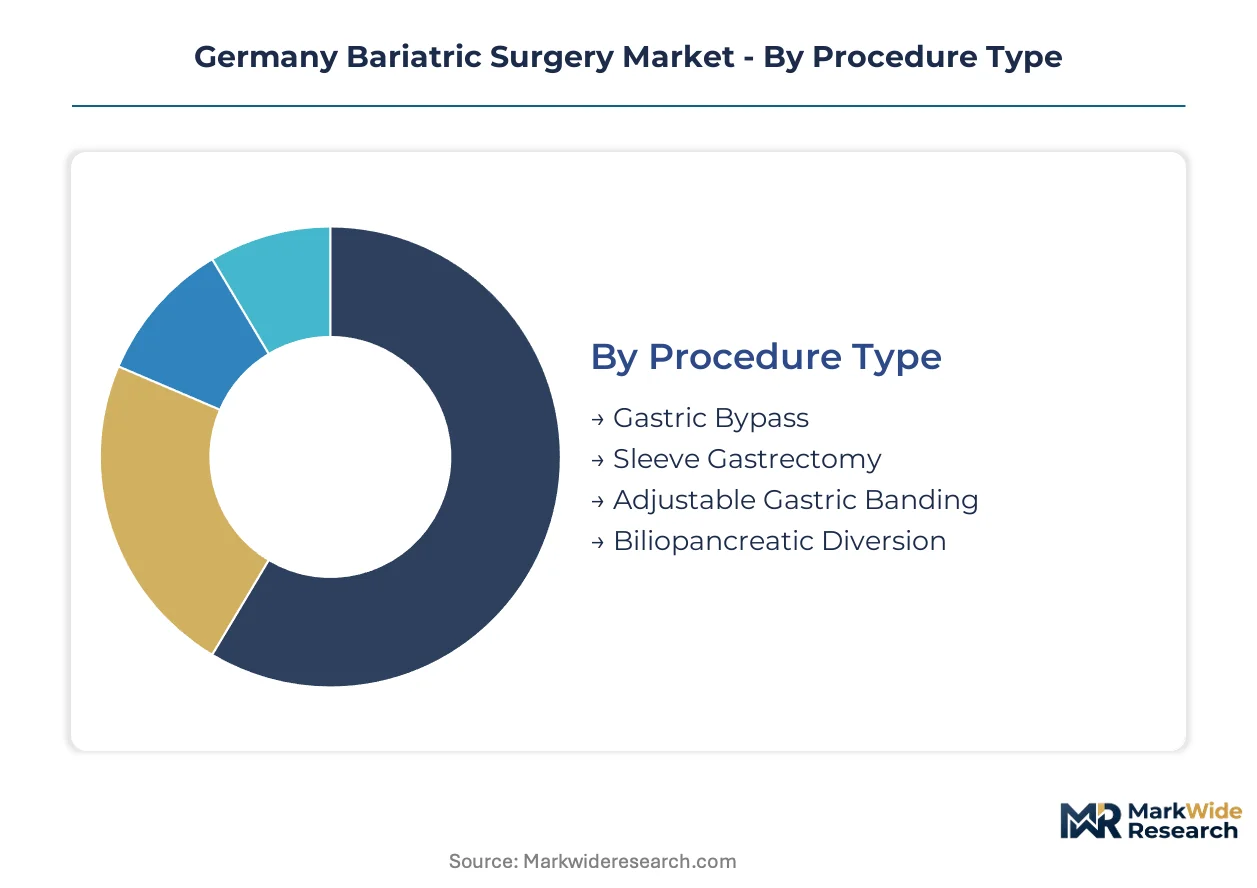
Procedure mix and facility configuration determine reimbursement capture and device procurement cycles across German federal states. Patient demographic stratification shapes statutory health insurance eligibility and pre-operative screening protocols. Understanding segment-level margin distribution enables targeted positioning within Bavaria's integrated care networks and North Rhine-Westphalia's hospital procurement consortia.
Procedure Type:
Margin pools concentrate in laparoscopic stapling platforms and adjustable implant systems, with revisional procedures commanding premium device pricing.
- Sleeve Gastrectomy:Resection of the gastric fundus creates a tubular stomach remnant using linear staplers with tissue reinforcement. Demand concentrates in Baden-Württemberg specialty clinics where same-day discharge protocols reduce per-procedure costs while maintaining outcomes.
- Gastric Bypass:Roux-en-Y reconstruction requires anastomotic stapling and limb measurement precision. University hospitals in Berlin and Munich anchor volume for complex metabolic cases with comorbid diabetes, driving integrated platform procurement from single-source vendors.
- Adjustable Gastric Banding:Silicone implant systems with subcutaneous port access dominate ambulatory revision volumes in Hamburg municipal networks.
- Biliopancreatic Diversion:Malabsorptive anatomy modification serves super-obese patient segments in high-volume academic centers with dedicated nutritional support infrastructure.
Sleeve gastrectomy holds installed capacity. Gastric bypass is rotating up the share rankings.
Patient Demographic:
Cost tier stratification separates statutory-covered adults from self-pay segments seeking expedited access outside GKV queues.
- Morbidly Obese:BMI thresholds above 40 kg/m² or 35 kg/m² with comorbidities define surgical candidacy under German S3 guidelines. North Rhine-Westphalia health insurers prioritize this segment for bundled reimbursement contracts with integrated care networks.
- Adults:Ages 18-65 represent core procedural volume across all facility types, with pre-operative screening backlogs longest in rural Bavaria.
- Adolescents:Ages 12-17 face restrictive BfArM guidance on metabolic surgery eligibility, capping segment expansion pending updated evidence reviews.
- Seniors:Patients over 65 require cardiovascular clearance protocols that extend pre-operative timelines in university hospital settings.
- Overweight:BMI 25-30 kg/m² patients fall outside surgical indications, redirecting toward medical weight management programs.
Morbidly obese captures reimbursement density. Adults is climbing the fastest.
Healthcare Facility:
Application focus determines device specification requirements, from high-complexity revisional suites to streamlined ambulatory protocols.
- Specialty Clinics:Dedicated bariatric units in Baden-Württemberg coordinate pre-operative counseling, surgical intervention, and long-term dietary monitoring under bundled pricing structures.
- Multispecialty Hospitals:Rhön-Klinikum and Sana Kliniken networks centralize procurement authority across stapler and port system categories through annual volume commitments.
- Private Hospitals:Self-pay patient segments drive shorter wait times and premium device selection in Berlin and Munich metropolitan markets.
- Ambulatory Surgical Centers:Bavarian same-day discharge protocols require compact instrument trays and rapid sterilization turnaround.
Specialty clinics command margin concentration. Ambulatory surgical centers are gaining share fastest.
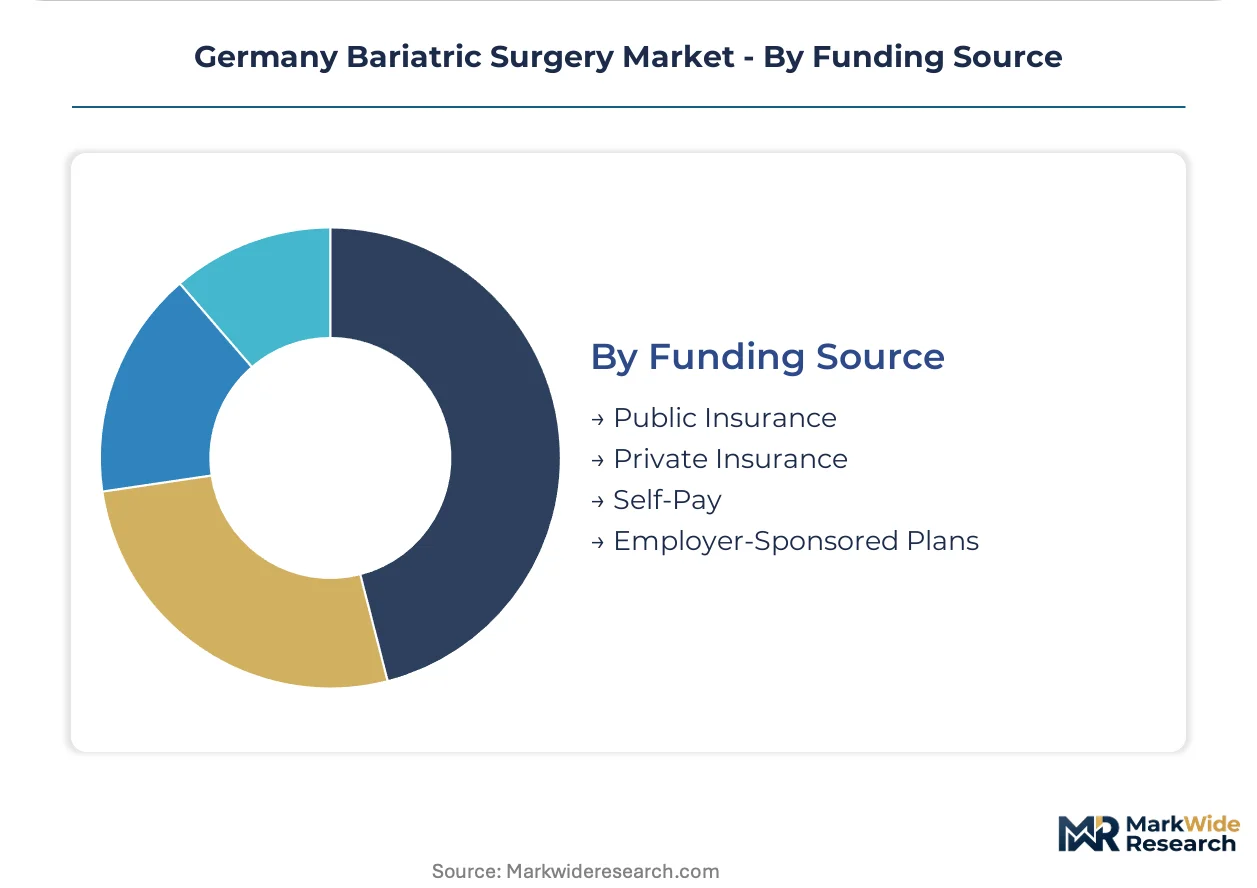
Funding Source:
Customer type differentiation shapes pricing acceptance and payment cycle duration across statutory and private channels.
- Public Insurance:GKV funds approximately 85% of bariatric procedures through diagnosis-related group reimbursement, with coverage contingent on documented failed conservative therapy attempts.
- Private Insurance:PKV patients in Hamburg and Frankfurt access expedited scheduling and premium implant selections outside statutory fee schedules.
- Self-Pay:Direct payment segments concentrate in cosmetic-adjacent procedures and international patient flows to Munich university centers.
- Employer-Sponsored Plans:Corporate health schemes for automotive and chemical sector workforces in Baden-Württemberg fund preventive metabolic interventions.
Public insurance anchors volume scale. Private insurance is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procedure mix varies sharply across German federal states, with western regions favoring sleeve gastrectomy in ambulatory settings while eastern states concentrate complex revisional cases in university hospitals.
Bavaria
Specialty clinics in Munich and Nuremberg deploy same-day discharge protocols for sleeve gastrectomy, reducing per-procedure costs. BfArM guidance on metabolic surgery eligibility shapes patient screening criteria. The Munich metropolitan cluster anchors premium device procurement for robot-assisted procedures.
North Rhine-Westphalia
Rhön-Klinikum and Sana Kliniken networks centralize stapler and port system procurement through annual volume commitments. KBA registration protocols compress certification timelines for novel implantable devices. The Cologne-Düsseldorf corridor concentrates GKV bundled reimbursement contracts with integrated care networks.
Baden-Württemberg
Automotive and chemical sector employer-sponsored plans fund preventive metabolic interventions for workforce populations. DGAV certification requirements limit procedural capacity expansion in Stuttgart university hospitals. The Karlsruhe-Mannheim region hosts dedicated bariatric units with bundled pricing for pre-operative counseling and long-term monitoring.
Berlin-Brandenburg
University-affiliated centers anchor volume for complex metabolic cases with comorbid diabetes. MDR compliance timelines enforced by German notified bodies accelerate market access for novel stapling platforms. The Berlin metropolitan market attracts self-pay patient segments seeking expedited scheduling outside GKV queues.
Hamburg
Municipal hospital networks restructure quality management systems to accommodate enhanced MDR Article 83 vigilance reporting. Adjustable gastric banding implant systems dominate ambulatory revision volumes. The Hamburg cluster serves as a gateway for international patient flows to German university centers.
Germany Bariatric Surgery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with university-affiliated procurement relationships and ambulatory surgical center contracts determining competitive positioning. The vendor base separates into three archetypes: diversified surgical platform providers, specialized stapling system manufacturers, and regional instrument tray suppliers. Consolidation pressure intensifies as hospital purchasing consortia centralize contracting authority across multi-site networks. M&A activity targets ambulatory-focused technology portfolios, while strategic partnerships address legacy EMR integration requirements.
Among diversified surgical platform providers, Medtronic PLC and Johnson & Johnson occupy positions anchoring integrated system procurement at high-volume academic centers. B. Braun Melsungen AG exemplifies the regional instrument tray specialist archetype, with its German corporate structure aligning with Baden-Württemberg ambulatory protocol requirements. These three entities represent distinct competitive vectors: platform breadth, specialized workflow dominance, and regional service integration.
| Leading Market Players |
|---|
| Medtronic PLC |
| Johnson & Johnson |
| Apollo Endosurgery, Inc |
| Olympus Corporation |
| Intuitive Surgical Inc |
| MEDIMEX GmbH & Co. |
| Allergan |
| B. Braun Melsungen AG |
| USGI Medical |
| Others |
Supply & Pricing Matrix
Installed capacity utilization at German university hospitals shapes procurement leverage across stapling platform categories, compressing price floors for mid-tier instrument suppliers while concentrating volume discounts within Rhön-Klinikum and Sana Kliniken purchasing consortia. KBA registration timelines and MDR compliance costs feed directly into manufacturer pricing strategies, with notified body backlog extending certification overhead to device cost structures.
Pricing Analysis
Annual volume commitments dominate contract structures across German hospital networks, with multi-year offtake agreements securing preferential pricing for integrated surgical platforms. Price differentiation hinges on CE marking tier under MDR Article 83 and after-sales service bundling for revisional procedure support. Cost compression in standard stapler categories is intensifying because Asian titanium suppliers face input volatility. Municipal hospital procurement committees exhibit highest price sensitivity, while private Berlin and Munich centers prioritize premium device selection.
Supply Chain Analysis
China and Japan anchor titanium alloy refining for German device manufacturers, with South Korea supplying specialized laparoscopic instrumentation. Raw material dependencies center on medical-grade titanium, surgical stainless steel, and biocompatible silicone polymers. Single-source vulnerability concentrates in Asian smelter capacity for implant-grade alloys. Distribution runs through hospital purchasing consortia and GPO contracts, with ambulatory surgical centers sourcing via regional instrument tray specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in German bariatric surgery is reaching an inflection as robotic-assisted workflows demand interoperability between haptic feedback systems and legacy hospital information infrastructure.
For Market Incumbents: Secure DGAV certification pathways for surgeon training programs to defend against emerging ambulatory-focused competitors. Deepen backward integration into titanium alloy sourcing to offset Asian supplier volatility. Hospital purchasing consortium consolidation threatens direct supplier relationships; channel control through exclusive service contracts represents the critical defensive lever. For New Entrants and Emerging Players: MDR streamlined assessment routes for Class IIa implantable devices offer fastest market access validation. East German federal states present white-space opportunity given underdeveloped bariatric infrastructure relative to western regions. Telehealth-enabled pre-operative screening protocols in rural Bavaria provide differentiated go-to-market positioning outside established procurement networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty clinic operators with bundled pricing for long-term dietary monitoring services. Long-term viability favors platforms with software companion development capabilities and reimbursement strategy expertise. Watch BfArM guidance updates on adolescent metabolic surgery eligibility as inflection signal for demographic expansion trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| MDR CE Marking Pathway | Accelerates market access for novel stapling platforms under notified body streamlined assessment. |
| Hospital System Partnership | Secures annual volume commitments with Rhön-Klinikum and Sana Kliniken procurement consortia. |
| Software Companion Development | Enables EMR integration for bariatric workflow modules in municipal hospital networks. |
| Reimbursement Strategy | Aligns device positioning with GKV bundled contracts and BfArM coverage determinations. |
| Backward Integration | Reduces titanium alloy cost volatility from concentrated Asian raw material suppliers. |
Research Methodology
Operator-level perspectives from bariatric surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from BfArM guidance documents, KBA device registration databases, DGAV certification records, and statutory health insurance reimbursement schedules. Bottom-up procedure volume estimates triangulated against top-down device shipment data across federal state clusters.
Sensitivity analysis tested forecast robustness across alternative MDR compliance timeline scenarios and surgeon certification expansion rates. Segmentation dimensions modeled include procedure type, patient demographic stratification, healthcare facility configuration, and funding source channel. CAGRs were derived from fitted growth curves calibrated to historical surgical volume trajectories and procurement cycle observations. Forecast inputs incorporated KBA registration pipeline visibility and integrated care network expansion plans.
Decision-makers should treat outputs as directional under assumptions of stable GKV reimbursement structures and notified body capacity constraints; material deviation in BfArM adolescent surgery guidance or titanium supply disruptions would warrant model refresh. Forecasts reflect documented base-case assumptions regarding MDR harmonization progress and ambulatory migration rates. Recalibration cycles align with material shifts in regulatory compliance timelines and hospital procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
India Bariatric Surgery Devices Market