
 Asia Pacific Radiopharmaceuticals Market | 2026-2036
Asia Pacific Radiopharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Radiopharmaceuticals Market Analytics
Australian cyclotron facilities and Japan's domestic isotope production network is pivoting toward therapeutic radioisotopes to reduce import dependence on North American and European suppliers. Nihon Medi-Physics Co., Ltd. leverages its domestic distribution network to dominate hospital channel access across Japan. China Isotope & Radiation Corp. anchors government-backed capacity expansion for technetium-99m generators and lutetium-177 therapies. GE HealthCare competes through integrated cyclotron-to-pharmacy systems that streamline cold chain logistics.
Radiopharmaceuticals comprise biologically active molecules labeled with radioactive isotopes for diagnostic imaging or targeted radionuclide therapy, requiring half-life-matched production, sterile synthesis under GMP conditions, and real-time quality control for specific activity and radiochemical purity. Diagnostic radiopharmaceuticals sustain the largest revenue pool due to high procedure volumes in PET-CT and SPECT imaging, while therapeutic radiopharmaceuticals represent the fastest-expanding margin segment driven by lutetium-177 and actinium-225 alpha-emitter pipelines. Hospitals occupy the dominant end-user channel, though specialty clinics are capturing share in thyroid and prostate cancer theranostics.
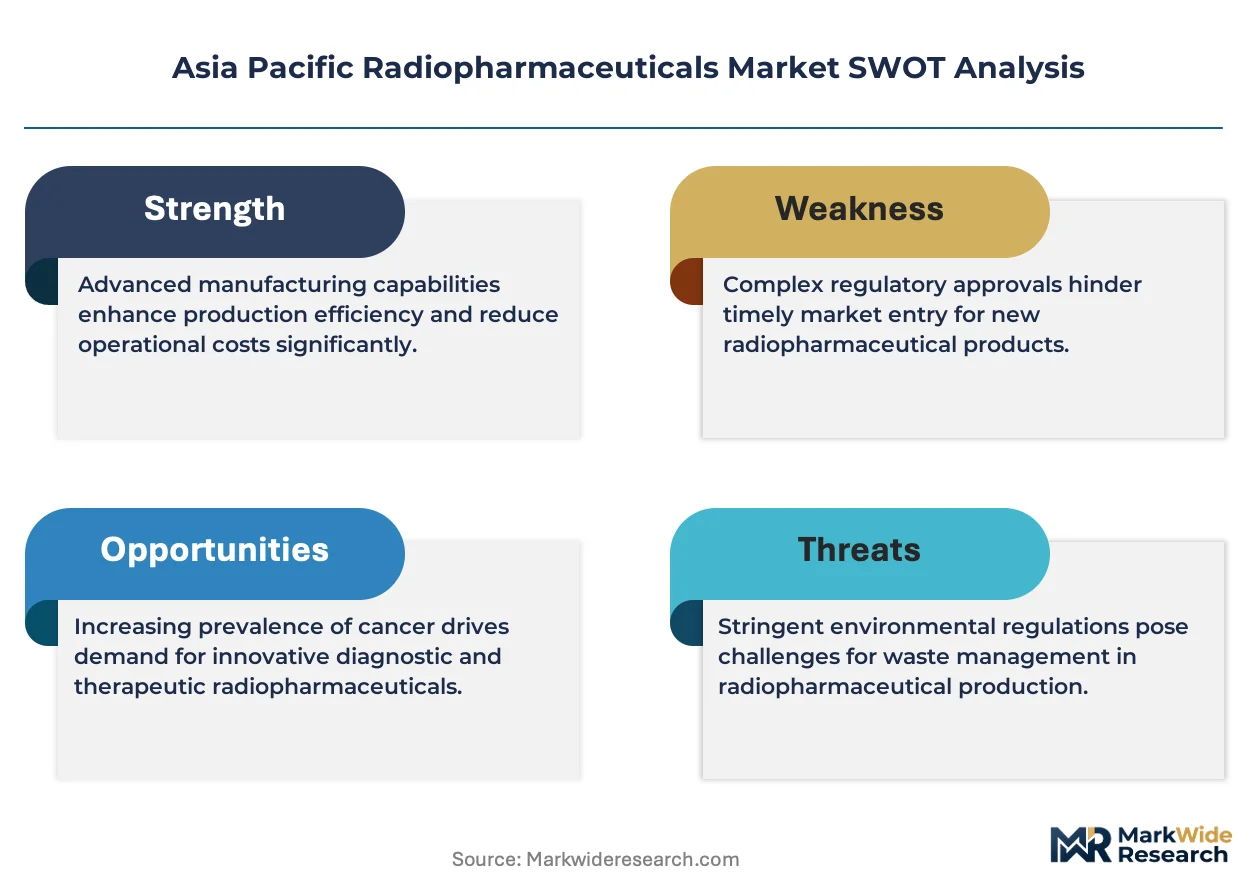
Japan's PMDA, Australia's TGA, and China's NMPA enforce divergent approval pathways for novel radioisotopes, creating complexity for multinational sponsors seeking simultaneous market entry. Australia's ARPANSA and Japan's METI coordinate isotope import quotas and domestic reactor scheduling, directly constraining supply availability for gallium-68 and iodine-131 formulations. Stakeholders must monitor regulatory harmonization progress between these agencies and reactor decommissioning timelines that threaten base isotope supply.
Market Dynamics
Asia Pacific radiopharmaceutical supply chains pivot on reactor decommissioning schedules across Australia and Japan, forcing domestic isotope infrastructure investment to displace historical import dependence on European and North American molybdenum-99 suppliers.
Growth Catalysts
- Domestic Reactor Investment:Australia's OPAL reactor expansion and Japan's JMTR refurbishment programs under METI coordination are securing gallium-68 and lutetium-177 supply for hospital networks without cross-border cold chain exposure.
- Theranostics Pipeline Maturation:Prostate cancer imaging centers across South Korea and China are integrating PSMA-targeted diagnostics with subsequent lutetium-177 therapy, creating paired revenue streams per patient pathway.
- PMDA Accelerated Review Pathway:Japan's novel radiopharmaceutical designation reduces approval timelines for alpha-emitter therapies, attracting sponsor investment in actinium-225 conjugate development.
Market Restraints
- Molybdenum-99 Decay Loss:Six-hour half-life of technetium-99m parent isotope necessitates geographic proximity between reactor and generator facility, constraining supply radius to 500 kilometers for viable clinical use.
- Cyclotron Capital Intensity:30 MeV proton accelerator installation exceeds USD 15 million with shielding requirements, limiting production capacity to government-backed facilities or consolidated hospital consortia.
- Divergent NMPA-TGA-PMDA Standards:China's pharmacopoeial radiochemical purity thresholds exceed Australian TGA specifications for iodine-131 capsules, forcing dual formulation development or market exclusion.
Strategic Opportunities
- Southeast Asia Greenfield Penetration:Thailand and Vietnam hospital networks lack domestic tracer production, creating first-mover advantage for regional distribution hubs with 4-hour flight coverage.
- Alpha-Emitter Therapeutic Expansion:Actinium-225 and lead-212 conjugates for metastatic melanoma and glioblastoma represent unaddressed oncology indications beyond current lutetium-177 prostate dominance.
- Centralized Pharmacy Models:GE HealthCare and IBA are deploying containerized radiopharmacy units that co-locate synthesis and quality control within hospital campuses, compressing logistics risk.
Industry Challenges
- Radiochemist Talent Scarcity:GMP-qualified synthesis technicians with hot cell experience are concentrated in Japan and Australia, leaving Chinese and South Korean facilities dependent on expatriate training programs.
- Batch Release Timeline Compression:Sterility and endotoxin testing for patient-specific doses must complete within isotope half-life windows, creating quality control bottlenecks at high-throughput centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Radiopharmaceuticals Market |
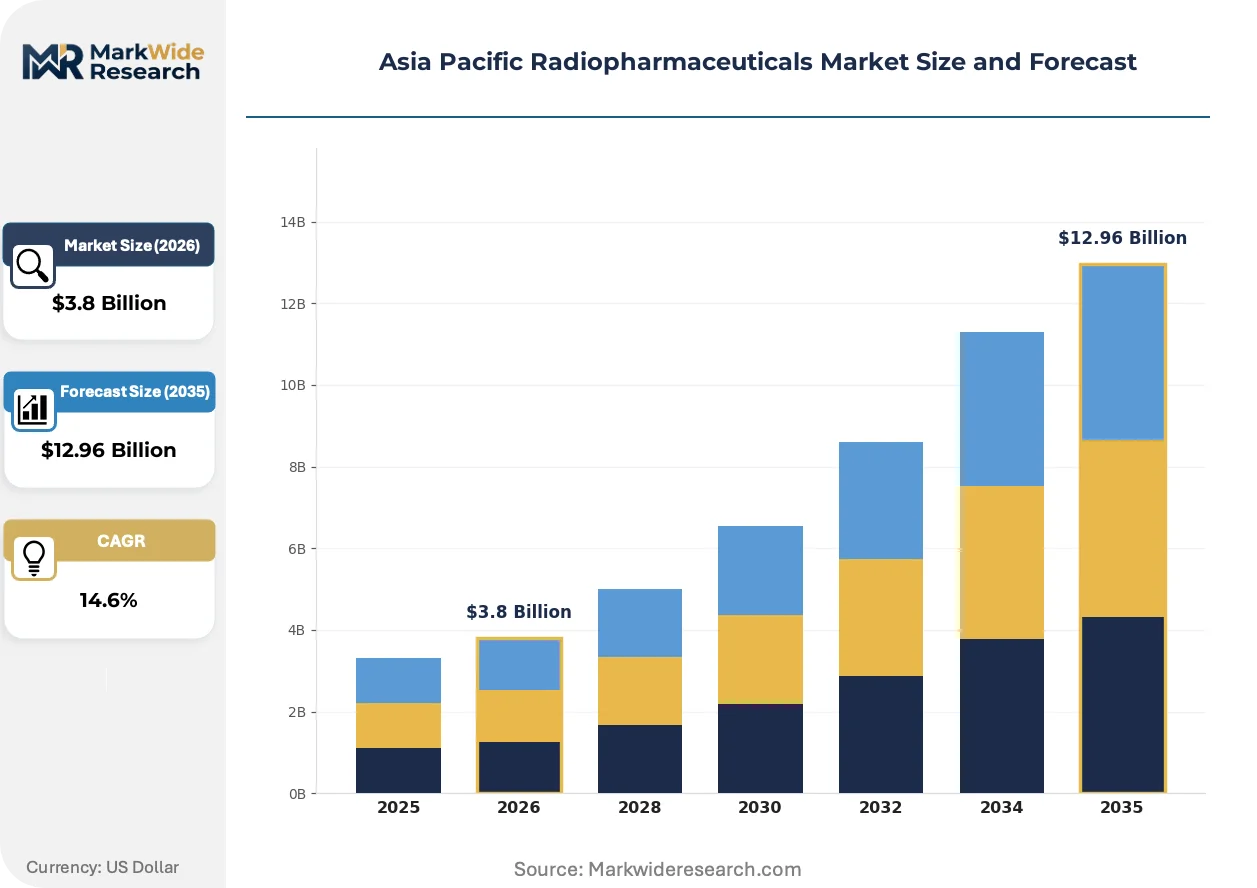
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Radiopharmaceuticals, Therapeutic Radiopharmaceuticals, Generator-based Radiopharmaceuticals, Cold Kit Radiopharmaceuticals End User: Hospitals, Diagnostic Centers, Research Institutions, Specialty Clinics Application: Oncology, Cardiology, Neurology, Endocrinology Distribution Channel: Direct Sales, Distributors, Online Retailers, Others |
| Companies Covered | Nihon Medi-Physics Co., Ltd., Fujifilm Corporation, China Isotope & Radiation Corp., ANSTO, Curium, GE HealthCare, Siemens Healthineers, Cardinal Health, Bracco Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Radiopharmaceuticals Market Evolving Landscape
Artificial intelligence reconstruction algorithms and solid-target cyclotron systems are compressing production-to-injection timelines while expanding tracer accessibility beyond metropolitan oncology centers.
Positron emission tomography tracers labeled with fluorine-18 and gallium-68 are converging with deep learning-based attenuation correction, enabling quantitative SUV measurements without CT radiation dose. Japanese university hospitals are adopting these hybrid workflows for Alzheimer's amyloid imaging, reducing scan time from 90 to 30 minutes. The structural consequence is displacement of traditional SPECT myocardial perfusion protocols in cardiology departments across Tokyo and Osaka.
Australia's ARPANSA revised its Code of Practice for Radiation Protection in Medical Applications, mandating real-time environmental monitoring for therapeutic isotope dispensing. This regulatory revision forces hospital nuclear medicine departments to install continuous air sampling systems and upgrade waste storage shielding. Facilities in Sydney and Melbourne are responding by consolidating high-dose lutetium-177 administration into dedicated theranotics suites rather than general infusion bays.
Hospital procurement committees across South Korea and China are unbundling radiopharmaceutical supply from imaging equipment leases, separating cyclotron maintenance contracts from tracer volume commitments. This purchasing pattern shift disrupts GE HealthCare's historical bundled pricing model and opens tender competition from Nihon Medi-Physics and China Isotope & Radiation Corp. The disaggregation is most visible in Shanghai and Seoul, where public hospital networks now issue standalone radiopharmacy service RFPs.
Asia Pacific Radiopharmaceuticals Market Segmentation
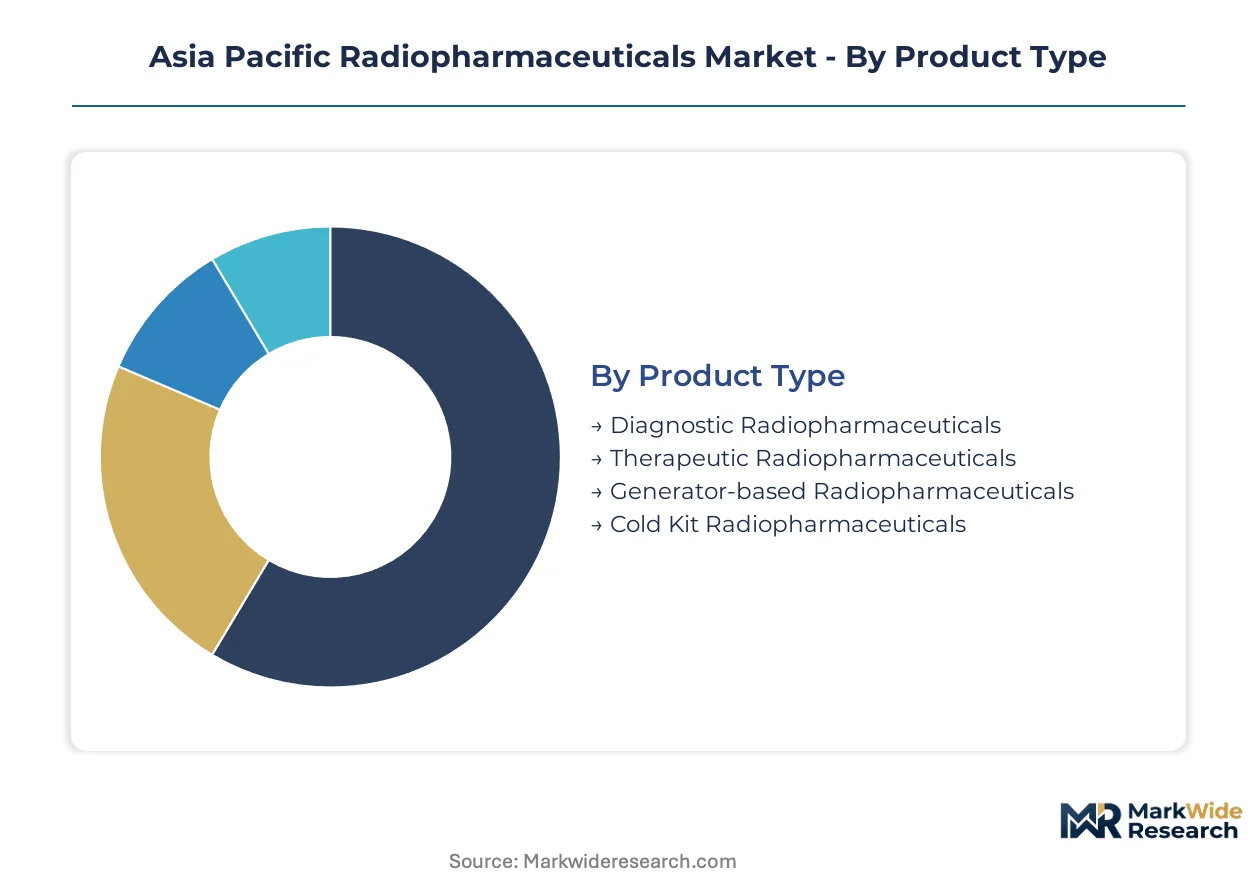
Radiopharmaceutical procurement cycles in Asia Pacific hospitals refresh every 3-5 years as imaging equipment upgrades and therapeutic protocols evolve. Segmentation reveals how supply chain investments align with procedure volume concentration and margin expansion priorities across Japan, Australia, and South Korea.
Product Type:
Replacement cycles for tracer production infrastructure vary sharply by half-life requirements and capital intensity, driving divergent upgrade timelines across hospital networks.
- Diagnostic Radiopharmaceuticals:Short-lived PET tracers including fluorine-18 FDG and gallium-68 PSMA conjugates require on-site cyclotron or generator infrastructure. Japanese university hospitals in Tokyo and Osaka deploy these for oncology staging and Alzheimer's amyloid imaging, with procurement tied to PET-CT scanner replacement cycles every 7-10 years.
- Therapeutic Radiopharmaceuticals:Lutetium-177 and iodine-131 formulations deliver targeted radionuclide therapy for neuroendocrine tumors and thyroid malignancies. Australia's ARPANSA-mandated shielding upgrades are forcing Sydney and Melbourne hospitals to consolidate high-dose administration into dedicated theranostics suites, accelerating facility renovation spend.
- Generator-based Radiopharmaceuticals:Technetium-99m derived from molybdenum-99 generators dominates cardiac perfusion and bone scan procedures across China's tier-2 cities.
- Cold Kit Radiopharmaceuticals:Pre-formulated reagent kits for instant labeling with generator-produced isotopes reduce synthesis complexity for smaller South Korean diagnostic centers.
Volume placements concentrate in Diagnostic Radiopharmaceuticals; the faster expansion belongs to Therapeutic Radiopharmaceuticals.
End User:
Capital deployment patterns across customer types reflect reimbursement density and regulatory complexity gradients from metropolitan to regional markets.
- Hospitals:Integrated nuclear medicine departments with in-house cyclotron or radiopharmacy infrastructure capture the highest procedure volumes. Japan's PMDA-accredited centers in Nagoya and Fukuoka anchor regional referral networks for complex theranostics.
- Diagnostic Centers:Standalone PET-CT facilities in China's Yangtze River Delta operate on equipment lease-plus-tracer bundle models, though procurement committees in Shanghai are increasingly unbundling these contracts.
- Research Institutions:Australia's ANSTO and Japan's domestic isotope programs supply academic medical centers developing novel alpha-emitter conjugates.
- Specialty Clinics:Thyroid and prostate cancer theranostics hubs in Seoul and Singapore concentrate patient-specific dosing capabilities outside general hospital infrastructure.
Revenue concentration sits with Hospitals; Specialty Clinics are climbing the fastest as theranostics carve out dedicated channels.
Application:
Procedure volume distribution across clinical domains tracks disease burden demographics and reimbursement pathway maturity in each national market.
- Oncology:PSMA-targeted imaging paired with lutetium-177 therapy dominates new protocol adoption. South Korean prostate cancer centers are integrating paired diagnostic-therapeutic workflows, creating repeat patient touchpoints per disease pathway.
- Cardiology:Myocardial perfusion imaging with technetium-99m sestamibi sustains high baseline volumes but faces displacement from coronary CT angiography in Australian cardiology departments.
- Neurology:Amyloid PET for Alzheimer's diagnosis expands in Japan's aging demographic, with PMDA reimbursement decisions driving scanner placement in dementia specialty centers.
- Endocrinology:Iodine-131 therapy for hyperthyroidism and differentiated thyroid cancer maintains steady demand across China's provincial hospital networks.
Procedure density peaks in Oncology; Neurology is gaining share fastest on demographic tailwinds and diagnostic protocol expansion.
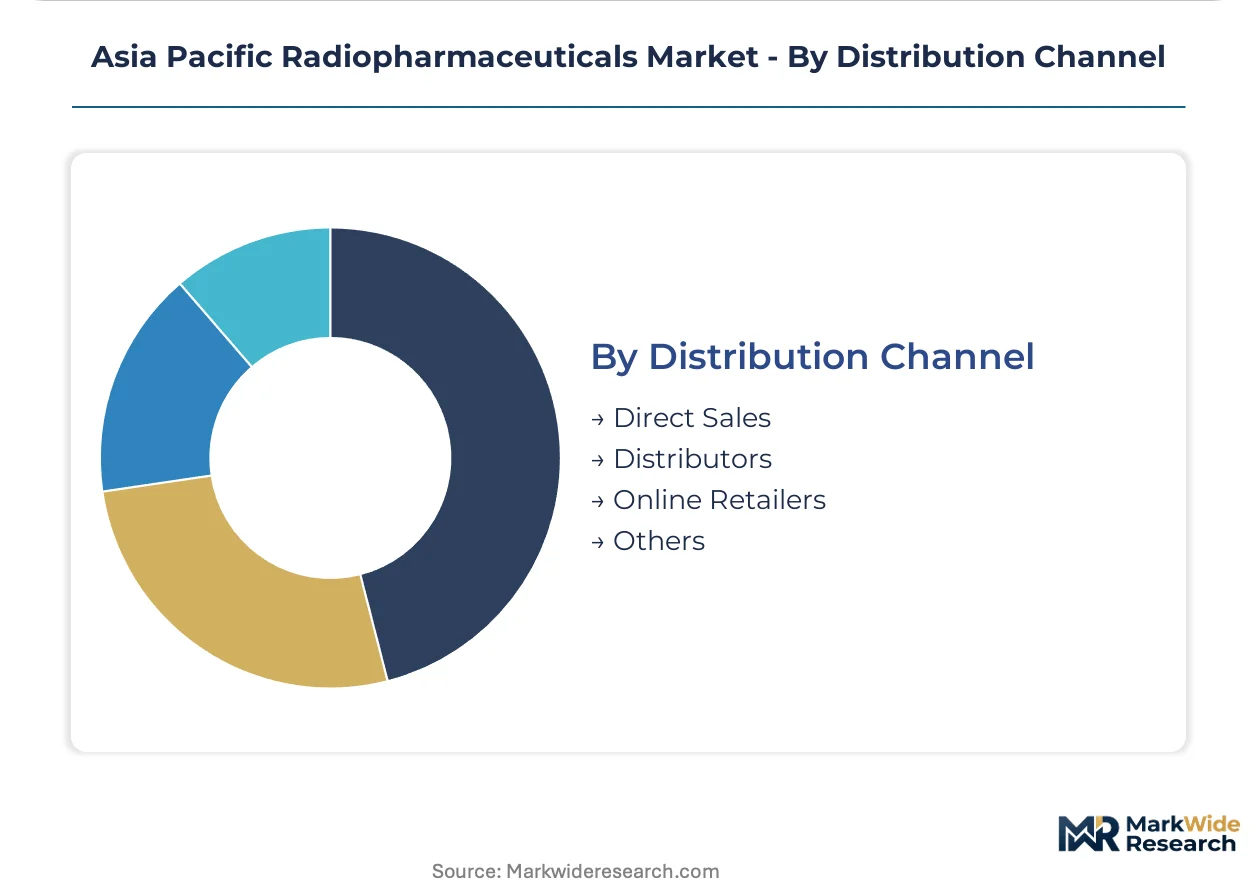
Distribution Channel:
Logistics configuration choices reflect isotope half-life constraints and cold chain reliability requirements that vary by tracer category.
- Direct Sales:Cyclotron manufacturers and integrated radiopharmacy operators including GE HealthCare deploy containerized synthesis units directly to hospital campuses, compressing production-to-injection timelines for gallium-68 formulations.
- Distributors:Nihon Medi-Physics Co., Ltd. leverages its domestic Japanese network to manage generator delivery and waste collection for technetium-99m customers outside metropolitan cyclotron coverage.
- Online Retailers:Cold kit reagents and calibration sources for research use move through specialized nuclear medicine supply portals with radioactive materials shipping licenses.
- Others:Government procurement frameworks in China channel generator supply through China Isotope & Radiation Corp. under centralized hospital network tenders.
Channel share concentrates in Direct Sales for short-half-life tracers; Distributors retain structural role for generator logistics and regional coverage extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic reactor infrastructure across Australia and Japan anchors isotope supply security for the Asia Pacific radiopharmaceuticals market. Australia's OPAL facility and Japan's JMTR refurbishment programs displace historical import dependence on European molybdenum-99 suppliers. Regional procurement committees now prioritize geographic proximity between production and clinical use.
Japan
Tokyo and Osaka university hospitals drive PSMA-targeted imaging volumes for prostate cancer staging. PMDA's novel radiopharmaceutical designation compresses approval timelines for alpha-emitter therapies. Nagoya's Chubu region hosts concentrated cyclotron networks supplying fluorine-18 FDG to dementia specialty centers.
Australia
Sydney and Melbourne hospitals are consolidating lutetium-177 administration into dedicated theranostics suites following ARPANSA shielding mandates. ANSTO's Lucas Heights reactor secures gallium-68 supply for metropolitan PET-CT networks. Queensland's emerging diagnostic centers lack domestic tracer production, creating distribution hub opportunities.
China
Shanghai's Yangtze River Delta hospitals are unbundling radiopharmaceutical supply from imaging equipment leases. NMPA pharmacopoeial standards for radiochemical purity exceed regional counterparts, forcing dual formulation development. Provincial hospital networks in tier-2 cities sustain technetium-99m generator demand for cardiac and bone imaging.
South Korea
Seoul prostate cancer centers are integrating paired diagnostic-therapeutic workflows creating repeat patient touchpoints. MFDS reimbursement pathways for theranostics are maturing alongside domestic cyclotron investment. Busan-Ulsan's manufacturing corridor hosts emerging radiopharmacy service providers.
Asia Pacific Radiopharmaceuticals Market Competitive Landscape
Global majors compete with regional champions across distribution network density and reactor access. The market structures around three tiers: integrated cyclotron-to-pharmacy system operators, domestic isotope infrastructure custodians, and specialized theranostics service providers. Consolidation pressures favor scale-driven players with captive reactor supply or hospital campus co-location capabilities. Dominant competitive moves include government-backed reactor expansion programs and containerized radiopharmacy unit deployment.
Within the domestic infrastructure tier, Nihon Medi-Physics Co., Ltd. and China Isotope & Radiation Corp. exemplify regional champions leveraging government-coordinated supply networks. GE HealthCare occupies a position among integrated system operators with cyclotron-to-pharmacy logistics capabilities. These three anchors represent divergent strategic archetypes: Japanese hospital channel dominance, Chinese state-backed capacity expansion, and multinational equipment-service integration.
| Leading Market Players |
|---|
| Nihon Medi-Physics Co., Ltd. |
| Fujifilm Corporation |
| China Isotope & Radiation Corp. |
| ANSTO |
| Curium |
| GE HealthCare |
| Siemens Healthineers |
| Cardinal Health |
| Bracco Group |
| Others |
Value Network & Pricing Analysis
Sovereign-backed reactor operators including ANSTO and Japan's domestic isotope programs anchor supply security while exerting pricing discipline through captive production capacity. Government-coordinated infrastructure investment displaces import-dependent procurement models, compressing margin capture by third-party distributors and reshaping hospital purchasing power across the Asia Pacific region.
Pricing Analysis
Equipment lease-plus-tracer bundling historically dominated hospital procurement in South Korea and China, though unbundling trends in Shanghai and Seoul now separate cyclotron maintenance from tracer volume commitments. Price differentiation rests on reactor proximity and cold chain reliability, with metropolitan centers commanding premiums for gallium-68 formulations while tier-2 cities absorb higher logistics costs for generator-based technetium-99m. Cost compression in diagnostic tracers is intensifying as procurement committees issue standalone radiopharmacy RFPs, eroding integrated vendor margins. Public hospital networks exhibit highest price sensitivity due to centralized tender processes, while private oncology centers in Tokyo and Singapore prioritize supply security over unit cost.
Supply Chain Analysis
Direct-to-hospital containerized radiopharmacy units from GE HealthCare and IBA compress production-to-injection timelines for short-half-life tracers. Geographic supply concentration centers on Australia's OPAL reactor, Japan's JMTR refurbishment network, and China's state-backed isotope expansion programs. Raw material dependencies include enriched molybdenum-99 targets, high-purity lutetium-177 feedstock, and specialized hot cell shielding components. Single-source vulnerability threatens gallium-68 and actinium-225 availability as reactor decommissioning schedules across the region outpace replacement capacity. Distribution runs through hybrid models: direct sales for cyclotron-linked tracers, Nihon Medi-Physics' domestic Japanese network for generator logistics, and China Isotope & Radiation Corp.'s government procurement frameworks for provincial hospital supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around scale-driven players with captive reactor access or hospital campus co-location capabilities, as cyclotron capital intensity exceeding USD 15 million forces smaller operators toward exit or acquisition.
For Market Incumbents: Hedge against unbundling-driven margin erosion by securing long-term generator supply contracts with tier-2 Chinese hospitals before Nihon Medi-Physics and China Isotope & Radiation Corp. consolidate regional distribution. Expand containerized radiopharmacy deployment to Queensland and Vietnam where domestic tracer production gaps create first-mover co-location opportunities. Priority defensive investment targets backward integration into lutetium-177 and actinium-225 production to offset import dependence on North American alpha-emitter suppliers. For New Entrants and Emerging Players: Begin with Southeast Asia greenfield penetration in Thailand and Vietnam hospital networks lacking domestic cyclotron infrastructure, establishing regional distribution hubs with 4-hour flight coverage. Target specialty clinic channels in Seoul and Singapore for thyroid and prostate cancer theranostics, where dedicated patient-specific dosing capabilities operate outside general hospital procurement frameworks. Go-to-market angle emphasizes compressed logistics risk through centralized pharmacy partnerships with emerging Busan-Ulsan radiopharmacy service providers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap radiopharmacy operators with PMDA or TGA accreditation but limited reactor access in Japan and Australia, as capital intensity pressures force consolidation. Long-term viability hinges on 5-10 year positioning around therapeutic isotope pipelines, particularly lutetium-177 and actinium-225 conjugates displacing diagnostic-dominant revenue pools. Signal to watch: regulatory harmonization progress between PMDA, TGA, and NMPA enabling simultaneous multi-country market entry for novel radioisotopes.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Reactor Capacity Expansion | Australia's OPAL expansion and Japan's JMTR refurbishment secure gallium-68 supply without cross-border cold chain exposure. |
| Containerized Radiopharmacy Deployment | GE HealthCare and IBA co-locate synthesis and quality control within hospital campuses, compressing logistics risk for short-half-life tracers. |
| Theranostics Pipeline Diversification | Actinium-225 and lead-212 conjugates for metastatic melanoma expand oncology indications beyond lutetium-177 prostate dominance. |
| Regulatory Harmonization Investment | Alignment between PMDA, TGA, and NMPA approval pathways reduces dual formulation development burdens for multinational sponsors. |
| Radiochemist Talent Development | Expatriate training programs address GMP-qualified synthesis technician scarcity concentrated in Japan and Australia. |
Research Methodology
Multi-period observation of reactor decommissioning schedules, cyclotron installation pipelines, and PMDA-TGA-NMPA regulatory filing timelines anchored the trend analysis, supplemented by interviews with nuclear medicine department heads, hospital procurement managers, radiopharmacy operations directors, and isotope infrastructure program officers. Secondary validation drew from ARPANSA reactor utilization reports, METI isotope supply coordination disclosures, NMPA pharmacopoeial standard updates, and hospital procurement database extracts across Tokyo, Shanghai, Sydney, and Seoul. Bottom-up procedure volume modeling triangulated against top-down reactor capacity and isotope production forecasts.
Segment-weighting applied differential growth assumptions across diagnostic versus therapeutic radiopharmaceuticals, hospital versus specialty clinic end users, and direct sales versus distributor channels throughout the forecast period. Modeled dimensions included product type, end-user category, clinical application, and distribution channel structure. CAGRs derived from isotope half-life-constrained supply elasticity, imaging equipment replacement cycles, and reimbursement pathway maturation trajectories. Industry-specific inputs incorporated PMDA accelerated review pathway utilization rates and ARPANSA shielding mandate compliance timelines.
Underlying measurement precision varies by segment; therapeutic radiopharmaceuticals and alpha-emitter pipelines carry tighter precision than diagnostic tracer volumes given earlier-stage pipeline visibility. Forecasts reflect assumptions regarding regulatory harmonization progress, reactor refurbishment schedule adherence, and radiochemist training program throughput. Periodic stress-testing of base assumptions is recommended, particularly around actinium-225 supply security and NMPA-TGA-PMDA standard convergence timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Intelligent Pills Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Global Chickenpox Vaccine Market