
 Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market | 2026-2036
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market Foresight
Biosimilar-grade insulin formulations is unwinding price compression across European tender markets. Novo Nordisk leverages its integrated active pharmaceutical ingredient production to sustain margin resilience in GLP-1 agonist supply. Sanofi anchors its position through long-acting insulin portfolios, while Eli Lilly competes via differentiated dual GIP/GLP-1 receptor agonist technology. AstraZeneca navigates payer negotiations with SGLT2-GLP-1 combination positioning.
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist comprise recombinant human insulin, insulin analogs with modified amino acid sequences, and GLP-1 receptor agonists such as liraglutide and semaglutide that enhance glucose-dependent insulin secretion with half-lives engineered from 12 hours to 7 days through fatty acid acylation or albumin binding. These agents serve primary commercial purpose in glycemic control for diabetes mellitus, with GLP-1 agonists additionally demonstrating cardiovascular risk reduction in approved indications. Injectable delivery mode dominates hospital procurement due to bioavailability requirements, though oral semaglutide tablets are gaining fastest growth in home care settings where patient adherence drives formulary placement. Biosimilar insulin vials represent mature, price-pressured segments, while pre-filled GLP-1 pens concentrate margin pools in pharmacy-dispensed channels.
EMA's centralized marketing authorization procedure governs novel insulin analog entry, while the EU MDR elevates post-market clinical follow-up obligations for device-drug combinations such as insulin pens. The F-Gas Regulation constrains propellant options in inhalable insulin development, redirecting R&D investment toward aqueous formulations. Stakeholders must monitor national health technology assessment divergence between France's HAS and Germany's IQWiG as reimbursement decisions increasingly determine launch sequencing across European markets.
Market Dynamics
EU MDR post-market surveillance obligations are compressing competitive entry timelines for biosimilar insulin manufacturers while concentrating procurement authority within Western European hospital systems.
Growth Catalysts
- EMA centralized authorization pathway:Streamlined marketing authorization for novel GLP-1 analogs accelerates cross-border commercialization across EU member states.
- Hospital formulary consolidation:Integrated German, French, and Italian procurement networks drive volume concentration for long-acting insulin portfolios.
- Fatty acid acylation engineering:Extended half-life GLP-1 formulations reduce injection frequency and improve adherence in home care settings.
Market Restraints
- Active pharmaceutical ingredient concentration:Peptide synthesis capacity concentrates in specialized European contract manufacturers, creating supply vulnerability.
- F-Gas Regulation constraints:Inhalable insulin propellant restrictions under EU environmental law redirect development resources toward injectable formats.
- Health technology assessment divergence:France's HAS and Germany's IQWiG employ divergent cost-effectiveness thresholds, fragmenting launch sequencing.
Strategic Opportunities
- Oral semaglutide tablets:Non-injectable GLP-1 delivery opens pharmacy-dispensed channels for patient populations avoiding needle-based therapy.
- Eastern European reimbursement expansion:Poland and Romania represent underpenetrated markets for analog insulin substitution from human insulin.
- Device-drug combination innovation:Smart insulin pen connectivity aligns with EU digital health initiative funding priorities.
Industry Challenges
- Peptide manufacturing expertise scarcity:Qualified personnel for large-scale recombinant protein production remain concentrated in legacy biologics hubs.
- EU MDR clinical follow-up timelines:Extended post-market study obligations for insulin pen systems compress product lifecycle economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market |
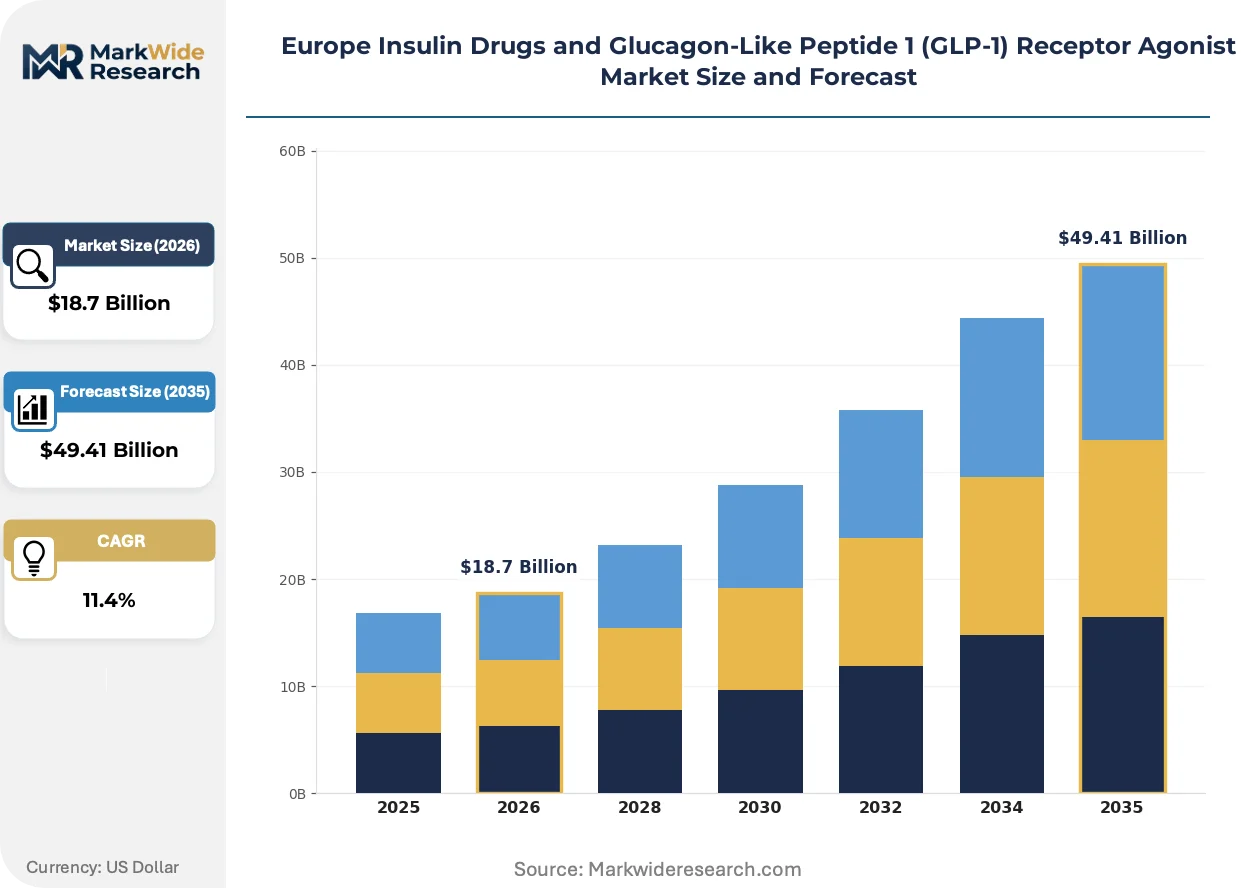
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, Biosimilars, Combination Therapy Delivery Mode: Injectable, Oral, Continuous Infusion, Pre-filled Pen End User: Hospitals, Clinics, Home Care, Pharmacies Form: Vials, Pens, Inhalers, Tablets |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly, AstraZeneca, Biocon, Pfizer, Wockhardt, Julphar, Exir, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market Shifts & Advancements
Injectable delivery platforms are fragmenting between hospital-centric pen systems and pharmacy-dispensed oral alternatives, while regulatory frameworks accelerate differentiation between originator and biosimilar evidence standards.
Dual GIP/GLP-1 receptor agonist technology is bifurcating the metabolic therapy landscape. Hospital endocrinology departments in Germany and France are prioritizing these agents for patients with cardiovascular comorbidities. The technology is bifurcating clinical trial investment away from standalone insulin analog development toward combination receptor targeting.
EU MDR device classification rules are elevating post-market clinical follow-up requirements for insulin delivery systems. Manufacturers must now generate real-world evidence on pen needle safety profiles across diverse patient populations. Pre-filled pen suppliers are responding by embedding digital dose-tracking capabilities to satisfy notified body expectations.
Home care formulary placement is displacing hospital-centric procurement as the primary growth channel for GLP-1 agonists. Pharmacy benefit managers in Italy and Spain are negotiating direct-to-patient distribution models that bypass traditional hospital pharmacy intermediaries. This channel rotation is most visible in semaglutide tablet dispensing, where patient adherence metrics drive payer contracting decisions.
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market Segmentation
Channel configuration determines margin capture across European diabetes therapeutics. Hospital procurement networks favor device-integrated formats, while pharmacy-dispensed channels reward adherence-optimized dosing regimens.
Product Type:
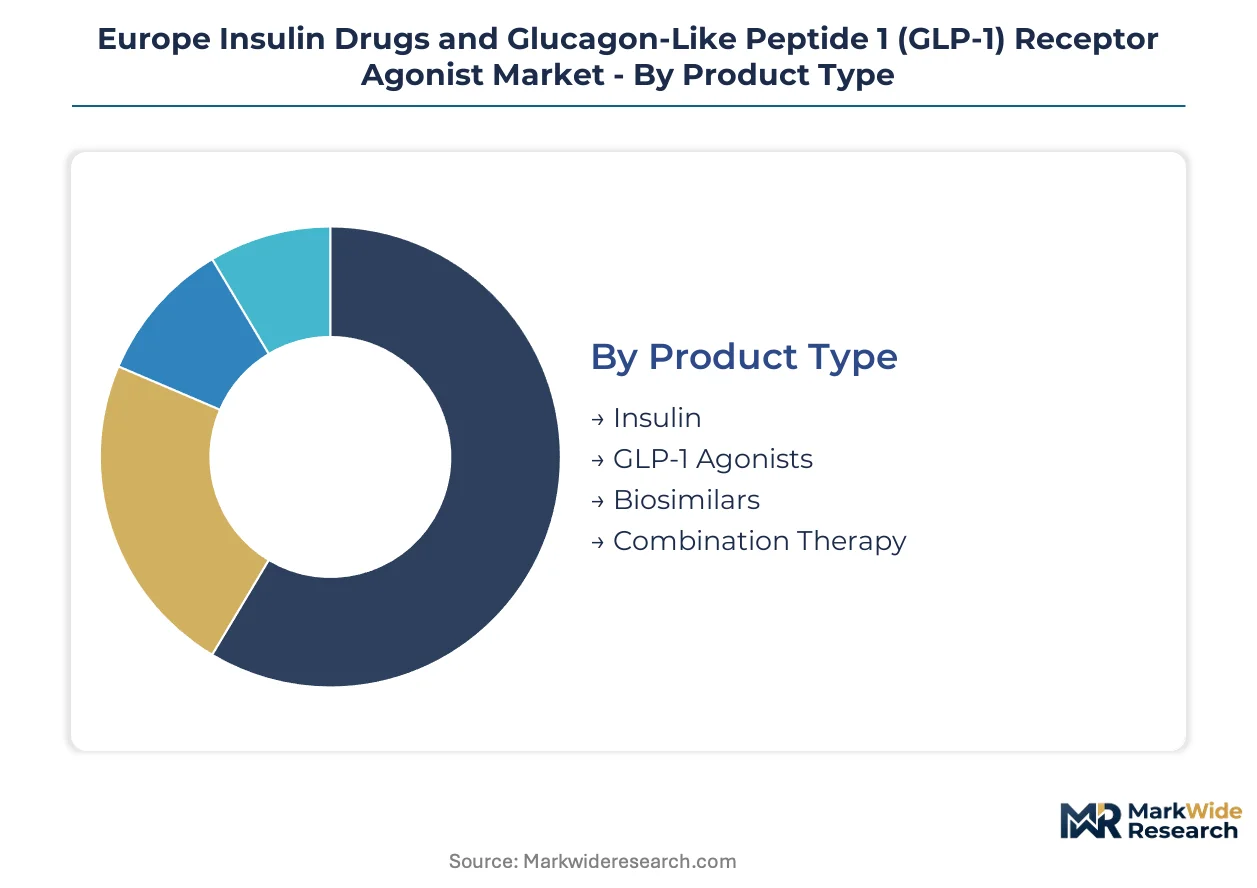
Channel-mix dynamics concentrate high-margin biologics in hospital tenders, while price-pressured biosimilars flow through wholesale pharmacy networks.
- Insulin:Recombinant human insulin and analog formulations with modified amino acid sequences enable precise glycemic control. German and French hospital systems concentrate procurement for long-acting analog portfolios, though reimbursement compression constrains originator pricing power.
- GLP-1 Agonists:Fatty acid acylated peptides with engineered half-lives from 12 hours to 7 days enhance glucose-dependent insulin secretion. Italian and Spanish pharmacy benefit managers drive volume for once-weekly formulations that improve home care adherence metrics.
- Biosimilars:Follow-on insulin formulations approved through EMA centralized pathways face EU MDR evidence escalation. Tender markets across Poland and Romania absorb volume as human insulin substitution accelerates.
- Combination Therapy:SGLT2-GLP-1 fixed-dose pairings target cardiovascular risk reduction in approved indications. Payer negotiations in France and Germany determine formulary placement against standalone alternatives.
By volume, Insulin leads. By growth pace, GLP-1 Agonists are expanding most quickly.
Delivery Mode:
Cost-tier stratification separates premium connected devices from standard disposable formats, with reimbursement thresholds determining channel access.
- Injectable:Subcutaneous delivery dominates bioavailability requirements for peptide therapeutics. Hospital procurement across Germany, France, and Italy standardizes on pen-needle systems with dose-tracking capabilities.
- Oral:Semaglutide tablets with absorption enhancers bypass injection barriers for needle-averse populations. Pharmacy-dispensed channels in Spain and Italy capture fastest expansion as adherence metrics drive payer contracting.
- Continuous Infusion:Pump-integrated insulin delivery serves intensive glycemic management in tertiary care settings. Reimbursement corridors in Germany and France concentrate adoption among Type 1 diabetes populations.
- Pre-filled Pen:Disposable injection systems with dose memory align with EU digital health initiative priorities. Smart connectivity features satisfy EU MDR post-market surveillance obligations for device-drug combinations.
By installed base, Injectable formats dominate. By trajectory steepness, Oral delivery is gaining share fastest.
End User:
Application concentration shifts from inpatient glycemic control toward ambulatory chronic disease management as therapy initiation moves to primary care.
- Hospitals:Tertiary endocrinology departments in Germany and France prioritize dual GIP/GLP-1 agonists for cardiovascular comorbidity patients. EU MDR clinical follow-up obligations concentrate procurement authority within integrated delivery networks.
- Clinics:Outpatient diabetes centers manage therapy escalation and complication screening. Italian regional health systems channel GLP-1 initiation through specialist-led pathways.
- Home Care:Patient-administered therapy dominates GLP-1 agonist growth as once-weekly formulations reduce clinical visit burden. Direct-to-patient distribution models in Spain bypass traditional pharmacy intermediaries.
- Pharmacies:Community dispensing captures oral semaglutide volume as adherence programs influence formulary placement. Reimbursement divergence between France's HAS and Germany's IQWiG fragments launch sequencing.
By patient volume, Home Care leads. By revenue concentration, Hospitals remain ahead.
Form:
Supply concentration in peptide manufacturing creates vulnerability for vial and pen formats, while inhaler development redirects under F-Gas constraints.
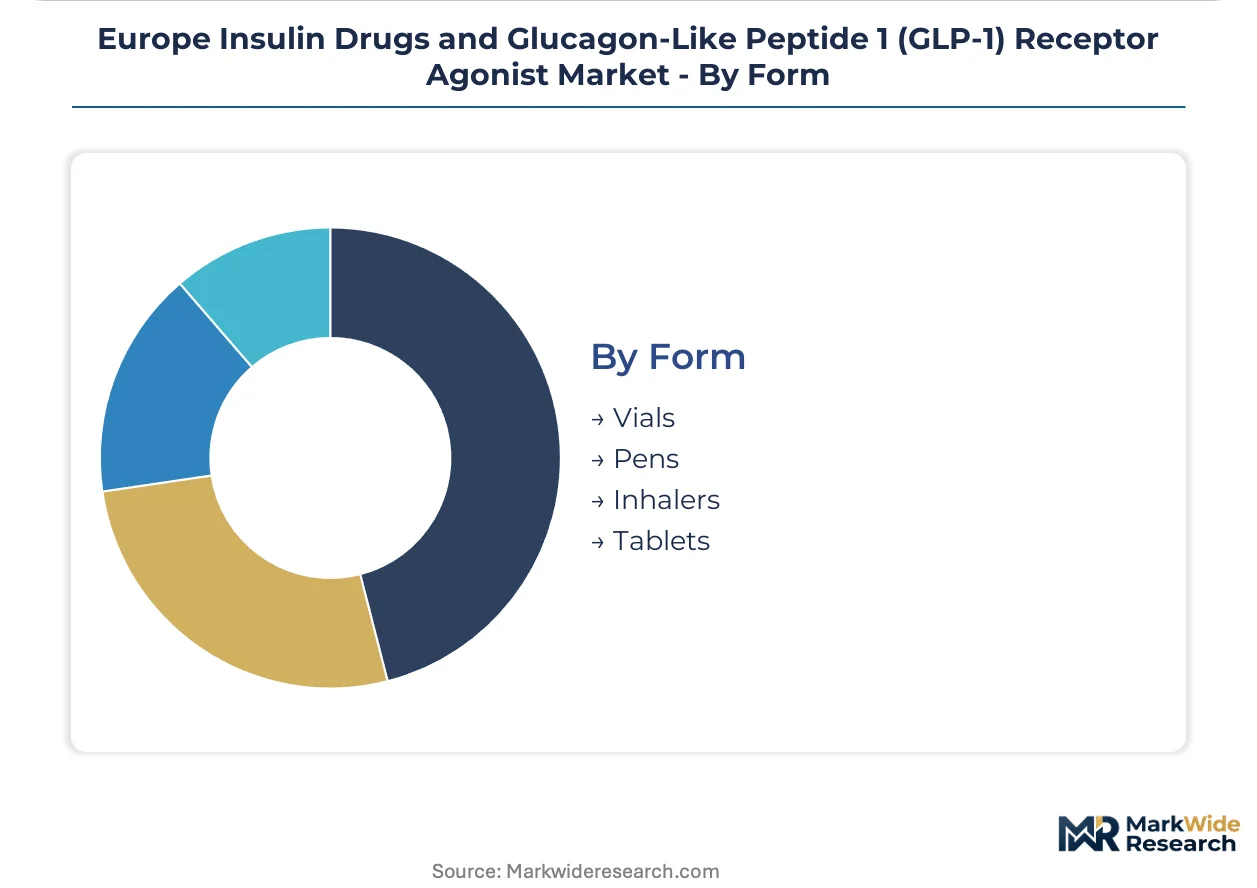
- Vials:Multi-dose glass containers serve cost-sensitive human insulin segments. Biosimilar-grade vials face price compression across Eastern European tender markets.
- Pens:Cartridge-based disposable systems dominate GLP-1 agonist dispensing. Pre-filled pen suppliers embed digital dose-tracking to satisfy notified body expectations under EU MDR.
- Inhalers:Pulmonary insulin delivery faces propellant restrictions under F-Gas Regulation. Development resources redirect toward aqueous formulations as environmental compliance costs escalate.
- Tablets:Oral semaglutide with absorption enhancers opens pharmacy channels for injection-averse patients. Patient adherence metrics drive payer contracting decisions in Italy and Spain.
By unit volume, Pens lead. By expansion trajectory, Tablets show the steepest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European insulin and GLP-1 agonist trade flows reflect concentrated API production in Denmark and France against distributed formulation finishing across Germany and Italy. Import dependency for recombinant peptide precursors shapes procurement security calculations in hospital networks.
Germany
Hospital procurement networks in North Rhine-Westphalia and Bavaria concentrate volume for long-acting insulin analogs. IQWiG cost-effectiveness thresholds determine reimbursement corridors for novel GLP-1 formulations. Berlin-Brandenburg hosts digital health initiative funding for connected insulin pen development.
France
HAS evaluation frameworks prioritize cardiovascular outcome data in GLP-1 agonist formulary placement. The Île-de-France region anchors Sanofi's integrated production footprint for insulin active pharmaceutical ingredients. Lyon-based contract manufacturers supply peptide synthesis capacity to European biosimilar developers.
Italy
Lombardy regional health systems channel GLP-1 initiation through specialist-led diabetes pathways. AIFA pricing negotiations fragment launch sequencing for oral semaglutide tablets. Emilia-Romagna pharmacy benefit managers pilot direct-to-patient distribution models bypassing hospital intermediaries.
Spain
Catalonia and Madrid autonomous communities drive fastest oral GLP-1 expansion as adherence metrics influence payer contracting. Ministry of Health tender processes concentrate biosimilar insulin volume in Andalusia hospital networks. Barcelona hosts emerging peptide manufacturing investment from Indian biosimilar entrants.
Poland
Human insulin substitution accelerates in Masovia and Silesia regional health systems as analog penetration lags Western Europe. AOTM reimbursement decisions determine biosimilar access corridors. Warsaw hospital networks represent underpenetrated demand for once-weekly GLP-1 formulations.
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market Competitive Landscape
Listed leaders compete with private specialists across API supply and device integration dimensions. Danish and French pharmaceutical conglomerates anchor consolidated peptide production capacity, while Indian and Middle Eastern biosimilar specialists fragment formulation finishing. Three archetypes dominate: integrated API-to-device conglomerates, biosimilar pure-plays, and device-technology licensors. Capacity expansion and strategic patent licensing constitute the dominant competitive moves.
Within the integrated conglomerate tier, Novo Nordisk and Sanofi occupy positions exemplifying captive API supply and pen-system integration. Eli Lilly represents the dual-receptor technology archetype through its GIP/GLP-1 positioning. These three listed entities anchor margin concentration in pre-filled pen formats and extended-half-life formulations.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly |
| AstraZeneca |
| Biocon |
| Pfizer |
| Wockhardt |
| Julphar |
| Exir |
| Others |
Supply & Pricing Matrix
Human insulin substitution in Eastern European tender markets simultaneously redistributes manufacturing volume toward Polish and Romanian contract finishers and compresses originator pricing power across Western European hospital networks. This substitution dynamic concentrates procurement authority within integrated German and French delivery systems while fragmenting margin capture between biosimilar pure-plays and integrated API conglomerates.
Pricing Analysis
Hospital procurement managers anchor three-tier pricing structure across premium, standard, and economy levels for insulin and GLP-1 agonist portfolios. Price differentiation rests on EMA approval pathway and EU MDR device classification tier, with cardiovascular outcome data commanding premium positioning in French HAS evaluations. Cost compression in biosimilar vials intensifies because tender aggregation across Poland and Romania consolidates buyer leverage. Retail pharmacy channels exhibit highest price sensitivity for oral semaglutide tablets, while tertiary hospital networks retain lowest sensitivity due to bundled device-drug procurement.
Supply Chain Analysis
Peptide synthesis capacity chokepoints in Denmark and France underwrite European insulin API security, with recombinant protein production concentrated in Novo Nordisk's Danish facilities and Sanofi's Île-de-France operations. Active pharmaceutical ingredient supply draws from specialized European contract manufacturers, with formulation finishing distributed across Germany and Italy. Single-source vulnerability concentrates in fatty acid acylation precursor supply for extended-half-life GLP-1 engineering. Distribution runs through hospital procurement networks in Germany and France, pharmacy benefit managers in Italy and Spain, and tender authorities in Poland and Romania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified personnel scarcity for large-scale recombinant protein production constrains capacity expansion timelines, with peptide manufacturing expertise concentrated in legacy Danish and French biologics hubs limiting competitive entry velocity.
For Market Incumbents: Consolidate API supply security through captive peptide synthesis capacity expansion in Denmark and France. Lock in long-acting insulin portfolio positioning within German IQWiG reimbursement corridors to defend against dual GIP/GLP-1 receptor agonist substitution. Prioritize EU MDR clinical follow-up data generation for connected pen systems to satisfy notified body expectations and extend product lifecycle economics.
For New Entrants and Emerging Players: EMA centralized authorization fast-tracks offer entry acceleration for biosimilar insulin developers with EU MDR-compliant device-drug combinations. White-space concentration sits in Polish and Romanian human insulin substitution markets, where analog penetration lags Western European benchmarks. Direct-to-patient distribution partnerships with Spanish pharmacy benefit managers bypass entrenched hospital pharmacy intermediaries.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed biosimilar pure-plays in peptide formulation finishing, particularly those with Eastern European tender market positioning. Long-term viability favors integrated API-to-device conglomerates with backward control over recombinant protein supply. Monitor EMA biosimilar approval velocity and EU MDR notified body capacity as inflection indicators for competitive entry economics.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Centralized Authorization Pathway | Streamlined cross-border commercialization accelerates novel GLP-1 analog entry across EU member states. |
| EU MDR Clinical Follow-Up Investment | Real-world evidence generation on pen needle safety satisfies notified body expectations for device-drug combinations. |
| Peptide Manufacturing Capacity Expansion | Captive recombinant protein production in Denmark and France secures API supply against contract manufacturer scarcity. |
| Hospital Procurement Network Consolidation | Integrated German and French delivery systems concentrate volume for long-acting insulin and dual agonist portfolios. |
| Oral Semaglutide Pharmacy Channel Development | Direct-to-patient distribution models in Italy and Spain bypass traditional hospital pharmacy intermediaries. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation through EMA centralized procedure filings, EU MDR notified body guidance documents, ClinicalTrials.gov cardiovascular outcome studies, and national health technology assessment publications from HAS and IQWiG. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation anchored market sizing.
Across the projection horizon, analytical framework segmented by product type, delivery mode, end user, and form, with regional regulatory clusters modeled separately. CAGRs derived from therapy line expansion rates, biosimilar substitution curves, and reimbursement corridor penetration. Forecast inputs incorporated EU MDR implementation timelines, F-Gas Regulation compliance costs, and digital health initiative funding allocations.
Underlying assumptions cover stable EMA review capacity, continued IQWiG-HAS divergence in cost-effectiveness thresholds, and peptide synthesis supply continuity, with deviation risk concentrated in EU MDR notified body backlog and Eastern European reimbursement expansion velocity. Practitioners should keep alternative scenarios live as biosimilar evidence requirements and environmental compliance costs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Riociguat Tablets Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Global Azithromycin Market