
 Lansoprazole API Market | 2026-2036
Lansoprazole API Market Size, Share, and Industry Trends Forecast 2026-2036
Lansoprazole API Market Insights
Indian bulk drug manufacturers is pivoting toward dedicated proton pump inhibitor synthesis lines to secure long-term offtake contracts. Dr. Reddy's Laboratories leverages backward integration into lansoprazole intermediates to protect margin pools against volatile starting material costs. Cipla sustains formulation-to-API coordination across its Indian manufacturing network, while Lupin competes through specialized effluent-handling capabilities that ease environmental compliance burdens.
Lansoprazole API refers to the active pharmaceutical ingredient of a benzimidazole-derived proton pump inhibitor, typically manufactured via oxidative coupling of 2-mercaptobenzimidazole with a substituted pyridine followed by sulfoxide formation, with chiral resolution yielding the pharmacologically active (R)-enantiomer used to suppress gastric acid secretion. Powder-grade material dominates commercial transactions due to its versatility across oral solid dosage forms, while capsule applications command tighter particle-size specifications that filter the supplier base. Pharmaceutical companies represent the primary demand channel, though contract manufacturers are capturing volume growth as brand holders outsource final dosage production.
US FDA, CDSCO, and ICH Q7 standards govern facility inspections, impurity profiling, and active pharmaceutical ingredient good manufacturing practice compliance across production sites serving regulated markets. These frameworks elevate entry barriers for new API entrants while rewarding incumbents with established regulatory dossiers and inspection histories. Stakeholders must monitor evolving nitrosamine impurity thresholds and bioequivalence study requirements for generic lansoprazole formulations as regulatory stringency tightens.
Market Dynamics
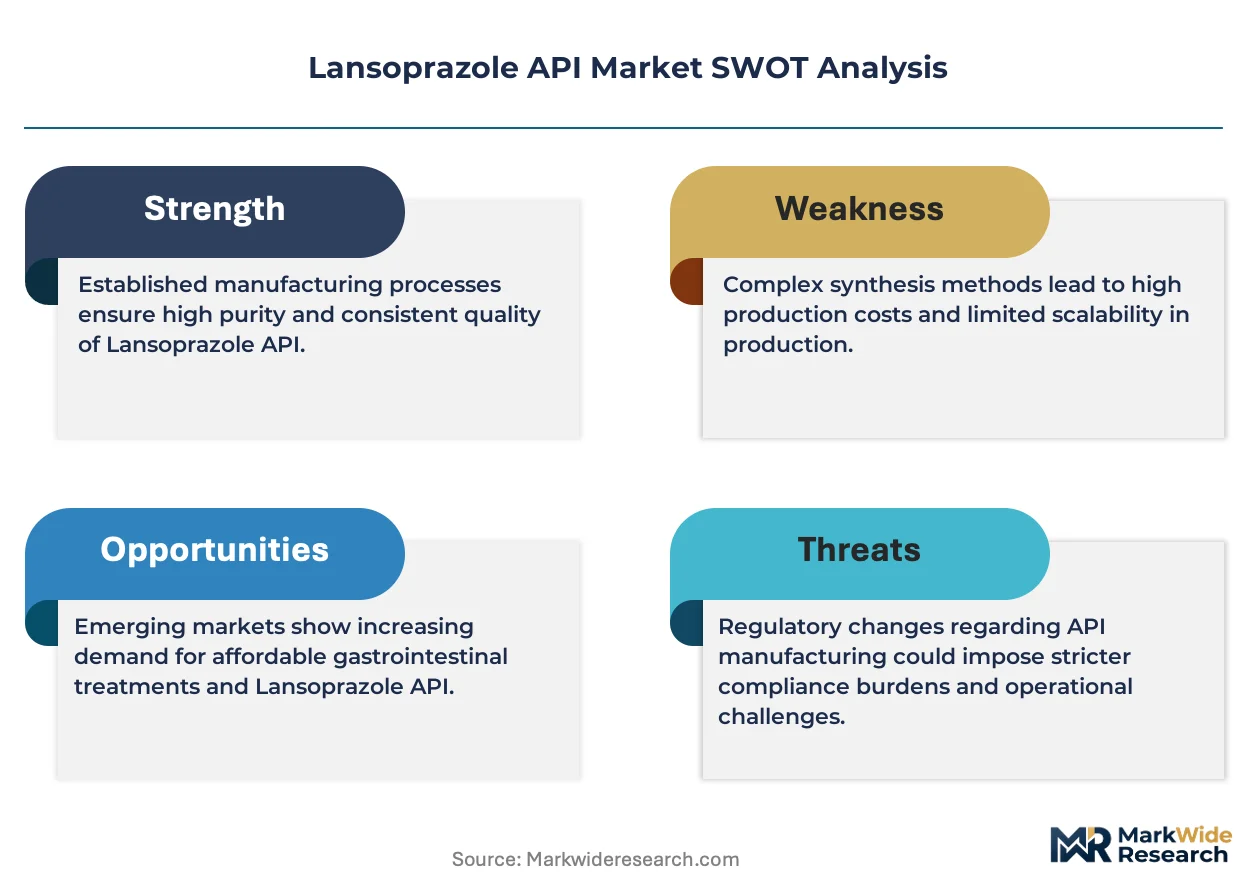
Supplier consolidation around ICH Q7-compliant facilities is compressing the qualified vendor pool, forcing formulation manufacturers to lock in multi-year API supply contracts ahead of regulatory inspections.
Growth Catalysts
- CDSCO domestic manufacturing mandates:India's push for API self-sufficiency under production-linked incentive schemes is channeling capital toward benzimidazole synthesis capacity expansion in Gujarat and Telangana.
- Chronic GERD prevalence:Rising diagnosed cases across Southeast Asian outpatient clinics are expanding prescription volumes for proton pump inhibitor formulations.
- Continuous flow chemistry:Adoption of microreactor systems for oxidative coupling reactions is shortening batch cycle times and improving yield consistency at commercial scale.
Market Restraints
- Starting material volatility:Fluctuating 2-mercaptobenzimidazole spot prices from Chinese intermediate suppliers squeeze margin predictability for API converters.
- Regulatory friction:US FDA nitrosamine impurity guidance requires costly method redevelopment and validation across existing product portfolios.
- Substitution threat:Esomeprazole and rabeprazole APIs compete for identical ulcer and reflux indications with comparable bioequivalence profiles.
Strategic Opportunities
- African market underpenetration:Local formulation capacity in Nigeria and Kenya relies heavily on Indian API imports, creating first-mover advantages for dossier-ready suppliers.
- Orally disintegrating tablet demand:Pediatric and geriatric dosage preferences are opening specialized particle-size specification contracts.
- Green chemistry incentives:REACH-aligned solvent recovery mandates in the European Union reward manufacturers with closed-loop effluent systems.
Industry Challenges
- Analytical method transfer complexity:Relocating validated impurity profiling protocols between manufacturing sites triggers six-to-nine month regulatory reapproval timelines.
- Specialized synthesis workforce scarcity:Experienced chiral resolution chemists command premium compensation in Hyderabad and Mumbai labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lansoprazole API Market |
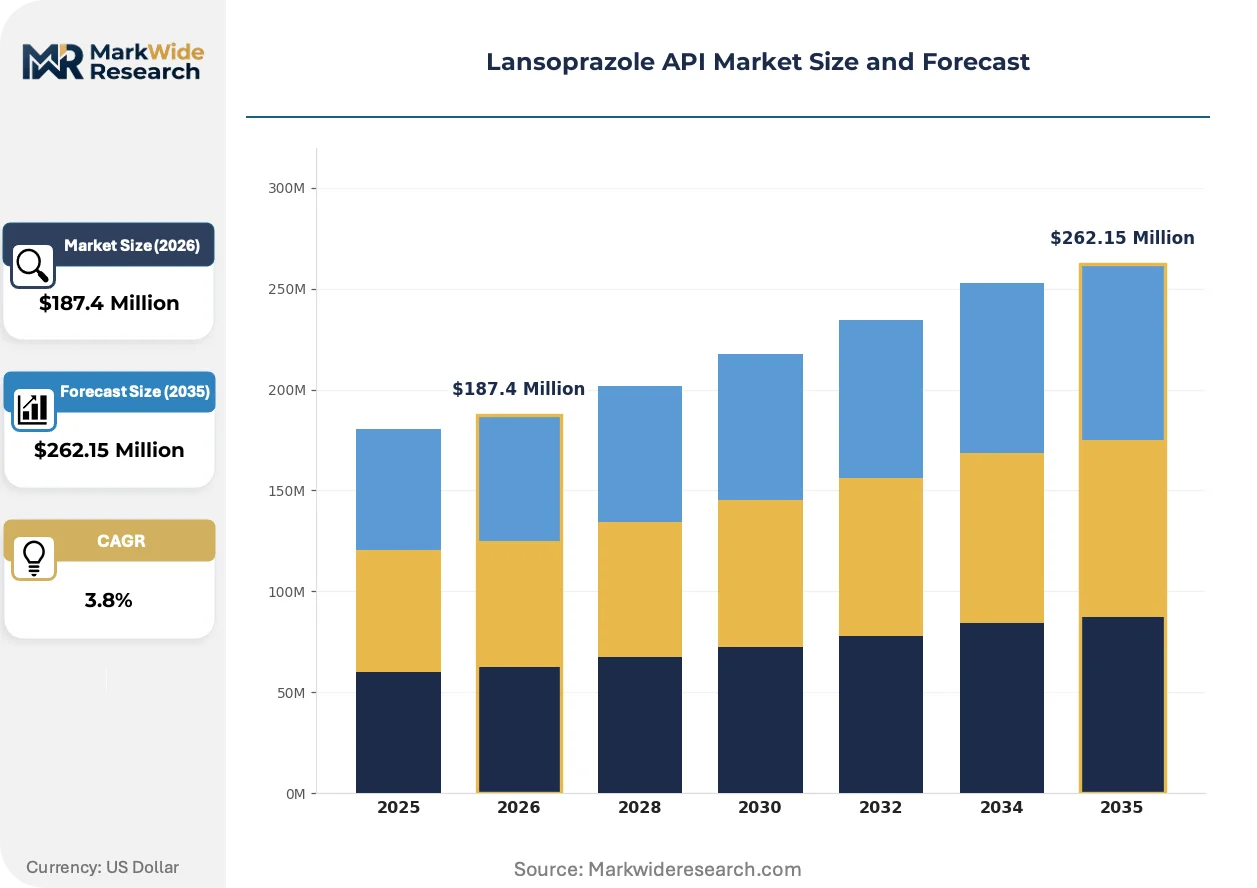
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granule, Powder, Tablet, Capsule End User: Pharmaceutical Companies, Contract Manufacturers, Research Laboratories, Hospitals Application: Treatment of Ulcers, Gastroesophageal Reflux Disease, Helicobacter Pylori Eradication, Zollinger-Ellison Syndrome Delivery Mode: Oral, Intravenous, Enteral, Others |
| Companies Covered | Dr. Reddy’s Laboratories, Cipla, Lupin, Sandoz Private Limited, Mylan Laboratories Limited, Metrochem API Private Limited, Shandong Keyuan Pharmaceutical, Luoxin Pharmaceuticals, Argus Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lansoprazole API Market Trends and Innovations
Process intensification and regulatory chemistry are converging to redefine manufacturing economics, with automation and impurity control emerging as the primary vectors of competitive differentiation.
Continuous manufacturing systems for sulfoxide formation are rewriting capital efficiency benchmarks in proton pump inhibitor API production. Mid-scale Indian manufacturers are piloting these platforms to secure European formulation contracts. The technology is compressing facility footprint requirements while tightening batch-to-batch consistency metrics.
EMA nitrosamine risk assessment templates now mandate retrospective evaluation of all chemically synthesized APIs. European formulation holders are demanding updated impurity profiles from Asian suppliers. This regulatory tightening is accelerating supplier qualification audits and disqualifying legacy manufacturing sites.
Long-term offtake agreements are displacing spot market transactions as the dominant procurement mechanism for lansoprazole API. Multinational generic houses in Germany and the United States are locking in three-to-five year supply contracts with inspection-ready Indian facilities. This shift is most visible in Mumbai-Ahmedabad corridor supply negotiations.
Lansoprazole API Market Segmentation
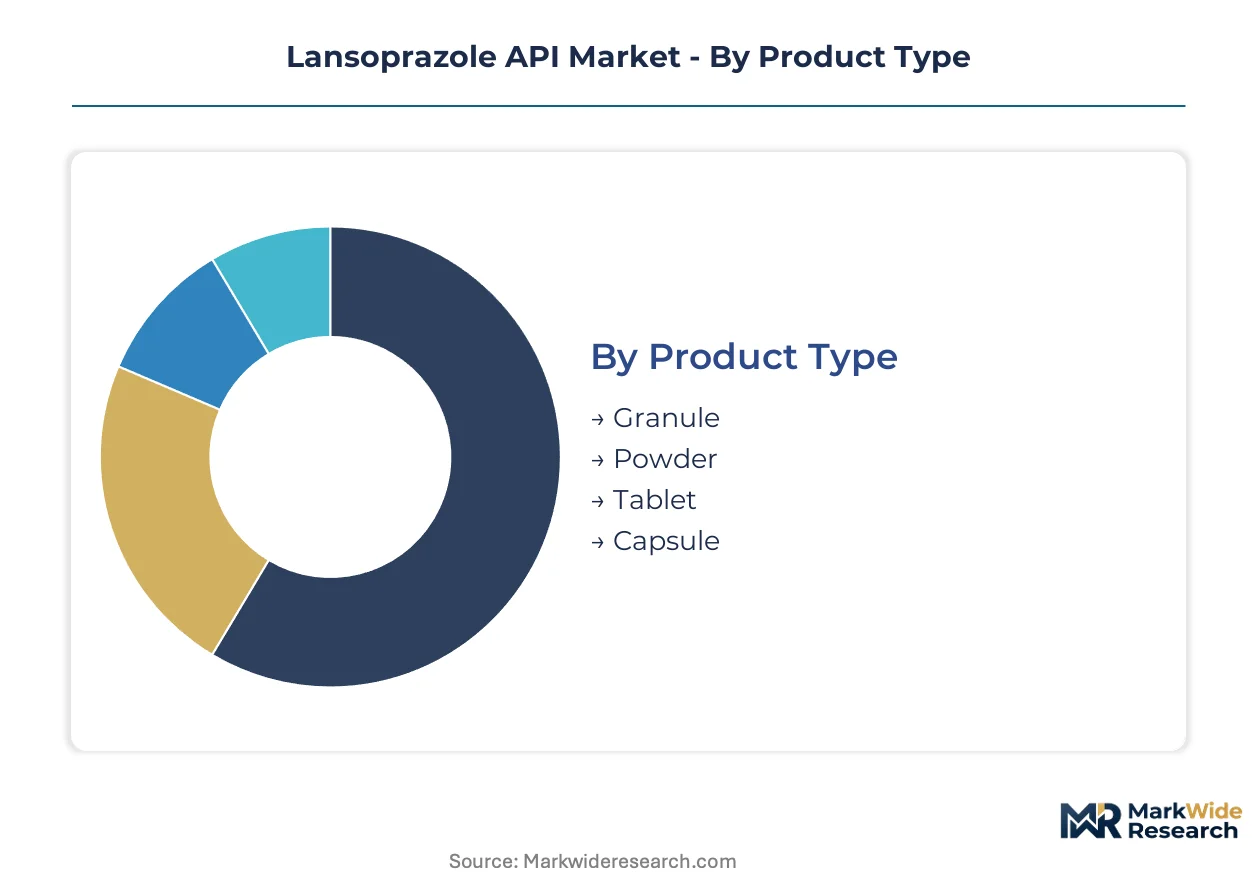
Lansoprazole API procurement patterns diverge sharply across physical forms and customer channels, with regulatory dossier requirements filtering supplier eligibility for each segment. Specification tolerances for particle size, dissolution profiles, and impurity thresholds determine which manufacturing facilities qualify for premium versus commodity contracts.
Product Type:
FDA, CDSCO, and ICH Q7 certification burdens fall heaviest on powder and granule grades destined for regulated markets, while tablet and capsule specifications trigger additional bioequivalence documentation.
- Granule:Spherical agglomerates manufactured via fluid-bed processing with controlled porosity for delayed-release coating applications. Demand concentrates among European formulation houses seeking uniform dissolution kinetics for enteric-coated products, constrained by EMA nitrosamine testing mandates.
- Powder:Fine milled material with specified particle-size distribution for direct compression or capsule filling. Indian generic manufacturers in Gujarat and Telangana drive procurement volume for both domestic formulation and Southeast Asian export markets, with CDSCO facility inspections gating supplier qualification.
- Tablet:Pre-compressed intermediate requiring tighter hardness and friability specifications. Contract manufacturers in Mumbai-Ahmedabad corridor favor this form for streamlined final dosage production.
- Capsule:Grade material with enhanced flow properties and low residual solvent limits. Pediatric and geriatric formulation specialists specify this segment for orally disintegrating applications.
Leading the category by volume: Powder. Growing fastest: Granule.
End User:
Customer type determines contract structure, with pharmaceutical companies favoring multi-year offtake agreements while research laboratories drive spot-market spot demand for small-batch qualified material.
- Pharmaceutical Companies:Integrated generic houses and innovator firms with captive formulation capacity. Dr. Reddy's Laboratories and Cipla anchor Indian procurement, locking in three-to-five year supply contracts with backward-integrated API suppliers.
- Contract Manufacturers:Third-party dosage facilities serving brand holders without internal production. Volume is climbing fastest here as German and US generic houses outsource final manufacturing to inspection-ready Indian sites.
- Research Laboratories:Academic and clinical trial material providers requiring gram-to-kilogram scale with expedited COA turnaround. Price insensitivity characterizes this segment.
- Hospitals:Institutional procurement for in-house compounding and specialty pharmacy operations. Limited volume but strict chain-of-custody documentation requirements.
Dominant buyer type: Pharmaceutical companies. Expanding most quickly: Contract manufacturers.
Application:
Therapeutic indication shapes impurity profiling depth, with H. pylori eradication protocols demanding validated nitrosamine thresholds and Zollinger-Ellison applications requiring higher-purity grades.
- Treatment of Ulcers:Duodenal and gastric ulcer indications represent the foundational demand driver. Indian formulation exports to African markets concentrate here.
- Gastroesophageal Reflux Disease:Chronic GERD management commands the largest prescription volume. Southeast Asian outpatient clinic expansion is propelling API demand.
- Helicobacter Pylori Eradication:Combination therapy with antibiotics requires API lots with validated low-nitrosamine certification. EMA retrospective risk assessments have tightened supplier qualification for this segment.
- Zollinger-Ellison Syndrome:Rare gastrinoma indication with ultra-high purity requirements and small batch sizes. Premium pricing reflects specialized analytical burden.
Largest application by volume: Gastroesophageal Reflux Disease. Steepest expansion trajectory: Helicobacter Pylori Eradication.
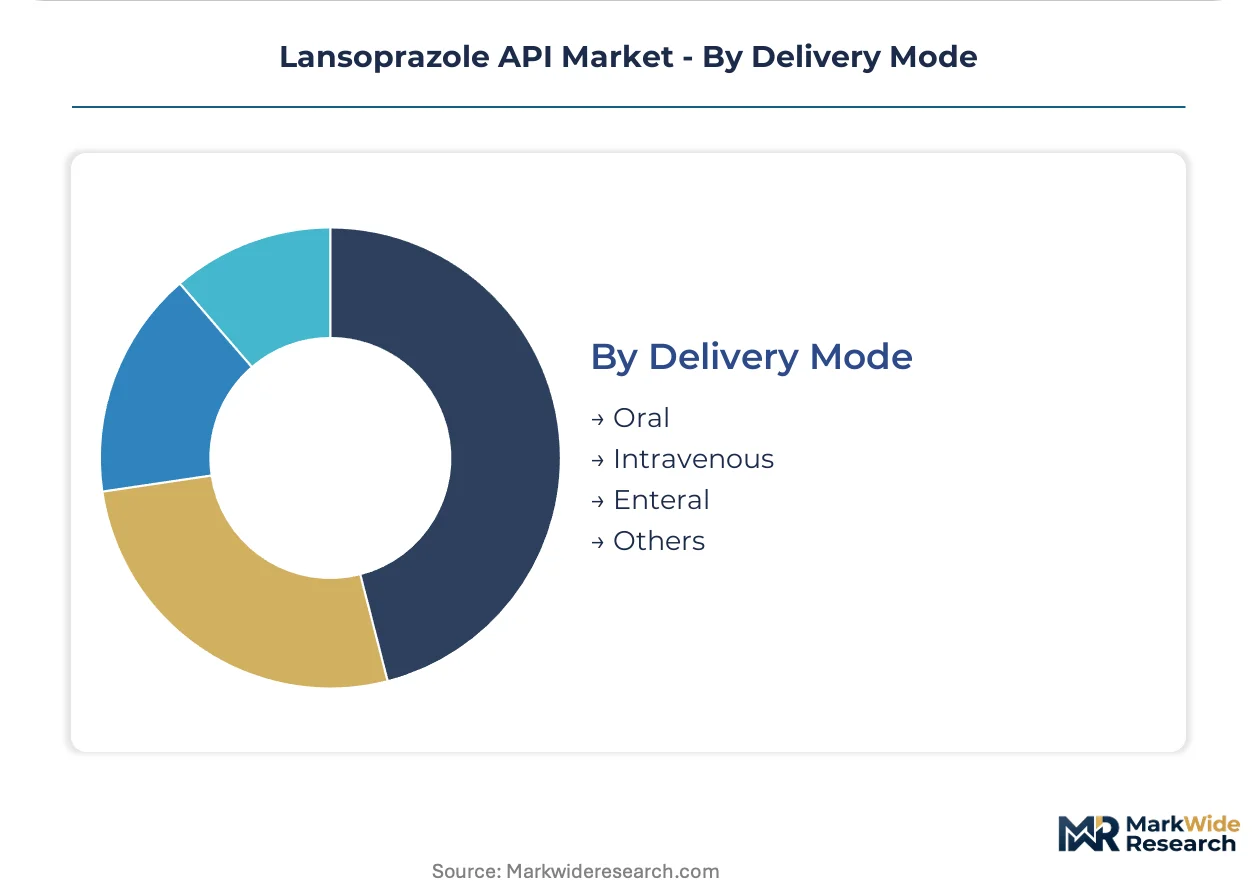
Delivery Mode:
Route of administration determines sterility and endotoxin specifications, with intravenous grades requiring aseptic manufacturing suites that filter the qualified supplier base.
- Oral:Dominant route encompassing capsules, tablets, and suspensions. Powder and granule API forms serve this channel with standard GMP compliance.
- Intravenous:Sterile lyophilized or solution formulations for hospitalized patients with impaired oral intake. Limited supplier pool due to aseptic processing requirements.
- Enteral:Tube-fed administration for critical care settings. Specialized particle-size specifications prevent clogging.
- Others:Rectal and topical experimental formulations with minimal commercial volume.
Oral delivery commands absolute volume dominance. Intravenous represents the highest-margin niche.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
2-mercaptobenzimidazole intermediate supply from Chinese chemical hubs anchors manufacturing economics across lansoprazole API production networks. Indian formulation demand and Southeast Asian export markets channel procurement toward Gujarat and Telangana synthesis corridors. Regulatory inspection readiness separates qualified suppliers from commodity traders in this geography.
United States
Generic proton pump inhibitor prescription volumes sustain API import reliance from inspection-ready Indian facilities. FDA nitrosamine impurity guidance mandates retrospective risk assessments across existing ANDA portfolios. New Jersey and North Carolina formulation clusters source qualified material through multi-year offtake agreements with Mumbai-Ahmedabad corridor suppliers.
India
Domestic GERD diagnosis expansion and African export formulation demand concentrate procurement in western chemical belts. CDSCO production-linked incentive schemes channel capital toward dedicated benzimidazole synthesis capacity in Gujarat and Telangana. Hyderabad and Mumbai manufacturing corridors compete on effluent-handling capabilities and chiral resolution workforce access.
China
Intermediate supply dominance in 2-mercaptobenzimidazole and substituted pyridine derivatives positions Shandong and Jiangsu provinces as upstream price-setters. NMPA facility inspections and environmental compliance tightening filter the qualified API converter base. Zibo and Taizhou chemical parks consolidate oxidative coupling capacity under stricter MEE effluent discharge mandates.
Germany
European formulation holders demand EMA nitrosamine risk assessment documentation for all chemically synthesized API lots. REACH-aligned solvent recovery requirements reward manufacturers with closed-loop effluent systems. Frankfurt and Leverkusen generic houses lock in three-to-five year supply contracts with inspection-ready Asian facilities.
Brazil
Latin American ulcer and reflux indication expansion drives API import dependence on Indian and Chinese suppliers. ANVISA facility inspection protocols increasingly align with FDA and EMA standards, elevating supplier qualification barriers. São Paulo and Rio de Janeiro formulation clusters prioritize dossier-ready suppliers with established regulatory histories.
Lansoprazole API Market Competitive Landscape
Global majors compete with regional champions across regulatory dossier depth and inspection readiness. The supplier base concentrates around ICH Q7-compliant facilities with established FDA and EMA inspection histories, compressing the qualified vendor pool for formulation manufacturers. Three archetypes dominate: backward-integrated pharmaceutical houses with captive intermediate supply, specialized API converters with dedicated proton pump inhibitor synthesis lines, and contract manufacturers capturing outsourced final dosage production. Capacity expansion and long-term offtake agreement negotiation represent the primary competitive moves as procurement shifts from spot markets to multi-year contracts.
Among Indian pharmaceutical houses, Dr. Reddy's Laboratories and Cipla occupy positions exemplifying backward-integrated API-to-formulation coordination, while Lupin represents specialized environmental compliance capabilities that ease regulatory burden management. Chinese intermediate and API suppliers including Shandong Keyuan Pharmaceutical and Luoxin Pharmaceuticals anchor the upstream supply tier. Sandoz Private Limited and Mylan Laboratories Limited sit within the multinational generic tier competing on inspection-ready facility networks and established European and US regulatory dossiers.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories |
| Cipla |
| Lupin |
| Sandoz Private Limited |
| Mylan Laboratories Limited |
| Metrochem API Private Limited |
| Shandong Keyuan Pharmaceutical |
| Luoxin Pharmaceuticals |
| Argus Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
Backward integration into 2-mercaptobenzimidazole intermediates anchors both supply security and margin protection for Indian API manufacturers serving regulated markets. Captive production of key starting materials insulates Dr. Reddy's Laboratories and Cipla from Chinese spot price volatility while enabling three-to-five year contract pricing that undercuts non-integrated competitors.
Pricing Analysis
Regulatory dossier completeness functions as the core bundling mechanism, with FDA-inspected facilities commanding premiums that include validated impurity profiling and nitrosamine risk assessment documentation. Three-tier pricing structure across ICH Q7-certified, CDSCO-registered, and non-regulated grades filters buyer segments, with European formulation houses least sensitive and African spot purchasers most price-responsive. Cost compression in the commodity tier intensifies because Chinese intermediate suppliers squeeze converter margins. Contract manufacturers in the Mumbai-Ahmedabad corridor negotiate volume discounts that shift procurement from spot markets to locked-in offtake agreements.
Supply Chain Analysis
Recovered solvent streams and effluent treatment byproducts circulate through closed-loop systems at Gujarat and Telangana facilities, reducing virgin material intensity and regulatory compliance costs. Geographic supply concentration centers on India, China, and Germany, with Shandong and Jiangsu provinces feeding 2-mercaptobenzimidazole and substituted pyridine derivatives to downstream converters. Raw material dependencies rest on Chinese intermediate supply, Indian chiral resolution expertise, and European formulation demand. Single-source vulnerability in starting material supply chains exposes margin predictability to Shandong chemical park environmental enforcement actions. Distribution runs through inspection-qualified API stockists to formulation manufacturers, with long-term contracts displacing spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over benzimidazole intermediates separates sustainable margin pools from commodity trap vulnerability. Players are pursuing captive synthesis capacity as the decisive upstream lever.
For Market Incumbents: Hedge against esomeprazole and rabeprazole substitution threats by deepening captive intermediate supply and locking multi-year offtake contracts with inspection-ready contract manufacturers. Prioritize nitrosamine impurity method redevelopment ahead of FDA guidance enforcement to maintain dossier competitiveness. Capacity addition in Telangana's effluent-handling corridors secures environmental compliance headroom against tightening MEE mandates. For New Entrants and Emerging Players: Continuous flow chemistry platforms for oxidative coupling reactions offer a technology-first wedge into mid-scale Indian manufacturing gaps left by legacy batch operators. Target Nigerian and Kenyan formulation markets where local production capacity relies on Indian API imports and dossier-ready suppliers remain scarce. Pursue pediatric orally disintegrating tablet specifications as the go-to-market angle, as particle-size specialization commands premium pricing with limited qualified competition. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational generic houses seeking inspection-ready Indian facilities with established FDA and EMA histories. Long-term viability over the projection horizon favors backward-integrated API converters with captive intermediate supply and locked formulation contracts. Watch CDSCO production-linked incentive disbursement velocity as the inflection signal for capacity expansion timing and competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | Captive 2-mercaptobenzimidazole production shields margin pools from Chinese spot volatility. |
| Continuous Flow Chemistry Adoption | Microreactor systems for oxidative coupling compress batch cycle times and tighten consistency metrics. |
| Long-term Supply Agreement Negotiation | Three-to-five year offtake contracts with German and US generic houses displace spot procurement. |
| Nitrosamine Impurity Method Redevelopment | EMA retrospective risk assessments demand updated analytical protocols for H. pylori eradication segments. |
| African Market Dossier Preparation | First-mover qualification for Nigerian and Kenyan formulation imports captures underpenetrated demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with API synthesis directors, regulatory affairs managers at CDSCO and FDA-inspected facilities, formulation procurement leads, and benzimidazole intermediate traders. Secondary sources incorporated FDA 483 inspection observations, EMA nitrosamine risk assessment templates, CDSCO production-linked incentive disbursement records, and Indian pharmaceutical export statistics. Bottom-up capacity modeling triangulated against top-down prescription volume projections across the analysis window.
Granularity-level modeling operated at dosage-form, purity grade, regulatory certification tier, and regional production cluster dimensions. Volume and value outputs drew from segmented patient population forecasts, treatment duration assumptions, and bioequivalence study filing trajectories. CAGRs derived from regression-based trend extrapolation calibrated to historical API price elasticity and substitution patterns between proton pump inhibitors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt nitrosamine threshold revisions or Chinese environmental enforcement surges. Forecasts reflect assumptions regarding CDSCO incentive continuity, ICH Q7 inspection readiness maintenance, and GERD diagnosis expansion rates across Southeast Asian outpatient networks. Material deviation in FDA nitrosamine guidance timing or Shandong intermediate supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Drug Allergy Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Global Pediatric Drugs Market