
 Europe Diabetes Drugs Market | 2026-2036
Europe Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Diabetes Drugs Market Foresight
European biologics manufacturing capacity is realigning toward peptide and protein drug production to serve the diabetes pipeline. Novo Nordisk leverages its Danish production network to sustain insulin and GLP-1 supply across Northern Europe. Sanofi anchors its position through basal insulin specialization and broad channel reach into French and Spanish hospital systems. Eli Lilly and Company competes on manufacturing scale for its expanding incretin portfolio.
Europe diabetes drugs comprise pharmacological agents designed to regulate blood glucose through mechanisms including insulin replacement, incretin pathway modulation, and renal glucose excretion inhibition, with formulations requiring cold-chain distribution at two to eight degrees Celsius and precise bioactivity specifications. These therapies serve the clinical management of Type 1 and Type 2 diabetes mellitus across outpatient, inpatient, and self-administration settings. GLP-1 agonists lead product type momentum due to cardiovascular outcome benefits and weight management co-indications, while SGLT2 inhibitors occupy growing share in heart failure-adjacent prescribing. Injectable administration routes dominate biologic delivery, though oral formulations in DPP-4 and emerging GLP-1 classes are gaining pharmacy channel traction.
EMA centralized marketing authorization procedures and the EU MDR device-drug combination requirements shape product entry timelines and post-market surveillance obligations for diabetes drug manufacturers. France's ANSM and Germany's BfArM enforce national pricing and reimbursement controls that directly determine commercial access across the two largest national markets. Stakeholders must monitor evolving HTA convergence between EUnetHTA members and the implementation of joint clinical assessments that will reshape market access negotiations.
Market Dynamics
Cardiometabolic integration is restructuring European diabetes prescribing, as clinicians in Germany, France, and Italy expand GLP-1 agonist use beyond glycemic control into heart failure and renal protection protocols. This clinical paradigm shift is compressing traditional insulin-first pathways and elevating evidence requirements for market access.
Growth Catalysts
- EU MDR device-drug combinations:Streamlined conformity assessment procedures for connected insulin delivery systems are accelerating integrated therapy platform adoption in Dutch and Belgian hospital networks.
- France's ANSM fast-track pathways:Expedited reimbursement reviews for therapies demonstrating cardiovascular outcome benefits are shortening time-to-market for novel incretin classes.
- Peptide manufacturing scale-up:Biologics capacity expansion across Danish and Irish production clusters is resolving cold-chain bottlenecks for GLP-1 supply across Northern Europe.
Market Restraints
- EMA pharmacovigilance burden:Post-authorization safety study mandates for novel diabetes therapies are extending regulatory timelines and inflating clinical development costs by 15-25 percent.
- German BfArM reference pricing:Statutory health insurance reimbursement caps on basal insulin analogs are compressing manufacturer margins and deterring portfolio investment.
- GLP-1 peptide supply concentration:Active pharmaceutical ingredient production for incretin therapies concentrates in a limited number of European contract manufacturing organizations, creating vulnerability to single-source disruptions.
Strategic Opportunities
- Oral GLP-1 formulations:Non-injectible incretin delivery technologies are opening pharmacy-channel access in Spain and Portugal, where self-injection rates remain below Western European averages.
- EUnetHTA joint clinical assessments:Harmonized health technology evaluation procedures across member states are reducing redundant evidence generation requirements for multi-country launches.
- Renal indication expansion:SGLT2 inhibitor labeling for chronic kidney disease is creating new prescribing occasions in Italian nephrology clinics previously outside diabetes specialist reach.
Industry Challenges
- Cold-chain logistics certification:EU GDP compliance for temperature-sensitive biologics distribution requires specialized qualification protocols that smaller national distributors struggle to maintain.
- Endocrinology workforce density:Specialist physician shortages in Eastern European markets limit patient screening capacity and delay therapy initiation for complex diabetes cases.
- Legacy insulin switching friction:Established patient habits and pharmacy reimbursement lock-in mechanisms slow transitions from human insulin to analog therapies despite clinical guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Diabetes Drugs Market |
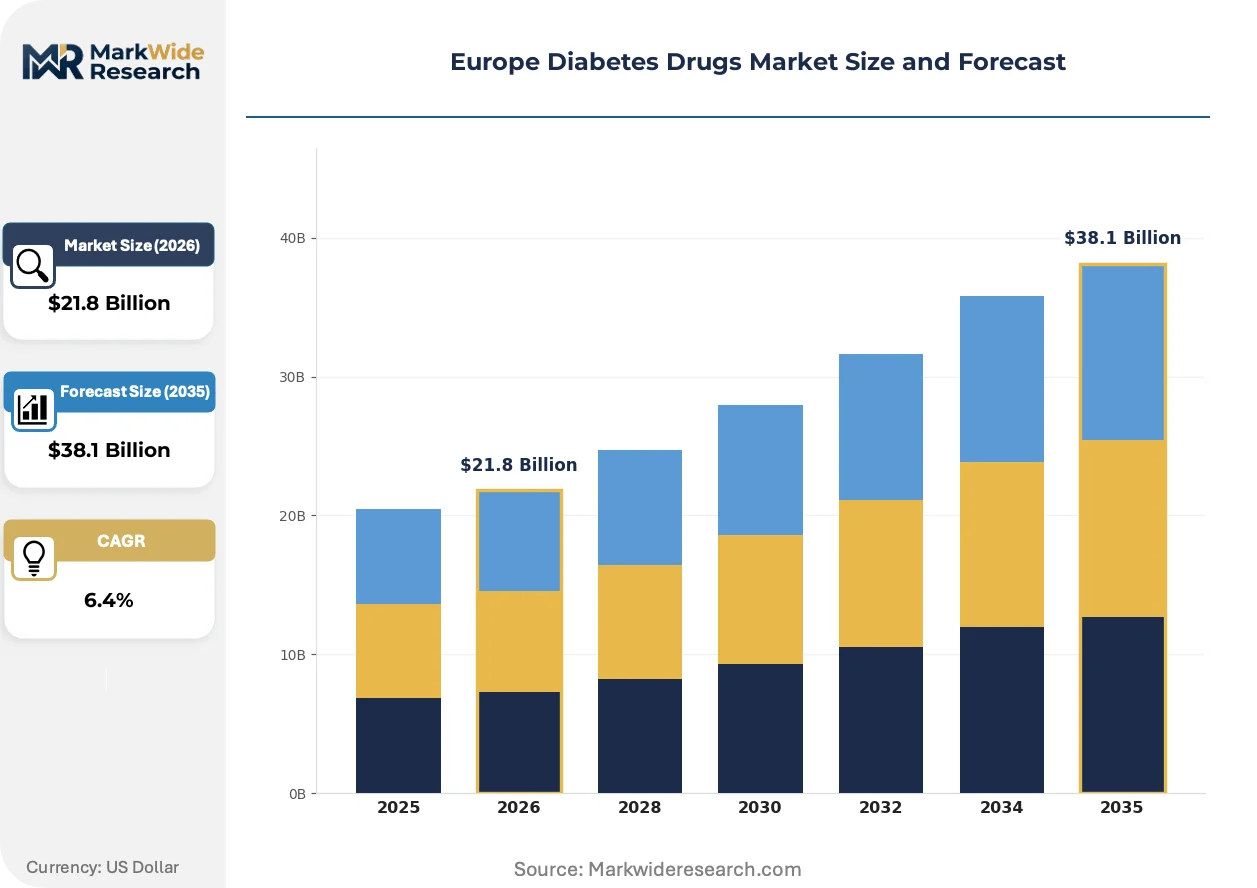
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors End User: Hospitals, Clinics, Pharmacies, Homecare Administration Route: Injectable, Oral, Transdermal, Intranasal Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, AstraZeneca, Boehringer Ingelheim, Merck, Takeda Pharmaceuticals, Novartis, Janssen, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Diabetes Drugs Market Shifts & Advancements
Digital therapeutics and connected delivery devices are merging with pharmacological interventions, creating integrated diabetes management ecosystems that reshape how therapies demonstrate value to European payers.
Continuous glucose monitoring is converging with automated insulin dosing algorithms to form closed-loop artificial pancreas systems. Academic medical centers in Sweden and the Netherlands are piloting these hybrid closed-loop configurations for Type 1 diabetes populations. The technology is converging with traditional pump therapy into single-platform offerings that compress the competitive landscape around integrated device-drug bundles rather than standalone molecules.
The EU MDR's strengthened clinical evidence requirements for device-drug combinations are extending development timelines for smart pen injectors and connected inhalation systems. Manufacturers must now generate prospective clinical data demonstrating added therapeutic value beyond conventional delivery methods. German notified bodies are applying the most stringent interpretation of these rules, making the country's conformity assessment procedures the de facto benchmark for pan-European product design.
Hospital formulary consolidation is concentrating purchasing power across European health systems, with centralized procurement in France and Italy displacing fragmented clinic-level ordering. Large teaching hospitals in Paris and Milan are negotiating multi-year therapy contracts that bundle GLP-1 agonists, SGLT2 inhibitors, and supporting diagnostics into single vendor relationships. This behavioral shift is most pronounced in Southern Europe, where public health system budget pressures have accelerated the transition from physician-driven to committee-based prescribing decisions.
Europe Diabetes Drugs Market Segmentation
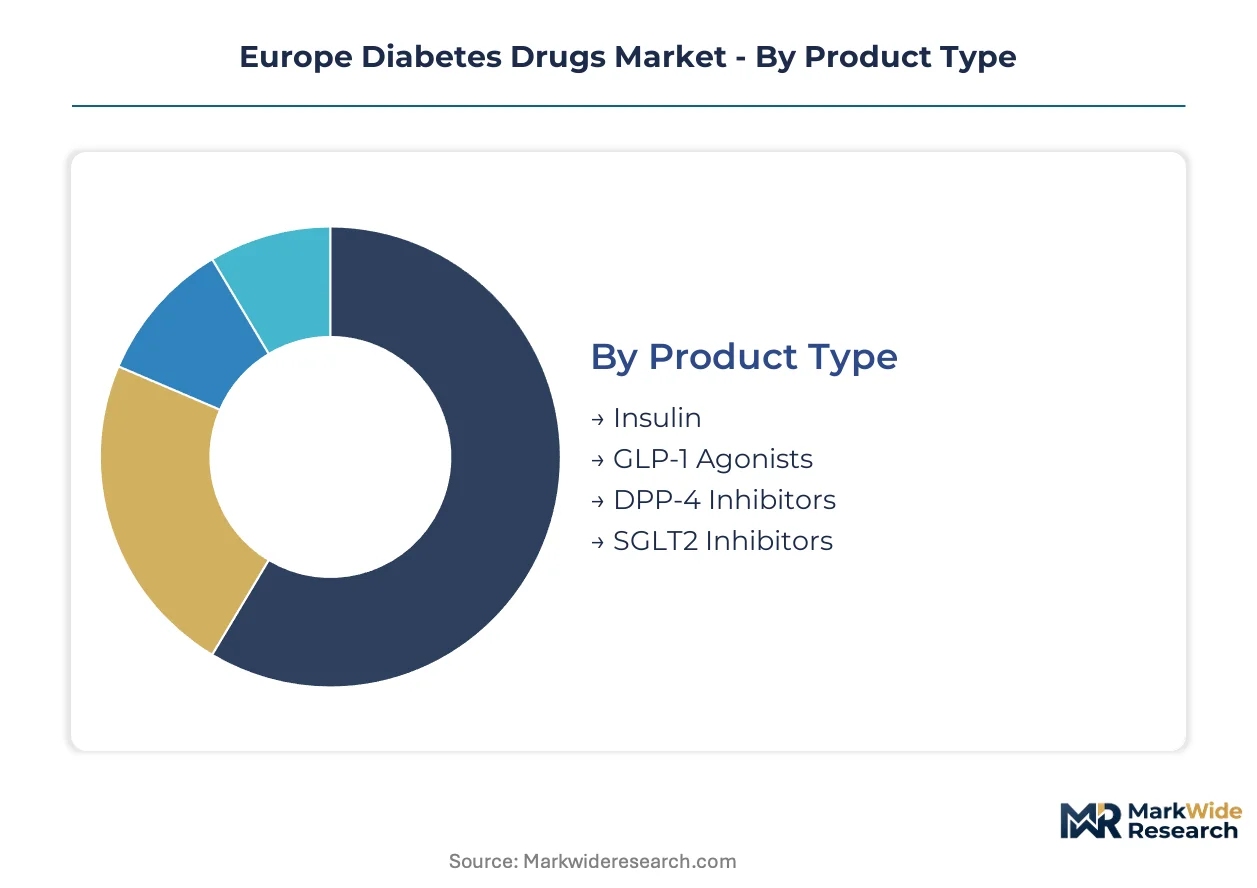
Segmentation reveals how therapy selection and procurement patterns diverge across European health systems. Prescribing authority, reimbursement pathways, and patient self-management capacity create distinct commercial access conditions for each segment combination.
Product Type:
Upgrade cycles in European diabetes care accelerate as cardiovascular outcome data reshapes prescribing hierarchies and displaces older therapeutic classes.
- Insulin:Basal and prandial analog formulations remain foundational for Type 1 management and advanced Type 2 cases. German BfArM reference pricing compresses margins on human insulin, while analog uptake concentrates in French and Italian hospital formularies with outcome-based procurement.
- GLP-1 Agonists:Peptide-based incretin therapies demonstrate cardiovascular and renal protective effects beyond glycemic control. Demand clusters in Western European markets where EMA-approved cardiometabolic indications trigger favorable HTA assessments and hospital protocol integration.
- DPP-4 Inhibitors:Oral gliptin formulations serve as second-line therapy in cost-sensitive prescribing environments. Spanish and Portuguese pharmacy channels favor these agents where injection acceptance lags Northern European averages.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers now carry chronic kidney disease and heart failure indications. Italian nephrology clinics and Dutch cardiology units drive expansion beyond traditional diabetes specialist reach.
Insulin sits at the top of the volume ranking, with GLP-1 Agonists climbing the fastest.
End User:
Cost tier differentiation separates high-acuity institutional prescribing from community-based chronic disease management.
- Hospitals:Acute care centers manage diabetic ketoacidosis, perioperative glycemic control, and complex comorbidity cases. Centralized procurement in Paris and Milan teaching hospitals bundles GLP-1 agonists with diagnostics into multi-year vendor contracts.
- Clinics:Outpatient endocrinology practices initiate and titrate advanced therapies. Specialist density in Stockholm and Amsterdam supports rapid protocol adoption, while Eastern European workforce shortages constrain screening capacity.
- Pharmacies:Community dispensaries handle oral agent fulfillment and patient counseling. French and Spanish pharmacy networks maintain strong insulin dispensing relationships despite hospital formulary consolidation pressures.
- Homecare:Self-administration settings require cold-chain infrastructure and patient education support. Danish and Irish distribution clusters enable reliable peptide delivery to remote Northern European populations.
Hospitals command the highest per-patient revenue tier, though Homecare expands most quickly as self-injection competence spreads.
Administration Route:
Patient acceptance patterns and cold-chain requirements create divergent distribution economics across delivery modalities.
- Injectable:Subcutaneous delivery dominates biologic therapies including insulin and GLP-1 agonists. EU GDP compliance for temperature-sensitive distribution qualifies only specialized logistics providers in Germany and the Netherlands.
- Oral:Small-molecule formulations eliminate cold-chain burden and expand pharmacy channel access. DPP-4 and emerging non-peptide GLP-1 programs target Spanish and Portuguese markets where injection rates trail Western European norms.
- Transdermal:Patch-based delivery systems remain developmental for diabetes applications. EMA MDR device-drug combination rules extend clinical evidence timelines for connected transdermal platforms.
- Intranasal:Nasal spray formulations address needle aversion in specific patient populations. Limited commercial presence reflects bioavailability challenges and regulatory complexity under centralized EMA authorization.
Injectable routes maintain volume leadership, while Oral formulations gain share fastest as peptide engineering advances.
Distribution Channel:
Supply concentration and margin structure vary sharply between consolidated wholesale and fragmented retail endpoints.
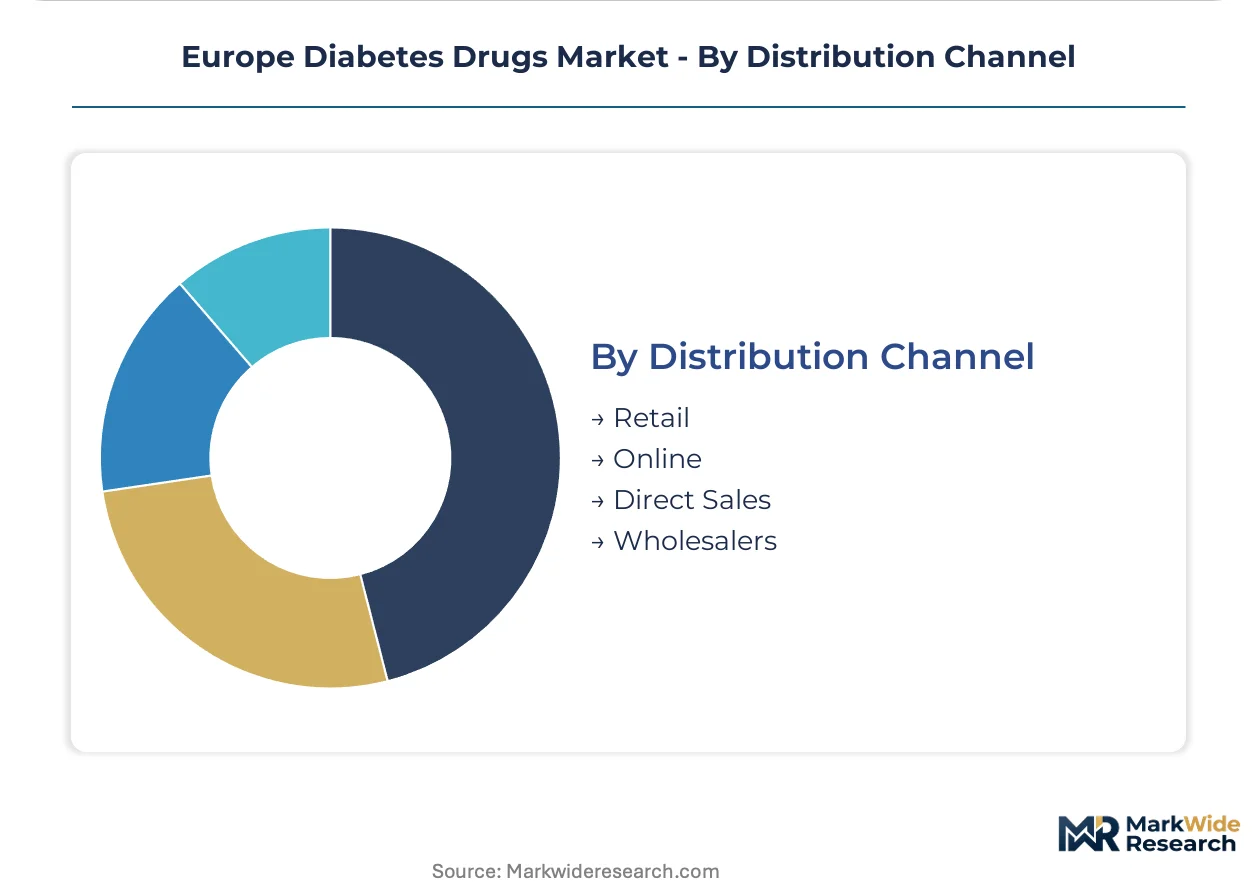
- Retail:Brick-and-mortar pharmacies maintain patient relationships for chronic refill patterns. French ANSM pricing controls and German statutory insurance frameworks determine reimbursement accessibility at the point of dispensing.
- Online:Digital pharmacies and direct-to-patient platforms expand convenience for stable chronic therapies. Dutch and Belgian regulatory frameworks permit remote prescription fulfillment with integrated glucose monitoring data sharing.
- Direct Sales:Manufacturer-to-institution contracts bypass wholesale markups for high-volume hospital agreements. Novo Nordisk leverages Danish production proximity to serve Northern European health systems directly.
- Wholesalers:National distributors aggregate demand across fragmented pharmacy networks. Cold-chain GDP certification requirements in Italy and Spain consolidate wholesale tier toward specialized biologics handlers.
Retail channels handle the greatest prescription volume, with Direct Sales expanding most steeply as hospital consolidation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA centralized authorization procedures and divergent national HTA timelines create arbitrage opportunities, with manufacturers relocating peptide production toward jurisdictions offering streamlined pharmacovigilance pathways and favorable reimbursement negotiation windows.
Germany
Hospital formulary consolidation in Bavaria and North Rhine-Westphalia drives centralized procurement of GLP-1 agonists for cardiometabolic protocols. BfArM reference pricing on basal insulin analogs compresses manufacturer margins while accelerating analog-to-incretin switching. The Rhine-Ruhr pharmaceutical cluster anchors cold-chain distribution infrastructure serving Northern European markets.
France
ANSM fast-track reimbursement pathways for cardiovascular outcome therapies concentrate novel incretin launches in Paris teaching hospitals. Outcome-based procurement bundles at AP-HP institutions displace fragmented clinic-level ordering. The Île-de-France biologics manufacturing corridor supplies peptide APIs across Mediterranean markets.
Italy
SGLT2 inhibitor expansion into nephrology clinics in Lombardy and Emilia-Romagna creates prescribing occasions outside traditional diabetes specialist networks. AIFA pricing negotiations favor therapies with renal protection labeling. The Milan pharmaceutical hub coordinates multi-year vendor contracts consolidating GLP-1, SGLT2, and diagnostic procurement.
United Kingdom
NICE technology appraisals for integrated closed-loop systems accelerate adoption in Greater London and Oxford academic medical centers. NHS England's specialized commissioning framework concentrates high-cost biologic prescribing in tertiary centers. The Cambridge-London life sciences corridor hosts digital therapeutics pilots merging CGM data with automated dosing algorithms.
Spain
Pharmacy-channel preference for oral DPP-4 inhibitors in Madrid and Catalonia reflects lower self-injection acceptance relative to Northern Europe. AEMPS regulatory pathways for non-peptide GLP-1 formulations attract development investment targeting Iberian markets. The Barcelona biotech cluster advances oral incretin delivery technologies bypassing cold-chain requirements.
Europe Diabetes Drugs Market Competitive Landscape
Danish and French producers anchor the biologics tier; Swiss and German specialists hold formulation and device-drug combination positions. The market structure concentrates around three strategic archetypes: integrated peptide manufacturers with captive supply chains, basal insulin specialists leveraging hospital formulary relationships, and oral formulation developers targeting pharmacy-channel access. Competitive moves center on manufacturing scale-up for incretin APIs and strategic partnerships for connected delivery platform certification under EU MDR.
Within the integrated peptide manufacturing tier, Novo Nordisk and Sanofi occupy positions exemplifying geographic production advantages and hospital system anchoring respectively. Eli Lilly and Company represents the scale-driven manufacturing archetype competing on incretin portfolio volume. These three entities collectively illustrate how Danish production proximity, French hospital network integration, and North American manufacturing scale define competitive positioning across European reimbursement environments.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| Boehringer Ingelheim |
| Merck |
| Takeda Pharmaceuticals |
| Novartis |
| Janssen |
| Others |
Supply & Pricing Matrix
Peptide synthesis specialists concentrated in Denmark and Ireland command wage premiums that widen spreads between premium GLP-1 agonists and economy-tier human insulin. Labor-cost differentials across Northern European biologics clusters translate directly into three-tier pricing structures that separate cardiovascular-validated incretins from basal analogs and commodity insulin.
Pricing Analysis
Distributor margins on cold-chain biologics absorb EU GDP compliance costs that inflate wholesale-to-pharmacy spreads. Pricing stratifies across premium, standard, and economy tiers based on cardiovascular outcome certification and manufacturing origin within EMA-regulated zones. Cost compression in basal insulin runs through German BfArM reference pricing caps. Hospital procurement committees demonstrate lowest price sensitivity, while Spanish and Portuguese pharmacy channels exhibit highest elasticity to out-of-pocket differentials.
Supply Chain Analysis
Reverse-logistics networks for temperature-deviated peptide shipments concentrate refurbishment capacity at Danish and Irish production hubs. Active pharmaceutical ingredient manufacturing draws from Denmark, France, and Switzerland. Cold-chain distribution rests on specialized logistics providers maintaining two-to-eight-degree Celsius integrity. Single-source vulnerability in GLP-1 peptide synthesis creates exposure to contract manufacturing organization disruptions. Distribution runs through hospital direct sales in France and Italy, pharmacy wholesale in Spain and Germany, and integrated homecare in Northern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European diabetes drugs constitute a late-cycle quality story as cardiometabolic integration shifts demand toward cardiovascular-validated premium therapies over commodity insulin.
For Market Incumbents: Hedge GLP-1 supply concentration through multi-source peptide manufacturing agreements across Danish and Irish production clusters. Anchor hospital formulary positions through outcome-based procurement bundles that integrate diagnostics with incretin therapies, defending against basal insulin margin compression from German reference pricing. For New Entrants and Emerging Players: Oral non-peptide GLP-1 delivery technologies offer a technology-first wedge into Spanish and Portuguese pharmacy channels where self-injection acceptance lags. Target Iberian markets with pharmacy-centric go-to-market models bypassing hospital formulary gatekeepers. For Investors and Strategic Acquirers: Large-cap pharmaceutical manufacturers with cardiometabolic portfolios are the most active acquirers in this space. Five-to-ten year viability hinges on cardiovascular outcome data assets and EMA regulatory relationships. Monitor EUnetHTA joint clinical assessment implementation as inflection signal for multi-country pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Cardiovascular outcome studies for GLP-1 agonists unlock hospital protocol integration across German and French teaching centers. |
| Manufacturing Scale-Up | Peptide API capacity expansion in Danish biologics clusters resolves supply bottlenecks for Northern European GLP-1 demand. |
| Regulatory Approval Pathway | EMA centralized marketing authorization accelerates pan-European market access for novel incretin formulations. |
| Licensing Agreement | Connected insulin delivery platform partnerships with German notified bodies establish EU MDR device-drug combination benchmarks. |
| Pipeline Diversification | Renal indication expansion for SGLT2 inhibitors penetrates Italian nephrology clinics beyond traditional diabetes specialist networks. |
Research Methodology
Bottom-up hospital and pharmacy demand modeling reconciled against top-down peptide manufacturing capacity tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation from EMA submissions, ClinicalTrials.gov records, hospital formulary databases, and national health technology assessment reports. Triangulation between prescribing pattern data and production volume estimates anchors market sizing.
Input-output matrices map patient population segments against therapy line positioning, administration route adoption curves, and regional regulatory clusters across the projection horizon. Segmentation dimensions include product type, end-user setting, administration route, and distribution channel. CAGRs derive from fitted growth curves applied to therapy-class-specific patient share trajectories. Forecast inputs incorporate EMA approval timelines, HTA convergence patterns, and cold-chain distribution capacity expansion.
The model holds under stable EMA regulatory frameworks and continued HTA convergence; deviation in pharmacovigilance burden escalation or single-source API disruptions would shift volume and value trajectories. Practitioners should monitor EUnetHTA joint clinical assessment rollout and GLP-1 peptide manufacturing concentration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Latin America Biguanide Market