
 Specialty Active Pharmaceutical Ingredients Market | 2026-2036
Specialty Active Pharmaceutical Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Active Pharmaceutical Ingredients Market Outlook
India is narrowing the gap between bulk commodity APIs and high-value specialty molecules through dedicated pharmaceutical parks in Hyderabad and Visakhapatnam. Pfizer Inc. leverages backward integration into biologics manufacturing to protect margins on oncology APIs. Teva Pharmaceutical Industries Ltd. anchors its competitive position in synthetic compounds through vertically integrated production in Eastern Europe. Merck KGaA specializes in high-potency active pharmaceutical ingredients, competing on regulatory compliance depth rather than volume scale.
Specialty active pharmaceutical ingredients are high-purity molecular entities manufactured under stringent current good manufacturing practice conditions, typically requiring chiral resolution, controlled crystallization, or recombinant DNA techniques to achieve therapeutic specificity. These substances serve as the pharmacologically active core of finished drug products, with potency specifications often measured in parts per million for impurities. Biologicals command premium pricing due to cell-line development complexity and cold-chain dependencies, while synthetic compounds retain volume leadership in cardiovascular and infectious disease applications. Oncology applications attract the fastest capacity investments as antibody-drug conjugates and targeted therapies multiply the need for linker-payload expertise. Contract manufacturers represent the most dynamic end-user channel, absorbing risk from pharmaceutical companies retreating from capital-intensive API production.
FDA approval pathways, EMA's active substance master file requirements, and WHO GMP certification standards collectively determine market access for specialty API suppliers, with regulatory divergence between jurisdictions forcing dual-track compliance investments. The EU AI Act and FDA's emerging guidance on continuous manufacturing are accelerating digitalization spending across quality control laboratories. Stakeholders must monitor how regulator alignment on real-time release testing reshapes capital allocation between batch and continuous production platforms.
Market Dynamics
Biotech firms are consolidating captive API production to insulate complex biologics from supply chain fragility, while FDA quality-by-design mandates and EMA impurity thresholds force simultaneous compliance investments across manufacturing footprints.
Growth Catalysts
- EMA tightened impurity thresholds:European regulators now demand parts-per-million specifications for genotoxic impurities, accelerating facility upgrades among contract manufacturers seeking EU market access.
- Antibody-drug conjugate proliferation:Oncology pipelines require linker-payload expertise that commands premium capacity allocation, pulling investment toward high-potency containment infrastructure.
- India's pharmaceutical park concentration:Dedicated fermentation and synthetic chemistry clusters in Hyderabad and Visakhapatnam are absorbing technology transfer from Western innovators seeking cost arbitrage.
Market Restraints
- Solvent cost volatility:Specialty API synthesis relies on acetonitrile and tetrahydrofuran feedstocks whose petrochemical linkage exposes margins to energy price swings.
- Single-source cell line dependency:Mammalian expression systems for biologics concentrate in Chinese hamster ovary banks controlled by a limited supplier base, creating chokepoint vulnerability.
- WHO GMP certification friction:Emerging market manufacturers face documentation burdens that extend timeline-to-revenue by eighteen to twenty-four months versus domestic competitors.
Strategic Opportunities
- Continuous manufacturing adoption:FDA emerging guidance on real-time release testing rewards capital investment in flow chemistry platforms that compress batch cycle times.
- EU AI Act laboratory integration:Predictive quality algorithms embedded in process analytical technology create differentiation for suppliers serving European pharmaceutical innovators.
- CDMO channel expansion:Pharmaceutical companies retreating from capital-intensive API production are outsourcing linker-payload conjugation to specialized contract research and manufacturing organizations.
Industry Challenges
- Containment engineering talent scarcity:High-potency active pharmaceutical ingredient facilities require occupational exposure band 5 expertise that outpaces vocational training pipeline output.
- Legacy batch system integration:Continuous manufacturing retrofits face data architecture conflicts with existing enterprise resource planning infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Active Pharmaceutical Ingredients Market |
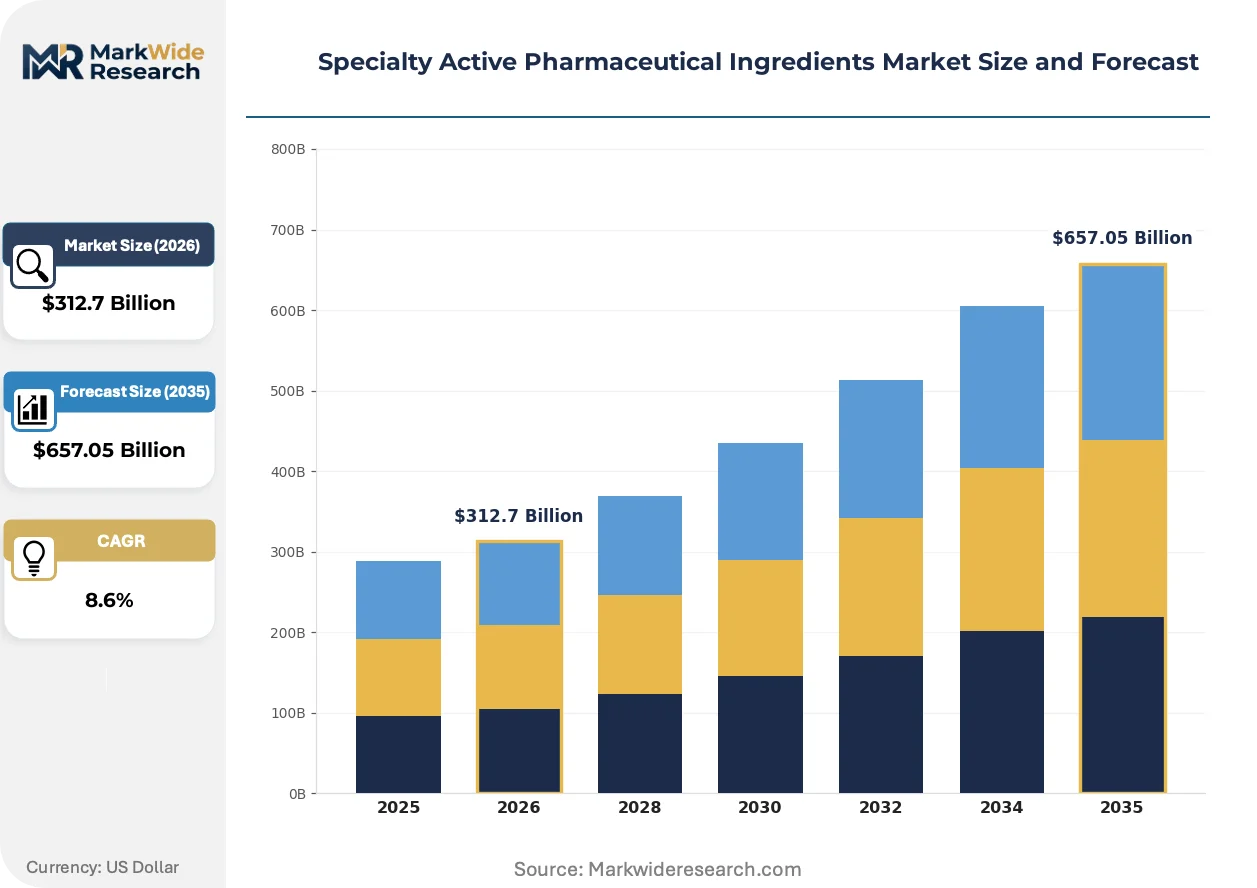
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologicals, Synthetic Compounds, Intermediates, Natural Extracts Application: Oncology, Cardiovascular, Neurology, Infectious Diseases End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Biotech Firms Regulatory Compliance: FDA Approved, EMA Approved, WHO GMP, ISO Certified |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., Merck KGaA, BASF SE, Evonik Industries AG, Sun Pharmaceutical Industries Ltd., Divi's Laboratories Limited, Corden Pharma International GmbH, Asymchem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Active Pharmaceutical Ingredients Market Strategic Shifts
Process analytical technology and artificial intelligence are converging to compress quality assurance timelines, while regulatory divergence between FDA and EMA pathways forces dual-track validation strategies.
Single-use bioreactor systems are rendering obsolete stainless steel fermentation infrastructure for clinical-scale biologics production. Mid-cap biotech developers now specify disposable contact surfaces from phase one trials, eliminating cleaning validation burdens. This shift is compressing facility repurposing timelines from years to months.
EMA's active substance master file requirements now mandate extended impurity profiling for synthetic peptides and oligonucleotides. Contract manufacturers serving European innovators must demonstrate orthogonal analytical method validation. Small-molecule specialists in Eastern Europe are absorbing compliance costs to defend existing customer relationships.
Pharmaceutical procurement teams now require supplier disclosure of secondary source qualification status before contract execution. Large molecule innovators are disqualifying single-site API suppliers regardless of pricing advantage. This pattern concentrates contract awards among manufacturers with validated backup production lines in India.
Specialty Active Pharmaceutical Ingredients Market Segmentation
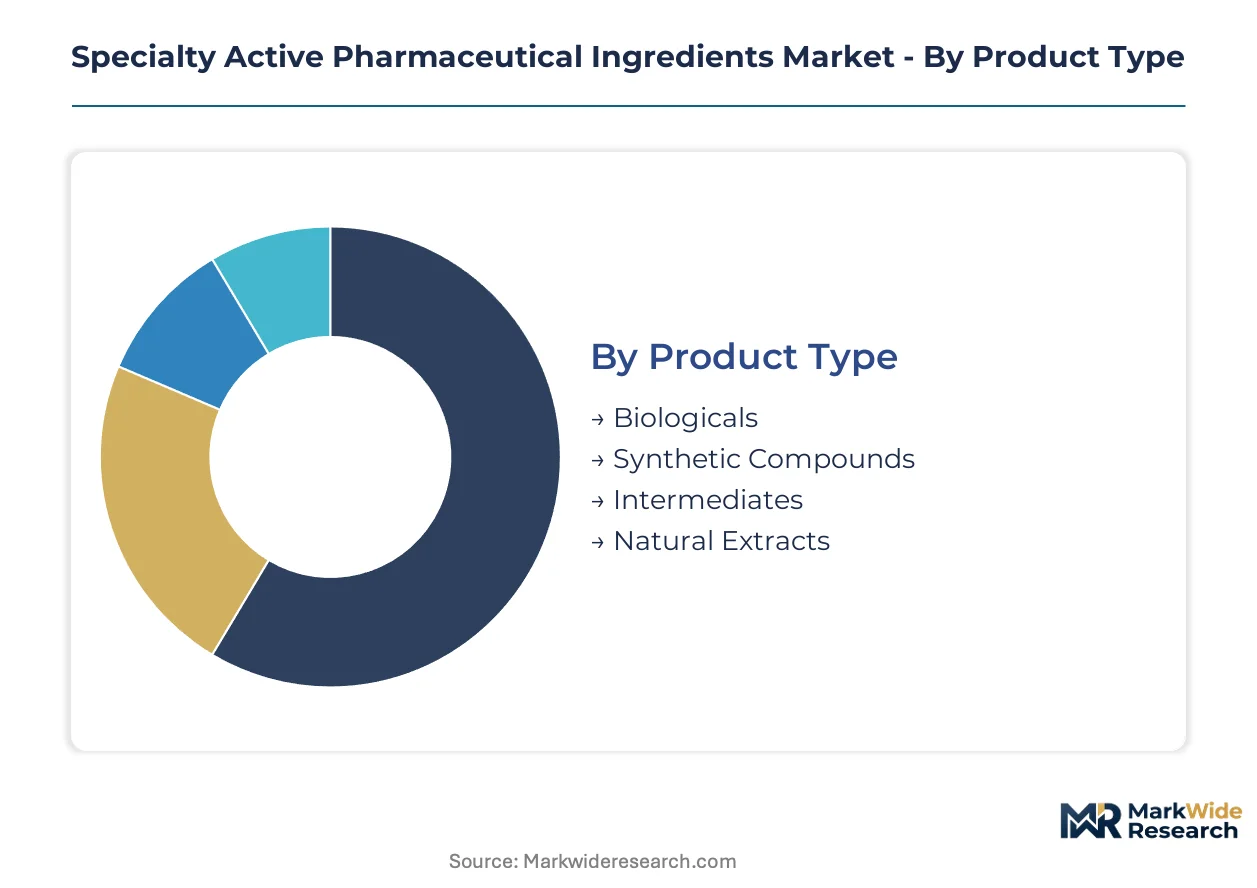
Specialty API procurement patterns diverge sharply across molecular complexity tiers and therapeutic applications. Each segmentation axis reveals distinct margin structures, compliance burdens, and capacity investment requirements that shape supplier selection criteria.
Product Type:
Biologicals and synthetic compounds occupy opposite ends of the manufacturing complexity spectrum, with intermediates and natural extracts filling cost-sensitive niches.
- Biologicals:Recombinant proteins and monoclonal antibodies derived from mammalian or microbial cell cultures require sterile fermentation, viral clearance validation, and cold-chain logistics. Demand concentrates in oncology antibody-drug conjugates where linker-payload expertise commands premium pricing.
- Synthetic Compounds:Small molecules manufactured through multi-step organic synthesis dominate cardiovascular and infectious disease applications. Hyderabad and Visakhapatnam clusters absorb technology transfer from Western innovators seeking cost arbitrage in chiral resolution and controlled crystallization.
- Intermediates:Penultimate chemical stages requiring further modification before API status.
- Natural Extracts:Plant-derived or fermentation-sourced materials for semi-synthetic modification.
Established volume favors synthetic compounds; emerging adoption favors biologicals.
Application:
Oncology and cardiovascular represent the revenue poles, with neurology and infectious diseases tracking divergent regulatory and pricing pathways.
- Oncology:Antibody-drug conjugates, immune checkpoint inhibitors, and targeted kinase inhibitors require high-potency containment infrastructure. CDMOs in India and Eastern Europe are scaling OEB 5 facilities to capture linker-payload conjugation demand from retreating pharmaceutical innovators.
- Cardiovascular:Statins, anticoagulants, and antihypertensives retain synthetic chemistry volume leadership. EMA impurity threshold tightening is forcing facility upgrades among contract manufacturers serving European markets.
- Neurology:Blood-brain barrier penetration requirements drive specialized formulation partnerships.
- Infectious Diseases:Antibiotic and antiviral APIs face pricing pressure from generic substitution.
Cardiovascular maintains the deepest volume base; oncology climbs the fastest.
End User:
Pharmaceutical companies and contract manufacturers split the procurement landscape, with research institutions and biotech firms occupying specialized niches.
- Pharmaceutical Companies:Large innovators are retreating from capital-intensive API production, outsourcing to specialized partners while retaining quality oversight and regulatory filing ownership. Pfizer and Teva anchor captive production only for oncology biologics and high-margin synthetic portfolios.
- Contract Manufacturers:CDMOs represent the most dynamic channel, absorbing technology transfer and compliance risk from pharmaceutical companies. Indian CROs in Hyderabad are scaling fermentation and synthetic chemistry capabilities to serve Western innovators.
- Research Institutions:Academic and government labs requiring gram-to-kilogram scale for early-stage discovery.
- Biotech Firms:Mid-cap developers specifying single-use bioreactor systems from phase one trials to compress facility repurposing timelines.
Pharmaceutical companies retain the largest procurement volumes; contract manufacturers gain share fastest.
Regulatory Compliance:
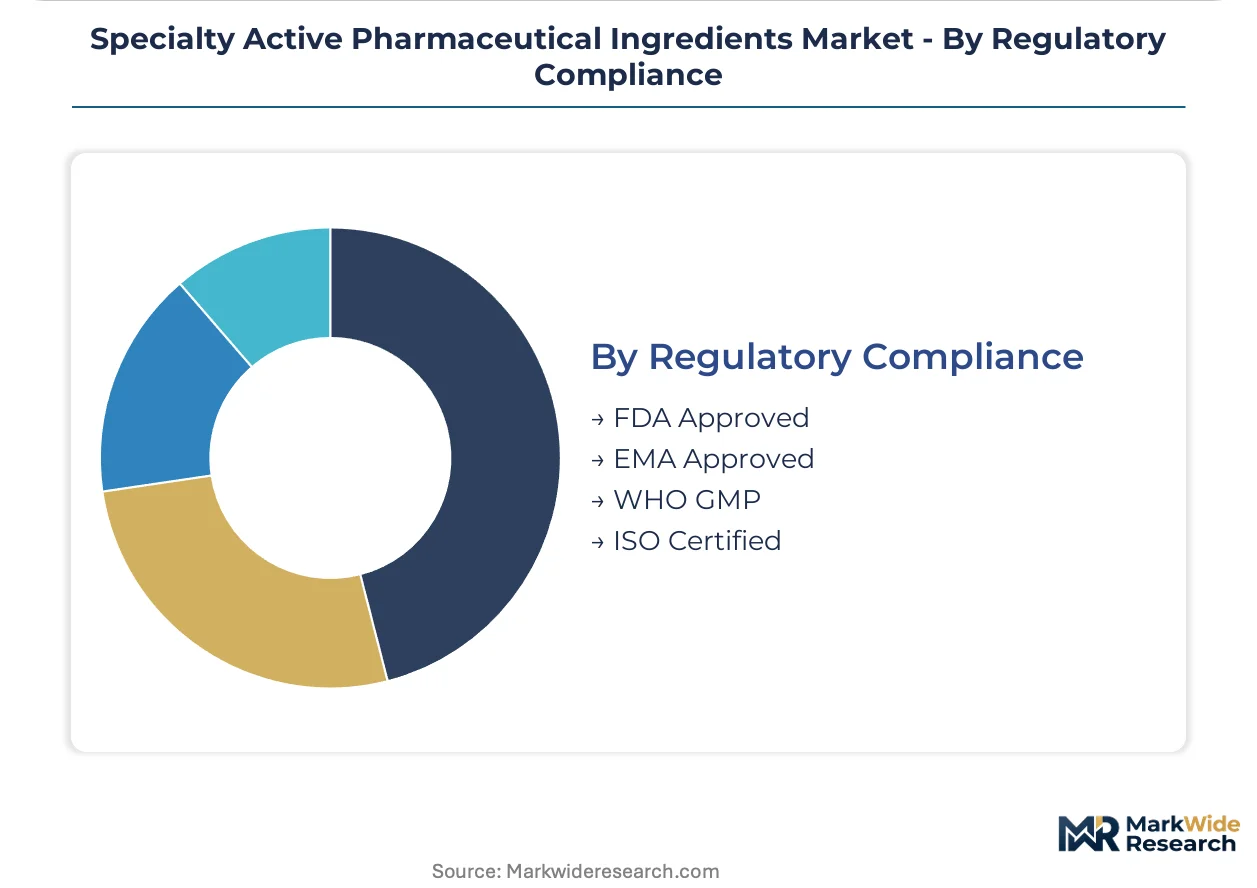
Certification tiers stratify supplier access across jurisdictional markets, with dual-track compliance becoming mandatory for multi-region supply.
- FDA Approved:US market access requires quality-by-design documentation and continuous manufacturing readiness. FDA emerging guidance on real-time release testing rewards investment in process analytical technology.
- EMA Approved:European access demands extended impurity profiling for synthetic peptides and oligonucleotides under active substance master file requirements. Small-molecule specialists in Eastern Europe absorb compliance costs to defend customer relationships.
- WHO GMP:Emerging market manufacturers face documentation burdens extending timeline-to-revenue by eighteen to twenty-four months versus domestic competitors.
- ISO Certified:Baseline quality management certification for non-pharmaceutical industrial applications.
FDA and EMA approvals dominate premium pricing; WHO GMP unlocks emerging market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing capacity clusters in jurisdictions with fermentation infrastructure and synthetic chemistry expertise. Regulatory divergence between FDA and EMA pathways forces dual-track compliance investments among suppliers seeking multi-region market access.
United States
Oncology biologics and antibody-drug conjugates drive domestic demand for high-potency containment facilities. FDA quality-by-design mandates accelerate facility upgrades among contract manufacturers serving innovator pharmaceutical companies. Boston and San Diego biotech corridors concentrate cell-line development and early-stage biologics production.
Germany
High-potency API synthesis and continuous manufacturing platforms anchor the industrial base. EMA active substance master file requirements force extended impurity profiling investments among synthetic peptide specialists. Ludwigshafen and Frankfurt Rhine-Main clusters host integrated chemical-pharmaceutical manufacturing complexes.
India
Contract research and manufacturing organizations scale fermentation and synthetic chemistry capabilities for Western technology transfer. CDSCO and WHO GMP certification timelines extend eighteen to twenty-four months for emerging market entrants. Hyderabad and Visakhapatnam pharmaceutical parks concentrate dedicated API manufacturing infrastructure.
Switzerland
Specialty biologics and high-value synthetic molecules command premium positioning in global supply chains. Swissmedic regulatory standards align with EMA frameworks while maintaining distinct pharmacovigilance requirements. Basel and Zurich clusters integrate pharmaceutical innovation with precision chemical manufacturing.
China
Mammalian expression systems and recombinant protein production expand domestic biologics capacity. NMPA alignment with ICH guidelines accelerates international regulatory convergence for export-oriented manufacturers. Shanghai and Suzhou biotech zones concentrate single-use bioreactor infrastructure for clinical-scale production.
Specialty Active Pharmaceutical Ingredients Market Competitive Environment
Integrated pharmaceutical innovators and specialized contract manufacturers split the market into captive production and outsourced supply channels. Large innovators retreat from capital-intensive API manufacturing while retaining regulatory filing ownership and quality oversight. Three archetypes dominate: vertically integrated biopharma conglomerates, pure-play CDMOs with geographic cost arbitrage, and high-potency containment specialists competing on regulatory compliance depth. Competitive moves center on capacity expansion in India and Eastern Europe, plus strategic partnerships for linker-payload conjugation expertise.
Among integrated pharmaceutical conglomerates, Pfizer Inc. and Merck KGaA occupy positions exemplifying backward integration into biologics and high-potency manufacturing respectively. Within the contract manufacturing tier, Divi's Laboratories Limited and Asymchem Inc. represent archetypes of geographic cost arbitrage serving Western innovators. Sun Pharmaceutical Industries Ltd. anchors a hybrid model spanning captive production and CDMO services.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Merck KGaA |
| BASF SE |
| Evonik Industries AG |
| Sun Pharmaceutical Industries Ltd. |
| Divi's Laboratories Limited |
| Corden Pharma International GmbH |
| Asymchem Inc. |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp chemical corridor freight costs compress margins for synthetic compound shipments while simultaneously widening spreads between FDA-certified and uncertified API tiers. This logistics chokepoint amplifies pricing power for Indian contract manufacturers with validated backup lines, as pharmaceutical procurement teams now mandate secondary source disclosure before contract execution.
Pricing Analysis
FDA quality-by-design mandates dictate the pricing tier structure across the specialty API landscape, separating GMP-certified biologicals from standard synthetic intermediates. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EMA active substance master file holders commanding fifteen to twenty percent premiums over WHO GMP alternatives. Cost compression in commodity cardiovascular APIs intensifies because Hyderabad and Visakhapatnam clusters absorb Western technology transfer. Research institutions exhibit highest price sensitivity due to gram-scale procurement volumes, while oncology biotech developers prioritize linker-payload expertise over unit economics.
Supply Chain Analysis
Divi's Laboratories, Asymchem Inc., and Sun Pharmaceutical anchor contract-manufacturing concentration across high-potency containment and fermentation capacity. Supply concentrates in India, China, and Switzerland, with mammalian expression systems drawing from Chinese hamster ovary cell banks controlled by limited supplier bases. Acetonitrile and tetrahydrofuran feedstock dependencies expose margins to petrochemical price swings. Single-source cell line vulnerability creates chokepoint risk for biologics innovators. Distribution runs through pharmaceutical company quality oversight layers and CDMO technology transfer agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance services and continuous manufacturing technology licensing expand faster than commodity API production, creating durable recurring revenue streams for equipment-attach business models.
For Market Incumbents: Build regulatory filing ownership moats by retaining quality oversight while outsourcing capital-intensive production to Indian CDMOs. Anchor captive capacity only for oncology biologics and high-potency APIs where linker-payload expertise commands premium pricing. EMA impurity threshold tightening threatens margin compression for synthetic compound specialists lacking orthogonal analytical validation. Defend position through backward integration into single-use bioreactor infrastructure and dual-track FDA-EMA compliance investments. For New Entrants and Emerging Players: Mid-market biotech developers in Boston and San Diego corridors represent the most penetrable entry point for single-use fermentation capacity. CDMO channel expansion into antibody-drug conjugate linker-payload conjugation absorbs risk from retreating pharmaceutical innovators. Target WHO GMP certification friction as differentiation angle, compressing eighteen-to-twenty-four month timeline disadvantages through pre-submission documentation services. For Investors and Strategic Acquirers: High-potency containment specialists with OEB 5 facility accreditation and validated European regulatory files offer scarce acquisition targets in a consolidating supplier base. Long-term viability hinges on continuous manufacturing platform readiness and AI-embedded process analytical technology differentiation. Monitor FDA real-time release testing guidance adoption rates as inflection indicator for capital allocation shifts between batch and flow chemistry platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | FDA emerging guidance on real-time release testing rewards flow chemistry platform investments. |
| High-Potency Containment Scale-Up | OEB 5 facility expansion in Hyderabad captures antibody-drug conjugate linker-payload demand. |
| Dual-Track Regulatory Compliance | Simultaneous FDA quality-by-design and EMA active substance master file investments defend EU market access. |
| Single-Use Bioreactor Integration | Disposable contact surfaces from phase one trials compress facility repurposing timelines for biotech clients. |
| AI-Embedded Process Analytical Technology | Predictive quality algorithms under EU AI Act create differentiation for European pharmaceutical innovators. |
Study Parameters
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and customs trade data preceded structured interviews with drug development executives, regulatory affairs leads, CDMO operations directors, and hospital procurement managers. Primary fieldwork captured technology transfer patterns, facility upgrade timelines, and procurement team supplier qualification criteria. Secondary validation triangulated against SEC 10-K disclosures, WHO GMP certification databases, and pharmaceutical park infrastructure announcements. Bottom-up capacity modeling and top-down therapeutic demand projections converged on segment-level estimates.
Assumptions held regulatory pathway convergence and energy price volatility within historical bands while varying biologics pipeline advancement and CDMO outsourcing penetration rates. Segmentation modeling spanned molecular complexity tier, therapeutic application, end-user channel, and regional regulatory cluster dimensions. CAGRs derived from weighted capacity expansion announcements, technology transfer timelines, and pricing spread trajectories across the analysis window. Forecast inputs incorporated single-use bioreactor adoption curves and high-potency containment facility commissioning schedules.
Practitioners should monitor EMA-FDA alignment on continuous manufacturing validation, solvent feedstock price spikes, and CHO cell line supplier consolidation for early signals of forecast revision. Quarterly review of CDMO capacity utilization rates, regulatory filing submission volumes, and pharmaceutical park infrastructure commissioning timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Global Fluorouracil (5FU) Market