
 Asia-Pacific GLP 1 Agonist Market | 2026-2036
Asia-Pacific GLP 1 Agonist Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific GLP 1 Agonist Market Insights
Specialist endocrinologist availability is unwinding across Southeast Asia and India, creating bottlenecks in GLP-1 agonist therapy initiation even as patient eligibility broadens. Novo Nordisk A/S leverages its established insulin infrastructure to anchor pen-device distribution in Japan and South Korea. Eli Lilly and Company sustains manufacturing scale through captive peptide synthesis investments in China. Innovent Biologics competes on cost positioning for hospital tender channels within domestic Chinese markets.
GLP-1 receptor agonists are peptide-based incretin mimetics that activate glucagon-like peptide-1 receptors to potentiate glucose-dependent insulin secretion, with semaglutide demonstrating extended half-life through albumin-binding fatty acid side-chain modification enabling once-weekly subcutaneous dosing. Semaglutide formulations command the dominant revenue position across the product type landscape due to superior glycemic control and cardiovascular outcome data. Subcutaneous injection maintains the leading delivery mode share though oral semaglutide tablets are gaining fastest in Japan's pharmacy-dispensed chronic disease management programs. Homecare end user segments show structural expansion potential as pen-device training protocols simplify self-administration for stable patients.
Japan's PMDA maintains stringent stability testing requirements for peptide therapeutics that extend registration timelines for regional biosimilar entrants. China's NMPA implements priority review designations for obesity-indicated GLP-1 therapies while India's CDSCO requires local bridging studies for imported biologics. Australia's TGA aligns with ICH guidelines yet imposes additional pharmacovigilance reporting that shapes post-market commitment structures. Stakeholders must monitor regulatory divergence between ASEAN harmonization initiatives and national biologics pathways when allocating clinical trial and manufacturing assets.
Market Dynamics
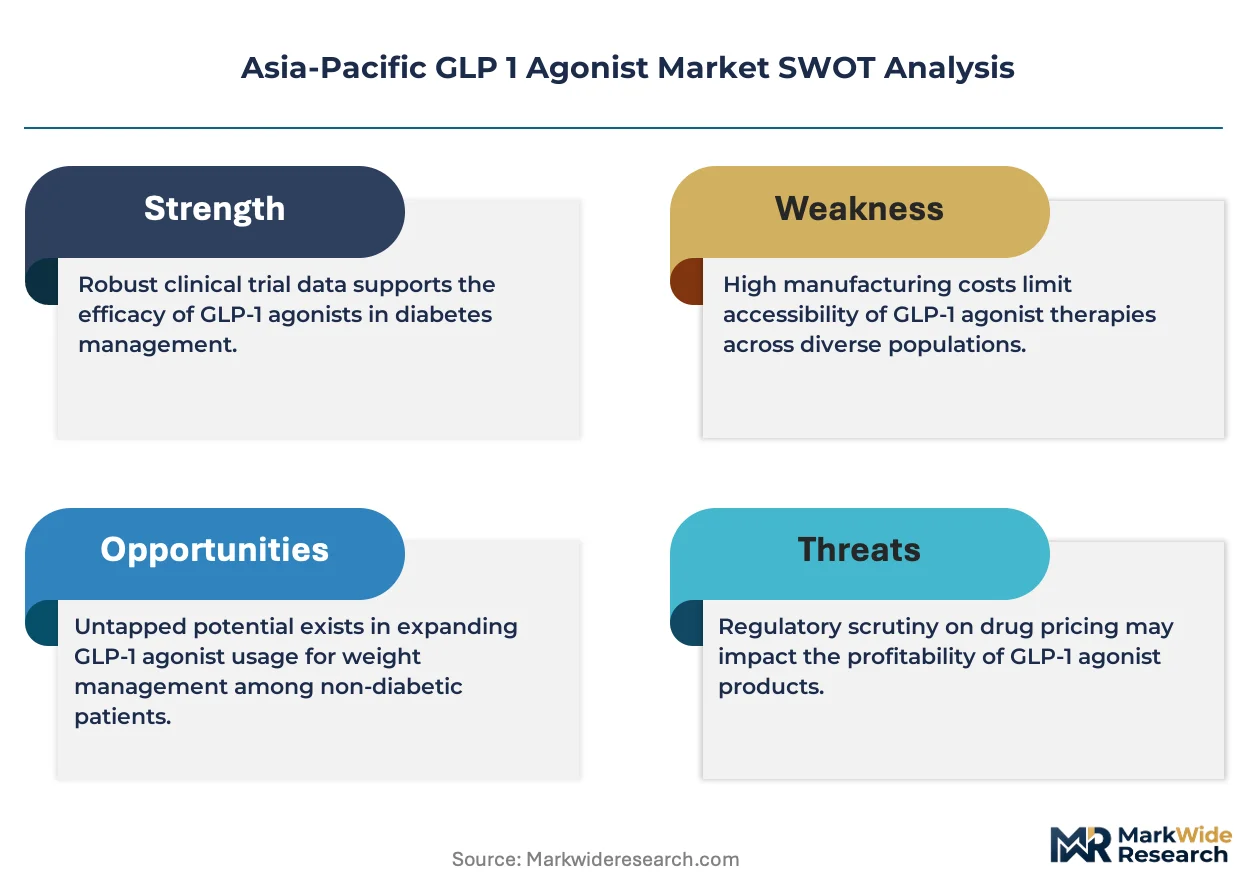
Specialist prescriber density in tier-one Chinese cities and Indian metropolitan hospital networks is compressing therapy initiation timelines while Southeast Asia faces acute endocrinologist shortages that throttle patient access to GLP-1 agonist protocols.
Growth Catalysts
- NMPA Priority Review Designations:China's accelerated pathways for obesity-indicated incretin therapies compress registration timelines and attract biosimilar developers to domestic manufacturing investments.
- Pen-Device Training Protocols:Simplified self-administration programs for stable patients expand homecare end user segments beyond hospital-based injection models.
- Albumin-Binding Fatty Acid Modification:Extended half-life peptide engineering enables once-weekly subcutaneous dosing that reduces clinical burden and improves adherence trajectories.
Market Restraints
- Peptide Synthesis Input Concentration:Captive manufacturing investments by multinational sponsors limit contract manufacturing access for regional biosimilar entrants.
- PMDA Stability Testing Requirements:Japan's stringent peptide therapeutic standards extend registration timelines and elevate capital requirements for market access.
- CDSCO Bridging Study Mandates:India's local clinical data requirements for imported biologics duplicate development costs and delay commercial launches.
Strategic Opportunities
- Oral Semaglutide Dispensing:Japan's pharmacy-dispensed chronic disease management programs create channel expansion potential beyond hospital-centric injection models.
- ASEAN Harmonization Gaps:Divergent national biologics pathways between Singapore, Thailand, and Indonesia create first-mover advantage for sponsors navigating regulatory arbitrage.
- Metropolitan Hospital Network Consolidation:India's tier-one city specialist density supports protocol standardization that accelerates complex injectable therapy initiation.
Industry Challenges
- Endocrinologist Training Bottlenecks:Southeast Asia's specialist availability gaps limit protocol scaling even as patient eligibility criteria broaden across diabetes and obesity indications.
- Pharmacovigilance Reporting Fragmentation:Australia's TGA imposes additional post-market commitments that reshape regional commitment structures and compliance resourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific GLP 1 Agonist Market |
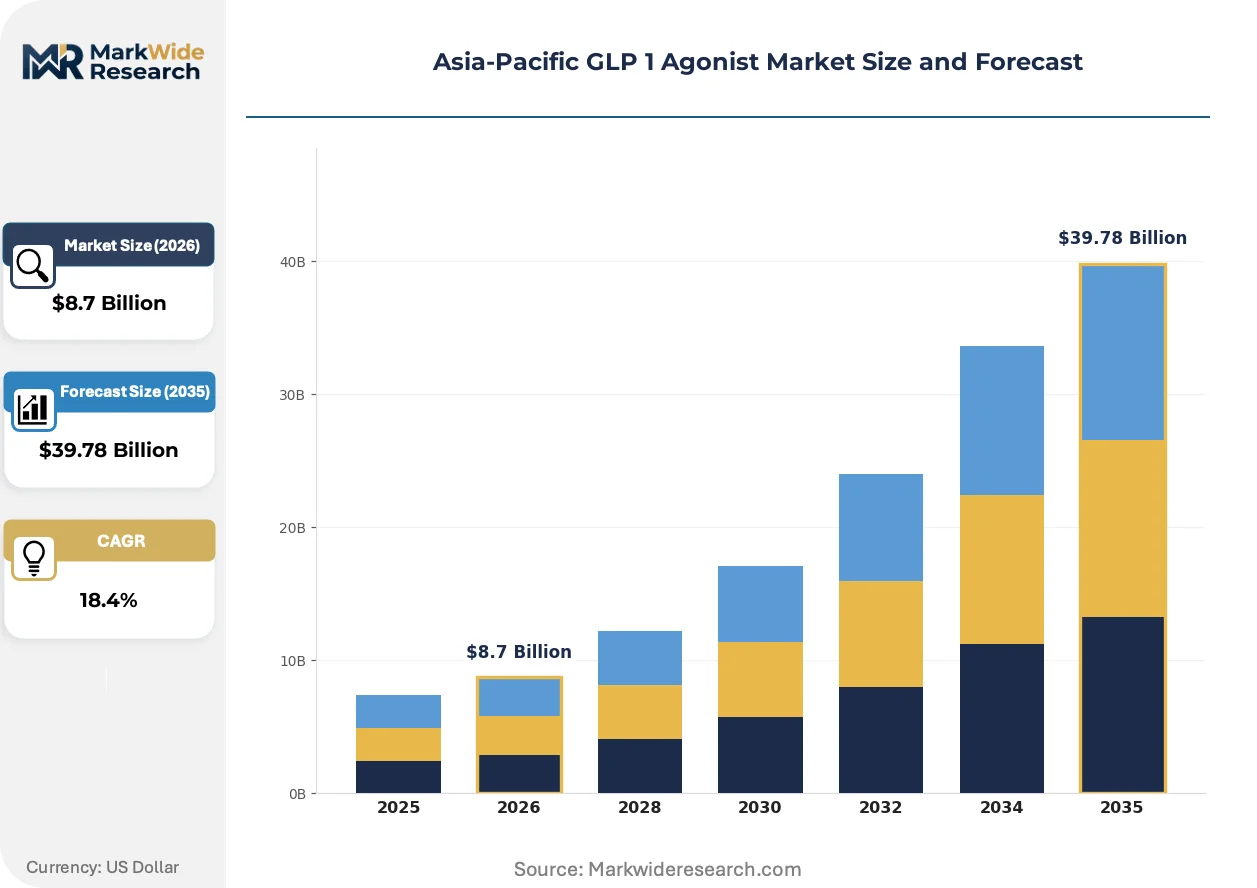
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liraglutide, Semaglutide, Dulaglutide, Exenatide Delivery Mode: Subcutaneous Injection, Oral, Intravenous, Intramuscular End User: Hospitals, Clinics, Pharmacies, Homecare Distribution Channel: Online, Retail, Wholesalers, Distributors |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, AstraZeneca, Sanofi, Biocon Ltd., Novartis, Innovent Biologics, Pfizer, Takeda Pharmaceutical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific GLP 1 Agonist Market Trends and Innovations
Peptide formulation engineering and delivery mode diversification are compressing competitive moats while regulatory pathway specialization is redrawing market entry economics across the region.
Subcutaneous injection technology is fragmenting as oral tablet formulations gain pharmacy channel traction. Japanese dispensing programs now prioritize chronic disease management through retail pharmacy networks rather than hospital outpatient clinics. This shift is fragmenting the historical monopoly of tertiary hospital endocrinology departments on therapy initiation and follow-up care.
NMPA obesity-indicated priority review designations are compressing time-to-market for domestic sponsors while extending compliance requirements for imported products. The policy differential redirects clinical trial investment toward Chinese manufacturing assets and local bridging study infrastructure. Regional biosimilar developers are responding by consolidating peptide synthesis capabilities within domestic free trade zones.
Hospital procurement committees in China's tier-one cities are unbundling device training from drug tender awards. Specialist prescriber networks now negotiate separate service contracts for pen-device education and patient adherence monitoring. This behavioral shift is most visible in Shanghai and Beijing where hospital formulary committees have instituted outcome-linked procurement criteria for diabetes management protocols.
Asia-Pacific GLP 1 Agonist Market Segmentation
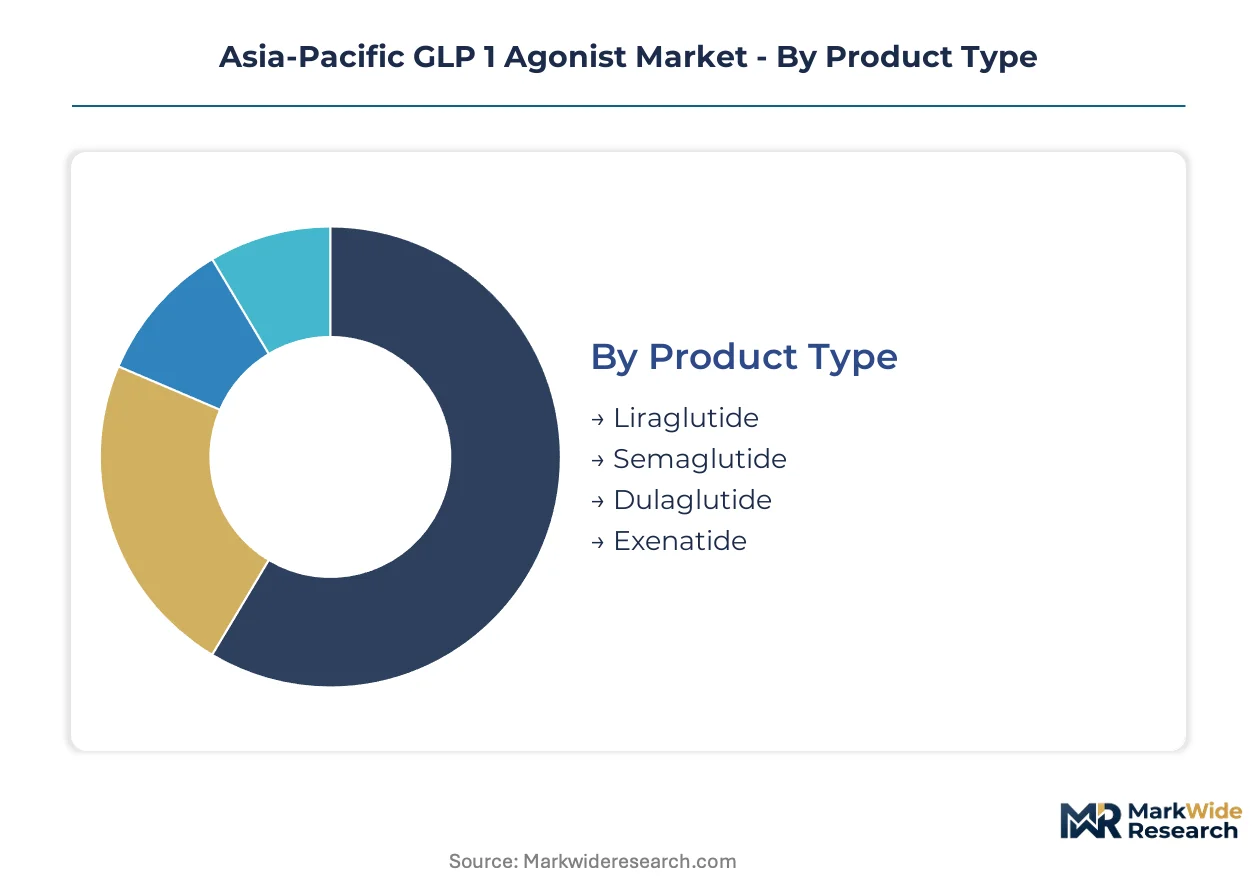
Channel fragmentation across Asia-Pacific GLP-1 agonist markets demands precise segment targeting. Hospital procurement committees, retail pharmacy networks, and direct-to-patient homecare channels each favor distinct product formulations and delivery technologies.
Product Type:
Semaglutide and liraglutide dominate hospital tender channels, while dulaglutide and exenatide compete through retail pharmacy and clinic dispensing networks.
- Semaglutide:Albumin-binding fatty acid side-chain modification enables once-weekly subcutaneous dosing. Shanghai and Beijing hospital formularies prioritize this formulation for cardiovascular outcome protocols.
- Liraglutide:Daily injectable GLP-1 receptor agonist with established reimbursement in Japan's chronic disease management programs. India's metropolitan hospital networks leverage its lower acquisition cost for protocol initiation.
- Dulaglutide:Single-dose pen device simplifies self-administration for stable patients in Australian homecare segments.
- Exenatide:Twice-daily and extended-release formulations serve price-sensitive clinic channels in Southeast Asia.
By volume, semaglutide leads. By growth pace, dulaglutide is expanding most quickly through pharmacy-dispensed models.
Delivery Mode:
Cost tiers separate hospital-based injection therapy from retail-accessible oral alternatives, with intravenous and intramuscular routes serving specialized clinical settings.
- Subcutaneous Injection:Pen-device technology dominates tertiary hospital endocrinology departments across China and South Korea. Patient training protocols now extend into homecare segments.
- Oral:Semaglutide tablets bypass injection barriers in Japan's pharmacy-dispensed chronic disease programs. NMPA review pathways are accelerating oral formulation registrations.
- Intravenous:Limited to inpatient glucose management in Indian metropolitan hospital networks.
- Intramuscular:Emergency department protocols in Australian tertiary centers deploy this route for acute hyperglycemic episodes.
By patient reach, subcutaneous injection leads. By channel expansion, oral formulations are gaining share fastest.
End User:
Customer type determines protocol complexity and device training requirements, from specialist-supervised hospital initiation to self-managed homecare maintenance.
- Hospitals:Tertiary endocrinology departments in China's tier-one cities anchor complex injectable therapy protocols. Specialist prescriber density supports patient selection and dose titration.
- Clinics:India's metropolitan hospital network satellites extend protocol reach into tier-two urban centers.
- Pharmacies:Japan's dispensing programs now manage stable patients through retail channels rather than hospital outpatient clinics.
- Homecare:Pen-device training simplification enables self-administration for adherent patients in Australian and South Korean markets.
By revenue concentration, hospitals lead. By structural expansion, homecare segments show steepest trajectory.
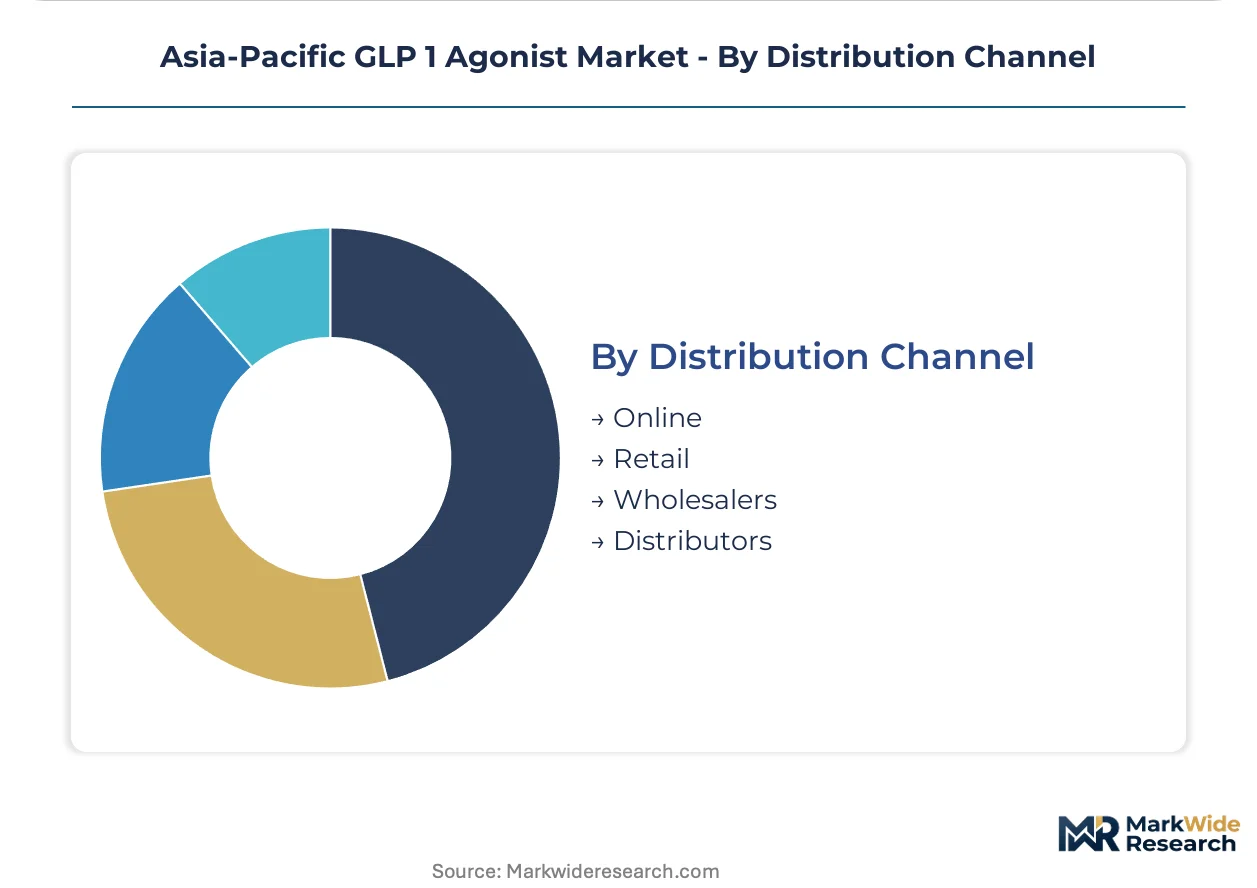
Distribution Channel:
Maturity gradients separate established wholesale-hospital relationships from emerging direct-to-patient digital platforms.
- Online:Direct-to-patient platforms gain traction in Japan's pharmacy-dispensed segments and Australia's remote patient monitoring programs.
- Retail:Brick-and-mortar pharmacies in Japan and South Korea now manage chronic disease medication dispensing.
- Wholesalers:Hospital procurement committees in China's tier-one cities negotiate bulk supply agreements through established pharmaceutical distributors.
- Distributors:Regional logistics networks serve India's metropolitan hospital networks and Southeast Asian clinic chains.
By transaction volume, wholesalers lead. By channel innovation, online platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA accelerated review pathways anchor the Asia-Pacific GLP-1 agonist landscape, compressing registration timelines for obesity-indicated therapies. Specialist prescriber density concentrates in metropolitan hospital networks across China, Japan, and India, while regulatory divergence shapes market entry economics throughout the region.
China
Tier-one city hospital procurement committees in Shanghai and Beijing prioritize semaglutide cardiovascular outcome protocols. NMPA priority review designations for obesity indications attract domestic biosimilar developers toward manufacturing investments in domestic free trade zones. Yangtze River Delta bioclusters concentrate peptide synthesis capabilities serving both innovator and biosimilar supply chains.
Japan
PMDA stability testing requirements for peptide therapeutics extend registration timelines, elevating capital requirements for regional entrants. Pharmacy-dispensed chronic disease management programs in Tokyo and Osaka shift stable patients from hospital outpatient clinics to retail channels. Kanto region specialists now co-manage pen-device training through community pharmacy networks.
India
Metropolitan hospital networks in Mumbai and Delhi leverage liraglutide's lower acquisition cost for protocol initiation in type 2 diabetes. CDSCO bridging study mandates for imported biologics duplicate development costs and delay commercial launches for multinational sponsors. Maharashtra and Gujarat manufacturing zones attract contract peptide synthesis investment serving domestic tender channels.
South Korea
MFDS alignment with ICH guidelines enables faster regulatory convergence for multinational sponsors launching extended-release formulations. Seoul Capital Area tertiary hospitals anchor complex injectable therapy protocols with specialist endocrinologist density comparable to Japan. Busan-Ulsan logistics hubs support pen-device distribution into homecare segments for stable patients.
Australia
TGA pharmacovigilance reporting requirements reshape post-market commitment structures beyond baseline ICH expectations. New South Wales and Victoria hospital networks deploy intramuscular GLP-1 agonist protocols for emergency department hyperglycemic management. Remote patient monitoring programs in Queensland expand direct-to-patient digital platform access for adherent homecare patients.
Asia-Pacific GLP 1 Agonist Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific GLP-1 agonist structure. Multinational pharmaceutical sponsors with captive peptide synthesis capabilities occupy the upper tier, while regional biosimilar developers and domestic biologics firms populate the mid-market. Two strategic archetypes dominate: innovator sponsors leveraging established insulin infrastructure for device distribution, and cost-positioned domestic players competing through hospital tender channels. Competitive moves concentrate on manufacturing scale expansion and regulatory pathway specialization rather than portfolio diversification.
Among integrated multinational sponsors, Novo Nordisk A/S and Eli Lilly and Company exemplify the infrastructure-led archetype, occupying positions anchored by pen-device distribution networks and peptide engineering capabilities. Innovent Biologics represents the domestic cost-competitive tier, sitting within the hospital tender channel specialist group serving China's tier-one city procurement committees. These three players illustrate the structural bifurcation between innovator-sponsored extended-half-life formulations and biosimilar-driven price competition in metropolitan hospital networks.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| AstraZeneca |
| Sanofi |
| Biocon Ltd. |
| Novartis |
| Innovent Biologics |
| Pfizer |
| Takeda Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
NMPA priority review designations gate both manufacturing qualification and price differentiation simultaneously, compressing registration timelines for domestic sponsors while elevating compliance costs for imported biologics that must fund local bridging studies. This regulatory bifurcation concentrates pricing power among sponsors with captive peptide synthesis capabilities in Chinese free trade zones.
Pricing Analysis
Price spreads between innovator semaglutide and domestic liraglutide alternatives widen across China's tier-one hospital networks versus Southeast Asian clinic channels. Three-tier pricing structure across premium cardiovascular-outcome formulations, standard diabetes-management protocols, and economy biosimilar tenders dominates procurement negotiations. Cost compression in economy tiers intensifies as Innovent Biologics and domestic competitors consolidate peptide synthesis capabilities. Hospital procurement committees in Shanghai and Beijing show lowest price sensitivity, while Southeast Asian clinic chains and Indian tier-two distributors exhibit acute budget constraints.
Supply Chain Analysis
Inventory lead times for albumin-binding fatty acid side-chain inputs extend registration timelines for regional biosimilar entrants unable to secure captive synthesis contracts. Peptide manufacturing concentrates in China's Yangtze River Delta bioclusters, India's Maharashtra and Gujarat zones, and South Korea's Busan-Ulsan hubs. Active pharmaceutical ingredient supply draws from Chinese fermentation capacity, Indian contract synthesis infrastructure, and Japanese precision peptide engineering. Single-source vulnerability in fatty acid side-chain modification technology exposes sponsors to input concentration risk. Distribution runs through hospital procurement committees in tier-one Chinese cities, pharmacy-dispensed networks in Japan, and direct-to-patient platforms in Australian remote monitoring programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pen-device training and patient adherence monitoring services attach faster than drug revenue across Asia-Pacific GLP-1 agonist markets, with hospital formulary committees in Shanghai and Beijing now unbundling education contracts from pharmaceutical tenders.
For Market Incumbents: Shield cardiovascular outcome data advantages by deepening specialist prescriber network lock-in across China's tier-one cities. Novo Nordisk and Eli Lilly should expand pen-device training infrastructure into homecare segments before biosimilar competitors consolidate cost positions. Regulatory pathway specialization in NMPA priority review channels remains the critical defensive lever against domestic challengers. For New Entrants and Emerging Players: Differentiate on oral semaglutide dispensing capabilities in Japan's pharmacy-channel chronic disease programs, where hospital outpatient clinic displacement creates white-space expansion. Southeast Asian endocrinologist shortage markets offer penetrable access gaps for simplified self-administration protocols. Target Australia's remote patient monitoring infrastructure with direct-to-patient digital platform partnerships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across peptide synthesis manufacturing as NMPA local production requirements harden. Long-term viability over the next decade favors sponsors with backward integration into fatty acid side-chain modification technology. Acquisition targets should display captive manufacturing assets in Chinese free trade zones or Indian pharmaceutical corridors. Watch NMPA obesity-indication approval velocity as the inflection signal for domestic biosimilar valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pathway Specialization | NMPA priority review designations compress time-to-market for obesity-indicated therapies against PMDA-extended timelines. |
| Manufacturing Scale-Up | Yangtze River Delta bioclusters concentrate peptide synthesis serving both innovator and biosimilar supply chains. |
| Channel Expansion | Japan's pharmacy-dispensed chronic disease programs fragment hospital monopoly on therapy initiation and follow-up care. |
| Device Training Unbundling | Shanghai and Beijing hospital formulary committees now negotiate separate service contracts for pen-device education. |
| Homecare Segment Development | Simplified self-administration protocols enable stable patient migration from hospital injection models to direct-to-patient platforms. |
Research Methodology
The analysis maps semaglutide, liraglutide, dulaglutide, and exenatide sub-sectors, each validated through endocrinologists, hospital procurement managers, regulatory affairs leads, and pharmacy dispensing officers. Primary interview data triangulates against NMPA filings, PMDA submissions, CDSCO bridging study protocols, ClinicalTrials.gov entries, and hospital formulary databases. Bottom-up patient population estimates and top-down manufacturer capacity assessments converge across the analysis window.
Consistency checks validate volume and value outputs against tertiary hospital prescription audit data and regional biosimilar tender award records. Segmentation dimensions span product type, delivery mode, end user archetype, and distribution channel, with regulatory cluster and specialist prescriber density modeled as industry-specific forecast drivers. CAGRs derive from patient eligibility expansion trajectories and reimbursement pathway maturation across the projection horizon.
The analysis sits within stated boundaries; outcomes outside NMPA regulatory continuity, CDSCO bridging study requirements, or PMDA stability testing protocols would require recalibration. Forecasts reflect assumptions about specialist prescriber training pipeline expansion and peptide synthesis input availability. Revision becomes warranted when ASEAN harmonization initiatives or national biologics pathway divergence cross material implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Benzodiazepine Drugs Market