
 Spain Diabetes Devices Market | 2026-2036
Spain Diabetes Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Diabetes Devices Market Analytics
CE marking under the EU Medical Device Regulation (MDR) is bifurcating the competitive landscape between established manufacturers with notified body relationships and newer entrants facing extended conformity assessment timelines. Abbott Laboratories leverages its vertically integrated sensor manufacturing to sustain cost advantages in continuous glucose monitor production. Medtronic plc anchors its position through deep hospital channel relationships and legacy insulin pump installed bases across Spanish endocrinology departments. Dexcom, Inc. differentiates via direct-to-consumer digital onboarding platforms that reduce reliance on traditional clinic-mediated distribution.
Spain diabetes devices encompass electrochemical biosensors, precision microneedle arrays, and algorithm-driven insulin delivery systems designed to maintain glycemic control in diabetic patients. Continuous glucose monitors utilize subcutaneous platinum-wire electrodes with factory-calibrated algorithms measuring interstitial glucose every one to five minutes. Blood glucose meters retain dominant volume share among product types due to universal public reimbursement, though continuous glucose monitors capture expanding margin pools as private payers broaden access criteria. Remote monitoring systems within the technology dimension are accelerating fastest, driven by integration with mobile health apps that transmit real-time data to Madrid-based diabetes education centers.
Spain's national health system reimbursement criteria, shaped by the Ministry of Health and the Spanish Agency for Medicines and Health Products, determine which diabetes devices qualify for public funding and directly influence patient access patterns. The EU MDR and ISO 15197 standards for blood glucose meter accuracy enforce stringent clinical validation requirements that filter market participants. Stakeholders must monitor evolving autonomous community-level procurement centralization, as Andalusia and Catalonia experiment with consolidated purchasing frameworks that could reshape competitive dynamics for device manufacturers.
Market Dynamics
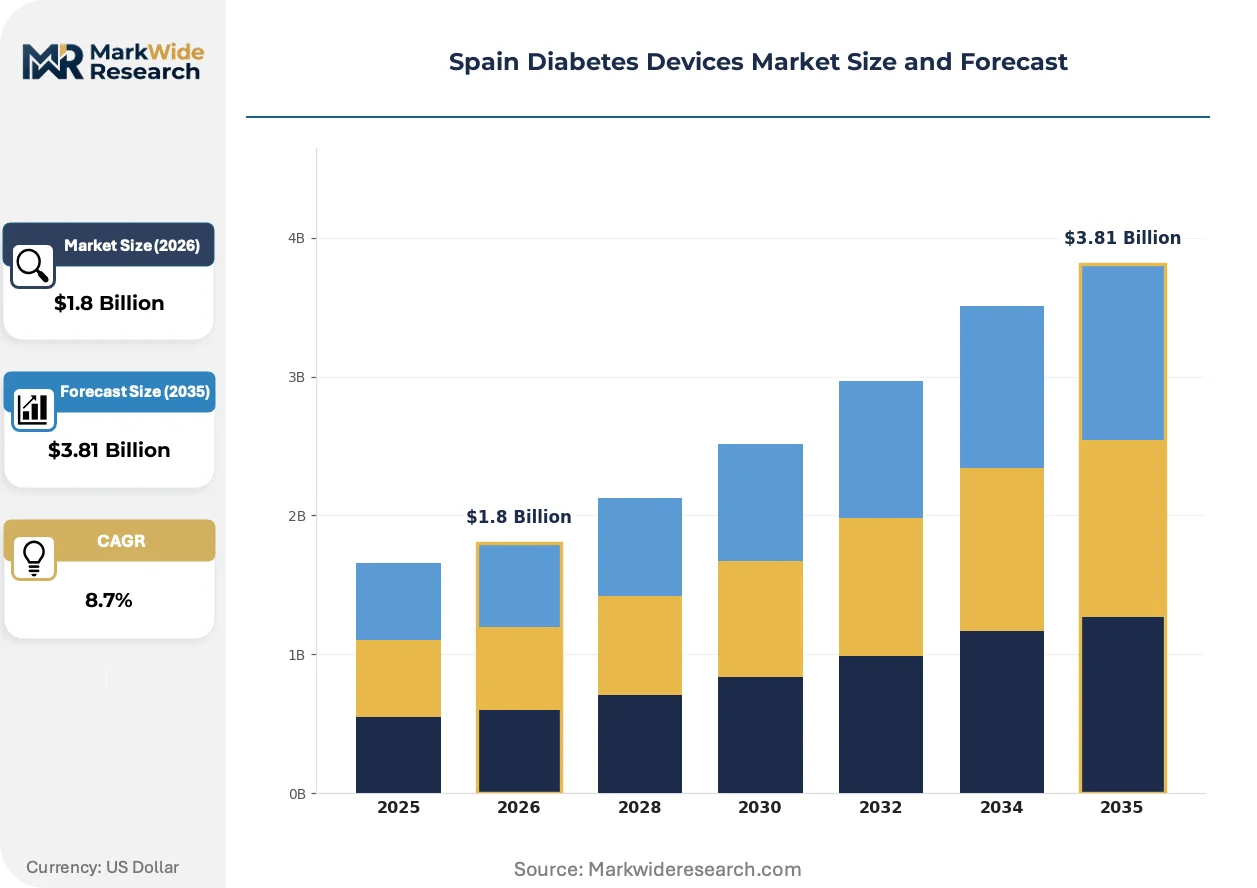
Spain's national health system reimbursement criteria for continuous glucose monitoring systems is redirecting procurement toward connected platforms, while autonomous community-level purchasing centralization in Andalusia and Catalonia consolidates buyer power.
Growth Catalysts
- EU MDR CE marking pathways:Established manufacturers with notified body relationships accelerate market entry timelines while newer entrants face extended conformity assessments, creating competitive asymmetry that favors incumbents with regulatory infrastructure.
- Homecare patient self-management protocols:Self-monitoring glucose systems gain traction among Type 1 diabetes patients seeking reduced clinic dependency, expanding addressable demand beyond traditional hospital-mediated channels.
- Madrid and Barcelona device clusters:Specialized diabetes centers concentrate procurement volume in these metropolitan areas, where private insurance penetration supports premium continuous glucose monitor uptake alongside public reimbursement.
Market Restraints
- Platinum-wire electrode supply concentration:Sensor manufacturing depends on precious metal supply chains concentrated in limited refining geographies, exposing continuous glucose monitor producers to input cost volatility and supply security risks.
- ISO 15197 clinical validation requirements:Blood glucose meter accuracy standards enforce stringent testing protocols that extend product development timelines and elevate R&D expenditure barriers for market entrants.
- Legacy insulin pump installed bases:Medtronic's entrenched hospital channel relationships across Spanish endocrinology departments create switching friction that slows adoption of alternative closed-loop systems.
Strategic Opportunities
- Andalusian consolidated purchasing frameworks:Regional procurement centralization experiments create volume aggregation opportunities for device manufacturers capable of meeting standardized technical specifications at scale.
- Mobile health app integration:Real-time data transmission to Madrid-based diabetes education centers enables remote monitoring service models that differentiate beyond hardware margins.
- Factory-calibrated algorithm advancement:Elimination of fingerstick calibration requirements in next-generation continuous glucose monitors reduces patient burden and expands addressable populations to less technically adept users.
Industry Challenges
- Notified body capacity constraints:EU MDR transition has strained conformity assessment resources, extending certification timelines for novel electrochemical biosensor platforms and delaying revenue recognition.
- Algorithm validation complexity:Machine learning-driven insulin delivery systems require extensive clinical datasets across diverse glycemic profiles, complicating regulatory submission packages and prolonging approval cycles.
- Interoperability standardization gaps:Proprietary data formats between continuous glucose monitors, insulin pumps, and electronic health record systems impede seamless care coordination and limit platform stickiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Diabetes Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Continuous Glucose Monitors, Blood Glucose Meters, Lancets End User: Hospitals, Clinics, Homecare Patients, Diabetes Education Centers Technology: Wearable Devices, Smart Insulin Pens, Mobile Health Apps, Remote Monitoring Systems Application: Blood Sugar Monitoring, Insulin Delivery, Patient Management, Health Reporting |
| Companies Covered | Abbott Laboratories, Medtronic plc, Dexcom, Inc., Roche Holding AG, Novo Nordisk A/S, Ascensia Diabetes Care, Insulet Corporation, Ypsomed Holding AG, Sanofi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Diabetes Devices Market Evolving Landscape
Algorithmic personalization and connectivity integration are actively reshaping competitive differentiation in Spanish diabetes care, moving value capture from discrete hardware toward data-enabled service ecosystems.
Microneedle-based glucose sensing arrays are fragmenting traditional blood glucose meter volume dominance by enabling painless interstitial fluid sampling without lancet penetration. Homecare patients in Catalonia and Madrid are adopting these platforms fastest, driven by reduced physiological barriers to frequent monitoring. The technology is fragmenting procurement patterns as private payers broaden access criteria ahead of public reimbursement parity.
Spain's Ministry of Health reimbursement criteria revisions for continuous glucose monitoring systems are compressing margins on standalone sensors while expanding eligibility for integrated closed-loop configurations. The Spanish Agency for Medicines and Health Products has accelerated review timelines for factory-calibrated devices, privileging manufacturers with robust clinical validation infrastructure. Private insurance channels are responding fastest, adjusting prior authorization protocols to capture outcome improvements from reduced hypoglycemic events.
Direct-to-consumer digital onboarding platforms are displacing clinic-mediated device distribution for tech-savvy patient segments. Dexcom's Spanish market approach exemplifies this channel innovation, reducing endocrinology department dependency and compressing patient acquisition costs. Barcelona's diabetes education centers report highest platform utilization, correlating with metropolitan digital literacy and private payer flexibility.
Spain Diabetes Devices Market Segmentation
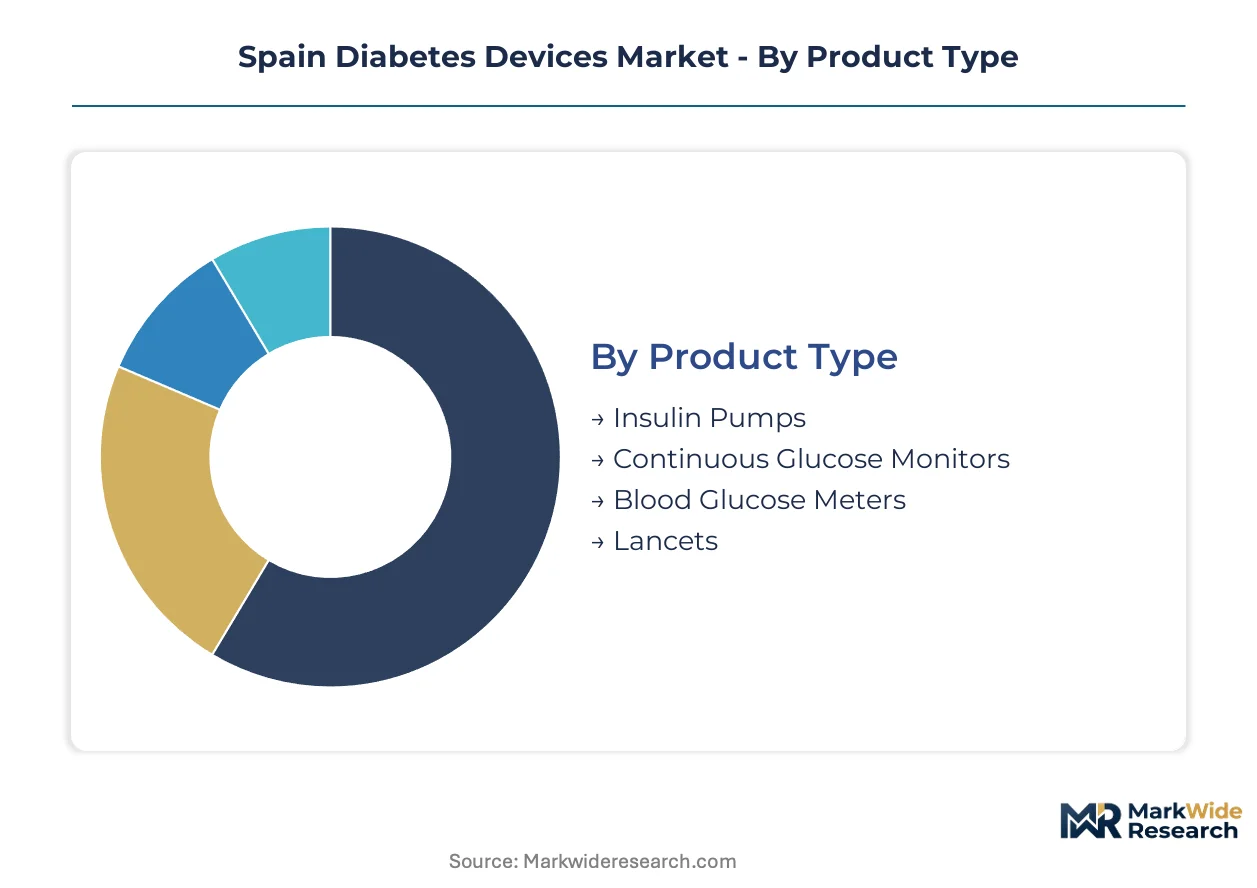
Device substitution pressures reshape procurement patterns across Spain's diabetes care landscape, with connected platforms displacing legacy hardware and algorithm-driven systems fragmenting traditional category boundaries. Understanding segment-level dynamics reveals where reimbursement shifts concentrate volume and which technologies face imminent displacement.
Product Type:
Continuous glucose monitors exert the strongest substitution pressure on blood glucose meters as factory-calibrated sensors eliminate fingerstick dependencies and capture margin migration toward connected platforms.
- Continuous Glucose Monitors:Subcutaneous platinum-wire electrodes with factory-calibrated algorithms measure interstitial glucose every one to five minutes. Demand concentrates in Madrid and Barcelona diabetes centers where private insurance penetration supports premium uptake ahead of SNS reimbursement parity.
- Blood Glucose Meters:Electrochemical biosensors retain dominant volume share due to universal public reimbursement under Spain's national health system. Procurement centralization in Andalusia and Catalonia is compressing per-unit margins while sustaining aggregate volume.
- Insulin Pumps:Precision microneedle arrays and algorithm-driven delivery systems maintain glycemic control through programmable basal-bolus protocols.
- Lancets:Single-use penetrating devices for capillary blood sampling face demand erosion as painless microneedle alternatives gain traction among homecare patients.
Blood glucose meters retain volume leadership; continuous glucose monitors hold the steepest expansion curve.
End User:
Cost tier stratification separates hospital-procured systems from direct-to-consumer channels, with reimbursement eligibility determining which patient populations access premium connected devices.
- Homecare Patients:Self-management protocols gain fastest traction among Type 1 diabetes patients seeking reduced clinic dependency. Madrid and Barcelona metropolitan areas show highest adoption correlating with digital literacy and private payer flexibility.
- Hospitals:Spanish endocrinology departments anchor legacy insulin pump installed bases, creating switching friction that slows closed-loop system migration despite clinical outcome advantages.
- Clinics:Outpatient facilities mediate device distribution for publicly reimbursed populations awaiting SNS criteria expansion for continuous monitoring.
- Diabetes Education Centers:Madrid-based institutions receive real-time data transmissions from remote monitoring platforms, enabling outcome-based service differentiation beyond hardware margins.
Hospitals retain volume leadership; homecare patients hold the steepest expansion curve.
Technology:
Application integration determines competitive positioning as standalone hardware gives way to data-enabled service ecosystems spanning multiple touchpoints in patient care journeys.
- Remote Monitoring Systems:Real-time glucose data transmission to healthcare providers enables proactive intervention and reduces emergency department utilization. Integration with Madrid-based diabetes education centers accelerates fastest among technology categories.
- Mobile Health Apps:Digital onboarding platforms reduce clinic-mediated distribution dependencies and compress patient acquisition costs for continuous glucose monitor manufacturers targeting tech-savvy segments.
- Wearable Devices:Skin-adherent sensor form factors enable discreet glucose tracking without lifestyle disruption for active patient populations.
- Smart Insulin Pens:Bluetooth-enabled dose logging devices bridge manual injection protocols with digital health records for patients not yet requiring pump therapy.
Wearable devices retain volume leadership; remote monitoring systems hold the steepest expansion curve.
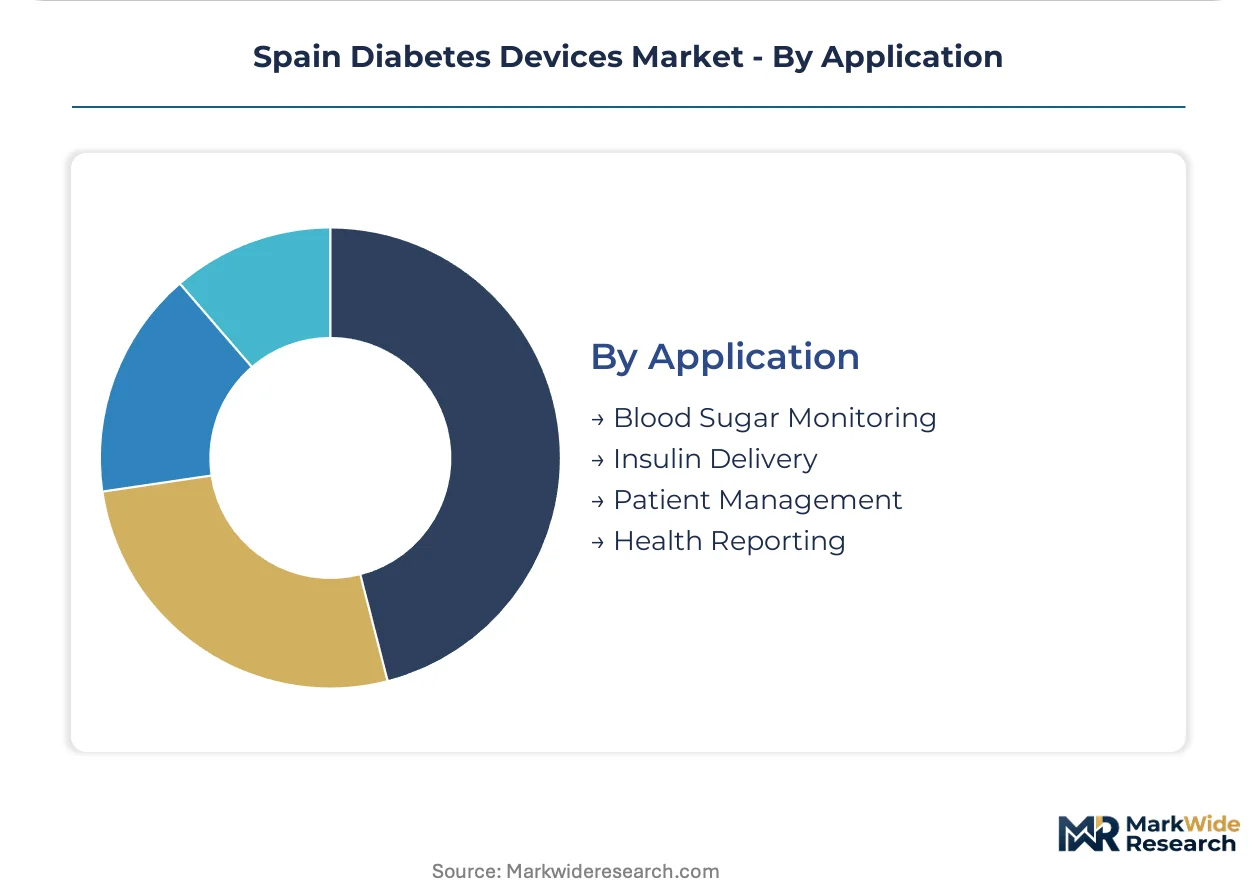
Application:
Maturity gradients separate established monitoring functions from emerging patient management capabilities, with health reporting integration representing the frontier of value capture migration.
- Blood Sugar Monitoring:Core glucose measurement functionality underpins all device categories, with interstitial fluid sampling methods fragmenting traditional capillary approaches in Spanish metropolitan markets.
- Insulin Delivery:Algorithm-driven closed-loop configurations integrate continuous sensing with automated dosing, though Medtronic's entrenched hospital channel relationships slow competitive penetration in Spanish endocrinology departments.
- Patient Management:Comprehensive care coordination platforms aggregate glucose data, medication adherence, and lifestyle factors for holistic diabetes control.
- Health Reporting:Structured data outputs for electronic health record integration and payer documentation requirements enable outcome-based reimbursement models.
Blood sugar monitoring retains volume leadership; health reporting holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in Spain splits sharply between publicly reimbursed hospital procurement and private-payer homecare channels, with metropolitan clusters in Madrid and Barcelona capturing disproportionate device volume.
Madrid
Specialized diabetes centers concentrate procurement volume for premium continuous glucose monitors, driven by private insurance flexibility and digital literacy among Type 1 patient populations. The Spanish Agency for Medicines and Health Products maintains regional offices here, accelerating review timelines for factory-calibrated devices. Madrid-based diabetes education centers receive real-time data transmissions from remote monitoring platforms, enabling outcome-based service differentiation.
Catalonia
Barcelona anchors the steepest adoption curve for direct-to-consumer digital onboarding platforms, correlating with metropolitan tech-savviness and private payer responsiveness. The autonomous community experiments with consolidated purchasing frameworks that aggregate volume across hospital networks. Procurement centralization experiments here compress per-unit margins while sustaining aggregate demand for connected platforms.
Andalusia
Regional procurement centralization creates volume aggregation opportunities for manufacturers meeting standardized technical specifications at scale. The Junta de Andalucía health ministry pilots outcome-based reimbursement models for remote monitoring integration. Seville and Málaga diabetes clinics mediate device distribution for publicly reimbursed populations awaiting SNS criteria expansion.
Basque Country
Osakidetza, the regional health service, maintains stringent cost-effectiveness thresholds for insulin pump reimbursement that slow closed-loop migration despite clinical advantages. Bilbao and San Sebastián hospital networks anchor legacy installed bases, creating switching friction for alternative systems. Industrial sensor manufacturing heritage in the region supports local electrochemical biosensor component supply.
Valencia
The Conselleria de Sanitat Universal i Salut Pública manages procurement for a dispersed patient population across coastal and inland provinces, favoring durable, low-maintenance device formats. Valencia's medical device distribution infrastructure serves as a logistics hub for Levante region supply. Homecare patient segments here lag Madrid and Barcelona in continuous glucose monitor penetration due to lower private insurance density.
Spain Diabetes Devices Market Competitive Landscape
Player mix skews toward diversified medtech conglomerates with established notified body relationships and notified body-dependent sensor specialists facing extended EU MDR conformity timelines. Market structure bifurcates between hospital-channel incumbents with deep endocrinology department relationships and direct-to-consumer entrants compressing patient acquisition costs through digital platforms. Dominant competitive moves include strategic partnerships for algorithm licensing and geographic expansion through autonomous community procurement centralization.
Within the diversified medtech tier, Abbott Laboratories, Medtronic plc, and Dexcom, Inc. occupy positions that exemplify divergent channel strategies. Abbott leverages vertically integrated sensor manufacturing infrastructure. Medtronic anchors hospital-mediated distribution through legacy installed bases. Dexcom represents the direct-to-consumer archetype with digital onboarding platforms reducing clinic dependency.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic plc |
| Dexcom, Inc. |
| Roche Holding AG |
| Novo Nordisk A/S |
| Ascensia Diabetes Care |
| Insulet Corporation |
| Ypsomed Holding AG |
| Sanofi |
| Others |
Value Network & Pricing Analysis
Factory-calibrated algorithm substitution for fingerstick-dependent sensors simultaneously shifts sensor manufacturing toward East Asian electronics clusters and compresses margin capture toward software-enabled recurring revenue models. This dual displacement redraws procurement economics as platinum-wire electrode costs decouple from end-device pricing power.
Pricing Analysis
Cost-plus contracts with platinum-wire electrode indexation dominate continuous glucose monitor procurement between Abbott Laboratories and Spanish hospital networks. Three-tier pricing structure across premium factory-calibrated systems, standard clinician-calibrated devices, and economy-tier blood glucose meters reflects ISO 15197 certification grade and after-sales algorithm update bundling. Pricing pressure stems from Andalusian consolidated purchasing frameworks aggregating volume across autonomous community networks. Public reimbursement channels exhibit highest price sensitivity; private insurance segments absorb premium connected platform markups.
Supply Chain Analysis
Inventory lead times for electrochemical biosensor substrates extend when platinum-wire electrode orders face notified body capacity constraints under EU MDR transition timelines. Manufacturing concentrates in Switzerland for precision microneedle arrays, Ireland for sensor electronics assembly, and Germany for insulin pump mechanical components. Raw material flows draw from South African platinum refining, Taiwanese semiconductor foundries, and Japanese precision ceramics. Single-source vulnerability concentrates in platinum-group metal supply. Distribution runs through Madrid-based medical device logistics hubs serving specialized diabetes centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins compress as remote monitoring service subscriptions expand faster than device shipments, creating attach-rate economics favoring platform-integrated vendors over standalone manufacturers.
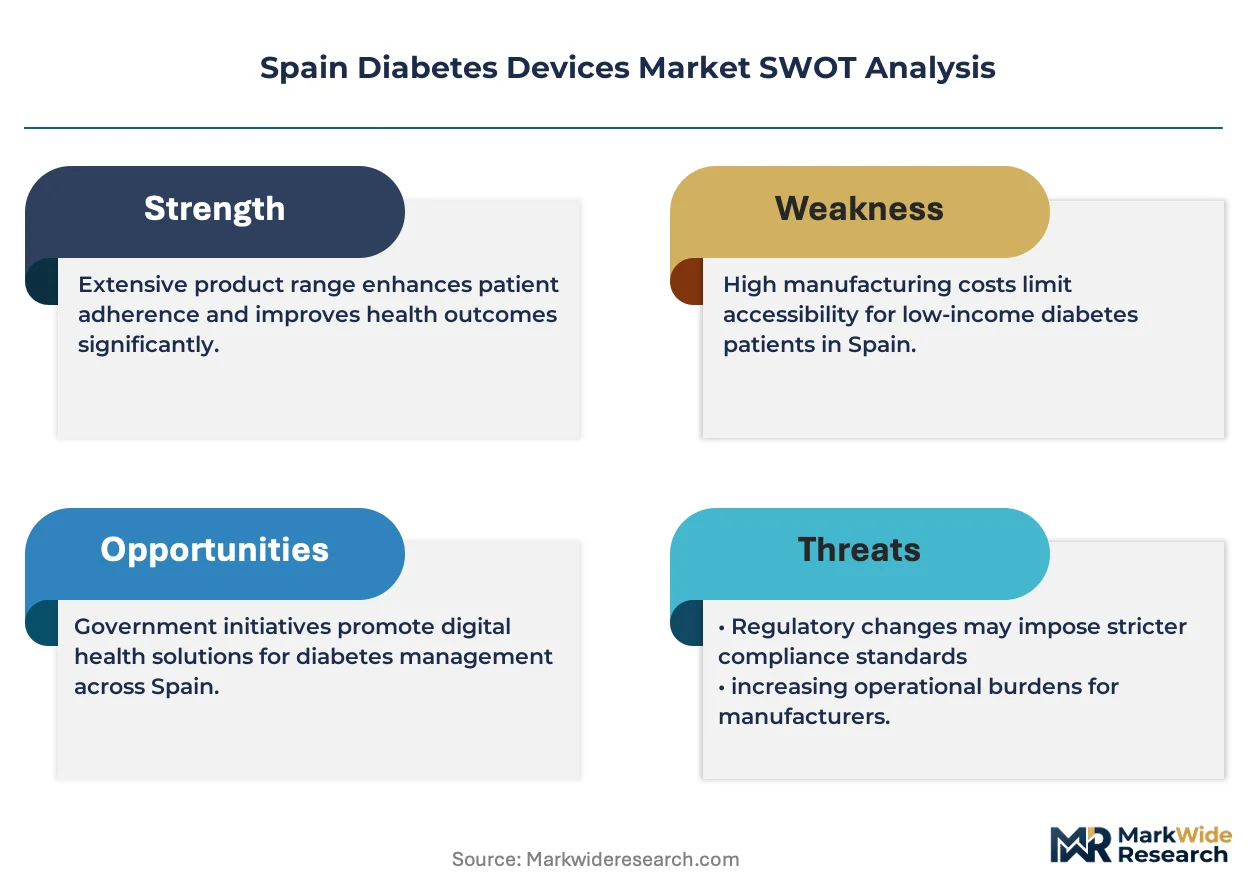
For Market Incumbents: Fortify hospital channel control through deepened endocrinology department partnerships and legacy insulin pump data lock-in. Medtronic's installed base switching friction exemplifies defendable positioning against Dexcom's direct-to-consumer encroachment. Backward integration into captive platinum-wire electrode supply hedges input cost volatility from South African refining concentration. For New Entrants and Emerging Players: Differentiate on algorithm personalization for Type 2 diabetes populations underserved by current factory-calibrated platforms targeting Type 1 patients. Andalusian consolidated purchasing experiments create white-space entry through standardized technical specification compliance at volume scale. Direct-to-consumer digital onboarding in Barcelona bypasses clinic-mediated distribution bottlenecks. For Investors and Strategic Acquirers: The market sits at a platform-integration phase that favors algorithm-specialist acquisition targets over hardware manufacturers. Long-term viability centers on data-enabled service ecosystems spanning glucose monitoring, insulin delivery optimization, and payer outcome documentation. Watch EU MDR notified body capacity expansion as inflection signal for novel electrochemical biosensor platform commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment acceleration privileges established notified body relationships for market entry. |
| Hospital System Partnership | Deepened Spanish endocrinology department ties anchor legacy device installed bases against substitution. |
| Software Companion Development | Mobile health app integration enables remote monitoring service differentiation beyond hardware margins. |
| Reimbursement Strategy | Spanish Agency for Medicines and Health Products criteria alignment determines public funding eligibility. |
| Strategic Partnership | Algorithm licensing agreements with Madrid-based diabetes education centers expand data-enabled care coordination. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement committees, biomedical engineers at specialized diabetes centers, GPO contracts managers, and endocrinology department heads. Secondary validation incorporated EU MDR CE marking databases, Spanish Agency for Medicines and Health Products reimbursement criteria filings, hospital procurement records from Madrid and Barcelona networks, and ISO 15197 accuracy standard documentation. Bottom-up device shipment estimates triangulated against top-down national health system expenditure data.
Across the analysis window, forecasts modeled product type substitution dynamics, end-user channel migration, technology integration intensity, and application maturity gradients. CAGRs derived from segment-level volume trajectories weighted by reimbursement eligibility evolution and private insurance penetration patterns. Algorithm validation complexity and notified body capacity constraints informed continuous glucose monitor adoption curve assumptions.
The analysis sits within stated boundaries; outcomes outside EU MDR transition completion or autonomous community procurement centralization stability would require recalibration. Forecasts reflect documented assumptions regarding platinum-wire electrode supply security and algorithm-driven insulin delivery regulatory pathways. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Clot Management Devices Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Medical Thermometer Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market
Medical Devices
Tumour Ablation Devices Market