
 US Emergency Contraceptive Pills Market | 2026-2036
US Emergency Contraceptive Pills Market Size, Share, and Industry Trends Forecast 2026-2036
US Emergency Contraceptive Pills Market Insights
US generic pharmaceutical manufacturing is pivoting toward hormone-based emergency contraception capacity. Afaxys Pharma leverages its 340B contract pharmacy network to sustain institutional access across federally qualified health centers. Teva Pharmaceutical Industries anchors retail shelf presence through decades of levonorgestrel brand equity. Foundation Consumer Healthcare specializes in direct-to-consumer packaging formats that compete with clinic-dispensed alternatives.
Emergency contraceptive pills are synthetic hormone formulations—primarily levonorgestrel or ulipristal acetate—designed to prevent ovulation or fertilization when taken within specified post-coital windows, typically manufactured through solid-dose compression with exacting dissolution specifications. The product type dimension shows levonorgestrel tablets occupying mature retail volume while ulipristal acetate commands premium positioning through prescription-only status and extended efficacy claims. Distribution channel dynamics reveal pharmacies capturing the bulk of over-the-counter transactions even as online retailers erode geographic access barriers in rural counties.
FDA labeling requirements and DEA scheduling protocols govern manufacturing standards, while state-level pharmacy board regulations determine pharmacist dispensing authority and age verification protocols. The Affordable Care Act preventive services mandate shapes insurer reimbursement posture for prescription-tier products. Stakeholders must monitor state legislature movements on conscience clause expansions and Medicaid formulary inclusion criteria.
Market Dynamics
FDA over-the-counter status expansions for levonorgestrel formulations have dismantled prescription barriers, shifting purchase authority from clinicians to consumers and compressing the traditional pharmacy dispensing workflow.
Growth Catalysts
- Affordable Care Act preventive services mandate:Federal policy frameworks require insurer coverage of prescription-tier emergency contraception, reducing out-of-pocket costs for ulipristal acetate products.
- Pharmacy chain automation:Major retailers deploy self-service kiosks and mobile prescription management tools that streamline OTC hormone product access in high-traffic locations.
- Texas and California metropolitan corridors:Dense population centers with elevated unplanned pregnancy rates concentrate demand for same-day emergency contraception pickup.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for synthetic progestins clusters among a limited set of overseas chemical suppliers, exposing finished dose producers to geopolitical disruption.
- State-level conscience clause expansion:Pharmacist refusal statutes in conservative jurisdictions create access friction for time-sensitive emergency contraception requests.
- Generic substitution economics:Commoditized levonorgestrel pricing compresses margins for branded entrants, discouraging novel formulation investment.
Strategic Opportunities
- Rural telehealth integration:Federally qualified health centers in Appalachian and Great Plains regions leverage 340B pricing to subsidize mail-dispensed emergency contraception for underserved counties.
- Dual-hormone combination development:Next-generation formulations pairing levonorgestrel with anti-inflammatory agents target extended efficacy windows beyond current 72-hour standards.
- Subscription direct-to-consumer channels:Digital pharmacies bypass traditional retail shelf competition by offering advance-stocked emergency contraception kits with automated refill protocols.
Industry Challenges
- Dissolution specification compliance:FDA bioequivalence requirements for rapid-dissolve tablet formats demand specialized analytical chemistry capabilities that contract manufacturers struggle to scale.
- Cold chain integrity for distribution:Temperature-sensitive hormone stability necessitates validated shipping protocols that increase last-mile logistics complexity for e-commerce dispensers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Emergency Contraceptive Pills Market |
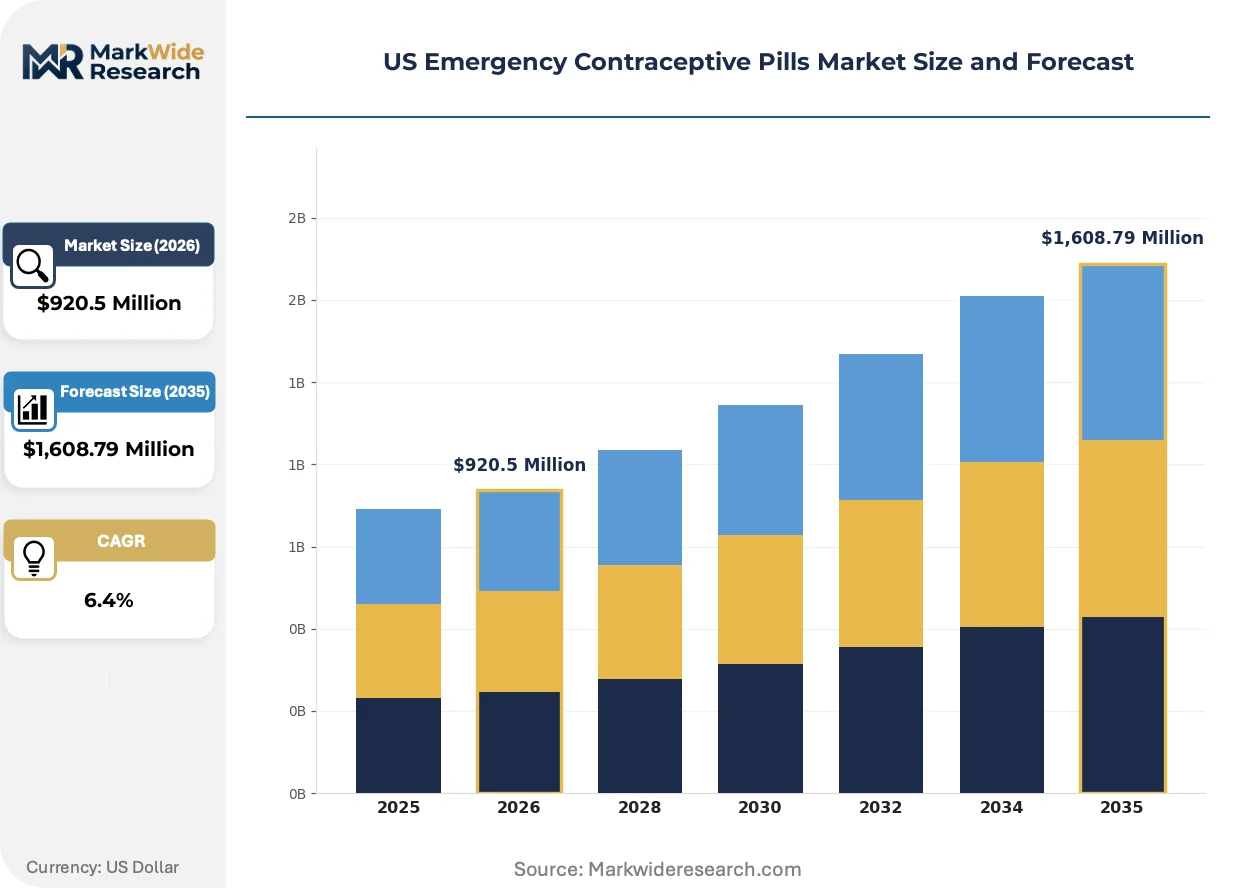
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,608.79 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Levonorgestrel, Ulipristal Acetate, Combined Hormonal Pills, Others Distribution Channel: Pharmacies, Online Retailers, Hospitals, Clinics End User: Women, Teens, Healthcare Providers, Family Planning Services Formulation: Tablet, Micro-Tablet, Softgel, Others |
| Companies Covered | Afaxys Pharma LLC, Teva Pharmaceutical Industries Ltd., Syzygy Healthcare, LLC, Gedeon Richter USA, Inc., Perrigo Company plc, Foundation Consumer Healthcare LLC, Pfizer Inc., Bayer AG, HRA Pharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Emergency Contraceptive Pills Market Trends and Innovations
Formulation science and regulatory pathway evolution are compressing development timelines while consumer-facing technologies reshape how emergency contraception reaches end users.
Orally disintegrating tablet platforms is modularizing solid-dose manufacturing by enabling rapid product line switches between standard and rapid-absorption formats without complete equipment retooling. Contract manufacturers serving generic pharmaceutical clients adopt these flexible production systems to accommodate batch-size volatility from seasonal demand spikes. This modularity is compressing capital requirements for new market entrants and fragmenting production across smaller regional facilities.
FDA labeling harmonization initiatives for OTC switch products are streamlining post-market surveillance requirements for hormone-based emergency contraception, reducing regulatory maintenance burdens for established manufacturers. The industrial consequence accelerates lifecycle management investments toward line extensions rather than defensive compliance spending. Ulipristal acetate prescription-only products face the most significant competitive pressure as levonorgestrel OTC alternatives capture price-sensitive segments.
Advance purchase and stockpiling behavior among reproductive health clinics is displacing just-in-time ordering patterns as organizations buffer against supply interruptions and state policy uncertainty. This inventory accumulation strains distributor working capital and compresses order frequency for wholesale pharmaceutical suppliers. The shift is most visible in Planned Parenthood affiliate networks and student health centers across politically contested Midwestern states.
US Emergency Contraceptive Pills Market Segmentation
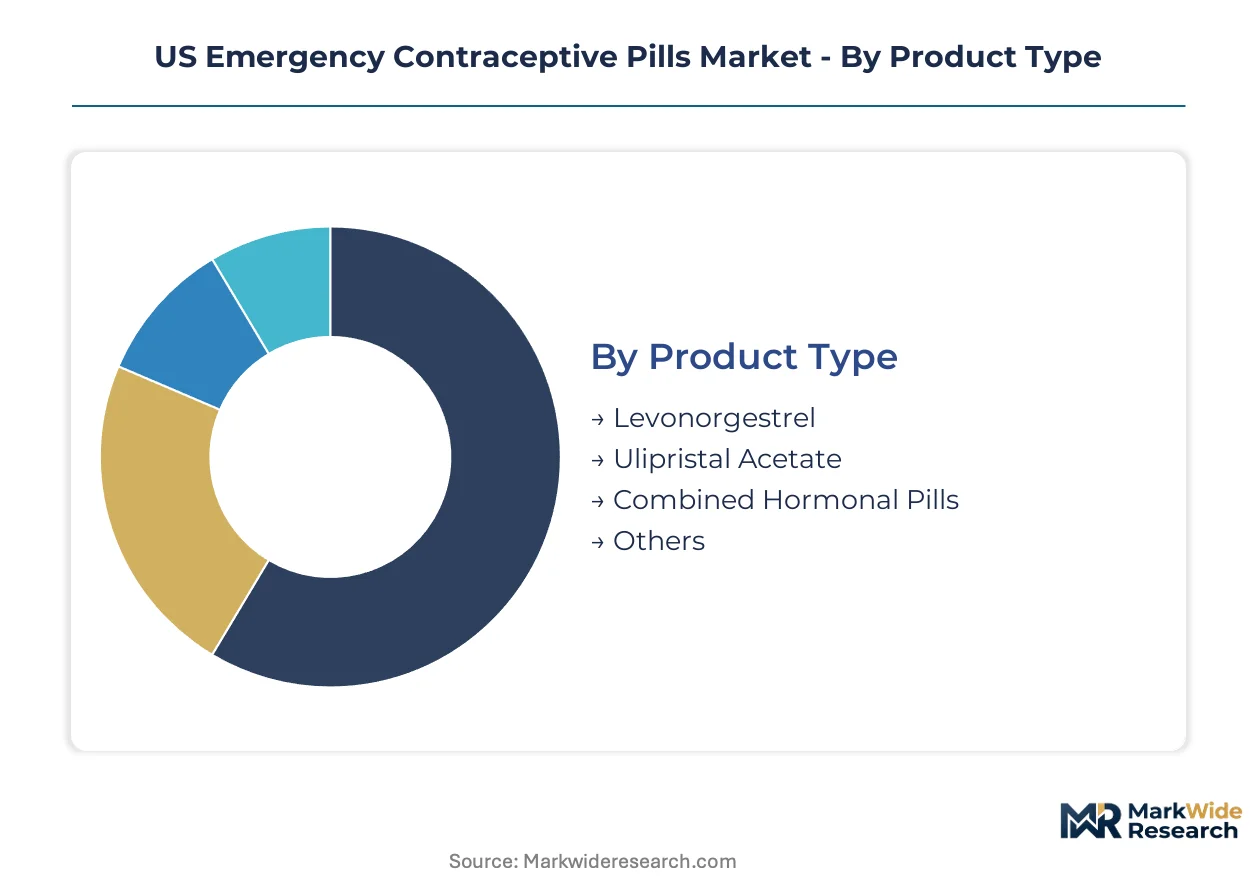
Emergency contraceptive pills segment across four dimensions that determine manufacturing priorities, regulatory pathways, and access economics. Product chemistry and distribution channel structure the bulk of commercial decision-making for suppliers serving the US market.
Product Type:
Active pharmaceutical ingredient sourcing for synthetic progestins clusters among concentrated overseas chemical manufacturers, exposing finished dose producers to supply disruption risks.
- Levonorgestrel:Single-dose synthetic progestin tablets manufactured through solid-dose compression with FDA dissolution specifications. California, Texas, and New York metropolitan corridors concentrate OTC demand where pharmacy chain automation streamlines same-day pickup.
- Ulipristal Acetate:Selective progesterone receptor modulator requiring prescription status and exhibiting extended efficacy to 120 hours post-coitus. The Affordable Care Act preventive services mandate reduces out-of-pocket costs, concentrating uptake among insured patients in family planning clinics.
- Combined Hormonal Pills:Estrogen-progestin combinations with off-label emergency use protocols.
- Others:Mifepristone-based regimens and investigational anti-progestin formulations.
Levonorgestrel absorbs the bulk of installed capacity; ulipristal acetate is expanding most quickly among prescription-tier alternatives.
Distribution Channel:
Channel economics stratify by regulatory status and reimbursement mechanics, with OTC pathways commanding volume and prescription channels capturing margin.
- Pharmacies:Retail chains and independent dispensers handling both OTC levonorgestrel and prescription ulipristal acetate transactions. Self-service kiosks and mobile prescription management tools in high-traffic locations compress dispensing friction for time-sensitive requests.
- Online Retailers:Direct-to-consumer platforms and digital pharmacies bypassing geographic access barriers in rural counties. Cold chain integrity requirements for temperature-sensitive hormone stability increase last-mile logistics complexity.
- Hospitals:Emergency department dispensing for sexual assault protocols and post-coital care.
- Clinics:Federally qualified health centers and Planned Parenthood affiliates leveraging 340B pricing.
Pharmacies capture the dominant transaction volume; online retailers are gaining share fastest through subscription advance-stocking models.
End User:
User segmentation reflects age-verification protocols, privacy preferences, and insurance coverage patterns that shape channel selection.
- Women:Primary consumer demographic aged 18-35 seeking same-day access through retail or clinical channels.
- Teens:Adolescent users navigating state-level pharmacy board age verification requirements and conscience clause barriers in conservative jurisdictions.
- Healthcare Providers:Clinicians prescribing ulipristal acetate and counseling on appropriate product selection.
- Family Planning Services:Institutional purchasers stockpiling inventory against supply interruptions and policy uncertainty.
Women account for the majority of direct purchases; family planning services are expanding procurement fastest through advance-purchase inventory accumulation.
Formulation:
Dosage form engineering determines dissolution kinetics, manufacturing equipment requirements, and patient compliance profiles.
- Tablet:Standard compressed solid-dose format with established bioequivalence pathways. Dissolution specification compliance for rapid-dissolve variants demands specialized analytical chemistry capabilities.
- Micro-Tablet:Reduced-mass formulations enabling faster gastric emptying and absorption onset.
- Softgel:Liquid-filled gelatin capsules with lipid-based drug delivery for enhanced bioavailability.
- Others:Orally disintegrating platforms and chewable formats in development.
Tablet formats occupy the dominant production capacity; orally disintegrating platforms are climbing the fastest as contract manufacturers adopt modular solid-dose systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing for synthetic progestins clusters among concentrated overseas chemical suppliers, exposing finished dose producers to supply disruption risks. Domestic formulation capacity concentrates in metropolitan corridors where pharmacy chain automation streamlines same-day access.
California
Los Angeles and San Francisco metropolitan corridors concentrate the nation's highest emergency contraception transaction volumes. Medi-Cal expansion and state-level reproductive health mandates sustain institutional procurement through federally qualified health centers. The Bay Area biotech cluster anchors analytical chemistry capabilities for dissolution specification compliance.
Texas
Houston and Dallas-Fort Worth corridors drive retail demand through pharmacy chain self-service kiosk deployments. State conscience clause statutes create access friction in conservative jurisdictions, shifting volume toward metropolitan hubs. Planned Parenthood affiliates in Austin advance-purchase inventory against policy uncertainty.
New York
New York City anchors prescription-tier ulipristal acetate uptake through family planning clinic networks. State pharmacy board regulations mandate pharmacist dispensing authority without age verification barriers. The Hudson Valley pharmaceutical manufacturing corridor supplies regional distribution networks.
Illinois
Chicago metropolitan demand concentrates in retail pharmacy and hospital emergency department channels. Illinois Medicaid formulary inclusion criteria shape insurer reimbursement posture for prescription products. Regional 340B contract pharmacy networks subsidize access in underserved collar counties.
Florida
Miami and Tampa corridors exhibit elevated unplanned pregnancy rates driving same-day pickup demand. State legislature movements on conscience clause expansions create geographic access variation between urban and rural counties. Southeastern distributor hubs manage temperature-sensitive hormone stability logistics.
US Emergency Contraceptive Pills Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and distribution channel access. The market structures around three tiers: multinational pharmaceutical conglomerates with decades of brand equity, generic specialists leveraging 340B pricing networks, and direct-to-consumer platforms eroding traditional retail shelf competition. Two strategic archetypes dominate: vertically integrated API-to-dose manufacturers and modular contract manufacturing organizations. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure hormone supply chain resilience.
Within the generic specialist tier, Afaxys Pharma LLC and Teva Pharmaceutical Industries Ltd. exemplify contrasting channel strategies. Afaxys occupies a position anchored in institutional access through federally qualified health centers. Teva sits within retail shelf presence archetypes sustained by levonorgestrel brand recognition. Foundation Consumer Healthcare LLC represents the direct-to-consumer packaging format specialists competing with clinic-dispensed alternatives.
| Leading Market Players |
|---|
| Afaxys Pharma LLC |
| Teva Pharmaceutical Industries Ltd. |
| Syzygy Healthcare, LLC |
| Gedeon Richter USA, Inc. |
| Perrigo Company plc |
| Foundation Consumer Healthcare LLC |
| Pfizer Inc. |
| Bayer AG |
| HRA Pharma |
| Others |
Pricing and Supply Chain Analysis
Active pharmaceutical ingredient costs for synthetic progestins flow from concentrated overseas chemical manufacturers through three distinct pricing tiers downstream, with levonorgestrel commoditization compressing margins at the economy level while ulipristal acetate prescription status sustains premium positioning through insurance reimbursement mechanics.
Pricing Analysis
Prescription counseling and clinical follow-up services bundled with ulipristal acetate sustain premium capture against unbundled OTC levonorgestrel transactions. Three-tier pricing structure across premium, standard, and economy levels separates prescription-tier ulipristal with ACA-mandated coverage from branded OTC levonorgestrel and generic private-label alternatives. Cost compression in the levonorgestrel tier is intensifying because of generic substitution economics and Indian API oversupply. Uninsured cash-pay consumers exhibit highest price sensitivity, driving volume toward economy-tier generics, while insured patients in family planning clinics show lowest sensitivity due to preventive services mandate coverage.
Supply Chain Analysis
Dual-sourcing requirements for hormone API qualification mandate finished dose producers maintain validated supplier relationships across India and China, with backup qualification protocols for domestic manufacturing contingency. Synthetic progestin manufacturing draws from specialized chemical producers in India, China, and select European facilities. Levonorgestrel and ulipristal acetate active ingredients, specialized dissolution testing reagents, and temperature-controlled packaging materials constitute critical input dependencies. Single-source vulnerability concentrates in high-potency hormone API synthesis where regulatory filing requirements lock producers into specific overseas suppliers. Distribution runs through wholesale pharmaceutical distributors with validated cold chain protocols to retail pharmacy chains, federally qualified health centers, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where API supply concentration and FDA bioequivalence barriers force sub-scale generic manufacturers toward exit or acquisition by integrated dose producers with captive analytical chemistry capabilities.
For Market Incumbents: To counter margin erosion from Indian API oversupply, Teva Pharmaceutical Industries and Perrigo Company plc should deepen backward integration into hormone synthesis through contract manufacturing organization partnerships or captive production facilities in FDA-inspected jurisdictions. Securing 340B contract pharmacy network exclusivity across federally qualified health centers provides channel control against Afaxys Pharma's institutional access dominance. For New Entrants and Emerging Players: Capture underserved rural counties in Appalachian and Great Plains regions through telehealth-integrated subscription models that bypass retail pharmacy conscience clause barriers. The most penetrable segment lies in advance-stocked emergency contraception kits for university student health centers, where privacy preferences and policy uncertainty drive institutional procurement shifts. A direct-to-consumer go-to-market angle with automated refill protocols and discreet packaging outflanks traditional clinic-dispensed alternatives. For Investors and Strategic Acquirers: FDA approval of a next-generation dual-hormone combination formulation is the leading indicator that premium prescription-tier positioning will extend beyond current 120-hour efficacy standards, reshaping competitive dynamics. Long-term viability over the coming decade hinges on securing hormone supply chain resilience against geopolitical disruption. Acquisition targets should prioritize modular contract manufacturing organizations with rapid-dissolve tablet platform capabilities and validated cold chain distribution infrastructure. The signal to monitor is state-level Medicaid formulary inclusion criteria shifts that would expand or contract prescription-tier reimbursement access.| Strategic Initiative | Industry Significance |
|---|---|
| API Supply Chain Diversification | Dual-qualification of Indian and Chinese hormone suppliers insulates Teva and Perrigo from geopolitical disruption. |
| Orally Disintegrating Tablet Platform Investment | Modular solid-dose manufacturing systems enable Afaxys Pharma to switch between standard and rapid-absorption formats without retooling. |
| 340B Contract Pharmacy Network Expansion | Institutional access through federally qualified health centers anchors Foundation Consumer Healthcare's clinic-dispensed alternative positioning. |
| Direct-to-Consumer Subscription Launch | Digital pharmacy advance-stocking with automated refill protocols captures privacy-sensitive segments in rural Texas and Florida counties. |
| Dual-Hormone Combination Development | Next-generation formulations pairing levonorgestrel with anti-inflammatory agents target efficacy windows beyond current FDA standards. |
Research Methodology
Document review covered FDA New Drug Application filings, DEA controlled substance manufacturing quotas, and 340B program participation records, complemented by interviews with regulatory affairs directors at generic pharmaceutical manufacturers, pharmacy benefit managers, and procurement leads at Planned Parenthood affiliate networks. Secondary validation drew from CMS Medicaid formulary databases, state pharmacy board dispensing authority regulations, and American College of Obstetricians and Gynecologists clinical practice guidelines. Bottom-up demand modeling across metropolitan corridor transaction volumes was cross-checked against top-down pharmaceutical wholesale shipment data.
Segmentation-level projections across product chemistry, distribution channel, and end-user dimensions were generated through multivariate regression incorporating ACA preventive services mandate coverage expansion, pharmacy chain automation deployment rates, and state-level conscience clause legislative activity. CAGRs were derived from exponential smoothing of historical prescription and OTC transaction volumes adjusted for policy scenario weightings. Forecast inputs included API import customs data from India and China, FDA dissolution specification compliance rates, and telehealth platform adoption curves in federally qualified health center networks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA labeling harmonization initiatives, state legislature movements on pharmacist refusal statutes, and geopolitical disruption to hormone API supply corridors. Deviation in 340B program funding levels or Medicaid formulary inclusion criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Asia-Pacific Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Drug Designing Tools Market