
 Myocardial Infarction Drugs Market | 2026-2036
Myocardial Infarction Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Myocardial Infarction Drugs Market Foresight
Next-generation antiplatelet potency tiers are reorganizing competitive benchmarks across the myocardial infarction drugs landscape. Bristol-Myers Squibb anchors its position through sustained manufacturing scale in oral anticoagulant production. Pfizer differentiates via R&D intensity in novel mechanism cardiovascular therapies. Sanofi leverages its geographic dominance in European hospital formulary channels.
Myocardial infarction drugs comprise pharmaceutical agents designed to restore coronary perfusion, limit myocardial necrosis, and prevent recurrent cardiac events through antithrombotic, anti-ischemic, and cardioprotective mechanisms; these formulations typically demonstrate defined therapeutic windows measured by bleeding risk profiles and platelet inhibition thresholds. The acute phase treatment segment leads in revenue intensity due to emergency department administration protocols and higher per-dose pricing for intravenous thrombolytics. Injectable delivery methods represent the fastest-growing structural category as pre-hospital and cath-lab administration expands. Preventive care applications remain mature with stable statin prescribing patterns.
The FDA's breakthrough therapy designation and the EMA's PRIME scheme are accelerating market access for novel antiplatelet candidates while tightening cardiovascular outcome study requirements. The EPA's pharmaceutical manufacturing effluent guidelines and the EU's REACH framework are reshaping active pharmaceutical ingredient sourcing standards for cardiac drug producers. Stakeholders must monitor evolving pharmacovigilance mandates from the FDA and EMA that increasingly require real-world evidence for post-approval safety verification of combination antithrombotic regimens.
Market Dynamics
The myocardial infarction drugs market is restructuring around pre-hospital administration protocols that compress treatment windows from hospital arrival to first drug delivery. Emergency medical services now carry intravenous thrombolytics and oral antiplatelet loading doses, shifting revenue capture from inpatient pharmacy budgets to ambulance formulary contracts.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses Phase III timelines for novel antiplatelet candidates, enabling earlier commercialization of P2Y12 inhibitors with superior bleeding profiles.
- Integrated Stroke-Heart Attack Networks:United States hospital systems are standardizing dual-antiplatelet protocols across emergency departments, creating formulary lock-in for preferred agents.
- Injectable Formulation Innovation:Lyophilized thrombolytic presentations enable ambient-temperature storage in catheterization labs, expanding administration points beyond centralized pharmacy operations.
Market Restraints
- Heparin Active Pharmaceutical Ingredient Concentration:Over 70% of unfractionated heparin API originates from Chinese pig farming regions, exposing supply chains to zoonotic disease disruptions and trade policy volatility.
- EMA Pharmacovigilance Mandates:Post-approval cardiovascular outcome study requirements for combination antithrombotic regimens extend development costs and delay label expansion into secondary prevention.
- Generic Statin Saturation:Atorvastatin and rosuvastatin commoditization eliminates pricing power in the preventive care segment, compressing manufacturer margins on stable chronic therapy prescriptions.
Strategic Opportunities
- Pre-Hospital Emergency Medical Services Channel:Ambulance formulary access remains underpenetrated outside Germany and the United States, offering first-mover advantage for rapid-dissolution oral antiplatelet formulations.
- EU Green Deal Pharmaceutical Manufacturing Standards:REACH framework compliance for cardiac drug API sourcing creates competitive differentiation for manufacturers with verified green chemistry supply chains.
- Anticoagulant-Antiplatelet Convergence:Fixed-dose combination therapies integrating factor Xa inhibition with P2Y12 blockade address polypharmacy adherence gaps in elderly post-MI populations.
Industry Challenges
- Interventional Cardiologist Training Bottlenecks:Percutaneous coronary intervention volume requirements for thrombolytic administration certification limit cath-lab expansion in community hospital settings.
- Legacy Electronic Health Record Integration:Emergency department medication order sets require manual reprogramming to accommodate new antiplatelet potency tiers, delaying protocol adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myocardial Infarction Drugs Market |
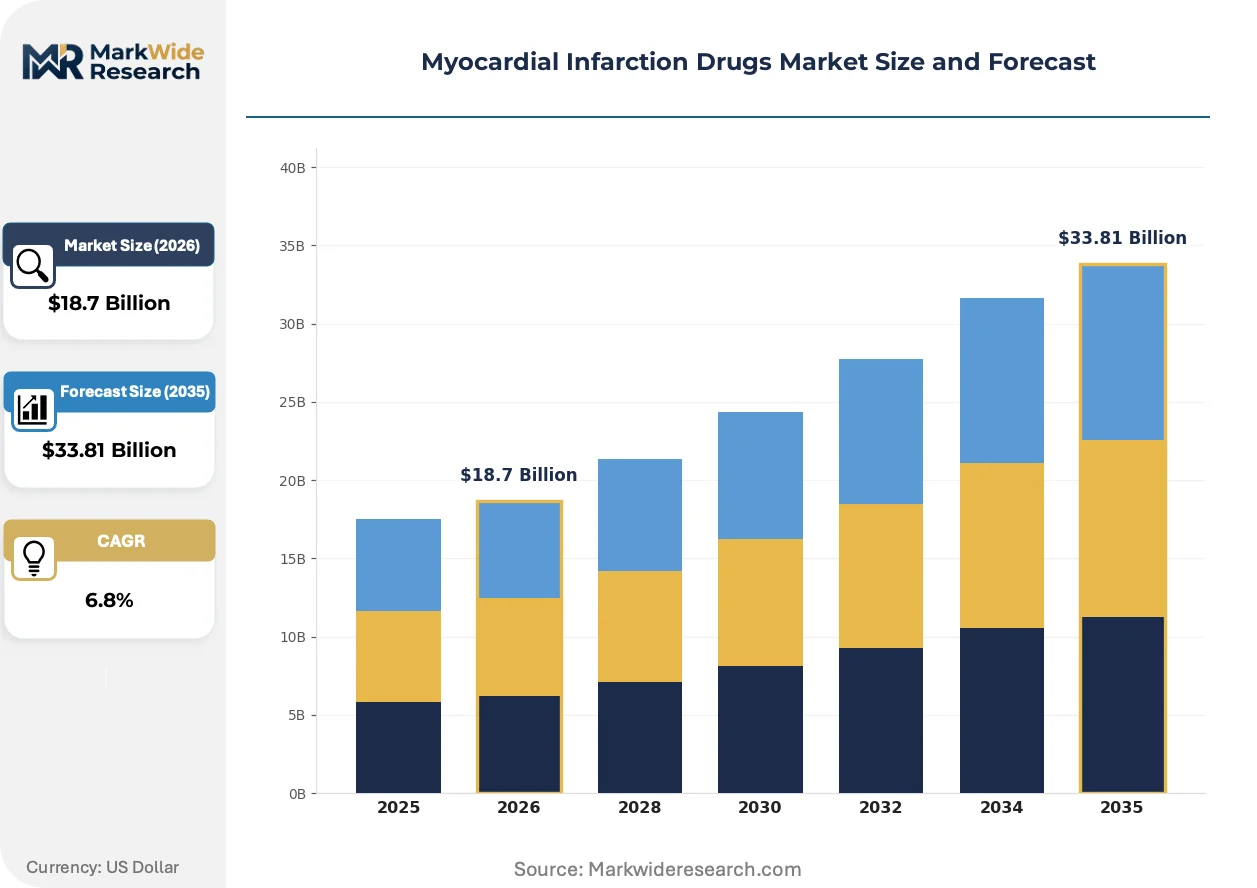
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Antiplatelet Agents, Beta Blockers, ACE Inhibitors, Statins Delivery Method: Oral, Injectable, Intravenous, Subcutaneous End User: Hospitals, Outpatient Clinics, Homecare, Rehabilitation Centers Treatment Stage: Acute Phase, Post-Acute Phase, Chronic Management, Preventive Care |
| Companies Covered | Sanofi, Amgen, Pfizer, Bristol-Myers Squibb, Boehringer Ingelheim, AstraZeneca, Merck & Co., Eli Lilly and Company, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myocardial Infarction Drugs Market Shifts & Advancements
Cardiovascular pharmacology is converging with point-of-care diagnostics, enabling real-time platelet function testing to guide antithrombotic intensity. This integration is compressing therapeutic decision cycles from hours to minutes in acute coronary syndrome management.
Subcutaneous anticoagulant delivery systems are miniaturizing through prefilled autoinjector platforms that eliminate dose-calculation errors in emergency settings. Emergency medical technicians in Scandinavian health systems are adopting these devices for field administration of direct oral anticoagulants. The technology is miniaturizing treatment infrastructure requirements, enabling antithrombotic therapy initiation in ambulances and remote clinics previously dependent on hospital pharmacy compounding.
REACH framework amendments are tightening effluent discharge limits for cardiac drug manufacturing facilities across EU member states. Active pharmaceutical ingredient producers must retrofit wastewater treatment systems to remove antiplatelet residues below detectable thresholds. German and French contract manufacturing organizations are absorbing compliance costs through long-term supply agreements with originator pharmaceutical companies.
Hospital procurement committees are consolidating antithrombotic purchasing through integrated stroke-heart attack network contracts rather than individual facility negotiations. Group purchasing organizations in the United States are displacing standalone hospital pharmacy negotiations with three-year sole-source agreements tied to outcome guarantees. This concentration is most visible in Texas and Florida, where Catholic health systems and for-profit chains dominate acute myocardial infarction admission volumes.
Myocardial Infarction Drugs Market Segmentation
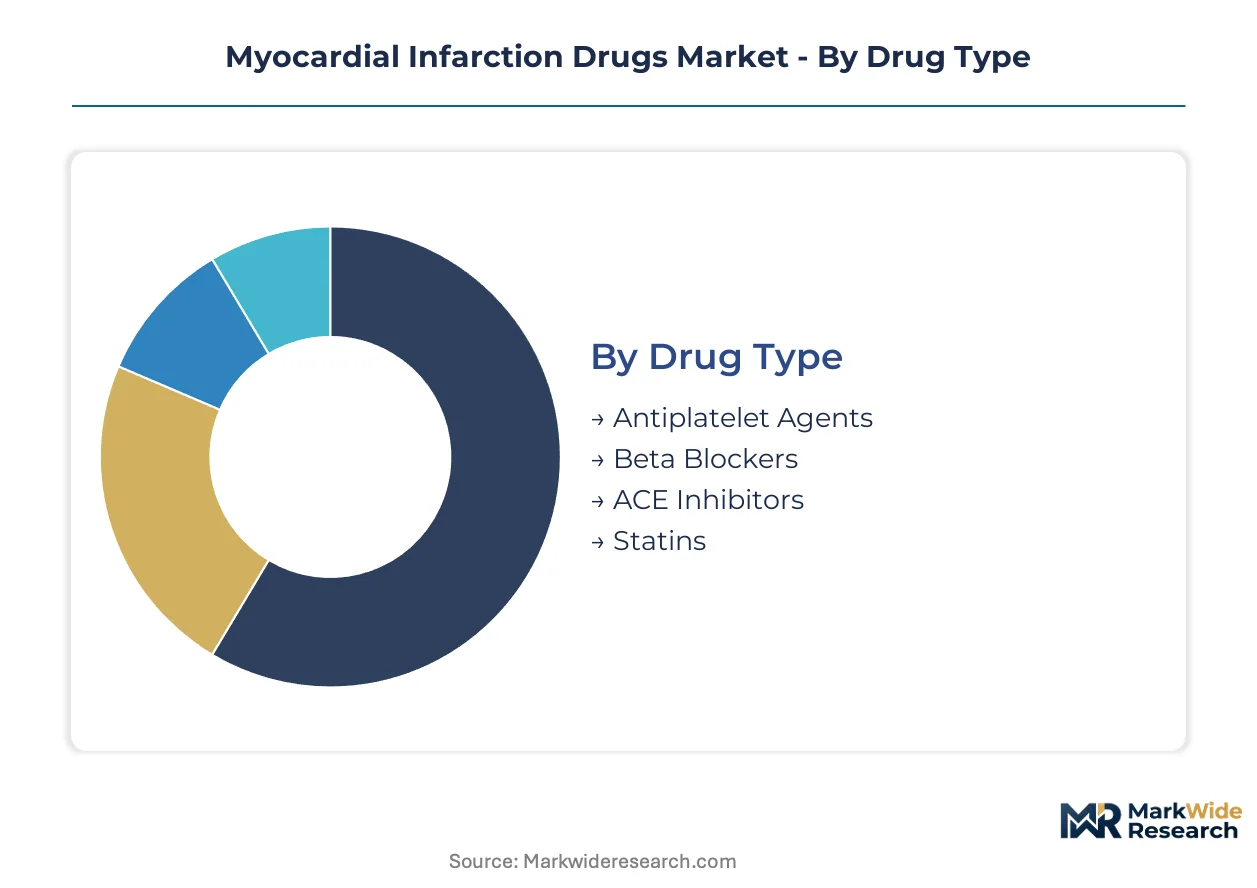
Drug type and delivery method segments in the myocardial infarction drugs market face divergent regulatory pathways. FDA breakthrough designations favor novel antiplatelet mechanisms while EMA pharmacovigilance mandates extend post-approval study timelines for combination therapies.
Drug Type:
FDA cardiovascular outcome study requirements and EMA PRIME eligibility criteria create tiered approval timelines across pharmacological classes.
- Antiplatelet Agents:P2Y12 inhibitors and glycoprotein IIb/IIIa antagonists form the acute-phase backbone with defined therapeutic windows measured by platelet inhibition thresholds and bleeding risk profiles. Demand concentrates in United States emergency departments where integrated stroke-heart attack networks standardize dual-antiplatelet protocols and lock in formulary preference.
- Statins:HMG-CoA reductase inhibitors anchor chronic lipid management with established prescribing patterns in post-MI secondary prevention. Atorvastatin and rosuvastatin commoditization in the United States and Germany has eliminated manufacturer pricing power, compressing margins on stable maintenance therapy.
- Beta Blockers:Cardioselective and non-selective formulations reduce myocardial oxygen demand through heart rate and contractility modulation.
- ACE Inhibitors:Angiotensin-converting enzyme blockers interrupt renin-angiotensin-aldosterone system activation to limit ventricular remodeling after infarction.
Antiplatelet agents handle the majority of throughput; statins are the fastest mover on share.
Delivery Method:
Route selection determines administration setting, cold-chain requirements, and emergency medical services formulary access.
- Injectable:Lyophilized thrombolytic presentations enable ambient-temperature storage in catheterization labs, expanding administration points beyond centralized pharmacy operations. Pre-hospital adoption concentrates in Scandinavian health systems where emergency medical technicians initiate subcutaneous anticoagulant therapy in ambulances.
- Intravenous:Direct vascular delivery achieves rapid therapeutic plasma concentrations for thrombolytic agents in acute coronary syndrome. United States hospital systems favor IV loading doses in emergency departments to compress door-to-needle times below guideline thresholds.
- Oral:Tablet and capsule formulations dominate maintenance-phase prescribing with patient self-administration convenience.
- Subcutaneous:Prefilled autoinjector platforms eliminate dose-calculation errors and enable field administration by paramedics.
Oral formulations retain the largest prescription volume; injectable methods are expanding most quickly into pre-hospital channels.
End User:
Procurement concentration varies by care setting, with hospital group purchasing organizations displacing standalone pharmacy negotiations.
- Hospitals:Acute care facilities capture the highest per-dose revenue for intravenous thrombolytics administered in emergency departments and catheterization labs. Catholic health systems and for-profit chains in Texas and Florida dominate United States acute myocardial infarction admission volumes and consolidate antithrombotic purchasing through three-year sole-source agreements.
- Outpatient Clinics:Cardiology practices manage post-discharge medication reconciliation and chronic therapy optimization. German ambulatory care networks coordinate with hospital discharge protocols to maintain therapeutic continuity.
- Homecare:Visiting nurse services administer subcutaneous anticoagulants for patients with mobility limitations.
- Rehabilitation Centers:Post-acute facilities adjust polypharmacy regimens during cardiac recovery programs.
Hospitals handle the majority of throughput; outpatient clinics are gaining share fastest as care shifts toward ambulatory settings.
Treatment Stage:
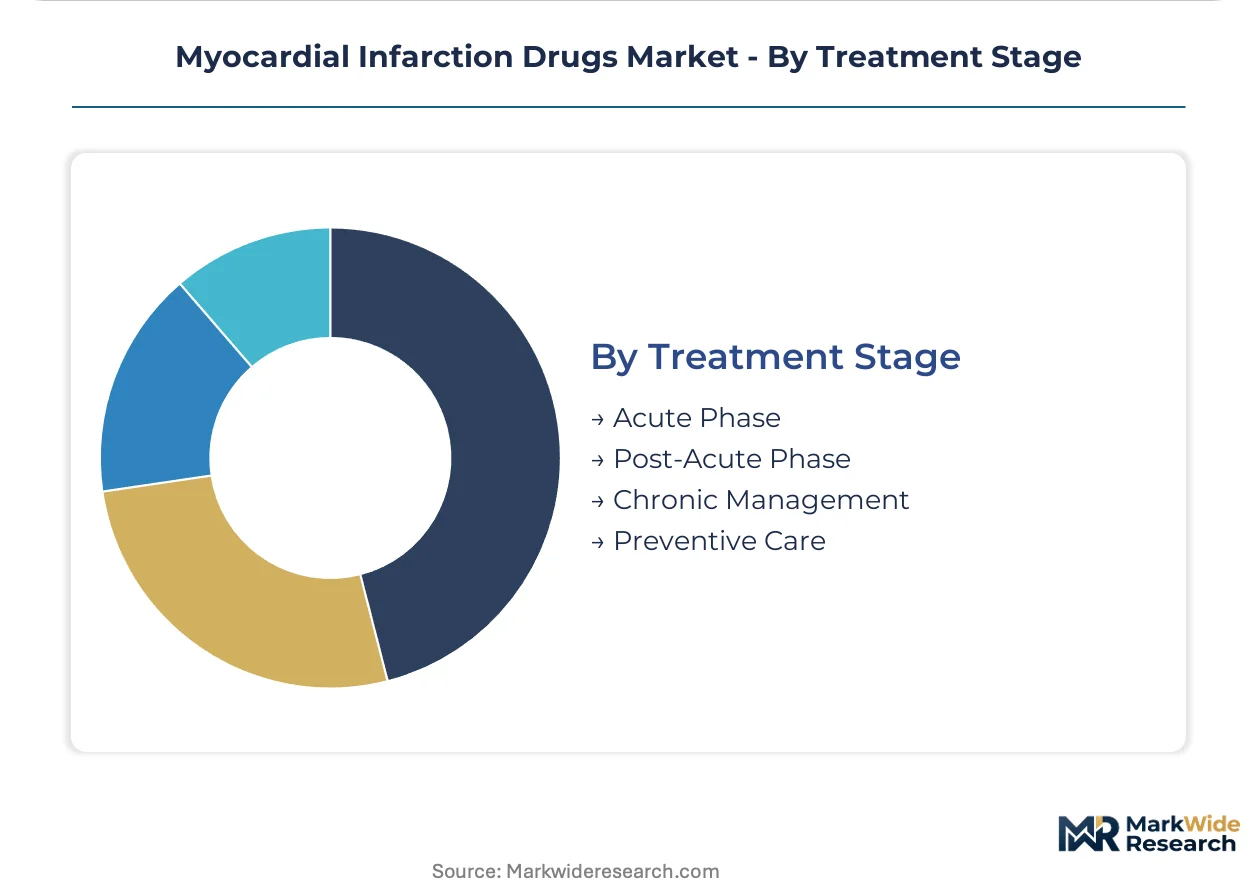
Revenue intensity and regulatory scrutiny intensify in acute-phase applications with emergency administration protocols.
- Acute Phase:Emergency department and cath-lab interventions command premium pricing for rapid-onset antithrombotic and thrombolytic agents. United States integrated stroke-heart attack networks drive protocol standardization that locks in preferred agents across emergency departments.
- Chronic Management:Long-term secondary prevention relies on statin maintenance and antihypertensive combinations with stable prescribing volumes. Generic saturation in the United States and United Kingdom has compressed manufacturer margins on maintenance therapies.
- Post-Acute Phase:Transition care focuses on medication reconciliation and adherence support following hospital discharge.
- Preventive Care:Risk-factor modification targets high-risk populations before first cardiac events.
Acute phase handles the majority of throughput; post-acute phase is climbing the fastest as readmission reduction programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exporters supply antiplatelet active pharmaceutical ingredients to United States hospital systems, while Swiss contract manufacturers service European cath-lab networks.
United States
Integrated stroke-heart attack networks in Texas and Florida drive formulary standardization across Catholic health systems and for-profit chains. The FDA breakthrough therapy designation accelerates Phase III timelines for novel P2Y12 inhibitors. Boston and Minneapolis clusters host emergency medical services pilot programs for pre-hospital thrombolytic administration.
Germany
Baden-Württemberg and Bavaria pharmaceutical manufacturers dominate European anticoagulant API production under REACH framework compliance requirements. The EU Green Deal pharmaceutical manufacturing standards reshape cardiac drug effluent treatment investments. Frankfurt-Rhine-Main contract manufacturing organizations absorb wastewater retrofit costs through long-term originator supply agreements.
Switzerland
Swissmedic regulatory pathways attract cardiovascular drug developers seeking parallel FDA-EMA approval efficiency. Basel and Zurich pharmaceutical clusters specialize in lyophilized thrombolytic formulations for ambient-temperature cath-lab storage. The country's central European logistics position enables just-in-time delivery to German and French hospital networks.
Japan
PMDA post-market surveillance requirements for combination antithrombotic regimens extend real-world evidence collection timelines. Tokyo and Osaka metropolitan hospitals pioneer point-of-care platelet function testing integration. METI industrial policy supports domestic production of heparin alternatives to reduce Chinese API dependency.
India
CDSCO accelerated approval pathways for generic antiplatelet agents attract multinational licensing partnerships. Hyderabad and Ahmedabad API manufacturers expand heparin production capacity following Chinese supply chain disruptions. The country's central bank pharmaceutical export financing schemes support contract manufacturing organization expansion into European markets.
Myocardial Infarction Drugs Market Competitive Landscape
Listed leaders compete with private specialists across R&D intensity and manufacturing scale dimensions. The market structures around three tiers: multinational originators with integrated cardiovascular portfolios, mid-cap specialists focused on antithrombotic mechanisms, and regional generics manufacturers serving price-sensitive maintenance therapy segments. Strategic archetypes include breakthrough-therapy chasers prioritizing FDA expedited pathways, REACH-compliant green chemistry suppliers, and pre-hospital channel specialists. Dominant competitive moves involve sole-source hospital network contracting and API backward integration to secure heparin supply chains.
Within the originator tier, Sanofi and Bristol-Myers Squibb exemplify divergent geographic strategies. Sanofi anchors European hospital formulary dominance through established cath-lab relationships. Bristol-Myers Squibb occupies a position defined by oral anticoagulant manufacturing scale and United States emergency department protocol penetration. Pfizer represents the R&D-intensive archetype, with novel mechanism cardiovascular programs positioned for breakthrough designation eligibility.
| Leading Market Players |
|---|
| Sanofi |
| Amgen |
| Pfizer |
| Bristol-Myers Squibb |
| Boehringer Ingelheim |
| AstraZeneca |
| Merck & Co. |
| Eli Lilly and Company |
| Novartis |
| Others |
Supply & Pricing Matrix
Chinese heparin active pharmaceutical ingredient substitution for European porcine sources simultaneously reshapes supply geography toward East Asian biomanufacturing clusters and compresses pricing economics for anticoagulant producers facing REACH compliance cost absorption. This input displacement concentrates procurement leverage among API intermediaries while forcing originators to renegotiate long-term offtake terms.
Pricing Analysis
Next-generation P2Y12 inhibitor pricing gaps against legacy clopidogrel and emerging factor Xa combinations stratify across premium, standard, and economy tiers. Contract-based long-term offtake dominates hospital group purchasing organization procurement, with price differentiation driven by FDA breakthrough designation status and bleeding risk profile certification. Pricing pressure stems from generic statin saturation in chronic maintenance segments. Community hospital systems exhibit highest price sensitivity; integrated stroke-heart attack networks command volume discounts.
Supply Chain Analysis
China and India anchor heparin API and generic antiplatelet production respectively, with German contract manufacturers specializing in lyophilized thrombolytic formulations. The supply chain draws from porcine tissue sourcing, synthetic anticoagulant precursors, and cold-chain logistics infrastructure. Single-source vulnerability concentrates in Chinese pig farming regions exposed to zoonotic disruption. Distribution runs through hospital group purchasing organizations and emergency medical services formulary contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as pre-hospital administration protocols create channel niches outside traditional hospital pharmacy procurement, with ambulance formulary access remaining underpenetrated across most European markets.
For Market Incumbents: Secure backward integration into heparin API production to mitigate Chinese supply concentration risk. Lock in three-year sole-source agreements with Catholic health systems and for-profit chains dominating Texas and Florida admission volumes. Defend formulary position through real-world evidence generation for combination antithrombotic regimens facing EMA pharmacovigilance mandates. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-track offers accelerated market access for novel antiplatelet mechanisms with superior bleeding profiles. Pre-hospital emergency medical services channels in Scandinavia and Germany present white-space penetration opportunity. Target lyophilized thrombolytic formulations enabling ambient-temperature cath-lab storage as differentiated entry angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap antithrombotic specialists with REACH-compliant manufacturing infrastructure. Long-term viability centers on regulatory differentiation rather than commodity scale. Watch EMA pharmacovigilance mandate enforcement intensity as inflection signal for combination therapy development economics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough designation compresses Phase III timelines for P2Y12 inhibitors. |
| Backward Integration | Captive heparin API production insulates against Chinese zoonotic supply disruptions. |
| Hospital System Partnership | Three-year sole-source agreements with Catholic health systems lock formulary preference. |
| Green Manufacturing Transition | REACH framework compliance creates competitive differentiation in European procurement. |
| Pre-Hospital Channel Expansion | Ambulance formulary contracts capture revenue shifting from inpatient pharmacy budgets. |
Research Methodology
The analysis maps antiplatelet agents, thrombolytics, anticoagulants, and statin maintenance therapies, each validated through hospital formulary directors, emergency department physicians, and pharmaceutical regulatory affairs leads. Primary interviews with cath-lab procurement managers and emergency medical services formulary committees combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and hospital GPO contract databases. Bottom-up prescription volume modeling and top-down therapeutic class revenue triangulation anchored segmentation outputs.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include drug class, delivery method, treatment stage, and regional regulatory cluster. CAGRs derived from therapeutic adoption curve analysis and pricing trajectory modeling. Forecast inputs incorporated REACH compliance cost absorption rates and pre-hospital protocol expansion timelines.
Underlying assumptions cover guideline adherence rates for dual-antiplatelet therapy and heparin API supply stability, with deviation risk concentrated in EMA pharmacovigilance mandate enforcement and Chinese trade policy volatility. Recalibration cycles align with material shifts in cardiology guideline updates and breakthrough therapy designation awards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Global Female Contraceptive Market
Pharmaceuticals
P2X7 Receptor Antagonists Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Loratadine Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Esomeprazole Market