
 China Plasma Protein Therapeutics Market | 2026-2036
China Plasma Protein Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
China Plasma Protein Therapeutics Market Outlook
Tertiary hospital systems are bifurcating from smaller clinics as the dominant buyer archetype for plasma protein therapies. China Biologic Products leverages its vertically integrated plasma collection network to secure raw material access across multiple provinces. Hualan Biological Engineering anchors its position through concentrated immunoglobulin manufacturing capacity in Henan province. Beijing Tiantan Biological Products differentiates via coagulation factor specialization tied to state-backed hemophilia treatment programs.
Plasma protein therapeutics comprise fractionated human blood derivatives including albumin, immunoglobulin, coagulation factors, and antithrombin, produced through cold ethanol precipitation and chromatographic purification processes designed to isolate specific proteins for clinical administration. These therapies serve essential functions in volume replacement, immune modulation, and hemostatic control across acute and chronic care settings. Albumin maintains the largest revenue footprint due to its established role in cirrhosis and surgical volume resuscitation, while immunoglobulin segments capture expanding utilization in primary immunodeficiency and neurological autoimmune protocols. Coagulation factors represent the fastest-growing structural category as recombinant and plasma-derived options proliferate for hemophilia A and B management under national reimbursement expansion.
NMPA enforces batch release certification and GMP compliance for all plasma fractionation facilities, while GB standards mandate viral inactivation protocols that elevate manufacturing complexity and capital requirements for market participants. The National Health Commission's centralized procurement pilots for blood products are compressing pricing bandwidth and favoring scaled domestic producers with cost-advantaged plasma supply chains. Stakeholders must monitor how provincial bulk-purchasing aggregation affects product mix decisions and whether NMPA's evolving biosimilar guidance creates pathways for recombinant alternatives to displace plasma-derived equivalents in select therapeutic categories.
Market Dynamics
NMPA's tightened plasma collection center licensing requirements are consolidating raw material access around scaled domestic fractionators with multi-province collection networks.
Growth Catalysts
- Centralized procurement pilots:The National Health Commission's bulk-purchasing aggregation favors producers with cost-advantaged plasma supply chains across Henan and Shandong provinces.
- Albumin:Surgical volume resuscitation protocols in tertiary hospitals drive consistent offtake for human serum albumin in cirrhosis and trauma settings.
- Coagulation factor expansion:State-backed hemophilia treatment programs under national reimbursement expansion accelerate plasma-derived and recombinant factor VIII/IX utilization.
Market Restraints
- Plasma supply concentration:Collection center licensing caps limit raw material expansion to incumbent operators with existing provincial permits.
- GB viral inactivation standards:Mandatory pathogen reduction protocols elevate capital intensity for new fractionation facility construction.
- Recombinant substitution:Recombinant coagulation factors threaten displacement of plasma-derived equivalents in hemophilia A management under evolving NMPA biosimilar guidance.
Strategic Opportunities
- Western China penetration:Sichuan and Shaanxi provinces show underdeveloped immunoglobulin access relative to Yangtze River Delta saturation.
- Neurological autoimmune protocols:Intravenous immunoglobulin expansion into CIDP and myasthenia gravis indications opens new prescriber segments beyond infectious disease specialists.
- Dual carbon alignment:Energy-efficient cold ethanol precipitation and chromatographic purification upgrades attract green financing for facility modernization.
Industry Challenges
- Plasma collection technician scarcity:Qualified donor screening and apheresis operation expertise concentrates in legacy collection hubs.
- Batch release timelines:NMPA certification delays for new fractionation lines extend time-to-revenue for capacity expansions.
- Legacy system integration:ERP upgrades for cold chain traceability compliance strain IT resources at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Plasma Protein Therapeutics Market |
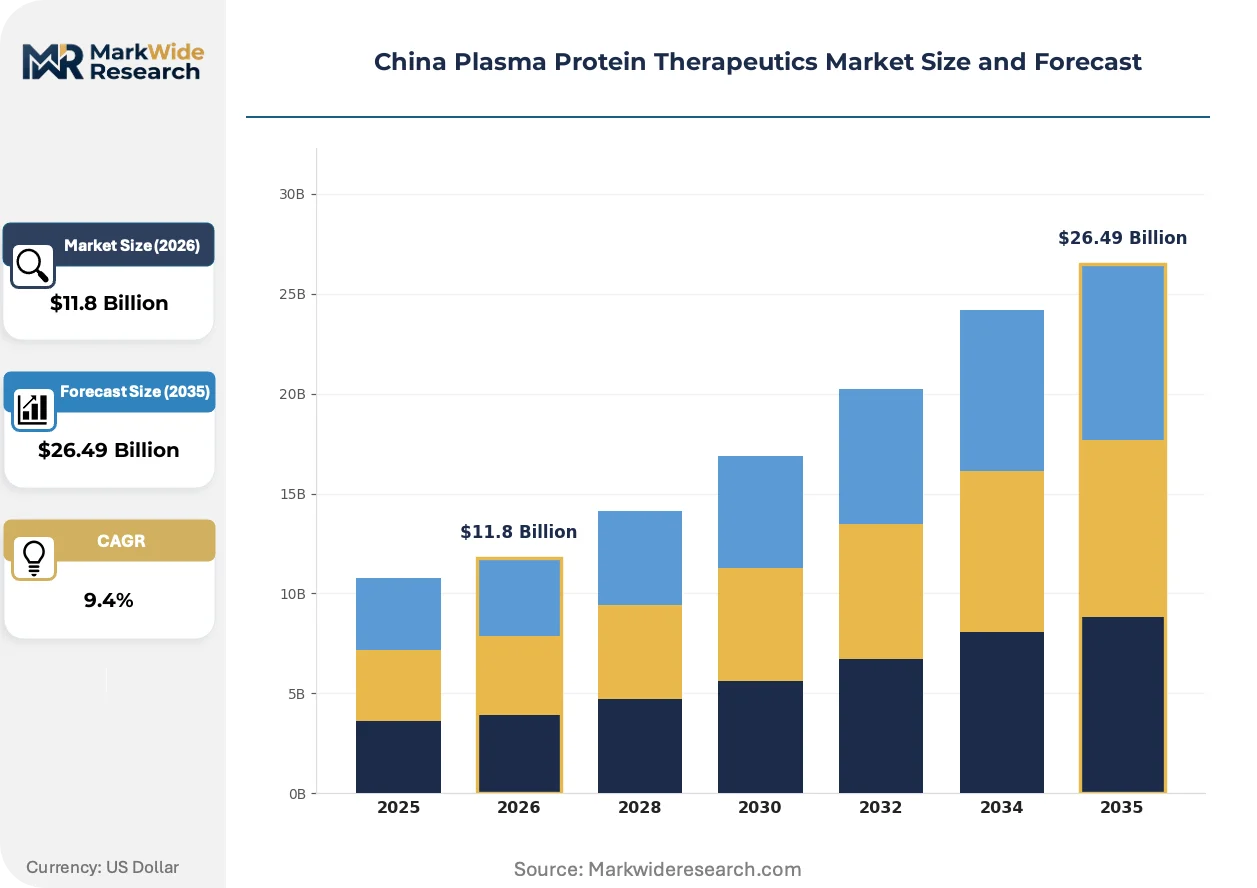
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Albumin, Immunoglobulin, Coagulation Factors, Antithrombin End User: Hospitals, Clinics, Home Care, Blood Centers Application: Immunodeficiency Disorders, Hemophilia, Liver Diseases, Shock Treatment Distribution Channel: Direct Sales, Online Pharmacies, Wholesalers, Retail Pharmacies |
| Companies Covered | China Biologic Products, Hualan Biological Engineering, Beijing Tiantan Biological Products, Shanghai RAAS Blood Products, CSL Behring, Grifols, Octapharma, Kedrion Biopharma, Takeda Pharmaceutical Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Plasma Protein Therapeutics Market Strategic Shifts
Process intensification and regulatory stringency are bifurcating competitive advantage between scaled fractionators with captive plasma supply and specialized recombinant developers.
Caprylic acid precipitation is fragmenting traditional cold ethanol dominance in immunoglobulin manufacturing. Tertiary hospital systems in Jiangsu and Zhejiang are adopting caprylic-acid-processed IVIG for reduced adverse reaction profiles. This technology is fragmenting procurement preferences between academic medical centers prioritizing purity metrics and cost-sensitive municipal hospitals.
NMPA's evolving biosimilar guidance for plasma-derived biologics is compressing development timelines for recombinant alternatives. The regulation creates accelerated pathways for factor VIII and fibrinogen biosimilars while maintaining batch release requirements for plasma originators. Coagulation factor manufacturers are responding with hybrid portfolios balancing plasma-derived heritage products against recombinant pipeline investments.
Hospital procurement committees are consolidating immunoglobulin purchasing authority at provincial level. Municipal blood product distributors are losing direct access to tertiary buyers as Shanghai and Jiangsu health commissions aggregate volume negotiations. This concentration is most visible in Yangtze River Delta clusters where single-source contracts now cover multiple hospital systems.
China Plasma Protein Therapeutics Market Segmentation
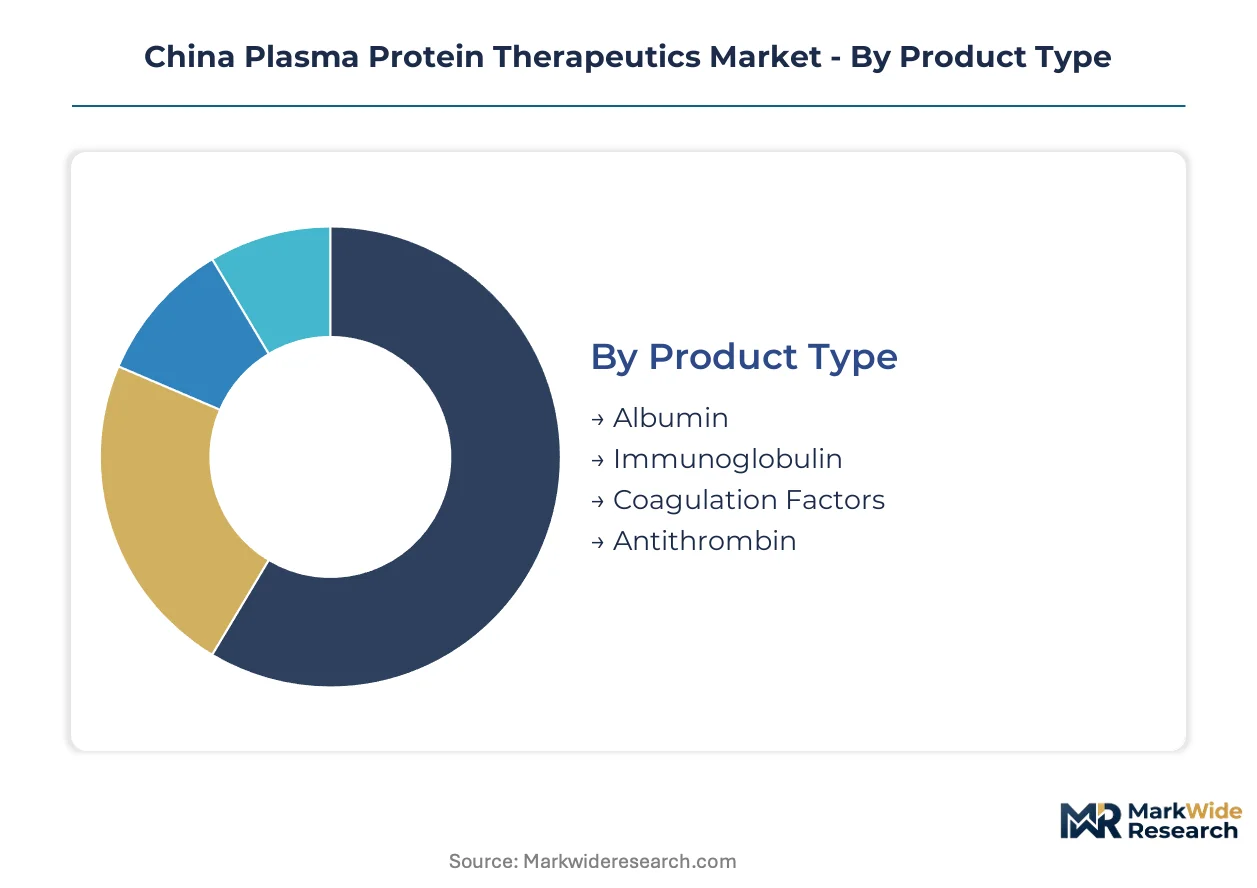
Plasma protein therapeutics in China fragment across four structural dimensions that determine pricing power and procurement access. Product type concentration governs manufacturing capital allocation, while end-user consolidation around tertiary hospital systems reshapes distribution economics.
Product Type:
Margin pools concentrate in immunoglobulin and coagulation factor segments where manufacturing complexity and clinical specificity sustain premium positioning.
- Albumin:Human serum albumin fractionated through cold ethanol precipitation maintains the largest revenue footprint across China's plasma protein market. Demand concentrates in Shanghai and Jiangsu tertiary hospitals for cirrhosis ascites management and surgical volume resuscitation, with NMPA batch release requirements limiting new entrant participation.
- Immunoglobulin:Intravenous and subcutaneous immunoglobulin products command elevated margins due to caprylic acid precipitation technology differentiation. Jiangsu and Zhejiang academic medical centers are adopting purity-optimized IVIG for neurological autoimmune protocols, compressing procurement preferences at municipal hospitals.
- Coagulation Factors:Plasma-derived and recombinant factor VIII/IX products for hemophilia A and B management.
- Antithrombin:Anticoagulant protein concentrates for heparin resistance and disseminated intravascular coagulation.
The dominant share belongs to Albumin, while Immunoglobulin is closing the gap fastest.
End User:
Procurement authority is shifting toward centralized hospital systems and away from fragmented clinic networks.
- Hospitals:Tertiary care centers in the Yangtze River Delta cluster aggregate the majority of immunoglobulin and albumin offtake through provincial bulk-purchasing pilots.
- Clinics:Municipal and county-level clinics face exclusion from direct blood product procurement as health commissions consolidate purchasing authority.
- Home Care:Subcutaneous immunoglobulin self-administration for primary immunodeficiency patients.
- Blood Centers:Plasma collection and fractionation facilities with captive supply chains.
Hospitals control the volume majority, though Home Care is expanding most quickly for chronic immunodeficiency management.
Application:
Clinical indication breadth determines reimbursement tier placement and prescriber specialization requirements.
- Immunodeficiency Disorders:Primary and secondary immunodeficiency states requiring chronic immunoglobulin replacement.
- Hemophilia:Hemophilia A and B under state-backed treatment programs with national reimbursement expansion accelerating factor VIII/IX utilization across Henan and Shandong provinces.
- Liver Diseases:Cirrhosis, acute-on-chronic liver failure, and hepatorenal syndrome.
- Shock Treatment:Trauma, burns, and septic shock volume resuscitation protocols.
Immunodeficiency Disorders anchors current utilization, while Hemophilia shows the steepest expansion trajectory under expanded national reimbursement.
Distribution Channel:
Channel selection reflects cold chain capability and regulatory traceability requirements.
- Direct Sales:Manufacturer-to-hospital contracts dominating Yangtze River Delta procurement.
- Online Pharmacies:E-commerce platforms for patient-direct specialty pharmacy services.
- Wholesalers:Regional blood product distributors losing access as provincial health commissions aggregate volume.
- Retail Pharmacies:Community pharmacy channels for outpatient albumin prescriptions.
Direct Sales commands the dominant position, while Online Pharmacies are gaining share fastest for patient convenience and specialty pharmacy integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tertiary hospital systems in the Yangtze River Delta cluster concentrate procurement authority for plasma protein therapies, with provincial health commissions aggregating volume negotiations away from municipal distributors.
Yangtze River Delta
Shanghai and Jiangsu province host China's densest network of blood product manufacturing facilities, with tertiary care centers driving immunoglobulin offtake for neurological autoimmune protocols. NMPA batch release requirements govern all fractionation output from this cluster. The region's academic medical centers in Zhejiang are adopting caprylic acid-processed IVIG for reduced adverse reaction profiles.
Henan Province
Henan anchors concentrated immunoglobulin manufacturing capacity serving state-backed hemophilia treatment programs across central China. The National Health Commission's centralized procurement pilots favor producers with cost-advantaged plasma supply chains in this province. Collection center licensing caps limit raw material expansion to incumbent operators with existing provincial permits.
Shandong Province
Shandong's plasma collection networks supply fractionators participating in national reimbursement expansion for coagulation factor therapies. GB standards mandate viral inactivation protocols that elevate manufacturing complexity for facilities in this region. Qingdao and Jinan host legacy collection hubs where qualified donor screening expertise concentrates.
Sichuan-Chongqing
Sichuan and Chongqing show underdeveloped immunoglobulin access relative to eastern saturation, presenting expansion opportunities for fractionators with multi-province networks. Western China penetration lags due to plasma collection technician scarcity and extended batch release timelines from NMPA. Chengdu's tertiary hospitals are upgrading hematology departments to match Yangtze River Delta protocols.
China Plasma Protein Therapeutics Market Competitive Environment
Player mix skews toward vertically integrated domestic fractionators with captive plasma collection networks and multinational specialists with recombinant technology portfolios. Market structure concentrates around scaled producers holding multi-province collection permits under NMPA's tightened licensing regime. Two strategic archetypes dominate: domestic incumbents leveraging geographic plasma access and global players importing recombinant alternatives. Competitive moves center on provincial bulk-purchasing contract aggregation and hybrid portfolio construction balancing plasma-derived heritage against recombinant pipeline investments.
Among domestic incumbents, China Biologic Products, Hualan Biological Engineering, and Beijing Tiantan Biological Products occupy positions representing the vertically integrated archetype. These China-based entities exemplify producers securing raw material access across multiple provinces through established collection networks. Their positioning reflects the supply-side consolidation dynamics reshaping competitive advantage under NMPA's regulatory framework.
| Leading Market Players |
|---|
| China Biologic Products |
| Hualan Biological Engineering |
| Beijing Tiantan Biological Products |
| Shanghai RAAS Blood Products |
| CSL Behring |
| Grifols |
| Octapharma |
| Kedrion Biopharma |
| Takeda Pharmaceutical Company Limited |
| Others |
Value Chain & Pricing Dynamics
NMPA batch release certification gates both manufacturing qualification and tiered price positioning simultaneously, compressing margin bandwidth for non-compliant operators while rewarding scaled fractionators with captive plasma networks. The National Health Commission's centralized procurement pilots amplify this bifurcation, aggregating volume negotiations toward producers with multi-province collection permits and cold chain scale.
Pricing Analysis
Caprylic acid-processed IVIG commands premium positioning against legacy cold ethanol immunoglobulin, with next-generation recombinant coagulation factors threatening further price stratification. Three-tier pricing structure across premium caprylic-acid IVIG, standard cold ethanol immunoglobulin, and economy-grade albumin segments reflects purification technology differentiation. Pricing pressure stems from provincial bulk-purchasing aggregation compressing contract margins, particularly for municipal hospitals excluded from academic medical center procurement. Tertiary care systems show lowest price sensitivity due to neurological autoimmune protocol requirements, while county-level clinics face acute cost compression under centralized procurement exclusion.
Supply Chain Analysis
Henan and Shandong provinces anchor plasma collection network density, with Jiangsu and Zhejiang concentrating fractionation capacity and tertiary hospital offtake. Raw material supply draws from donor apheresis operations, viral inactivation reagents, and chromatographic purification media. Single-source vulnerability concentrates in qualified plasma collection technician pools, where screening expertise clusters in legacy provincial hubs. Distribution runs through manufacturer-to-hospital direct contracts dominating Yangtze River Delta procurement, bypassing municipal distributors losing access under health commission aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma protein therapeutics present a service-attach opportunity as patient monitoring and infusion training services expand faster than fractionated product volume, particularly for subcutaneous immunoglobulin self-administration in primary immunodeficiency.
For Market Incumbents: Fortify captive plasma collection networks through technician training investments and multi-province permit renewals ahead of NMPA licensing tightening. Secure provincial bulk-purchasing contracts by expanding cold chain traceability systems to meet health commission ERP integration requirements. Recombinant substitution threats in hemophilia A management demand hybrid portfolio construction balancing plasma-derived heritage products against biosimilar pipeline partnerships. For New Entrants and Emerging Players: Anchor in Sichuan-Chongqing immunoglobulin access gaps, where tertiary hospital hematology upgrades lag Yangtze River Delta saturation. Target caprylic acid precipitation technology licensing as a differentiation lever against incumbent cold ethanol dominance. Partner with western China provincial health commissions on green financing-aligned facility modernization to bypass collection network scale disadvantages. For Investors and Strategic Acquirers: NMPA's evolving biosimilar guidance for plasma-derived biologics reshapes the acquisition landscape, accelerating recombinant developer valuations against fractionation asset multiples. Long-term viability centers on dual carbon alignment credentials and multi-province collection permit portfolios. Monitor provincial bulk-purchasing contract renewal cycles as inflection indicators for pricing power consolidation among scaled domestic operators.| Strategic Initiative | Industry Significance |
|---|---|
| Caprylic Acid Technology Licensing | Purity-optimized IVIG manufacturing differentiates academic medical center procurement preferences in Jiangsu. |
| Multi-Province Collection Permit Expansion | NMPA licensing consolidation favors operators with geographic diversification across Henan and Shandong. |
| Green Financing Facility Modernization | Energy-efficient cold ethanol upgrades attract sustainability-linked capital for dual carbon alignment. |
| Provincial Bulk-Purchasing Contract Aggregation | Direct manufacturer-to-hospital contracts displace municipal distributors under health commission pilots. |
| Hybrid Plasma-Recombinant Portfolio Construction | Biosimilar pathway investments hedge against factor VIII displacement in hemophilia A management. |
Study Parameters
A standing panel of plasma fractionation executives, hospital procurement directors, NMPA regulatory affairs specialists, and blood bank operations managers provided ongoing calibration against secondary validation. Primary interviews combined with NMPA batch release databases, National Health Commission procurement pilot disclosures, and provincial health commission contract aggregations. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, application, and distribution channel dimensions.
Forecast outputs underwent consistency checks against external benchmarks including customs trade data for plasma-derived product imports, hospital procurement database trends, and GPO contract aggregation patterns. Segmentation modeling spanned product type concentration, tertiary versus municipal hospital procurement authority, neurological autoimmune versus infectious disease application expansion, and direct sales versus online pharmacy channel evolution. CAGRs derived from spline interpolation across annualized volume and value estimates, incorporating plasma collection center licensing trajectory and recombinant biosimilar approval pathway assumptions.
Material uncertainties — NMPA regulatory timeline shifts, provincial bulk-purchasing pilot expansion, recombinant substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding collection network permit renewal rates and health commission procurement aggregation speed. Recalibration cycles align with material shifts in NMPA biosimilar guidance and national reimbursement expansion for coagulation factor therapies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Global Heparin Sodium Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Long-Acting Insulin Market