
 Etoricoxib Market | 2026-2036
Etoricoxib Market Size, Share, and Industry Trends Forecast 2026-2036
Etoricoxib Market Insights
REACH compliance in Europe is expanding the cost-of-entry calculus for etoricoxib manufacturers seeking to supply the European Medicines Agency-regulated zone. Pfizer Inc leverages its established cardiovascular safety database to sustain market presence across regulated jurisdictions. Sun Pharmaceutical Industries Ltd anchors its position through backward integration into active pharmaceutical ingredient production, controlling cost structures for tablet and capsule formulations.
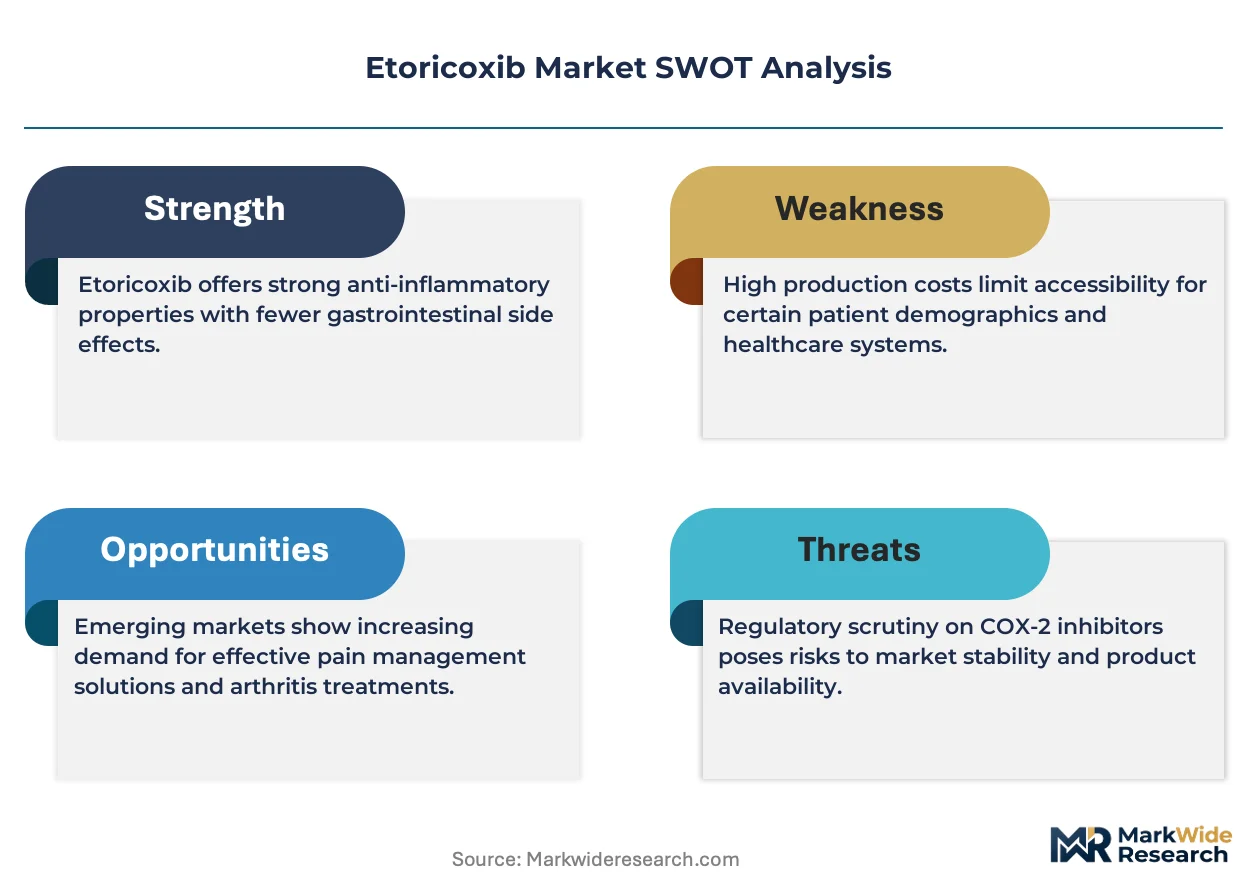
Etoricoxib is a selective cyclooxygenase-2 inhibitor with a diaryl-substituted pyrazole structure, formulated typically as 30 mg, 60 mg, 90 mg, or 120 mg film-coated tablets for oral administration; it suppresses prostaglandin synthesis to deliver anti-inflammatory and analgesic effects in osteoarthritis, rheumatoid arthritis, and acute gouty arthritis. Tablet formulations dominate current volume owing to manufacturing simplicity and patient familiarity, while oral suspensions represent the fastest-expanding delivery category as geriatric and pediatric populations seek dose-flexible alternatives. The pain relief application segment captures concentrated margin pools due to recurring prescription patterns and direct-to-consumer brand recognition in retail pharmacy channels.
The US FDA, the European Medicines Agency, and India's CDSCO each enforce distinct cardiovascular risk evaluation frameworks that shape etoricoxib labeling, post-market surveillance obligations, and prescriber education requirements across their territories. These regulatory divergences fragment approval pathways and elevate region-specific clinical trial investments for multinational filers. Stakeholders must monitor evolving cardiovascular safety signal assessments and generics substitution policies to align portfolio prioritization with jurisdiction-specific access dynamics.
Market Dynamics
Cardiovascular safety documentation requirements from the US FDA, EMA, and India's CDSCO are fragmenting approval pathways and forcing manufacturers to maintain parallel clinical datasets across jurisdictions. This regulatory divergence elevates compliance costs while compressing time-to-market for new entrants.
Growth Catalysts
- Osteoarthritis protocol standardization:Hospital pharmacies in India and the United States are expanding procurement of oral NSAID formulations as first-line treatment pathways formalize etoricoxib positioning.
- Generics access expansion:Backward integration into active pharmaceutical ingredient production enables cost control for tablet and capsule formulations serving aging demographics.
- REACH compliance maturation:European manufacturers who have absorbed ECHA documentation costs now hold preferential supply positions to the European Medicines Agency-regulated zone.
Market Restraints
- Cardiovascular safety signal monitoring:Post-market surveillance obligations from the US FDA and CDSCO require ongoing clinical investment that disadvantages smaller filers.
- API supply concentration:Active pharmaceutical ingredient production clusters in specific Indian manufacturing zones create geographic vulnerability to environmental compliance disruptions.
- COX-2 inhibitor substitution:Non-selective NSAID alternatives and physical therapy protocols compete for osteoarthritis prescriptions in cost-sensitive health systems.
Strategic Opportunities
- Oral suspension formulation expansion:Geriatric and pediatric populations in India drive demand for dose-flexible delivery alternatives to standard tablets.
- Retail pharmacy channel deepening:Direct-to-consumer brand recognition in pain relief applications enables margin capture outside hospital procurement.
- Cardiovascular safety database leveraging:Established post-market surveillance infrastructure from selective COX-2 inhibitor portfolios accelerates regulatory filings in new jurisdictions.
Industry Challenges
- Parallel clinical trial execution:Multinational filers must coordinate cardiovascular outcome studies across FDA, EMA, and CDSCO frameworks with non-harmonized endpoints.
- Generics substitution policy navigation:Pharmacy benefit managers and national formularies apply heterogeneous bioequivalence standards that fragment pricing power.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Etoricoxib Market |
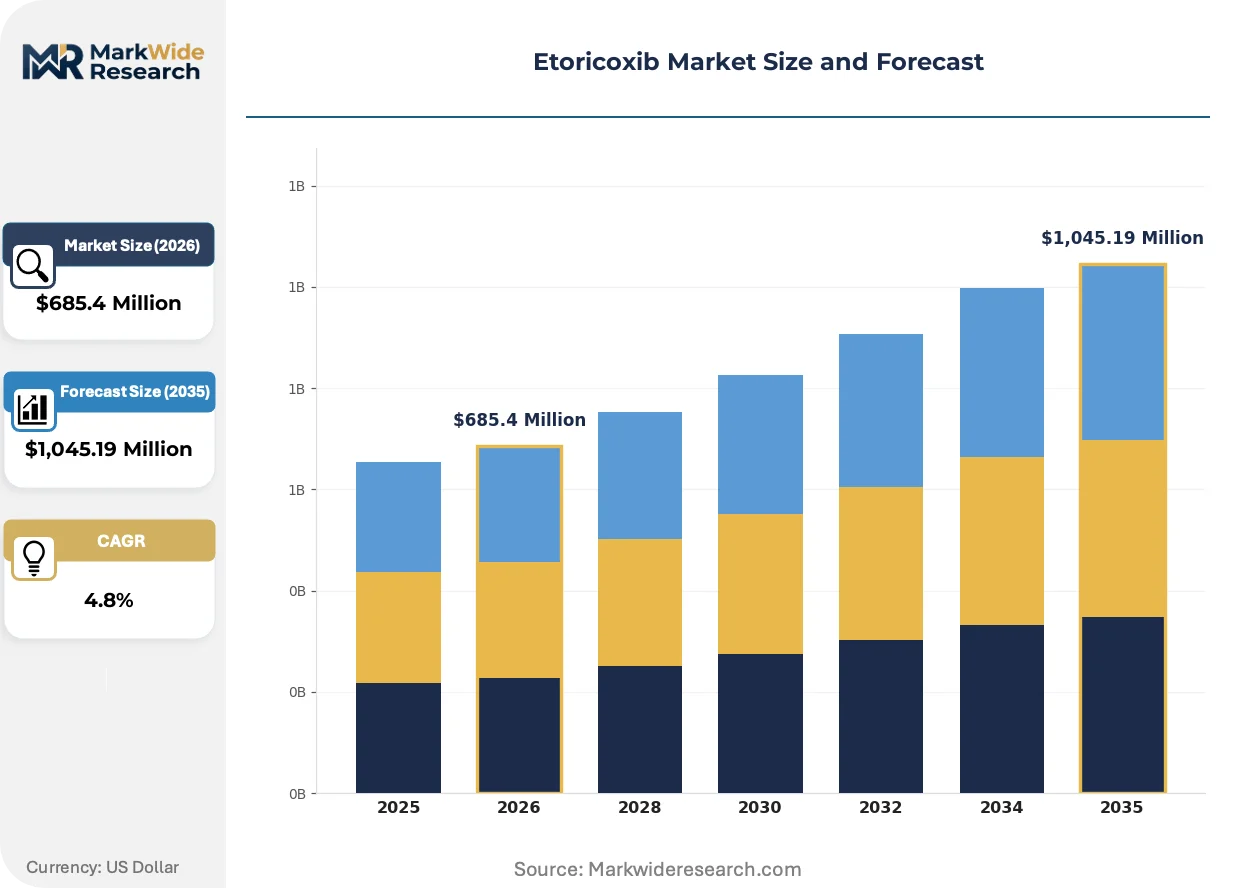
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable Solutions, Capsules, Oral Suspensions End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Delivery Mode: Oral, Intravenous, Topical, Transdermal Application: Anti-inflammatory, Pain Relief, Osteoarthritis, Rheumatoid Arthritis |
| Companies Covered | Sun Pharmaceutical Industries Ltd, Pfizer Inc, Bayer AG, Abbott Laboratories, GlaxoSmithKline, Merck & Co Inc, Perrigo Company, Geri-Care Pharmaceuticals, Kopran Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Etoricoxib Market Trends and Innovations
Formulation technology and regulatory data architecture are converging to reshape competitive positioning in selective COX-2 inhibitor supply. Manufacturers who unify manufacturing flexibility with jurisdiction-specific safety documentation capture preferential access.
Modified-release oral suspension technology is unifying dose precision with patient compliance in geriatric populations. Long-term care facilities and home-health providers in India are adopting these formulations at accelerating rates. This unification of delivery flexibility with chronic disease management protocols is compressing the traditional tablet-dominant supply model.
REACH registration requirements under ECHA are mandating substance-level environmental fate documentation for etoricoxib manufacturing inputs. European suppliers who completed this registration during earlier compliance windows now control access to the European Medicines Agency-regulated market. Contract manufacturers without REACH-aligned substance dossiers face exclusion from European supply chains.
Hospital procurement consolidation is concentrating volume with distributors who can deliver cardiovascular safety documentation alongside physical product. Integrated delivery networks in the United States are replacing fragmented pharmacy purchasing with centralized formularies that privilege suppliers with established FDA post-market surveillance databases. This concentration is most visible in Medicare Advantage plan structures where risk-bearing entities optimize pharmaceutical spend across chronic pain populations.
Etoricoxib Market Segmentation
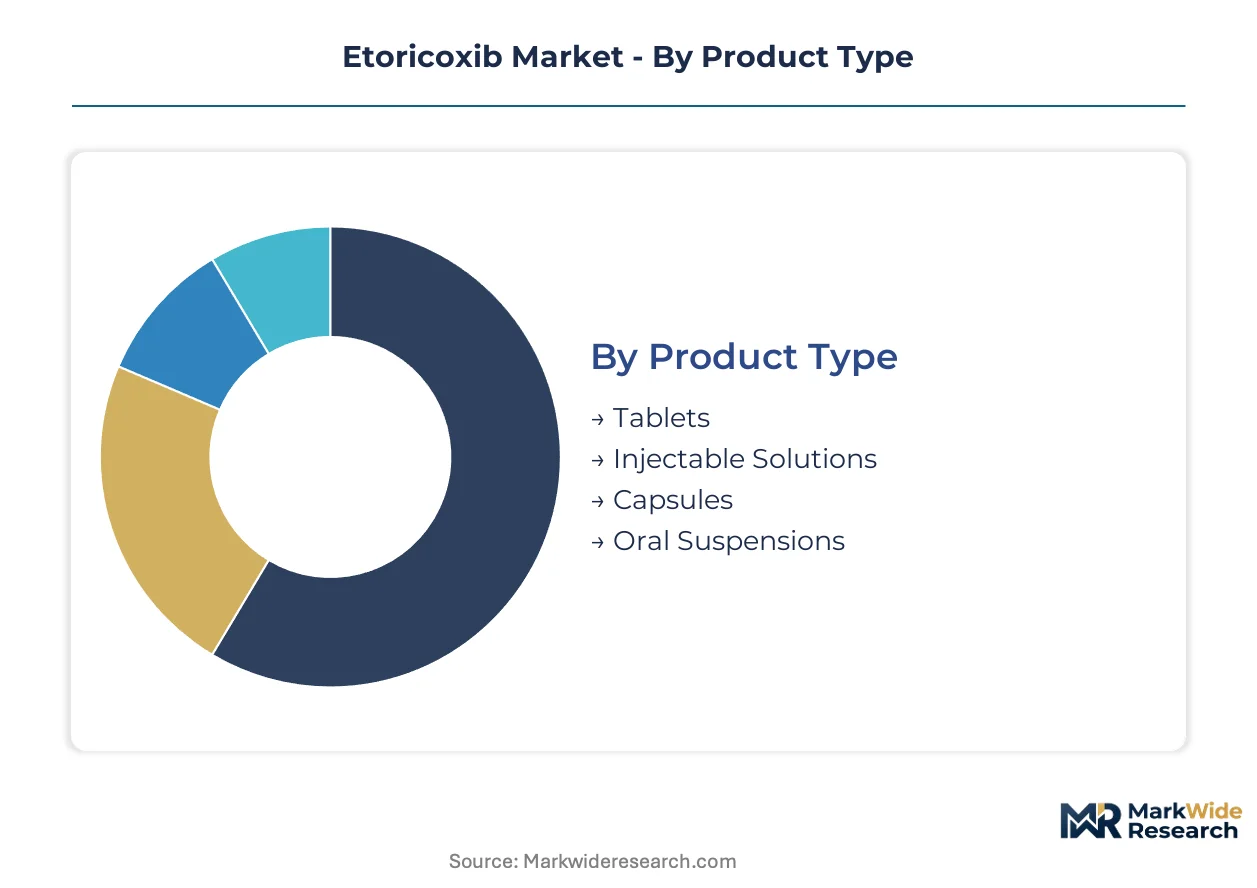
Etoricoxib supply chains fragment across formulation technologies, care settings, and pharmacological applications. Each segmentation axis reveals distinct margin structures, regulatory exposure, and procurement dynamics that shape manufacturer prioritization.
Product Type:
Film-coated solid dosage forms anchor current manufacturing capacity, while liquid and parenteral alternatives expand addressable populations.
- Tablets:Standard 30 mg, 60 mg, 90 mg, and 120 mg film-coated tablets dominate hospital procurement volumes due to manufacturing simplicity and established bioequivalence frameworks. Indian and US hospital pharmacies concentrate tablet demand through standardized osteoarthritis protocols.
- Oral Suspensions:Dose-flexible liquid formulations serve geriatric and pediatric populations requiring titration precision. Indian long-term care facilities and home-health providers are accelerating suspension adoption for chronic pain management.
- Capsules:Gelatin-encapsulated variants offer alternative excipient profiles for patients with tablet coating sensitivities.
- Injectable Solutions:Parenteral formulations target acute care settings requiring rapid onset in post-surgical or trauma contexts.
Mature deployment sits with tablets. Newer deployment is concentrated in oral suspensions.
End User:
Procurement authority determines pricing power, with institutional buyers commanding volume discounts distinct from retail channel margins.
- Hospitals:Integrated delivery networks and centralized formularies in the United States privilege suppliers with FDA post-market surveillance databases. Medicare Advantage risk-bearing entities optimize pharmaceutical spend across chronic pain populations through hospital pharmacy consolidation.
- Clinics:Outpatient rheumatology and orthopedic practices drive recurring prescription volumes for osteoarthritis and rheumatoid arthritis maintenance therapy.
- Rehabilitation Centers:Post-acute facilities managing recovery protocols generate steady demand for anti-inflammatory regimens.
- Home Care:Geriatric populations receiving domiciliary nursing services favor oral suspensions for caregiver-administered dosing flexibility.
Volume concentration rests with hospitals. Margin expansion is shifting toward home care.
Delivery Mode:
Route of administration shapes pharmacokinetic profiles, patient compliance, and manufacturing complexity thresholds.
- Oral:Gastrointestinal absorption of etoricoxib tablets and suspensions enables self-administration and retail pharmacy distribution at scale.
- Intravenous:Hospital-controlled infusion delivers rapid systemic exposure for acute gouty arthritis flares and perioperative pain.
- Topical:Localized application formulations target site-specific inflammation with reduced systemic COX-2 inhibition exposure.
- Transdermal:Patch-based delivery remains developmental, seeking steady-state plasma concentrations for chronic pain populations.
Oral delivery commands installed capacity. Transdermal development represents the steepest expansion trajectory for formulation investment.
Application:
Clinical indication determines prescriber specialty, reimbursement coding, and competitive substitution risk from non-selective NSAIDs or physical therapy.
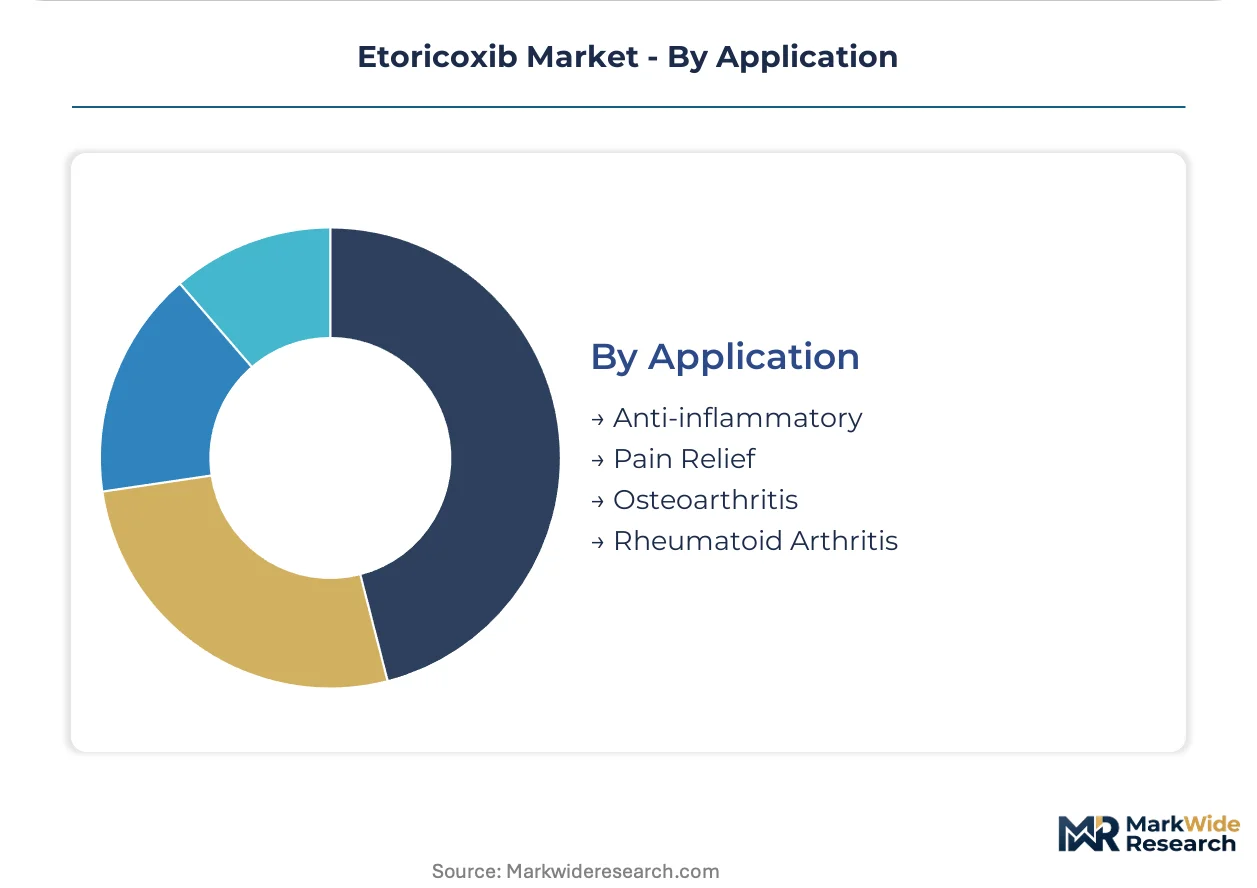
- Pain Relief:Acute and chronic analgesic use captures concentrated margin pools through direct-to-consumer brand recognition in retail pharmacy channels.
- Osteoarthritis:Degenerative joint disease management drives first-line NSAID protocol standardization in Indian and US hospital systems.
- Rheumatoid Arthritis:Autoimmune inflammatory joint disease requires long-term COX-2 selective therapy with cardiovascular monitoring.
- Anti-inflammatory:Broad-spectrum inflammation suppression spans multiple etiologies with less indication-specific reimbursement.
Osteoarthritis protocols anchor institutional procurement. Pain relief applications are gaining share fastest in retail channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Andhra Pradesh concentrate active pharmaceutical ingredient production, attracting etoricoxib manufacturers through tax holidays and duty exemptions on imported manufacturing equipment.
United States
Medicare Advantage risk-bearing entities consolidate pharmaceutical procurement across chronic pain populations, driving volume toward centralized hospital formularies. The FDA enforces cardiovascular outcome study requirements that fragment approval pathways for new entrants. New Jersey and Pennsylvania host established post-market surveillance infrastructure serving integrated delivery networks.
India
Aging demographics and expanding generics access propel etoricoxib consumption through hospital and retail channels. CDSCO tightens cardiovascular safety documentation requirements, elevating compliance costs for COX-2 selective inhibitors. Hyderabad and Ahmedabad manufacturing clusters control active pharmaceutical ingredient supply for tablet and oral suspension formulations.
Germany
REACH compliance under ECHA mandates substance-level environmental fate documentation for etoricoxib manufacturing inputs, creating preferential supply positions for early registrants. The country's national pharmaceutical regulator aligns with EMA cardiovascular risk evaluation frameworks. Bavaria and North Rhine-Westphalia house contract manufacturing organizations with ECHA-aligned substance dossiers.
United Kingdom
Post-acute rehabilitation facilities generate steady demand for anti-inflammatory regimens as orthopedic surgery volumes recover. The Medicines and Healthcare products Regulatory Agency maintains distinct labeling requirements from continental European frameworks. Southeast England distribution hubs consolidate procurement for National Health Service hospital trusts.
Brazil
Expanding private health insurance coverage drives prescription access for osteoarthritis maintenance therapy in urban centers. ANVISA applies bioequivalence standards that influence generics substitution patterns in pharmacy benefit structures. São Paulo state concentrates import and distribution infrastructure for South American supply.
Etoricoxib Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the etoricoxib supply base. Market structure tilts toward consolidation among manufacturers with established cardiovascular safety databases and backward-integrated active pharmaceutical ingredient production. Three archetypes dominate: multinational pharmaceutical conglomerates with regulatory infrastructure, Indian generics houses with cost-optimized manufacturing, and regional specialists serving niche formulation categories. Competitive moves center on portfolio diversification into oral suspension technologies and geographic expansion through jurisdiction-specific regulatory filings.
Within the multinational tier, Pfizer Inc and Sun Pharmaceutical Industries Ltd occupy anchor positions. Pfizer exemplifies the safety-database archetype, leveraging established post-market surveillance infrastructure across FDA and EMA jurisdictions. Sun Pharmaceutical represents the vertically integrated generics model, with captive active pharmaceutical ingredient production controlling cost structures for tablet formulations. Bayer AG sits within the diversified healthcare conglomerate category, where pharmaceutical operations complement broader consumer health portfolios.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd |
| Pfizer Inc |
| Bayer AG |
| Abbott Laboratories |
| GlaxoSmithKline |
| Merck & Co Inc |
| Perrigo Company |
| Geri-Care Pharmaceuticals |
| Kopran Ltd |
| Others |
Pricing and Supply Chain Analysis
Active pharmaceutical ingredient procurement costs in Indian manufacturing zones cascade through three pricing tiers for finished etoricoxib formulations. Hyderabad and Ahmedabad production clusters feed hospital procurement at contract-negotiated rates, while retail pharmacy channels absorb markups for inventory carrying costs and brand recognition premiums. The concentration of COX-2 inhibitor API supply in Gujarat Special Economic Zones creates geographic leverage that shapes downstream pricing power across tablet and oral suspension categories.
Pricing Analysis
Short lead-time premiums command pricing separation between spot inventory procurement and scheduled contract fulfillment in hospital pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels reflects cardiovascular safety database completeness, with FDA-validated suppliers capturing premium positioning against CDSCO-registered alternatives. Pricing pressure stems from generics substitution policies in Medicare Advantage formularies, compressing margins for non-differentiated tablet suppliers. Hospital procurement committees exhibit highest price sensitivity, while long-term care facilities accepting oral suspension formulations show reduced elasticity due to dosing flexibility requirements.
Supply Chain Analysis
Freight cost volatility from Indian manufacturing clusters to United States distribution centers is reshaping regional sourcing strategies for etoricoxib finished goods. API production concentrates in India, China, and the United States, with backward integration into pyrazole derivative chemistry controlling input cost structures. Raw material dependencies include diaryl-substituted intermediates, film-coating excipients, and suspension stabilizing agents. Single-source vulnerability in Hyderabad API manufacturing creates exposure to environmental compliance disruptions. Distribution runs through integrated delivery networks in the United States and hospital procurement consortia in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The etoricicoxib market sits at a formulation technology transition, with modified-release oral suspensions displacing legacy tablet dominance in geriatric care settings.
For Market Incumbents: Deepen cardiovascular safety database investments to defend formulary positioning against emerging generics houses with limited post-market surveillance infrastructure. Expand captive API production in Andhra Pradesh Special Economic Zones to offset REACH compliance cost inflation for European supply. Channel control through integrated delivery network partnerships represents the critical defensive lever against Medicare Advantage procurement consolidation. For New Entrants and Emerging Players: CDSCO's tightened cardiovascular documentation requirements in India opens a window for specialists with pre-assembled clinical datasets to capture share from legacy filers facing compliance backlogs. Oral suspension formulation capacity serving home-health providers represents the most penetrable white-space target, with geriatric dosing flexibility driving prescription conversion. A go-to-market angle anchored in long-term care facility partnerships bypasses hospital formulary barriers. For Investors and Strategic Acquirers: Accelerating oral suspension adoption in Indian geriatric populations is the leading indicator that formulation technology transitions are reaching inflection velocity. Over a multi-year horizon, vertically integrated manufacturers with captive API supply and established FDA post-market surveillance infrastructure present the most defensible acquisition profile. Watch for CDSCO enforcement actions against non-compliant COX-2 inhibitors as the signal for regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modified-Release Oral Suspension Development | Geri-Care Pharmaceuticals and Indian long-term care providers are accelerating dose-flexible formulation adoption for chronic pain populations. |
| REACH Compliance Registration | Early ECHA registrants in Bavaria now control preferential supply access to European Medicines Agency-regulated hospital formularies. |
| Cardiovascular Safety Database Expansion | FDA post-market surveillance infrastructure enables Medicare Advantage risk-bearing entities to consolidate procurement with validated suppliers. |
| Backward Integration into API Production | Sun Pharmaceutical's captive pyrazole derivative manufacturing insulates tablet cost structures from intermediate supply volatility. |
| Retail Pharmacy Channel Deepening | Pain relief applications with direct-to-consumer brand recognition capture margin pools outside hospital procurement discounting. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for etoricoxib regulatory pathway mapping, supplemented by formulary database surveillance across Medicare Advantage plans. Primary interviews with regulatory affairs leads, hospital procurement managers, formulary directors, and payer access specialists validated secondary intelligence on cardiovascular safety documentation requirements. Bottom-up tablet and oral suspension volume estimates triangulated against top-down pharmaceutical spend data from integrated delivery networks.
Historical trendline analysis of COX-2 inhibitor prescription patterns anchored the analytical framework across the projection horizon, with segmentation modeling across formulation type, end-user channel, delivery mode, and application indication. CAGR derivation incorporated patient population demographics, generics substitution elasticity, and regulatory approval velocity for modified-release technologies. Forecast inputs included CDSCO enforcement intensity projections and REACH registration completion rates for European supply qualification.
The model assumes a particular technology adoption path; alternative pathways for transdermal patch development would alter the outlook for oral formulation demand trajectories. Forecasts reflect assumptions regarding cardiovascular safety signal stability and osteoarthritis protocol standardization velocity in Indian and United States hospital systems. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
United States Pharmaceutical Logistics Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Zoledronic Acid Market