
 Global Contraceptive Drugs and Devices Market | 2026-2036
Global Contraceptive Drugs and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contraceptive Drugs and Devices Market Foresight
Community health programs are reorganizing procurement priorities across the Global Contraceptive Drugs and Devices Market, shifting volume toward long-acting reversible methods and away from short-cycle oral regimens. Bayer AG leverages its integrated hormonal manufacturing footprint to sustain supply security for levonorgestrel-releasing systems across multiple continents. Pfizer Inc. anchors its position through R&D intensity in injectable formulations, while CooperSurgical Inc. specializes in intrauterine device design and clinical training infrastructure.
Contraceptive drugs and devices comprise pharmaceutical agents and mechanical or biomedical instruments engineered to prevent pregnancy through hormonal suppression, physical barrier, or spermicidal action, with intrauterine devices typically constructed from polyethylene frames measuring 32 mm in length and releasing 20 mcg of levonorgestrel daily. These products serve primary commercial purposes in family planning administration, fertility management, and menstrual disorder treatment across clinical and retail channels. Oral contraceptives retain the largest revenue footprint due to decades of prescriber familiarity and pharmacy accessibility, while intrauterine devices represent the fastest-growing product category as healthcare systems prioritize multi-year efficacy and reduced patient compliance burden. Hormonal technology dominates manufacturing investment, though copper-based systems command durable margin pools in markets with constrained cold-chain infrastructure.
The FDA governs new drug applications and over-the-counter switching pathways for oral contraceptives in the United States, while the EMA's Medical Device Regulation imposes clinical evidence requirements on intrauterine systems entering European markets. WHO prequalification standards shape demand in low-income countries by determining eligibility for global procurement funds and national tender participation. Stakeholders must monitor regulatory divergence between stringent and emerging markets, as divergent evidence standards for biodegradable delivery systems threaten to fragment product development pipelines and delay market entry timelines.
Market Dynamics
Procurement concentration among multilateral health agencies is compressing supplier margins while elevating WHO prequalification from preference to prerequisite for commercial viability across low-income markets.
Growth Catalysts
- EMA Medical Device Regulation:The MDR's harmonized clinical evidence standards for intrauterine systems are reducing duplicate country-by-country registration burdens across European markets.
- Sub-Saharan Africa community health worker networks:Government-funded last-mile distribution infrastructure is expanding patient touchpoints for long-acting reversible contraceptives beyond traditional clinic settings.
- Biodegradable polymer delivery systems:Elimination of explantation procedures is reducing total cost-of-care calculations and expanding addressable patient populations in resource-constrained settings.
Market Restraints
- Levonorgestrel API concentration:Three contract manufacturers in India supply over seventy percent of global active pharmaceutical ingredient, creating single-source vulnerability for hormonal device production.
- Cold-chain dependency of etonogestrel implants:Temperature-controlled logistics requirements exclude rural distribution in markets lacking refrigerated transport infrastructure.
- FDA over-the-counter switching timelines:Extended pharmacovigilance study requirements for progestin-only pill reclassification are delaying market entry by four to six years versus European pathways.
Strategic Opportunities
- Indonesia's national health insurance expansion:Jaminan Kesehatan Nasional coverage of long-acting methods creates reimbursement-funded demand growth in the world's fourth-most-populous country.
- Telehealth prescription pathways:Asynchronous clinician consultation models are circumventing traditional brick-and-mortar access barriers for oral contraceptive initiation.
- Copper IUD manufacturing in Vietnam:Domestic production incentives under industrial development frameworks are attracting technology transfer partnerships for non-hormonal device assembly.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 series study backlogs at accredited laboratories are extending product development timelines by twelve to eighteen months.
- Legacy enterprise resource planning integration:Multinational manufacturers face data architecture conflicts when consolidating acquired regional brands into unified quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contraceptive Drugs and Devices Market |
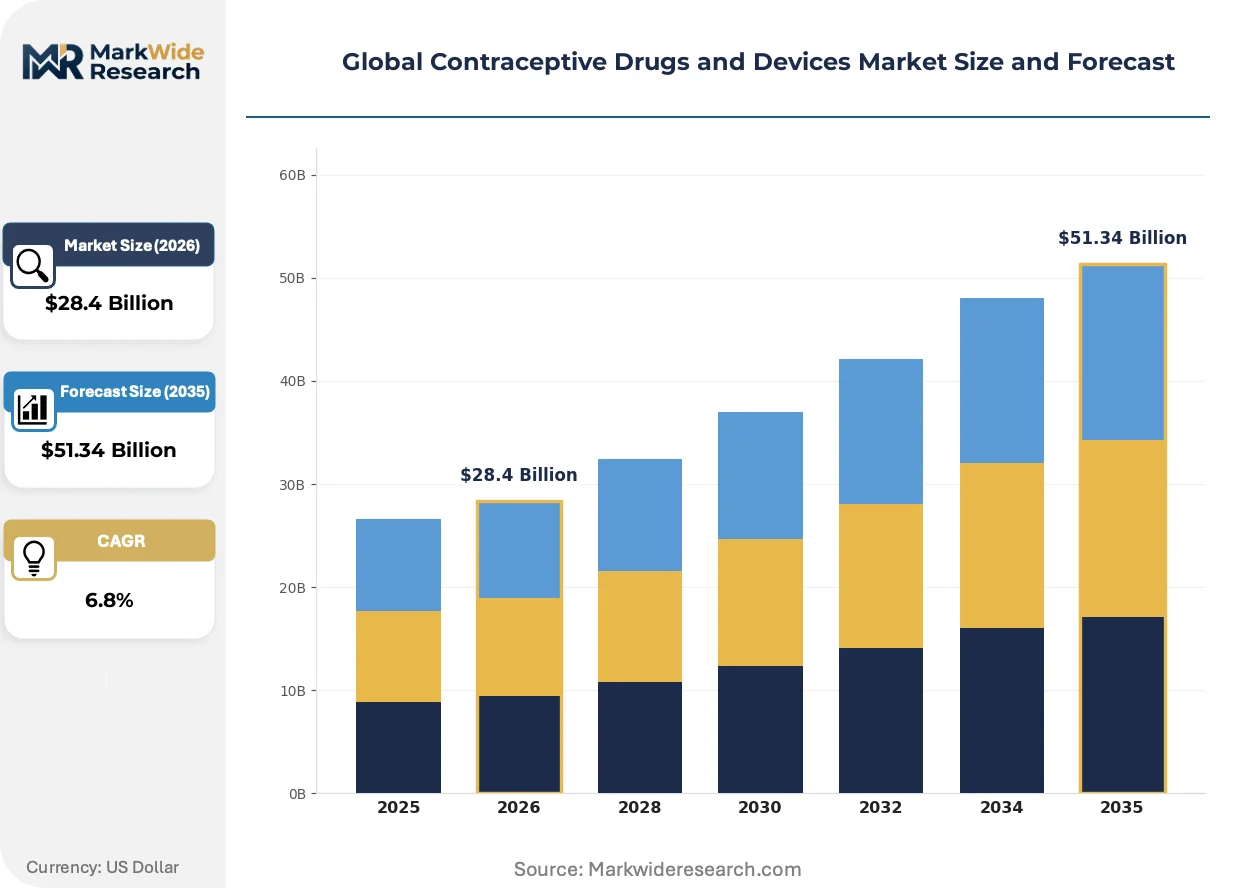
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Contraceptives, Intrauterine Devices, Barrier Devices, Emergency Contraceptives, Injectable Contraceptives Technology: Hormonal, Non-Hormonal, Biodegradable, Copper-Based, Levonorgestrel-Releasing Application: Family Planning, Fertility Control, Menstrual Regulation, Hormonal Therapy, STI Prevention End User: Gynecologists, Family Clinics, Sexual Health Centers, Pharmacies, Community Health Programs |
| Companies Covered | Bayer AG, Pfizer Inc., Johnson & Johnson, Organon Group of Companies, Teva Pharmaceutical Industries Ltd, CooperSurgical Inc., AbbVie Inc., Church & Dwight Co., Inc., Reckitt Benckiser Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contraceptive Drugs and Devices Market Shifts & Advancements
Biodegradable delivery architectures and regulatory pathway convergence are compressing product lifecycles while expanding addressable patient populations beyond traditional prescriber-dependent models.
Subdermal implants releasing etonogestrel or levonorgestrel over three to five years are supplanting daily oral regimens among working-age women in Brazil and Mexico. Public sector tenders in these markets now specify multi-year efficacy as a procurement criterion. The shift is compressing pharmacy refill revenue streams while expanding upfront device manufacturer margins.
REACH authorization requirements for polymer components in intrauterine systems are forcing reformulation of frame materials across European supply chains. Manufacturers are substituting traditional polyethylene with medical-grade thermoplastic elastomers to meet substance restriction thresholds. The transition elevates raw material costs but secures market access across EU member states.
Direct-to-consumer subscription models for oral contraceptives are disintermediating traditional pharmacy channels in the United States. Telehealth platforms handle prescription authorization, while specialized logistics providers manage recurring delivery. The model concentrates customer acquisition spend on digital marketing rather than wholesaler rebate structures.
Global Contraceptive Drugs and Devices Market Segmentation
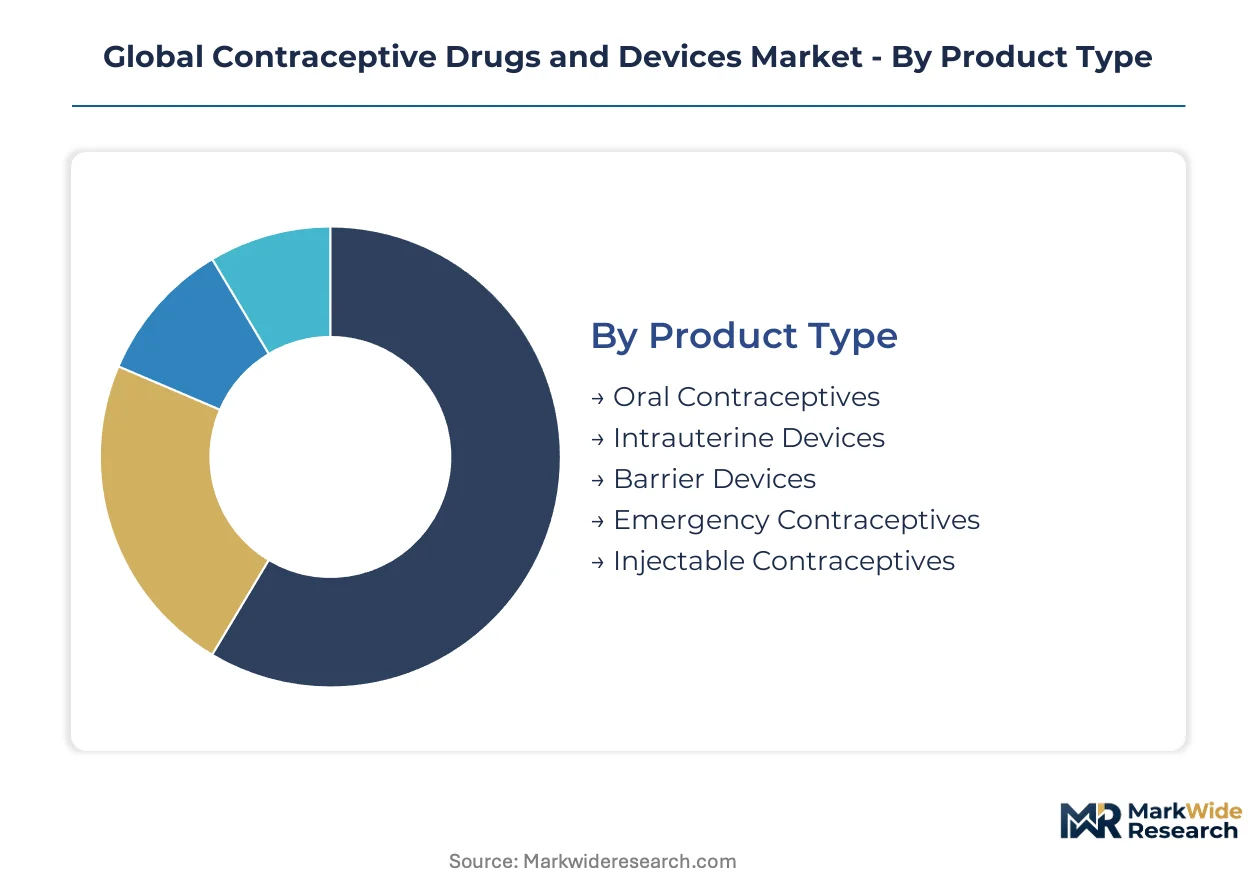
Segmentation in the Global Contraceptive Drugs and Devices Market reveals divergent margin structures across hormonal versus mechanical technologies and prescriber-dependent versus self-administered delivery modes. Understanding these fault lines enables suppliers to allocate R&D investment toward reimbursement-advantaged categories and distribution partnerships aligned with procurement concentration.
Product Type:
Margin pools concentrate in long-acting reversible methods where device manufacturers capture multi-year revenue upfront and clinical training creates switching costs.
- Intrauterine Devices:Polyethylene frames measuring 32 mm release 20 mcg levonorgestrel daily over five to seven years. Demand concentrates in Brazil and Mexico where public sector tenders now specify multi-year efficacy as mandatory procurement criteria, compressing pharmacy refill streams while expanding device manufacturer margins.
- Oral Contraceptives:Daily progestin-estrogen combinations retain the largest revenue footprint through decades of prescriber familiarity and pharmacy accessibility. Volume concentrates in India where government-funded family planning initiatives and domestic manufacturing capacity scale simultaneously, though direct-to-consumer subscription models in the United States are disintermediating traditional wholesale channels.
- Barrier Devices:Latex and polyurethane physical barriers serve STI prevention dual-use cases in sexual health centers.
- Emergency Contraceptives:High-dose levonorgestrel regimens address post-coital scenarios through pharmacy over-the-counter access where FDA switching pathways permit.
- Injectable Contraceptives:Depot medroxyprogesterone acetate formulations dominate sub-Saharan Africa community health worker distribution networks.
Intrauterine devices hold installed capacity. Oral contraceptives are rotating up the share rankings in direct-to-consumer channels.
Technology:
Technology selection determines cold-chain infrastructure requirements and regulatory evidence standards, with hormonal systems commanding manufacturing investment despite API concentration risks.
- Hormonal:Synthetic progestin and estrogen formulations suppress ovulation through systemic circulation. Demand concentrates in Indonesia where Jaminan Kesehatan Nasional reimbursement expansion funds long-acting method uptake, though levonorgestrel API concentration among three Indian contract manufacturers creates single-source vulnerability.
- Levonorgestrel-Releasing:Intrauterine and subdermal systems deliver localized hormone release with reduced systemic exposure. Manufacturing concentrates in facilities with integrated polymer extrusion and drug-loading capabilities, with REACH authorization requirements forcing European supply chain reformulation toward medical-grade thermoplastic elastomers.
- Non-Hormonal:Mechanical and spermicidal approaches serve patient populations with hormonal contraindications.
- Copper-Based:Intrauterine systems generate durable margin pools in markets lacking refrigerated transport infrastructure.
- Biodegradable:Elimination of explantation procedures reduces total cost-of-care calculations in resource-constrained settings.
Hormonal technology anchors current manufacturing capacity. Biodegradable delivery architectures are climbing the fastest as ISO 10993 study backlogs gradually clear.
Application:
Application scope determines prescriber specialty engagement and reimbursement coding complexity, with fertility management commanding premium pricing versus preventive family planning.
- Family Planning:Population-level pregnancy prevention programs drive volume procurement through multilateral health agencies. Demand concentrates in sub-Saharan Africa where government-funded last-mile distribution infrastructure expands patient touchpoints beyond traditional clinic settings, compressing supplier margins while elevating WHO prequalification from preference to prerequisite.
- Menstrual Regulation:Hormonal cycle control addresses dysmenorrhea and menorrhagia in gynecology practices. Patient populations in the United States and Germany access these indications through extended-cycle oral formulations and levonorgestrel-releasing intrauterine systems, with EMA MDR harmonized standards reducing duplicate registration burdens.
- Fertility Control:Reversible suppression for spacing births dominates public sector tenders.
- Hormonal Therapy:Endocrine modulation beyond contraception requires differentiated clinical evidence packages.
- STI Prevention:Barrier and chemical prophylaxis integrates with sexual health center protocols.
Family planning holds installed capacity. Menstrual regulation is gaining share fastest as gynecology practices expand off-label utilization.
End User:
End-user channel determines patient acquisition economics and regulatory oversight intensity, with pharmacy and telehealth pathways reducing clinical labor costs versus specialist administration.
- Community Health Programs:Government-funded worker networks deliver long-acting reversible contraceptives in rural and peri-urban settings. Procurement concentrates in Ethiopia, Kenya, and Nigeria where WHO prequalification standards determine eligibility for global procurement funds, with subdermal implants supplanting daily oral regimens among working-age women.
- Pharmacies:Retail distribution channels for oral and emergency contraceptives face disintermediation pressure. Asynchronous clinician consultation models through telehealth platforms in the United States circumvent traditional brick-and-mortar access barriers, concentrating customer acquisition spend on digital marketing rather than wholesaler rebate structures.
- Gynecologists:Specialist administration of intrauterine and implantable devices requires clinical training infrastructure.
- Family Clinics:Primary care settings manage oral contraceptive initiation and monitoring.
- Sexual Health Centers:Integrated service delivery combines contraception with STI screening and treatment.
Community health programs hold installed capacity. Pharmacies are rotating up the share rankings as subscription logistics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multilateral procurement agencies concentrate purchasing power across four demand centers, with government-funded family planning programs in India and Brazil absorbing the largest tender volumes for long-acting reversible methods.
United States
Direct-to-consumer subscription platforms are disintermediating traditional pharmacy channels for oral contraceptives. FDA over-the-counter switching pathways for progestin-only pills are extending pharmacovigilance timelines by four to six years versus European routes. Boston and San Francisco clusters host telehealth infrastructure that manages asynchronous prescription authorization.
Germany
EMA Medical Device Regulation harmonization is reducing duplicate country-by-country registration burdens for intrauterine systems. REACH authorization requirements for polymer components are forcing frame material reformulation toward medical-grade thermoplastic elastomers. The Rhine-Ruhr industrial corridor concentrates polymer extrusion and drug-loading manufacturing capabilities.
India
Government-funded family planning initiatives are scaling domestic manufacturing capacity for levonorgestrel API and finished devices simultaneously. CDSCO oversight aligns with WHO prequalification standards that determine eligibility for global procurement funds. Mumbai and Ahmedabad clusters host three contract manufacturers supplying over seventy percent of global active pharmaceutical ingredient for hormonal devices.
Brazil
Public sector tenders now specify multi-year efficacy as mandatory procurement criteria for subdermal implants supplanting daily oral regimens. ANVISA regulatory pathways accommodate WHO prequalification standards for community health worker distribution networks. São Paulo anchors clinical training infrastructure that creates switching costs for intrauterine device administration.
Indonesia
Jaminan Kesehatan Nasional reimbursement expansion is funding long-acting method uptake in the world's fourth-most-populous country. The national health insurance program covers hormonal intrauterine systems and etonogestrel implants through capitated payment structures. Jakarta and Surabaya clusters concentrate last-mile distribution infrastructure for community health programs.
Global Contraceptive Drugs and Devices Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with captive hormonal manufacturing footprints and specialized device manufacturers with clinical training infrastructures. Tiered competitive positioning separates multinational conglomerates with diversified portfolios from mid-cap specialists focused on single-modality delivery systems. Strategic archetypes include API-integrated device manufacturers, subscription-platform disintermediators, and copper-based non-hormonal specialists. Dominant competitive moves encompass backward integration into polymer extrusion capabilities and geographic expansion through WHO prequalification eligibility.
Within the integrated pharmaceutical tier, Bayer AG exemplifies the archetype of API-captive device manufacturing with multi-continental supply security. Pfizer Inc. occupies a position representing R&D-intensive injectable formulation development. CooperSurgical Inc. anchors the specialized device manufacturer segment with dedicated intrauterine system design capabilities.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Johnson & Johnson |
| Organon Group of Companies |
| Teva Pharmaceutical Industries Ltd |
| CooperSurgical Inc. |
| AbbVie Inc. |
| Church & Dwight Co., Inc. |
| Reckitt Benckiser Group PLC |
| Others |
Supply & Pricing Matrix
Medical-grade thermoplastic elastomer substitution for legacy polyethylene frames is simultaneously relocating polymer extrusion capacity toward REACH-compliant European facilities and compressing margin structures for non-compliant Asian manufacturers. This input transition elevates raw material costs by fifteen to twenty percent while securing market access across EU member states, fundamentally altering where value capture concentrates in intrauterine device production.
Pricing Analysis
Cost-plus contracts with levonorgestrel API indexation dominate procurement between Indian contract manufacturers and multinational device assemblers. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified products from domestic-only registrations and unlicensed parallel imports. Pricing pressure stems from multilateral agency procurement concentration compressing supplier margins, with community health programs in sub-Saharan Africa exhibiting highest price sensitivity while private gynecology practices in Germany and the United States demonstrate lowest.
Supply Chain Analysis
Inventory lead times for etonogestrel implants extend to ninety days due to cold-chain validation requirements at each distribution node. Manufacturing concentrates in India for levonorgestrel API, Germany for polymer extrusion, and the United States for final device assembly. Raw material dependencies encompass copper wire for non-hormonal intrauterine systems, medical-grade silicone for subdermal implant housings, and pharmaceutical-grade progestin compounds. Single-source vulnerability pervades the API tier where three Indian suppliers feed seventy percent of global hormonal device production. Distribution runs through multilateral procurement agencies consolidating demand from low-income markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where WHO prequalification creates regulatory entrenchment that incumbent manufacturers exploit to exclude unqualified competitors from tender participation.
For Market Incumbents: Secure backward integration into polymer extrusion capabilities to insulate margin structures from REACH-driven raw material cost inflation. Deepen clinical training infrastructure in Brazil and Indonesia to elevate switching costs for healthcare providers administering intrauterine devices. The threat of biodegradable delivery systems eliminating explantation revenue streams necessitates captive investment in next-generation polymer platforms.
For New Entrants and Emerging Players: Lead with copper-based intrauterine device manufacturing in Vietnam where domestic production incentives under industrial development frameworks reduce tariff exposure and cold-chain dependency. Target Indonesia's Jaminan Kesehatan Nasional reimbursement expansion as the most penetrable demand center, leveraging local distribution partnerships to circumvent established multilateral procurement relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed copper IUD specialists possessing Vietnamese manufacturing footprints and ANVISA regulatory clearances. Long-term viability across the projection horizon hinges on portfolio exposure to non-hormonal modalities insulated from API concentration risks. The signal to watch is FDA over-the-counter switching pathway acceleration for progestin-only pills, which would validate direct-to-consumer subscription models and compress traditional pharmacy channel valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Investment | Unlocks access to Global Fund and UNFPA procurement tenders across sub-Saharan Africa. |
| Biodegradable Polymer Platform Development | Eliminates explantation procedures and expands addressable patient populations in resource-constrained settings. |
| Telehealth Prescription Infrastructure | Enables direct-to-consumer subscription models disintermediating traditional pharmacy channels in the United States. |
| REACH-Compliant Supply Chain Migration | Secures European market access as ECHA substance restrictions tighten on legacy polyethylene frames. |
| Community Health Worker Training Networks | Creates switching costs for long-acting reversible contraceptive administration in Brazil and Indonesia. |
Research Methodology
Cross-validation between regulatory filing databases and procurement tender records anchors the qualitative findings on market access dynamics. Primary interviews with regulatory affairs leads at multinational pharmaceutical conglomerates, procurement managers at multilateral health agencies, and biomedical engineers at specialized device manufacturers combined with secondary validation against FDA 510(k) submissions, EMA MDR technical documentation, WHO prequalification assessment reports, and UNFPA contraceptive procurement databases. Bottom-up demand modeling across patient populations and top-down triangulation against national family planning expenditure data ensure consistency.
Sensitivity analysis across API price volatility scenarios and regulatory pathway timeline variations tests forecast robustness throughout the projection horizon. The analytical framework segments by product type, technology platform, application indication, and end-user channel, with additional dimensioning by regional regulatory cluster reflecting divergence between stringent and emerging market evidence standards. CAGRs derive from installed base erosion rates for daily oral regimens and penetration velocity for long-acting reversible methods. Forecast inputs encompass community health worker network expansion trajectories and national health insurance reimbursement coverage decisions.
The analysis sits within stated boundaries; outcomes outside sustained multilateral funding commitments or accelerated FDA over-the-counter switching timelines would require recalibration. Forecasts reflect documented assumptions regarding WHO prequalification eligibility rates and cold-chain infrastructure buildout pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Anastrozole Tablets Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Oral Thin Film Drugs Market