
 Throat Sprays Market | 2026-2036
Throat Sprays Market Size, Share, and Industry Trends Forecast 2026-2036
Throat Sprays Market Analytics
Chinese contract manufacturers is hardening supply-side capacity for throat spray actives and propellant systems. Prestige Consumer Healthcare leverages private-label scale across North American pharmacy chains. Procter & Gamble sustains brand equity through multi-symptom portfolio positioning. GlaxoSmithKline anchors European distribution with clinician-endorsed medicated formats.
Throat sprays are aqueous or alcohol-based liquid formulations delivered via mechanical pump or pressurized aerosol to deposit active agents onto pharyngeal mucosa, typically containing benzocaine, phenol, or herbal extracts at concentrations between 0.5% and 1.4% w/v for local anesthetic or antiseptic effect. Their primary purpose is to provide rapid symptomatic relief of sore throat, irritation, or minor infection without systemic drug absorption. Antiseptic and anesthetic product types command the largest revenue share due to established clinical validation and insurance-adjacent reimbursement in several markets. Herbal and moisturizing segments are gaining fastest traction among ingredient-sensitive consumers, though margin pools remain thinner due to limited premiumization and commodity botanical sourcing.
FDA over-the-counter monograph compliance, EMA MDR requirements for device-drug combinations, and ISO 13485 quality management standards collectively elevate barrier costs for new entrants while reinforcing incumbent positions. These frameworks shape demand by mandating stability testing, child-resistant packaging, and label claims substantiation that favor scaled manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor evolving monograph reform timelines and ingredient restriction proposals to anticipate portfolio rebalancing requirements.
Market Dynamics
OTC pharmacy channels are consolidating shelf access around scaled manufacturers with dedicated regulatory affairs infrastructure, compressing margin pools for mid-tier entrants unable to absorb FDA monograph compliance and EMA MDR testing costs.
Growth Catalysts
- Aging demographics in Germany, Japan, and the United States:Recurrent seasonal illness patterns among elderly populations sustain repeat purchase behavior and expand addressable household penetration for symptomatic relief products.
- EMA MDR device-drug combination pathways:Clinician-endorsed medicated formats gain pharmacy preference and partial reimbursement eligibility in European markets, anchoring premium positioning.
- Self-managed respiratory care prioritization:Post-pandemic consumer behavior favors immediate-access OTC solutions over physician consultation delays, driving traffic through pharmacy and convenience retail channels.
Market Restraints
- Active pharmaceutical ingredient disclosure mandates:FDA tightening on benzocaine and phenol sourcing documentation elevates formulation costs and extends stability testing timelines for new entrants.
- Propellant system supply concentration:Chinese contract manufacturers dominate HFA-152a and DME propellant capacity, creating input cost volatility and geographic supply risk for aerosol-format producers.
- Herbal extract standardization gaps:Commodity botanical sourcing without pharmacopeial-grade certification limits premiumization potential and invites quality inconsistency liabilities.
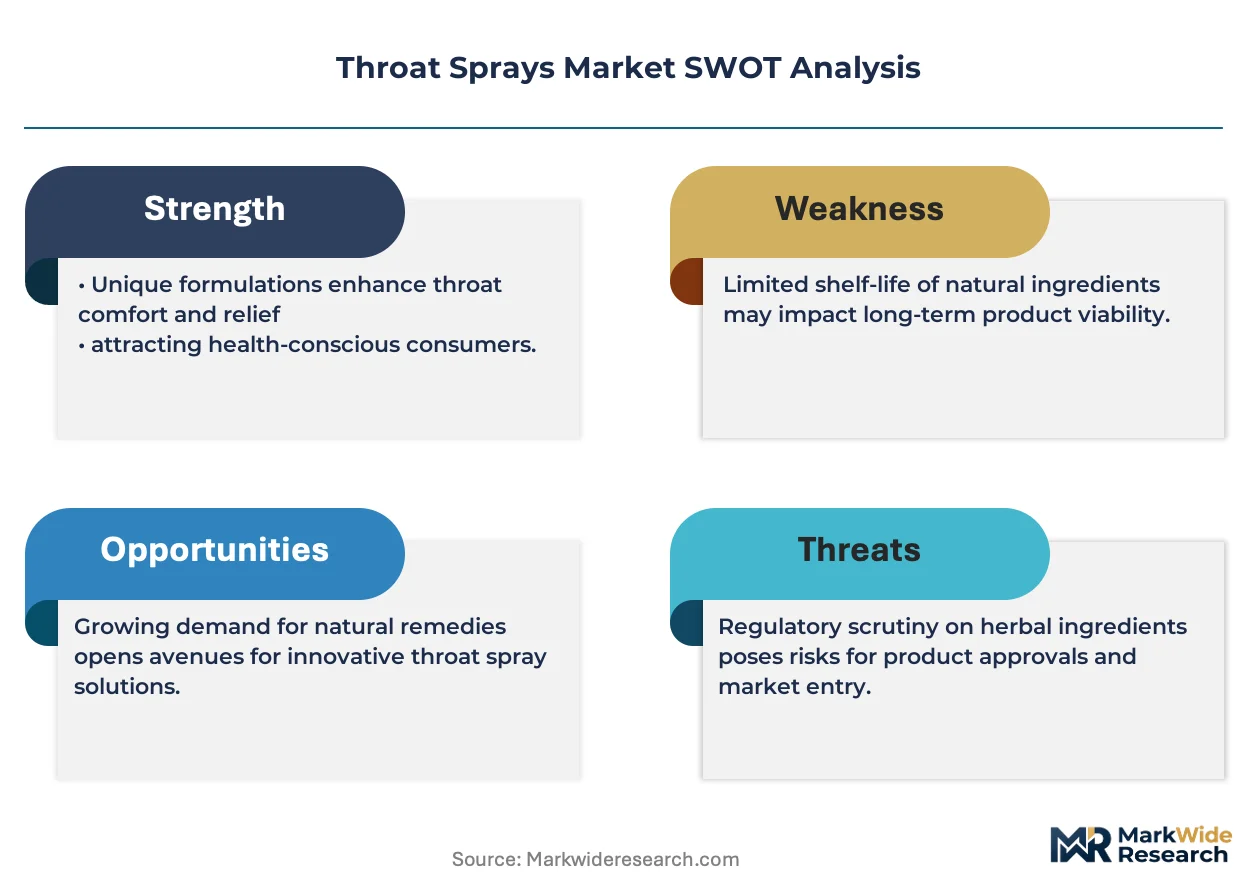
Strategic Opportunities
- Moisturizing segment white space:Ingredient-sensitive consumers in the United States and Germany demonstrate willingness to pay for hyaluronic acid and glycerin-based alternatives to traditional anesthetic formats.
- ISO 13485-certified contract manufacturing:Quality management standardization enables mid-tier brands to access pharmacy chain private-label programs previously reserved for scaled incumbents.
- Direct-to-consumer subscription models:Seasonal illness predictability supports recurring revenue capture through automated replenishment, bypassing traditional wholesale margin extraction.
Industry Challenges
- Regulatory affairs talent scarcity:Specialized expertise in FDA OTC monograph navigation and EMA MDR technical documentation commands premium compensation, constraining mid-cap manufacturer expansion velocity.
- Child-resistant packaging certification timelines:ISO 8317 and US 16 CFR 1700.20 testing protocols extend product launch cycles by 8-14 months, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Throat Sprays Market |
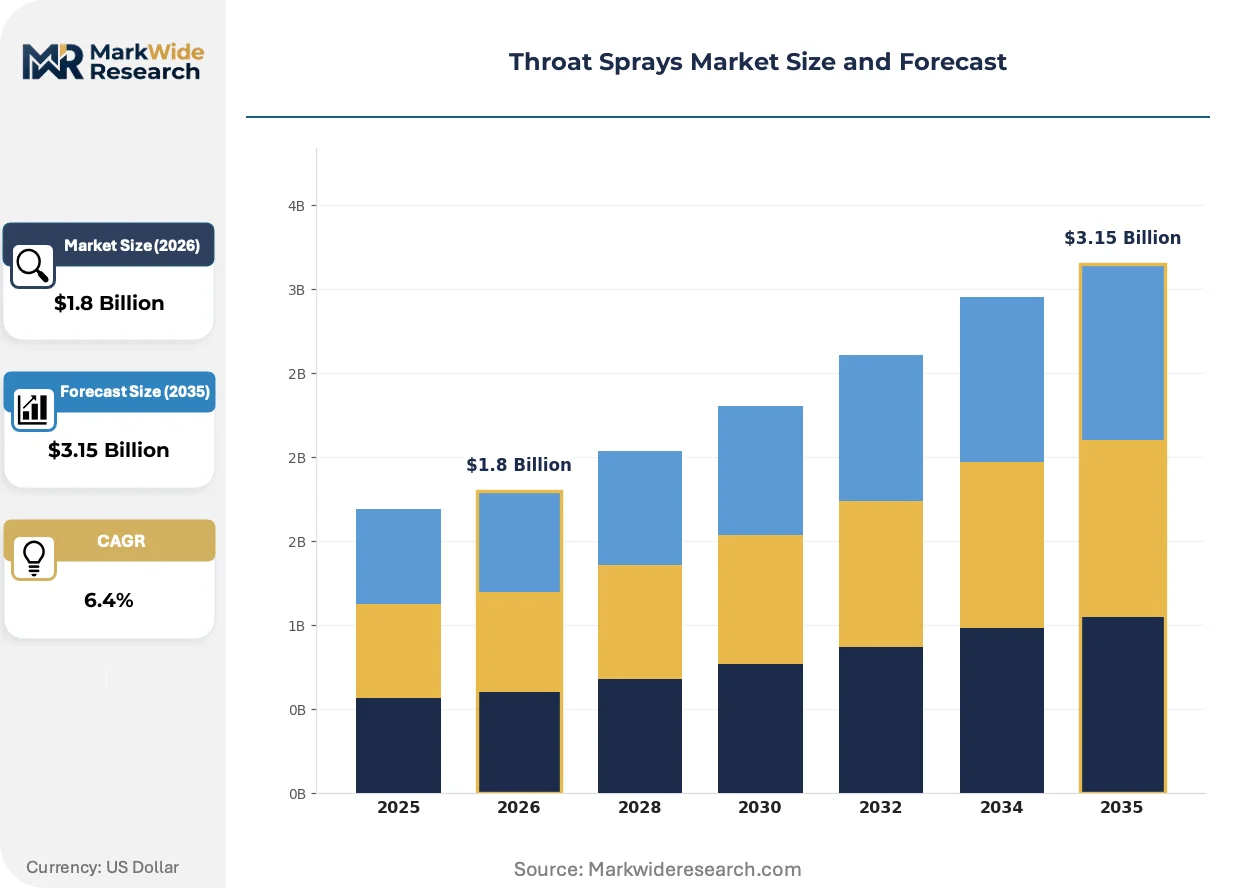
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiseptic, Anesthetic, Herbal, Moisturizing Delivery Mode: Aerosol, Pump Spray, Dropper, Gel End User: Adults, Pediatrics, Geriatrics, Athletes Ingredient Type: Natural, Synthetic, Antibacterial, Antiviral |
| Companies Covered | Prestige Consumer Healthcare Inc., Purdue Pharma, Procter & Gamble, iNova Pharmaceuticals, Marinomed Biotech AG, Johnson & Johnson, Cipla Limited, GlaxoSmithKline, Reckitt Benckiser Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Throat Sprays Market Evolving Landscape
Mechanical pump delivery systems are displacing pressurized aerosol formats as environmental and formulation stability concerns reshape manufacturer R&D priorities and pharmacy shelf composition.
Alcohol-free aqueous bases with enhanced mucoadhesion polymers are overtaking traditional ethanol-dominant formulations in European and North American pharmacy channels. Pediatric and geriatric end-use segments are driving adoption due to reduced mucosal irritation and improved taste masking. This technology is compressing market share for legacy phenol-alcohol combinations that dominated the 2010-2020 period.
REACH candidate list scrutiny of synthetic preservatives is forcing reformulation cycles across European manufacturing operations. ECHA notification requirements for benzalkonium chloride alternatives are accelerating investment in GRAS-certified natural antimicrobial systems. Medicated throat spray segments in Germany and France are absorbing the highest compliance costs, driving portfolio consolidation toward fewer, higher-volume SKUs.
Ingredient transparency claims are reshaping consumer purchase criteria and retail buyer negotiation leverage. Clean-label certification from third-party validators is displacing unverified "natural" marketing claims in United States pharmacy chain assortment decisions. This shift concentrates shelf access among manufacturers with documented supply chain audit trails and published excipient sourcing protocols.
Throat Sprays Market Segmentation
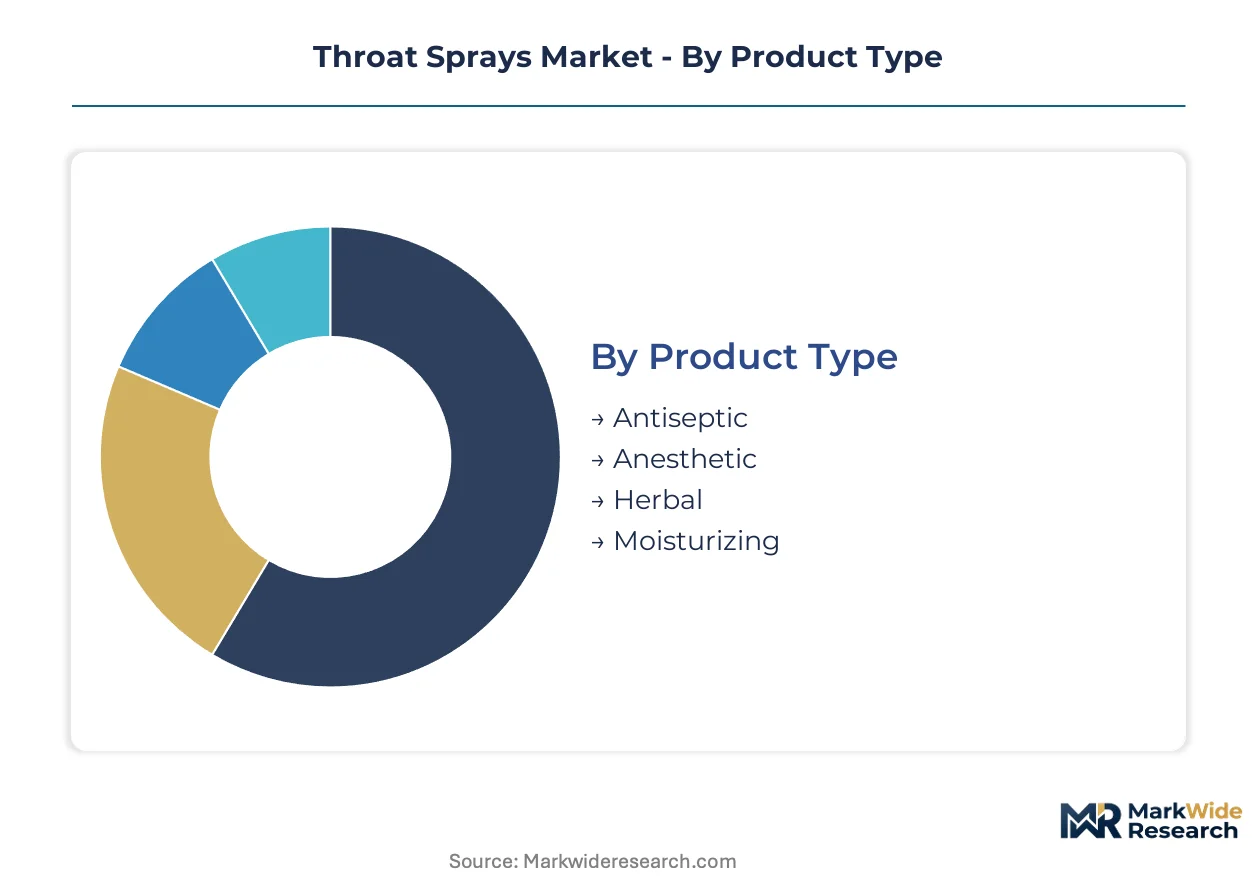
Throat spray purchasing decisions hinge on symptom severity, speed of relief required, and ingredient sensitivity thresholds. Manufacturers align portfolio architecture around these decision nodes to capture pharmacy shelf space and direct-to-consumer traffic.
Product Type:
Buyers prioritize clinical validation and reimbursement proximity when selecting symptomatic relief formats.
- Antiseptic:Phenol and benzalkonium chloride formulations at 0.5-1.4% w/v deliver broad-spectrum microbial control. Pharmacy chains in the United States and Germany allocate prime shelf positioning to these SKUs due to clinician familiarity and partial insurance adjacency.
- Anesthetic:Benzocaine-based sprays provide rapid numbness for acute pharyngeal pain. Repeat purchase rates among elderly populations in Japan sustain manufacturer investment in stability-enhanced formulations despite FDA documentation tightening on active sourcing.
- Herbal:Echinacea and propolis extracts appeal to ingredient-avoidant consumers seeking botanical alternatives to synthetic actives.
- Moisturizing:Hyaluronic acid and glycerin formulations target dryness without anesthetic effect, expanding fastest among vocal professionals and allergy sufferers.
Volume sits with Antiseptic and Anesthetic; growth tilts toward Moisturizing as premium positioning gains traction in pharmacy channels.
Delivery Mode:
Environmental compliance costs and formulation stability requirements reshape manufacturer R&D allocation across mechanical and pressurized systems.
- Aerosol:HFA-152a and DME propellant systems deliver fine particle deposition but face supply concentration risk from Chinese contract manufacturers. European regulators are scrutinizing F-Gas Regulation alignment, elevating reformulation timelines for legacy products.
- Pump Spray:Mechanical actuators eliminate propellant dependency and enable alcohol-free aqueous bases. ISO 13485-certified producers in Germany and the United States are capturing shelf space as pharmacy buyers prioritize environmental claims.
- Dropper:Direct liquid application suits pediatric dosing precision but limits portability compared to spray formats.
- Gel:Viscous mucoadhesive systems extend contact time on pharyngeal tissue, commanding niche positioning in clinician-directed segments.
Installed base favors Aerosol; competitive investment flows toward Pump Spray as REACH compliance deepens.
End User:
Age-specific mucosal sensitivity and usage context determine formulation tolerability and packaging requirements.
- Adults:The core revenue pool consumes standard anesthetic and antiseptic formats through pharmacy and convenience retail. Workplace absenteeism avoidance drives impulse purchase behavior during cold and flu season.
- Geriatrics:Dry mouth comorbidities and medication interactions elevate demand for alcohol-free moisturizing alternatives. Japan's aging demographic sustains dedicated SKU development with enhanced taste masking.
- Pediatrics:Child-resistant packaging mandates under US 16 CFR 1700.20 extend launch timelines but create defensive moats for compliant manufacturers.
- Athletes:Pre-competition vocal warm-up and post-exertion irritation management drive adoption of rapid-onset, non-drowsy formats.
Adult segments dominate transaction volume; Geriatrics and Pediatrics are climbing the fastest as demographic shifts and regulatory specialization deepen.
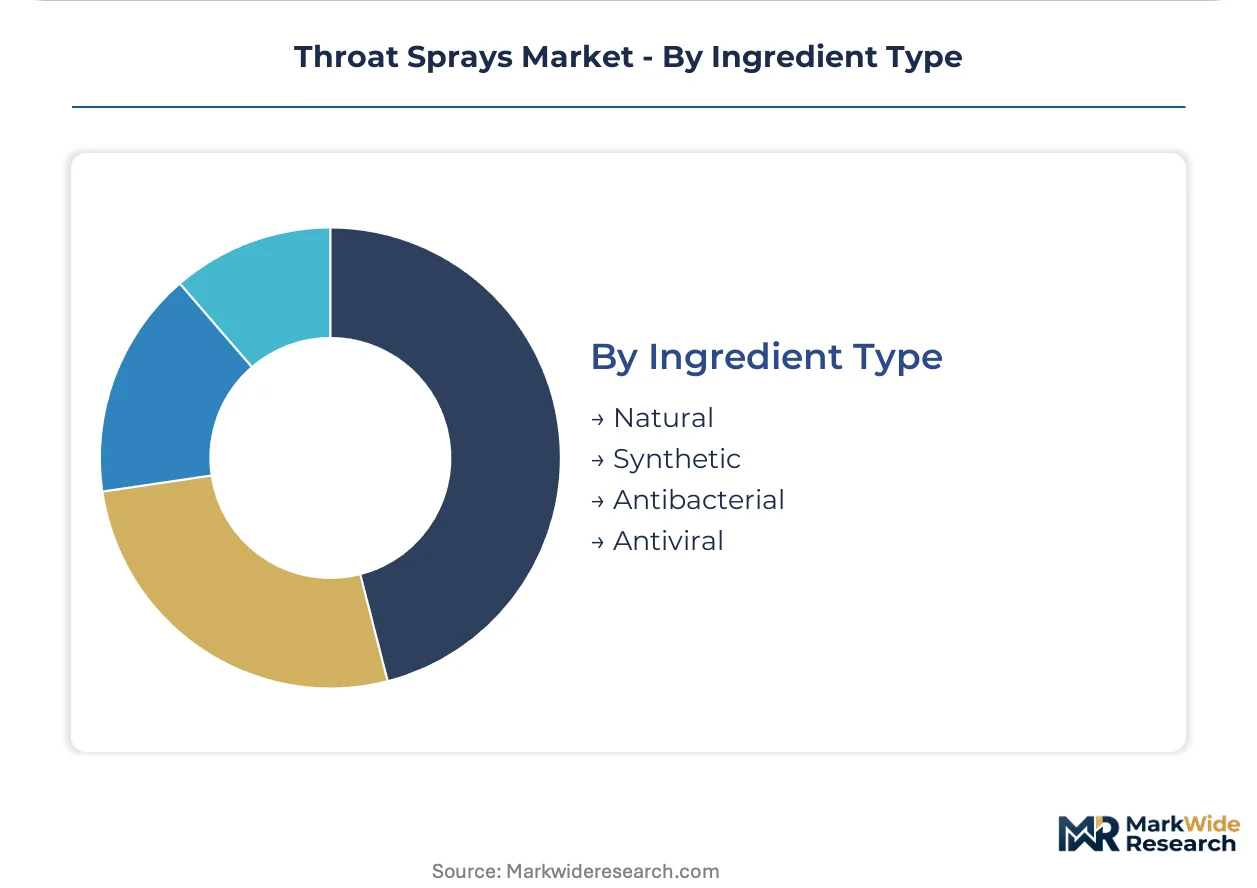
Ingredient Type:
Supply chain auditability and pharmacopeial certification now gate retail access more than clinical efficacy alone.
- Natural:GRAS-certified botanicals with documented excipient sourcing protocols satisfy clean-label certification requirements from United States pharmacy chain validators.
- Synthetic:Benzocaine and phenol derivatives retain cost advantages and established monograph pathways but face disclosure mandate escalation from FDA.
- Antibacterial:Targeted microbial control beyond broad-spectrum antisepsis, positioned for post-surgical and immunocompromised use cases.
- Antiviral:Emerging category addressing viral pharyngitis etiologies, constrained by limited OTC approval pathways in major markets.
Commercial concentration remains with Synthetic; Natural formulations are gaining share fastest as procurement shifts toward certified supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese propellant chemical clusters around Shanghai and Zhejiang anchor upstream supply for aerosol-format throat sprays, while finished-formulation demand concentrates in aging Western economies with established pharmacy infrastructure.
United States
Repeat purchase behavior among elderly consumers sustains OTC pharmacy channel dominance for symptomatic relief products. FDA over-the-counter monograph compliance mandates elevate barrier costs for new entrants, reinforcing incumbent shelf positions. New Jersey and Pennsylvania host concentrated manufacturing operations for scaled private-label producers serving national pharmacy chains.
Germany
EMA MDR device-drug combination pathways enable clinician-endorsed medicated formats to secure partial reimbursement eligibility. REACH candidate list scrutiny of synthetic preservatives forces reformulation investment in GRAS-certified natural antimicrobial systems. Bavaria's ISO 13485-certified contract manufacturers capture expanding private-label demand from European pharmacy buyers.
Japan
PMDA stability requirements for benzocaine-based anesthetic sprays sustain dedicated SKU development with enhanced taste masking for geriatric populations. METI guidance on alcohol-free aqueous formulations accelerates mechanical pump adoption over pressurized aerosol systems. Kanto region pharmaceutical clusters concentrate R&D investment for moisture-retaining polymer technologies.
China
Contract manufacturers in Jiangsu and Shandong harden capacity for throat spray actives and HFA-152a propellant systems, creating supply-side leverage over global aerosol-format producers. NMPA documentation requirements for active pharmaceutical ingredient sourcing extend stability testing timelines for export-bound formulations. Dual carbon goals pressure domestic producers toward pump-spray environmental compliance.
India
CDSCO regulatory alignment with FDA monograph standards positions domestic manufacturers for North American contract manufacturing opportunities. CDSCO's tightening on benzalkonium chloride alternatives accelerates botanical extract sourcing from Karnataka and Maharashtra agricultural zones. Mumbai-Pune pharmaceutical corridor concentrates formulation expertise for alcohol-free pediatric formats.
Throat Sprays Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ingredient-transparent and moisturizing segments where premium positioning remains underdeveloped. Market structure consolidates around scaled manufacturers with dedicated regulatory affairs infrastructure capable of absorbing FDA and EMA compliance costs. Three archetypes dominate: multinational consumer health conglomerates with pharmacy chain scale, mid-tier specialists with ISO-certified contract manufacturing capabilities, and regional pharmaceutical houses leveraging local botanical sourcing. Competitive moves concentrate on portfolio diversification into alcohol-free aqueous bases and strategic partnerships with Chinese propellant suppliers to secure input cost stability.
Among North American consumer health conglomerates, Prestige Consumer Healthcare Inc. and Procter & Gamble exemplify the scale-driven archetype with private-label and multi-symptom portfolio positioning respectively. GlaxoSmithKline occupies a position within the European clinician-endorsed tier, anchoring medicated format distribution through pharmacy channel relationships. These three entities represent the dominant competitive anchors against which mid-tier ISO-certified specialists and regional botanical houses define their market entry strategies.
| Leading Market Players |
|---|
| Prestige Consumer Healthcare Inc. |
| Purdue Pharma |
| Procter & Gamble |
| iNova Pharmaceuticals |
| Marinomed Biotech AG |
| Johnson & Johnson |
| Cipla Limited |
| GlaxoSmithKline |
| Reckitt Benckiser Group |
| Others |
Value Network & Pricing Analysis
Captive integration into Chinese propellant manufacturing anchors both supply security and pricing power for aerosol-format producers, while ISO 13485-certified contract manufacturers in Germany and the United States command premium positioning through quality-assured pump-spray alternatives that bypass propellant dependency entirely.
Pricing Analysis
Warranty-backed stability guarantees separate premium anesthetic formulations from unbundled herbal alternatives in pharmacy chain negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA monograph compliance tiering and ISO certification status. Cost compression in mid-tier antiseptic segments intensifies because Chinese contract manufacturers are hardening capacity for throat spray actives. Price-sensitive consumers in India and Southeast Asia gravitate toward unbranded synthetic formulations, while vocal professionals in Germany demonstrate lowest price sensitivity for moisturizing hyaluronic acid SKUs.
Supply Chain Analysis
ISO 13485 and FDA OTC monograph compliance gating concentrates finished-formulation capacity among scaled manufacturers with dedicated regulatory affairs infrastructure. Active pharmaceutical ingredients draw from Chinese chemical clusters around Shanghai and Zhejiang, German precision pump actuator producers, and Indian botanical extract suppliers in Karnataka. HFA-152a and DME propellant dependencies rest on single-source vulnerability from Chinese contract manufacturers dominating global capacity. Distribution runs through OTC pharmacy chains in the United States and Germany, with direct-to-consumer subscription models emerging as secondary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation is forcing portfolio consolidation toward fewer, higher-volume SKUs, eliminating mid-tier entrants unable to absorb FDA and EMA testing timelines.
For Market Incumbents: Deepen backward integration into Chinese propellant supply through long-term offtake agreements with Jiangsu and Shandong manufacturers, insulating against input cost volatility. Expand ISO 13485-certified contract manufacturing capacity in Bavaria to capture European pharmacy private-label demand as REACH compliance deepens. For New Entrants and Emerging Players: Enter via the moisturizing segment white space in the United States and Germany, where hyaluronic acid and glycerin formulations face limited incumbent saturation. Pursue clean-label certification from third-party validators to displace unverified "natural" marketing claims in pharmacy chain assortment decisions. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of ISO-certified mid-tier specialists with documented supply chain audit trails and established regulatory affairs teams. Long-term viability hinges on portfolio diversification into alcohol-free aqueous bases and mechanical pump formats. Watch for EMA MDR reform timelines as inflection indicators for European reimbursement eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management standardization enables pharmacy chain private-label access previously reserved for scaled incumbents. |
| Alcohol-Free Formulation Transition | REACH candidate list scrutiny of synthetic preservatives forces GRAS-certified natural antimicrobial system adoption. |
| Direct-to-Consumer Subscription Launch | Seasonal illness predictability supports recurring revenue capture bypassing traditional wholesale margin extraction. |
| Chinese Propellant Supply Partnership | Long-term offtake agreements with Shanghai and Zhejiang manufacturers mitigate HFA-152a input cost volatility. |
| Clean-Label Certification Program | Third-party validator documentation displaces unverified marketing claims in United States pharmacy buyer negotiations. |
Research Methodology
Independent corroboration across regulatory filings, trade customs data, and channel inventory audits underwrites the qualitative findings in this analysis. Primary interviews with regulatory affairs directors, pharmacy chain category buyers, contract manufacturing executives, and clinical formulary specialists combined with secondary validation from FDA OTC monograph updates, EMA MDR submission databases, and ISO certification registries. Bottom-up SKU-level volume builds and top-down demographic penetration models triangulate to segment-level estimates.
Historical reference periods spanning pre-pandemic baselines through post-pandemic behavioral shifts anchor the forecast window across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end-user demographic, and ingredient certification tier. CAGRs derive from logistic diffusion curves fitted to pharmacy channel inventory turns and seasonal illness incidence patterns. Forecast inputs incorporate propellant supply concentration metrics and regulatory reform timeline probabilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA MDR acceleration or FDA benzocaine sourcing restriction scenarios. Forecasts reflect assumptions documented in the segmentation framework and regional outlook sections. A model refresh is warranted upon material change in REACH candidate list expansion or Chinese dual carbon goal enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Human Combination Vaccines Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market