
 Nuclear Medicines Radioisotopes Market | 2026-2036
Nuclear Medicines Radioisotopes Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Medicines Radioisotopes Market Intelligence
Reactor-based production of medical radioisotopes is decoupling from reliance on a few aging, government-owned nuclear facilities. NorthStar Medical Radioisotopes pioneers non-uranium-based technetium-99m production, directly addressing historical supply vulnerabilities. Curium Pharma leverages its global network of cyclotrons and reactors to ensure consistent supply across diverse geographies. GE HealthCare sustains its market position through tightly integrated offerings of advanced imaging systems and companion radiopharmaceuticals.
Nuclear medicines radioisotopes are unstable atoms that emit radiation as they decay, a property harnessed for medical purposes. These materials, such as the common gamma-emitter Technetium-99m, are formulated into radiopharmaceuticals for either diagnostic imaging or targeted therapeutic intervention. Diagnostic imaging applications, particularly in cardiology scans, represent the largest current use case, while oncology treatments using therapeutic isotopes are the fastest-expanding segment. Hospitals and specialized diagnostic centers form the primary end-user base for these critical medical products.
Market access and manufacturing practices are strictly governed by powerful national and regional bodies, including the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA). These agencies enforce stringent current Good Manufacturing Practice (cGMP) guidelines on radiopharmaceutical purity, safety, and efficacy. In parallel, organizations like China's National Medical Products Administration (NMPA) oversee a rapidly expanding domestic market with its own approval pathways. Stakeholder success will hinge on navigating complex supply logistics for short-lived isotopes and securing approvals for next-generation theranostic agents.
Market Dynamics
The central dynamic shaping the nuclear medicines radioisotopes market is the tension between rapid innovation in theranostic agents and the capital-intensive, highly regulated supply chain required to produce and deliver these short-lived materials globally.
Growth Catalysts
- Targeted Radionuclide Therapy:The expansion of theranostics, which pairs diagnostic imaging with targeted radiotherapy using novel alpha and beta-emitting isotopes, is creating significant clinical demand within oncology for more precise cancer treatments.
- Government Supply Initiatives:Policies like the American Medical Isotopes Production Act in the United States encourage the development of domestic, non-uranium-based isotope production, aiming to secure national supply chains against global disruptions.
- Aging Demographics:A growing elderly population worldwide corresponds with a higher incidence of cancer and cardiovascular disease, directly increasing the volume of diagnostic imaging procedures and therapeutic interventions that rely on radioisotopes.
Market Restraints
- Logistical Complexity:The extremely short half-lives of critical isotopes, such as Technetium-99m, necessitate a complex, time-sensitive, and costly global logistics network, creating a significant barrier to consistent supply.
- High Capital Investment:The construction, operation, and decommissioning of nuclear reactors and cyclotrons for isotope production require massive capital expenditure and long lead times, limiting the number of new entrants.
- Stringent Regulatory Hurdles:Lengthy and rigorous approval processes enforced by agencies like the US FDA and the European Medicines Agency for new radiopharmaceuticals and manufacturing facilities can delay market entry.
Strategic Opportunities
- Geographic Expansion:There is a significant opportunity to expand into developing healthcare markets in regions like Latin America and Southeast Asia, where investments in diagnostic imaging infrastructure are increasing.
- Neurological Applications:The development of novel radiotracers for diagnosing and potentially treating neurodegenerative diseases, such as Alzheimer's and Parkinson's, represents a major frontier for market expansion beyond oncology and cardiology.
- AI-Enhanced Diagnostics:Integrating artificial intelligence with PET and SPECT imaging data can enhance diagnostic accuracy and quantify treatment response, creating value-added services around existing radiopharmaceutical products.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of qualified nuclear pharmacists, radiochemists, and medical physicists creates bottlenecks in production, quality control, and the clinical administration of radiopharmaceuticals.
- Waste Disposal and Decommissioning:The management and disposal of radioactive waste, along with the high costs of decommissioning aging production facilities, pose significant long-term financial and environmental challenges for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Medicines Radioisotopes Market |
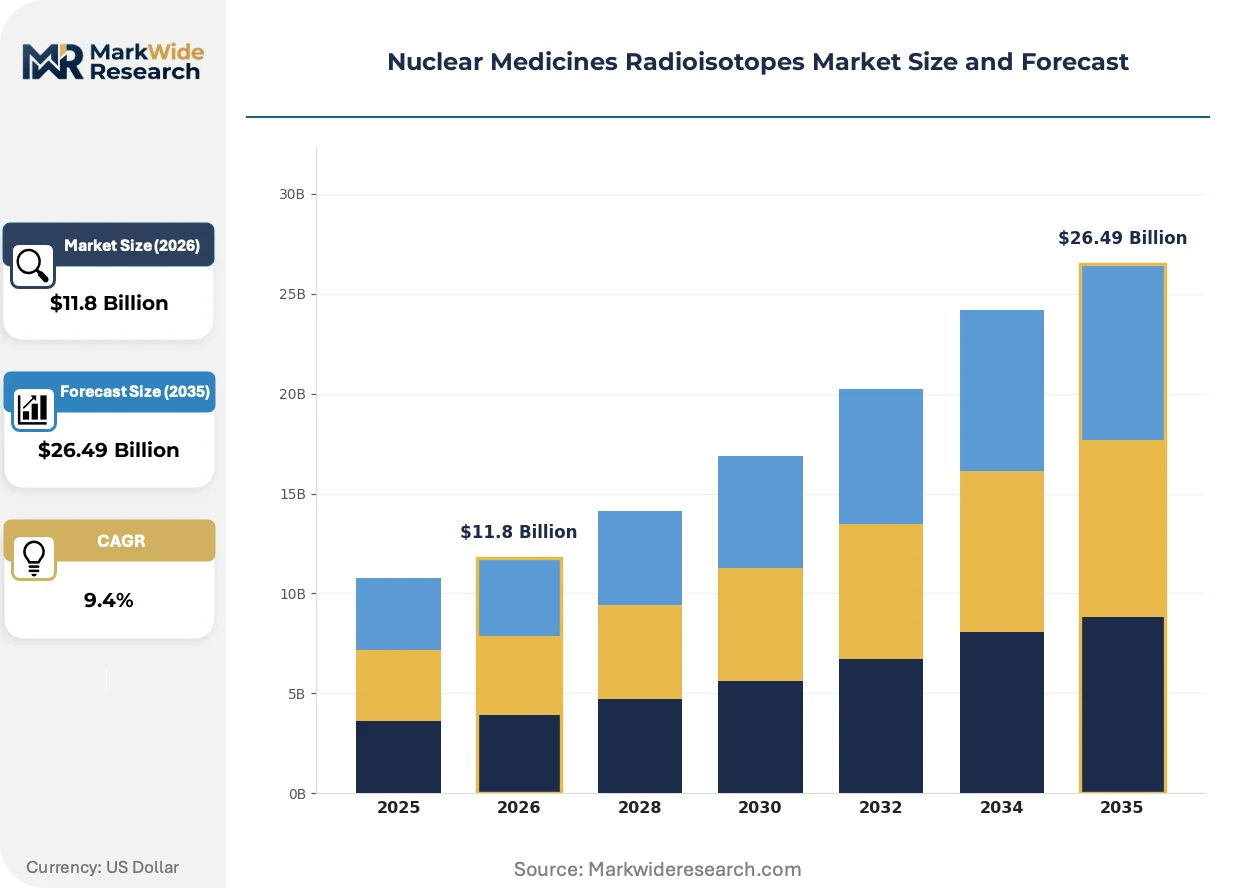
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Radioisotope Type: Technetium-99m, Iodine-131, Fluorine-18, Gallium-68, Thallium-201 Application: Diagnostic Imaging, Radiotherapy, Cardiology Scan, Oncology Treatment, Neurology Diagnostics End User: Hospitals, Diagnostic Centers, Research Institutes, Pharmaceutical Companies, Specialty Clinics Production Method: Reactor-Based, Cyclotron-Based, Generator-Based, Accelerator-Based, Batch Processing |
| Companies Covered | GE HealthCare, Cardinal Health, Siemens Healthineers, Curium Pharma, Lantheus Holdings, Novartis AG, NorthStar Medical Radioisotopes, Eckert & Ziegler, Bracco Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Medicines Radioisotopes Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive pivot from purely diagnostic imaging towards integrated therapeutic applications. This shift is enabled by novel production methods that improve the availability of next-generation isotopes for targeted cancer therapy.
Targeted alpha therapy (TAT) utilizes potent alpha-emitting isotopes like Actinium-225 to deliver highly localized radiation to cancer cells. Advanced oncology centers and research hospitals are rapidly adopting these therapies for difficult-to-treat, late-stage cancers. The demonstrated clinical efficacy of these agents is consolidating their role as a critical treatment modality for specific metastatic diseases, displacing less-targeted approaches.
Regulatory frameworks are adapting to the rise of personalized medicine. The European Medicines Agency, through initiatives aligned with the EU's Beating Cancer Plan, is developing more flexible pathways for the evaluation of complex radiopharmaceuticals. This shift supports faster, though still rigorous, review cycles for theranostic agents. Consequently, developers with robust pan-European clinical trial data are best positioned to navigate these evolving EMA approval channels.
A notable change in purchasing behavior is emerging among large healthcare providers. Hospital networks are moving beyond simple per-dose procurement and toward comprehensive supply agreements that bundle radiopharmaceuticals with imaging systems and data analytics software. This disrupts the fragmented, transactional purchasing model historically prevalent in the market. This trend is most visible in the United States, where integrated delivery networks leverage their purchasing power to secure more holistic solutions from suppliers.
Nuclear Medicines Radioisotopes Market Segmentation
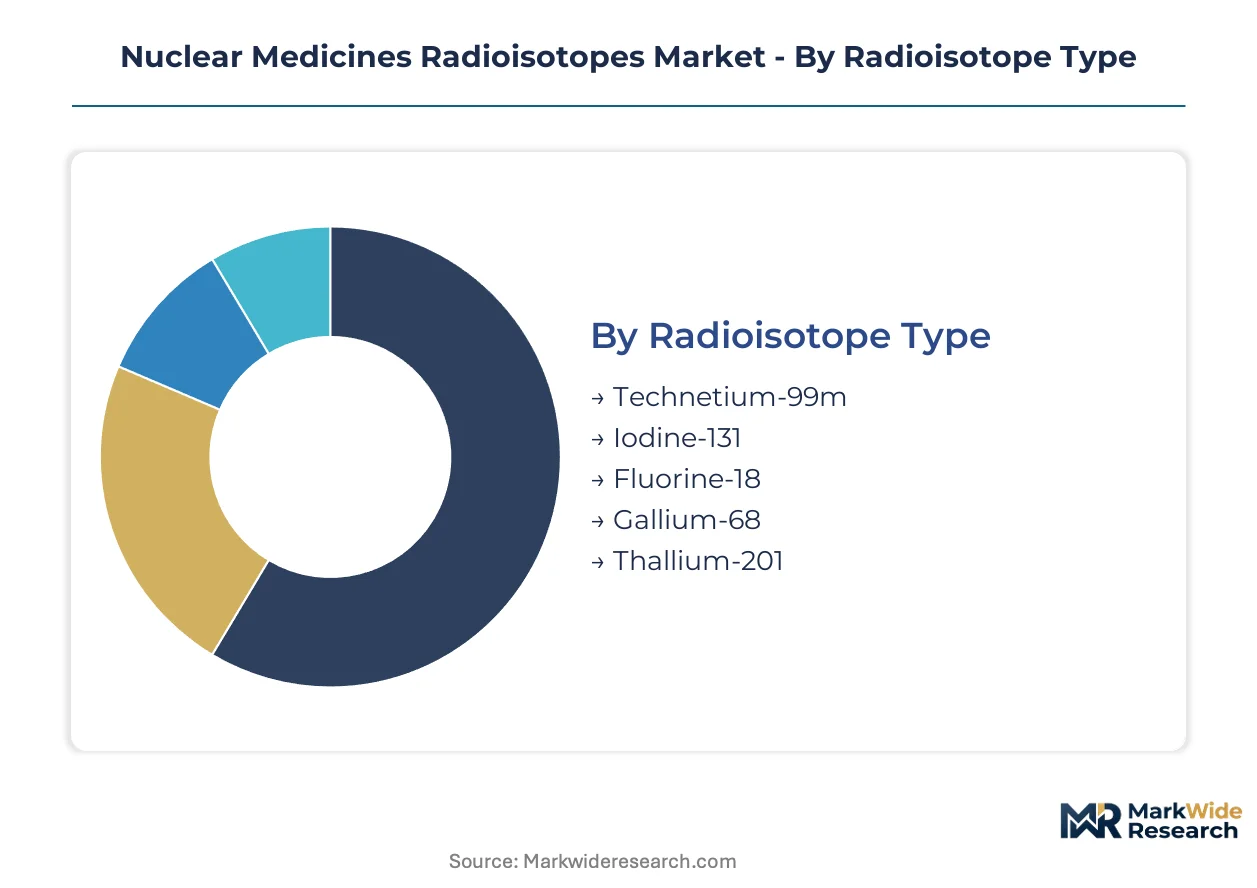
The nuclear medicines radioisotopes market is categorized by distinct attributes influencing product development, supply chain dynamics, and end-user adoption. Understanding these segments provides clarity on where investment in production capacity and novel radiopharmaceutical research is most impactful. Each segment reflects specific clinical needs and technological advancements driving market evolution.
Radioisotope Type:
The choice of radioisotope type often hinges on the specific diagnostic or therapeutic requirement for a patient.
- Technetium-99m:This common gamma-emitting isotope is used extensively in diagnostic imaging, particularly for SPECT scans of the heart, brain, and bones. Its short half-life necessitates efficient, localized production and rapid distribution to hospitals in the United States and Europe.
- Fluorine-18:A positron-emitting isotope primarily used in PET imaging for oncology, neurology, and cardiology. Demand concentrates heavily within advanced diagnostic centers in Germany and Japan, driven by its precision in detecting metabolic activity in tumors.
- Iodine-131:A beta-gamma emitter primarily utilized for treating thyroid cancer and hyperthyroidism. Its application is widespread across various global healthcare systems for targeted radiotherapy.
- Gallium-68:This positron emitter is increasingly used in PET imaging, particularly with somatostatin analogs for neuroendocrine tumors. Its use is expanding in specialized oncology clinics.
- Thallium-201:A gamma emitter used in myocardial perfusion imaging to assess blood flow to the heart. This isotope remains relevant for specific cardiac diagnostic procedures.
Technetium-99m leads on scale; Fluorine-18 leads on momentum.
Application:
The diverse medical applications of radioisotopes dictate their formulation and clinical utility.
- Diagnostic Imaging:This segment encompasses the largest volume of radioisotope use, enabling non-invasive visualization of organ function and disease detection. Demand remains high in cardiology and oncology departments across developed healthcare markets.
- Oncology Treatment:This rapidly expanding segment utilizes therapeutic radioisotopes to target and destroy cancer cells with minimal damage to healthy tissue. Novel alpha and beta emitters are driving significant growth in advanced cancer centers in Europe and North America.
- Cardiology Scan:Radioisotopes are critical for assessing heart function, blood flow, and identifying coronary artery disease. These scans are a routine diagnostic tool in hospitals globally.
- Radiotherapy:This application involves using radioactive materials to treat various diseases, including specific cancers. It represents a significant therapeutic intervention.
- Neurology Diagnostics:Radioisotopes assist in diagnosing neurological conditions like Alzheimer's and Parkinson's disease by imaging brain activity. Research institutes are developing new tracers for this field.
Diagnostic imaging applications hold significant market share, while oncology treatments are expanding most quickly.
End User:
Different end-user facilities procure radioisotopes based on their specialized medical service offerings and patient volumes.
- Hospitals:These institutions represent the largest end-user segment, utilizing radioisotopes for a broad spectrum of diagnostic and therapeutic procedures across various departments. Large hospital networks in the United States often secure comprehensive supply agreements.
- Diagnostic Centers:Specialized facilities focusing solely on imaging services, including PET and SPECT scans, are significant consumers of diagnostic radioisotopes. These centers require consistent supply for their high patient throughput.
- Research Institutes:Academic and private research institutions use radioisotopes for preclinical studies, drug development, and advancing nuclear medicine techniques. They often require specialized or experimental isotopes.
- Pharmaceutical Companies:These companies develop and commercialize radiopharmaceuticals, requiring radioisotopes for manufacturing and clinical trials. They are critical for bringing new theranostic agents to market.
- Specialty Clinics:Focused clinics, such as those for oncology or cardiology, utilize radioisotopes for targeted treatments or specific diagnostic tests. Their procurement is often for niche applications.
Hospitals represent the foundational demand, with specialized diagnostic centers also showing consistent procurement.
Production Method:
The method of production significantly influences the availability, cost, and specific isotope output for medical use.
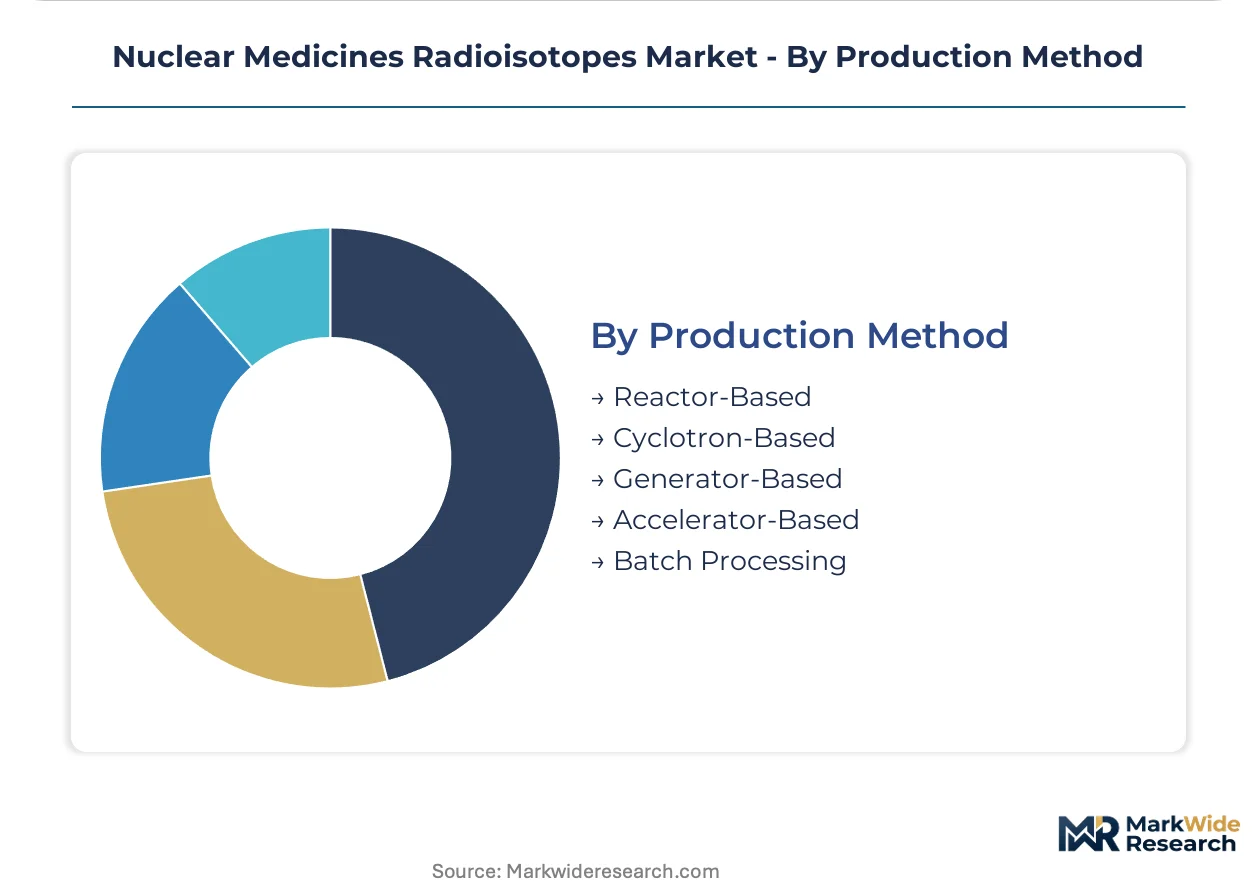
- Reactor-Based:This traditional method produces a range of radioisotopes, including Technetium-99m precursors, through neutron irradiation of target materials. It remains a primary source for high-volume, widely used isotopes.
- Cyclotron-Based:Cyclotrons produce short-lived, positron-emitting isotopes like Fluorine-18 and Gallium-68, crucial for PET imaging. Their decentralized nature helps mitigate logistical challenges for hospitals in urban centers.
- Generator-Based:Generators provide a convenient, on-site source of short-lived isotopes, such as Technetium-99m, derived from longer-lived parent isotopes. This method simplifies distribution to end-user facilities.
- Accelerator-Based:Accelerators offer an alternative production route for certain radioisotopes, reducing reliance on nuclear reactors. This technology is gaining traction for securing diversified supply chains.
- Batch Processing:This method refers to the production of radioisotopes in discrete quantities, often for specific therapeutic applications or smaller-scale diagnostic needs. It allows for flexible production schedules.
Reactor-based methods remain central to high-volume isotope supply, with cyclotron-based production expanding its footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States demonstrates robust demand for novel theranostic agents, while China rapidly expands its domestic production capabilities. These regional dynamics reflect differing stages of healthcare infrastructure maturity and regulatory environments. Global market growth is influenced by localized production and distribution networks.
United States
Demand for diagnostic imaging and targeted radionuclide therapy is significant in the United States. The American Medical Isotopes Production Act fosters domestic, non-uranium-based isotope production. Major research and healthcare hubs like Boston and Houston drive innovation and clinical adoption of new radiopharmaceuticals.
Germany
Germany exhibits strong demand for advanced diagnostic imaging, particularly PET scans utilizing Fluorine-18. The European Medicines Agency (EMA) oversees strict regulatory pathways for radiopharmaceuticals within Germany. The Rhine-Main region, with its pharmaceutical clusters, supports specialized radiopharmaceutical manufacturing and distribution.
Japan
Japan’s aging population fuels consistent demand for cardiology scans and oncology diagnostics. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous oversight of radiopharmaceutical safety and efficacy. Tokyo and Osaka host advanced diagnostic centers and research institutes focusing on neurological applications.
China
China’s expanding healthcare infrastructure is increasing the uptake of nuclear medicine diagnostics and therapies. The National Medical Products Administration (NMPA) regulates a rapidly growing domestic market for radioisotopes. Shanghai and Beijing are emerging as key centers for radiopharmaceutical production and clinical trials.
India
India's healthcare sector is witnessing investments in diagnostic imaging facilities, boosting radioisotope consumption. The Central Drugs Standard Control Organization (CDSCO) manages approvals for radiopharmaceuticals within the country. Major metropolitan areas like Mumbai and Delhi are developing specialized nuclear medicine clinics.
Nuclear Medicines Radioisotopes Market Key Industry Players
United States producers anchor one tier, focusing on innovative production methods and advanced theranostics; European specialists hold another, emphasizing integrated supply chains. The market structure is moderately consolidated, with a few large players and several specialized firms. Strategic archetypes include integrated radiopharmaceutical providers, novel isotope producers, and imaging system manufacturers, each serving distinct market needs. Capacity expansion, particularly for next-generation isotopes, and strategic partnerships are dominant competitive moves.
Among global pharmaceutical and medical technology leaders, GE HealthCare exemplifies the integrated provider model, offering both advanced imaging systems and companion radiopharmaceuticals. Curium Pharma, a prominent European entity, occupies a position as a large-scale producer leveraging a global network of cyclotrons and reactors to ensure consistent supply. NorthStar Medical Radioisotopes, based in the United States, represents a specialized innovator, focusing on non-uranium-based technetium-99m production to address historical supply vulnerabilities. These companies collectively anchor different segments of the complex value chain.
| Leading Market Players |
|---|
| GE HealthCare |
| Cardinal Health |
| Siemens Healthineers |
| Curium Pharma |
| Lantheus Holdings |
| Novartis AG |
| NorthStar Medical Radioisotopes |
| Eckert & Ziegler |
| Bracco Imaging |
| Others |
Cost & Logistics Intelligence
Large hospital networks in the United States often secure comprehensive supply agreements, shifting procurement from per-dose transactions to bundled solutions. This concentration of buying power influences pricing for integrated radiopharmaceuticals, imaging systems, and data analytics software.
Pricing Analysis
Capacity additions in the United States and Europe are reshaping price floors for high-volume diagnostic isotopes. The market operates on a hybrid pricing model combining long-term contracts with transactional per-dose procurement, with price differentiation stemming from geographic delivery costs and stringent regulatory certification. Pricing softness for commodity isotopes reflects diversified production, while novel theranostics command premium pricing. Hospitals purchasing routine diagnostics exhibit higher price sensitivity compared to specialized oncology centers acquiring advanced therapeutic agents.
Supply Chain Analysis
Dual-sourcing requirements are becoming critical for ensuring consistent supply in the nuclear medicines radioisotopes market. Supply concentrates in the United States, Europe, and China, with production relying on Molybdenum-99 precursors for reactor-based isotopes and enriched water for cyclotron-produced Fluorine-18. Logistical complexity for short-lived isotopes, such as Technetium-99m, represents a significant structural risk. Distribution runs through a specialized network of radiopharmacies and dedicated transport, often directly to hospitals and diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nuclear medicines radioisotopes market presents a geographic-arbitrage play, leveraging differing regulatory approval pathways between the US FDA/EMA and China's NMPA. This allows for strategic market entry and production optimization based on regional regulatory stringency and market access.
For Market Incumbents: Extend existing supply chain control by investing in domestic production capabilities, particularly for next-generation alpha and beta-emitting isotopes. This defends against supply vulnerabilities from aging reactors and emerging non-uranium production methods. Securing long-term supply agreements for critical precursors and expanding R&D into neurological applications will diversify revenue streams. Consolidate market position through comprehensive supply agreements that bundle radiopharmaceuticals with imaging systems, countering fragmented transactional purchasing.
For New Entrants and Emerging Players: A price-point gap exists between high-premium novel theranostics and traditional diagnostic isotopes, creating an entry opportunity for specialized, cost-effective solutions. Target underpenetrated diagnostic imaging markets in regions like Latin America and Southeast Asia, where infrastructure investments are increasing. Develop novel radiotracers for neurological applications, a significant frontier beyond oncology and cardiology. A go-to-market angle involves strategic partnerships with local diagnostic centers and healthcare providers to ensure rapid distribution.
For Investors and Strategic Acquirers: Integrated healthcare technology providers are the most active acquirers in this space, seeking to consolidate offerings across imaging and therapeutics. The market demonstrates strong long-term viability over the next decade, driven by aging demographics and theranostic innovation. Target specialized radiopharmaceutical developers with robust pipelines in alpha-emitting isotopes or AI-enhanced diagnostic solutions. Regulatory approvals for next-generation alpha emitters, particularly Actinium-225, serve as a key signal for market inflection and accelerated growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Alpha Emitters | Addresses growing demand for targeted radionuclide therapy in advanced oncology centers. |
| AI Integration in Imaging | Enhances diagnostic accuracy and quantifies treatment response for existing radiopharmaceutical products. |
| Non-Uranium Production Investment | Secures national supply chains and reduces reliance on aging, government-owned nuclear facilities. |
| Geographic Market Entry in Asia | Capitalizes on expanding healthcare infrastructure and increasing diagnostic imaging in China and India. |
| Neurological Radiotracer Development | Unlocks new diagnostic and therapeutic applications for neurodegenerative diseases beyond oncology. |
Research Approach
Multiple input streams — primary interviews, extensive secondary research, and proprietary databases — were reconciled to build a robust market perspective. Industry stakeholders including nuclear pharmacists, radiochemists, medical physicists, and hospital procurement managers provided critical insights. Secondary validation utilized US FDA filings, EMA submissions, and company annual reports. A bottom-up and top-down triangulation approach ensured data accuracy and comprehensive market sizing.
Historical market performance was cross-referenced against expert panel input to construct the forecast framework across the analysis window. Segmentation dimensions modeled included radioisotope type, application, end user, production method, and regional regulatory frameworks. Compound annual growth rates were derived from projected demand, technological advancements, and evolving clinical practices. Incidence rates of cancer and cardiovascular diseases, alongside theranostic adoption rates, served as key industry-specific forecast inputs.
Caveats apply where regulatory changes, geopolitical disruptions affecting isotope supply, or unforeseen technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding current market dynamics and expected innovation trajectories. Deviation in supply chain stability or regulatory approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Anthelmintic Drugs Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Global Cytotoxic Drugs Market