
 Global Heparin Sodium Market | 2026-2036
Global Heparin Sodium Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heparin Sodium Market Foresight
Automated compounding and closed-system transfer devices are reshaping how heparin sodium is prepared and administered in clinical settings, reducing contamination risk and dosing variability. Pfizer Inc. leverages its integrated plasma supply network to sustain raw material security for unfractionated heparin production. Sanofi anchors its position through specialized low molecular weight heparin formulations with established hospital formularies. Baxter International Inc. competes in the dialysis application segment where heparin anticoagulation remains protocol-standard.
Heparin sodium is a sulfated glycosaminoglycan anticoagulant derived from porcine intestinal mucosa or bovine lung tissue, with a molecular weight range of 3,000 to 30,000 daltons for unfractionated forms and below 8,000 daltons for low molecular weight fractions. It accelerates antithrombin III-mediated inhibition of thrombin and factor Xa, serving as the primary parenteral anticoagulant for acute thromboembolic events and extracorporeal circulation procedures. Low molecular weight heparin commands the dominant value share due to its predictable pharmacokinetics and reduced monitoring burden, while synthetic heparin represents the fastest-developing category as manufacturers seek to eliminate animal-source dependency. Unfractionated heparin retains critical use in cardiovascular surgery and dialysis where rapid reversibility with protamine sulfate remains clinically essential.
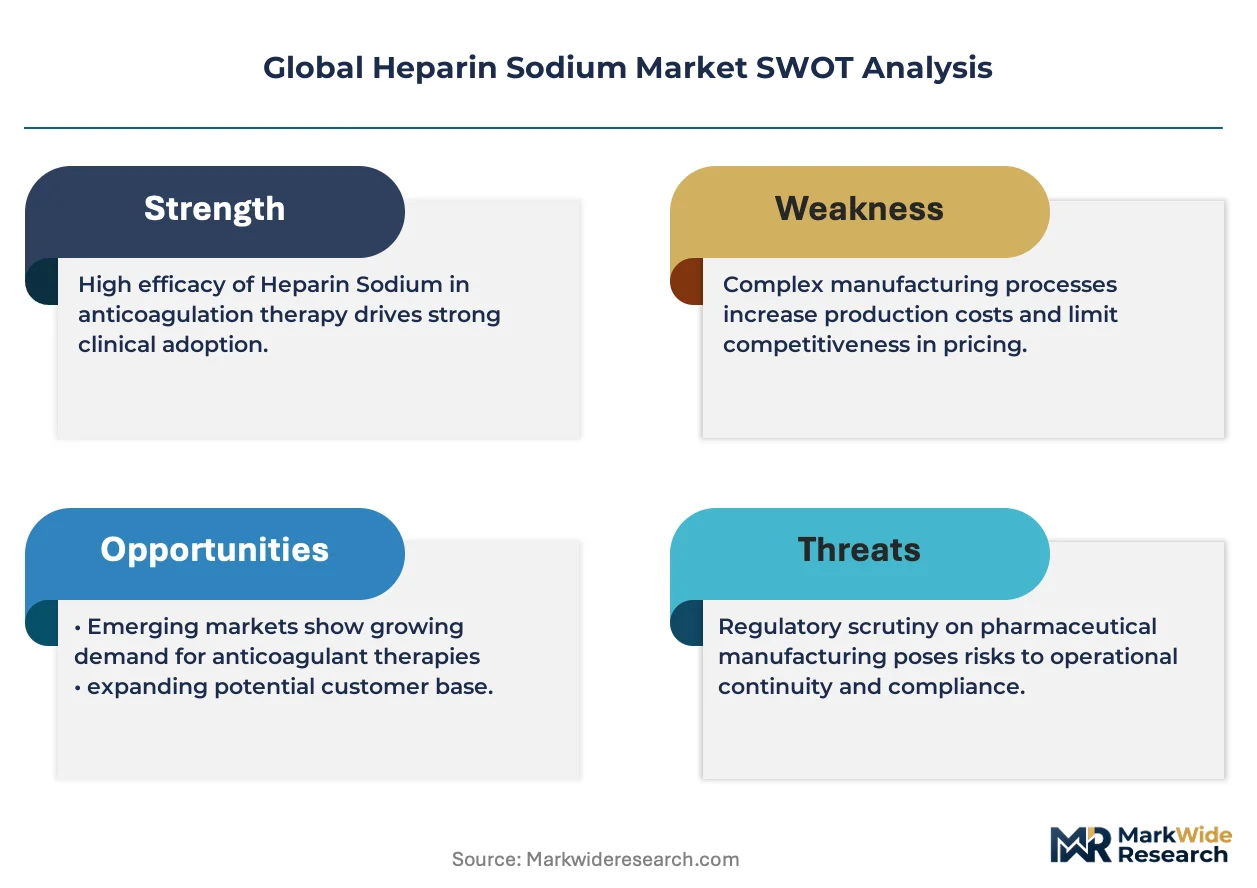
The FDA enforces Current Good Manufacturing Practice standards for heparin active pharmaceutical ingredients, while the EMA's pharmacovigilance framework mandates batch-level traceability and adverse event reporting across European supply chains. China's NMPA implements GB standards for heparin sodium purity and potency testing, creating divergent compliance pathways for multinational manufacturers. Stakeholders must monitor regulatory alignment between pharmacopeial standards as biosimilar competition and synthetic alternatives threaten to fragment pricing power in established heparin categories.
Market Dynamics
The FDA's pharmacovigilance mandates for anticoagulants are compressing manufacturing tolerances and forcing batch-level traceability investments across heparin supply chains. This regulatory pressure is reshaping competitive positioning toward integrated plasma processors capable of end-to-end documentation.
Growth Catalysts
- Dialysis infrastructure expansion:China's NMPA is accelerating dialysis center licensing in tier-2 cities, embedding heparin anticoagulation as protocol-standard for extracorporeal circuits.
- EMA pharmacovigilance framework:Batch-level adverse event reporting mandates are consolidating procurement toward suppliers with certified quality management systems.
- Closed-system transfer devices:Automated compounding technologies are reducing contamination risk in hospital pharmacy preparation, expanding addressable volume in acute care settings.
Market Restraints
- Porcine mucosa supply concentration:Over 80% of unfractionated heparin raw material originates from Chinese slaughterhouse processing, creating geopolitical and disease-outbreak exposure.
- Protamine sulfate reversibility requirement:Cardiovascular surgery protocols mandate rapid anticoagulation reversal, locking unfractionated heparin in place despite superior pharmacokinetics of low molecular weight alternatives.
- Synthetic heparin substitution trajectory:Chemoenzymatic production methods threaten to displace animal-derived supply chains once manufacturing scale economics mature.
Strategic Opportunities
- Underpenetrated Indian dialysis market:CDSCO regulatory harmonization with ICH guidelines is enabling multinational heparin suppliers to enter previously fragmented procurement environments.
- Home anticoagulation administration:Subcutaneous low molecular weight heparin formulations are displacing hospital-based infusion for deep vein thrombosis prophylaxis in post-surgical recovery.
- ISO 13485 quality certification:Medical device-grade heparin coating applications for catheters and stents are opening premium pricing tiers beyond pharmaceutical anticoagulation.
Industry Challenges
- Analytical biochemistry talent scarcity:Heparin molecular weight distribution testing requires specialized chromatography expertise that competes with broader biopharmaceutical quality control hiring pools.
- Legacy ERP integration with track-and-trace systems:Batch serialization mandates are forcing mid-tier manufacturers to reconfigure inventory management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heparin Sodium Market |
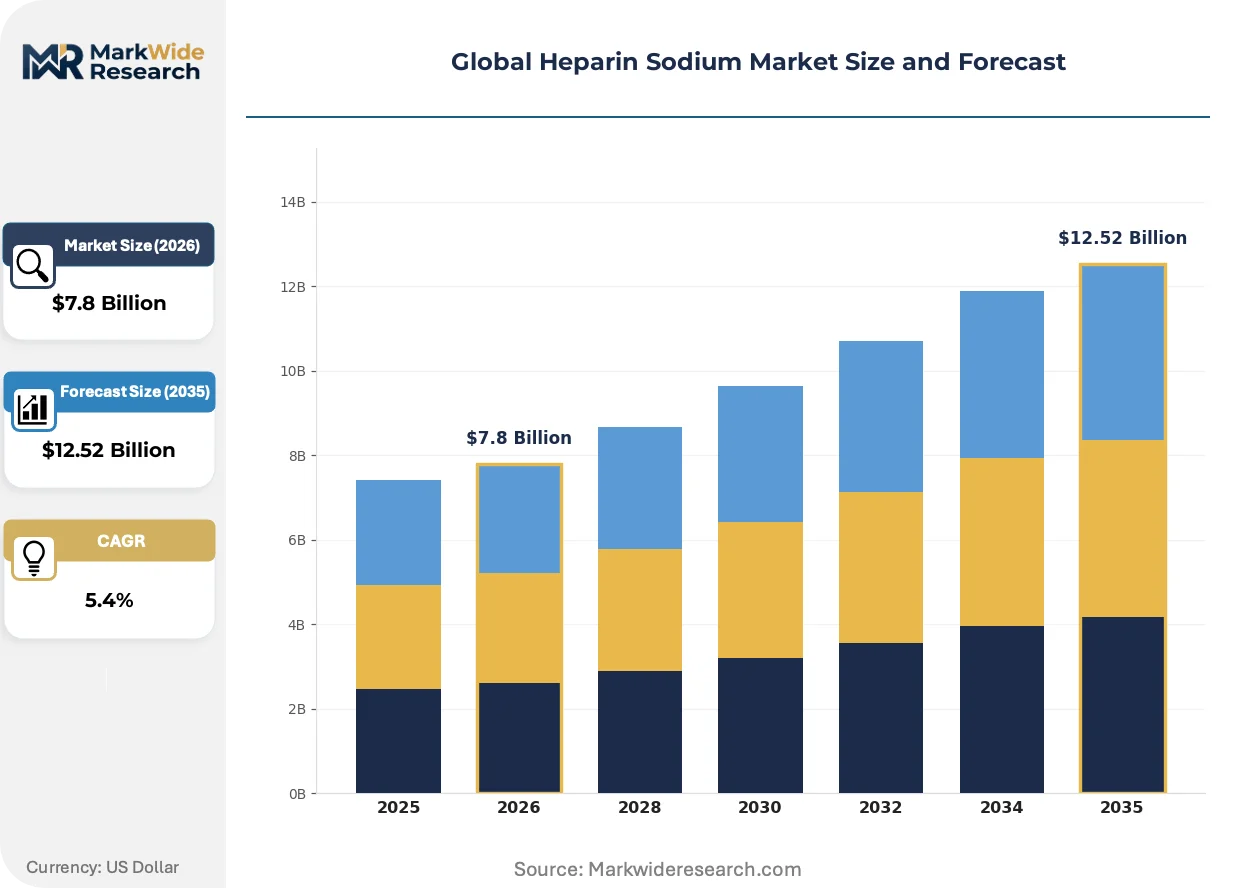
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfractionated Heparin, Low Molecular Weight Heparin, Ultra-LMW Heparin, Synthetic Heparin Application: Anticoagulation Therapy, Cardiovascular Surgery, Dialysis, Deep Vein Thrombosis Prevention End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Research Institutes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Medical Distributors |
| Companies Covered | Pfizer Inc., Sanofi, Baxter International Inc., B. Braun Medical Inc., Dr. Reddy’s Laboratories Ltd., LEO Pharma A/S, Fresenius SE & Co. KGaA, Aspen Holdings, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heparin Sodium Market Shifts & Advancements
Synthetic biology and automated manufacturing are collapsing traditional boundaries between animal-derived and engineered anticoagulant production. These shifts are compressing development timelines and redrawing supplier qualification criteria.
Ultra-low molecular weight heparin analogs produced through chemoenzymatic synthesis are collapsing the historical cost gap between porcine-derived and fully synthetic anticoagulants. Pfizer and Sanofi are scaling pilot facilities in Germany and France to validate commercial viability. This technology is collapsing raw material security risks that have constrained pharmaceutical procurement strategies for decades.
REACH registration requirements for heparin sodium as a substance of very high concern are forcing European manufacturers to submit full toxicological dossiers for import authorization. The ECHA's 2024 updated guidance on glycosaminoglycan derivatives is extending compliance timelines by 18-24 months for non-EU suppliers. Low molecular weight heparin importers into Germany and the Netherlands are absorbing these costs through dedicated regulatory affairs staffing.
Hospital pharmacy consolidation into centralized compounding services is compressing heparin sodium supplier rosters toward those with validated aseptic manufacturing partnerships. IDN procurement committees in the United States are mandating single-source contracts for anticoagulant categories to simplify formulary management. This concentration is most visible in cardiovascular surgical networks across Texas and Florida where case volumes justify dedicated supply agreements.
Global Heparin Sodium Market Segmentation
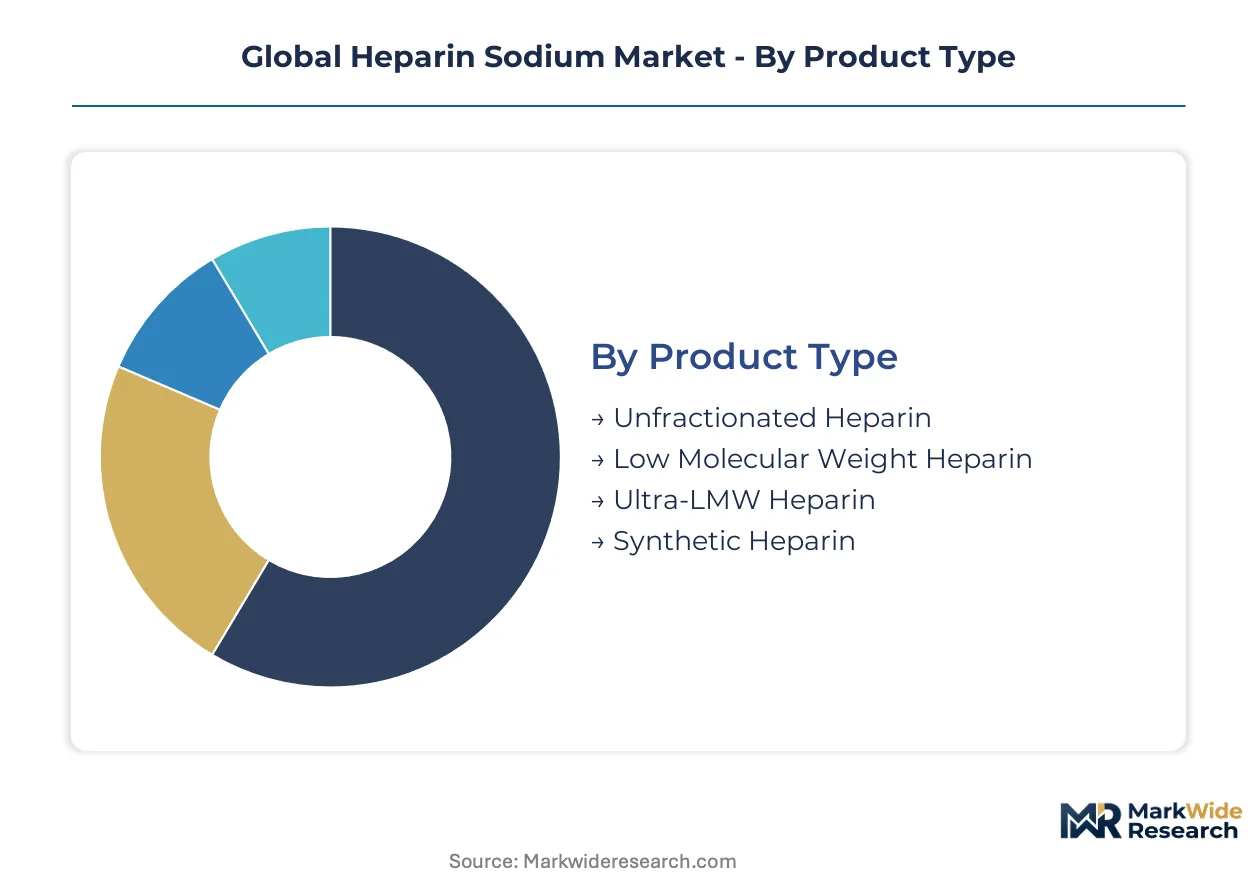
Heparin sodium segmentation reveals distinct value pools tied to molecular weight pharmacokinetics and clinical setting requirements. Product chemistry, application protocol, and procurement channel each reshape margin structures and supplier qualification barriers across supply chains.
Product Type:
Cost tier differentiation separates animal-derived extraction from synthetic manufacturing pathways, with molecular weight fractionation determining monitoring burden and pricing power.
- Low Molecular Weight Heparin:Enoxaparin and dalteparin dominate hospital formularies with predictable subcutaneous bioavailability eliminating activated partial thromboplastin time monitoring. Demand concentrates in post-surgical prophylaxis across United States and Germany where reduced nursing labor offsets higher unit costs.
- Unfractionated Heparin:Porcine intestinal mucosa extraction yields polydisperse chains of 3,000-30,000 daltons requiring continuous infusion and laboratory monitoring. Cardiovascular surgery protocols in China and dialysis circuits worldwide lock in volume despite synthetic substitution threats.
- Ultra-LMW Heparin:Fondaparinux and related pentasaccharides offer factor Xa selectivity with minimal platelet interaction.
- Synthetic Heparin:Chemoenzymatic production eliminates animal-source dependency and batch-to-batch variability.
Low molecular weight heparin commands the established base. The steepest expansion runs through synthetic heparin.
Application:
Clinical protocol specificity determines heparin selection, with reversibility requirements and circuit dwell times driving molecular weight preferences.
- Cardiovascular Surgery:Cardiopulmonary bypass mandates unfractionated heparin for immediate anticoagulation onset and complete protamine sulfate reversal. United States surgical networks in Texas and Florida consolidate procurement through single-source IDN contracts.
- Dialysis:Extracorporeal circuit anticoagulation requires continuous heparin infusion to prevent clotting while preserving patient hemostasis. China's NMPA-licensed dialysis centers in tier-2 cities embed heparin as protocol-standard.
- Deep Vein Thrombosis Prevention:Post-operative prophylaxis favors subcutaneous low molecular weight heparin for outpatient administration.
- Anticoagulation Therapy:Acute thromboembolic events require parenteral bridging until oral anticoagulation achieves therapeutic levels.
Cardiovascular surgery anchors premium pricing. Dialysis infrastructure expansion is gaining share fastest.
End User:
Customer type segmentation tracks care setting consolidation and regulatory oversight intensity.
- Hospitals:Centralized pharmacy compounding services and closed-system transfer devices dominate acute care anticoagulation. United States IDN formulary committees in cardiovascular networks mandate validated aseptic manufacturing partnerships.
- Specialty Clinics:Anticoagulation clinics manage outpatient bridging therapy and warfarin transitions.
- Diagnostic Laboratories:Coagulation testing facilities require heparin for quality control and assay calibration.
- Research Institutes:Cell culture and chromatography applications consume pharmaceutical-grade heparin for experimental protocols.
Hospitals command volume concentration. Specialty clinics are expanding most quickly.
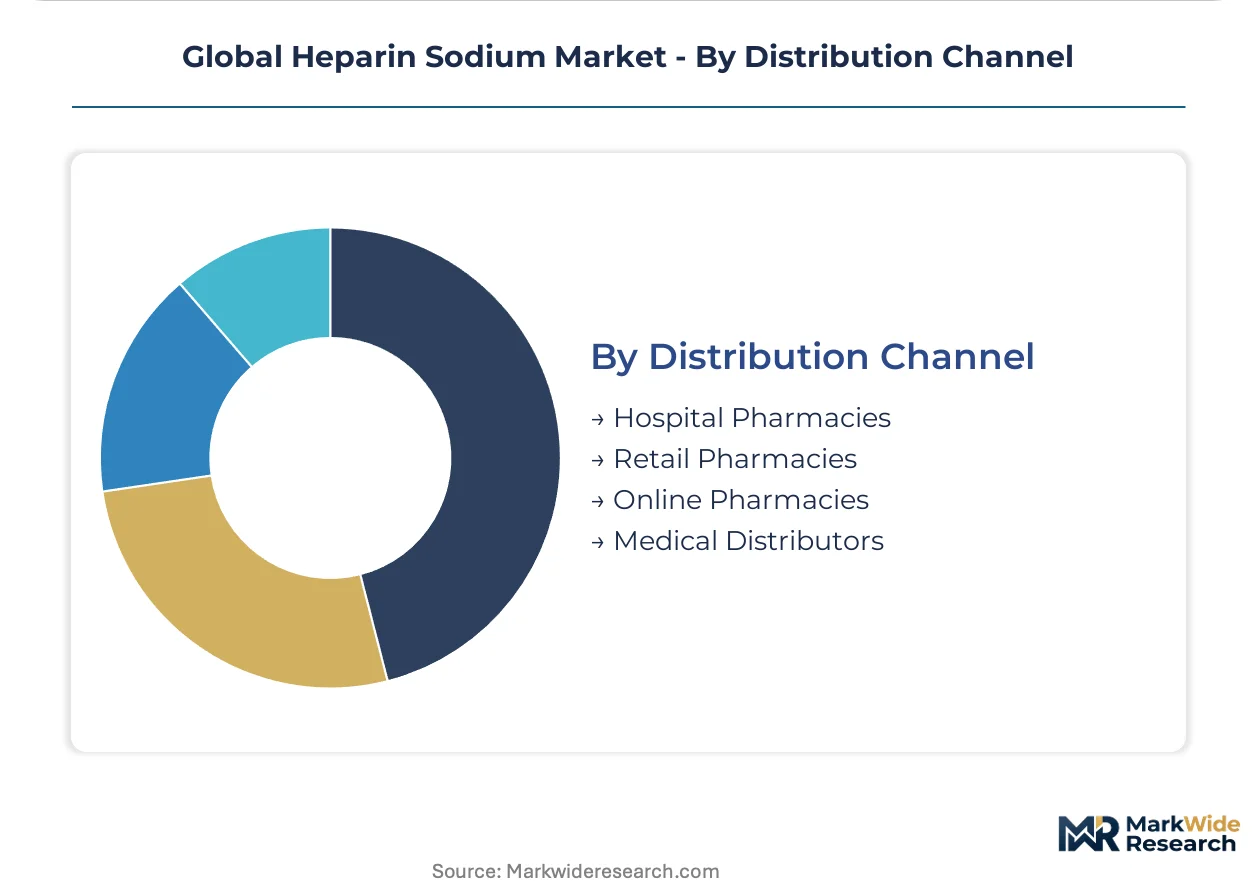
Distribution Channel:
Supply chain configuration determines cold chain requirements, batch traceability investment, and margin capture.
- Hospital Pharmacies:Direct contracting with integrated plasma processors ensures end-to-end documentation for FDA pharmacovigilance mandates. Automated compounding partnerships in United States academic medical centers reduce contamination risk.
- Medical Distributors:Regional wholesalers service specialty clinics and smaller hospitals with inventory management and just-in-time delivery.
- Retail Pharmacies:Outpatient low molecular weight heparin prescriptions for home administration.
- Online Pharmacies:Direct-to-patient delivery of maintenance anticoagulation supplies.
Hospital pharmacies anchor procurement consolidation. Medical distributors are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and China concentrate demand for heparin sodium through single-source contracts and protocol-standard anticoagulation regimens. Dialysis infrastructure expansion and cardiovascular surgical networks drive volume concentration in these three markets. Regulatory divergence between FDA pharmacovigilance mandates, EMA batch-traceability requirements, and NMPA GB standards fragments compliance pathways for multinational suppliers.
United States
Integrated delivery networks in Texas and Florida consolidate heparin procurement through dedicated supply agreements tied to cardiovascular surgical volumes. FDA pharmacovigilance mandates for anticoagulants enforce batch-level traceability and Current Good Manufacturing Practice standards across heparin active pharmaceutical ingredients. Academic medical centers in Boston and Houston deploy automated compounding partnerships to reduce contamination risk in hospital pharmacy preparation.
Germany
Fresenius SE & Co. KGaA anchors dialysis application demand through protocol-standard extracorporeal circuit anticoagulation in licensed treatment centers. EMA pharmacovigilance framework mandates adverse event reporting and certified quality management systems for heparin suppliers accessing European supply chains. REACH registration requirements for glycosaminoglycan derivatives extend compliance timelines for non-EU manufacturers importing into German ports.
China
NMPA-licensed dialysis centers in tier-2 cities embed unfractionated heparin as protocol-standard for extracorporeal circuits, driving infrastructure-linked demand expansion. GB standards for heparin sodium purity and potency testing create divergent compliance pathways distinct from FDA and EMA requirements. Zhejiang and Shandong provinces concentrate porcine mucosa processing operations supplying over 80 percent of global unfractionated heparin raw material.
India
CDSCO regulatory harmonization with ICH guidelines enables multinational heparin suppliers to enter previously fragmented procurement environments in underpenetrated dialysis markets. The country's national pharmaceutical regulator accelerates import authorization timelines for low molecular weight heparin formulations. Maharashtra and Gujarat host expanding pharmaceutical manufacturing clusters where domestic producers compete with imported anticoagulant supply.
Japan
PMDA oversight of parenteral anticoagulants maintains stringent batch-release requirements for heparin sodium used in cardiovascular surgery and dialysis applications. METI industrial policy supports domestic pharmaceutical manufacturing capacity for critical medical supplies including anticoagulants. The Kanto region around Tokyo concentrates hospital procurement decision-making for national cardiovascular surgical networks.
Global Heparin Sodium Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating toward integrated plasma processors capable of end-to-end documentation. Hospital pharmacy and IDN procurement committees compress supplier rosters through single-source contracting and validated aseptic manufacturing partnerships. Three archetypes dominate: integrated pharmaceutical conglomerates with captive plasma supply networks, specialized anticoagulant manufacturers with established hospital formularies, and dialysis-focused suppliers with protocol-standard positioning. Competitive moves center on regulatory compliance infrastructure investment and synthetic heparin pilot facility scaling to eliminate animal-source dependency.
Among integrated pharmaceutical conglomerates, Pfizer Inc. and Sanofi occupy positions exemplifying the plasma-network and formulation-specialist archetypes respectively. Baxter International Inc. represents the dialysis-application focus within this competitive set. These three companies anchor the market structure through distinct supply chain configurations: Pfizer through integrated raw material security, Sanofi through low molecular weight heparin formulation dominance, and Baxter through extracorporeal circuit protocol standardization. Mid-tier manufacturers including Dr. Reddy's Laboratories Ltd. and LEO Pharma A/S sit within specialized anticoagulant tiers competing on regulatory compliance speed and regional market access rather than vertical integration depth.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi |
| Baxter International Inc. |
| B. Braun Medical Inc. |
| Dr. Reddy's Laboratories Ltd. |
| LEO Pharma A/S |
| Fresenius SE & Co. KGaA |
| Aspen Holdings |
| GlaxoSmithKline plc |
| Others |
Supply & Pricing Matrix
Zhejiang and Shandong provinces concentrate over 80 percent of global porcine mucosa processing, anchoring raw material costs and feeding margin compression downstream as synthetic alternatives mature. This upstream geography locks pharmaceutical manufacturers into long-term offtake contracts with Chinese slaughterhouse processors while hospital IDNs extract volume discounts through consolidated procurement.
Pricing Analysis
Cost-plus contracts with porcine mucosa indexation dominate unfractionated heparin procurement, with pharmaceutical-grade certifications and FDA batch-release status driving premium-mid-economy pricing differentiation. Synthetic heparin pilot batches command standard-tier spreads until manufacturing scale economics mature. Pricing pressure stems from chemoenzymatic substitution threats as Pfizer and Sanofi validate commercial viability. Dialysis clinics in China exhibit highest price sensitivity; cardiovascular surgical networks in Texas and Florida absorb premiums for protamine sulfate reversibility.
Supply Chain Analysis
Export-control regimes for glycosaminoglycan derivatives under REACH registration requirements constrain non-EU supplier flows into German and Dutch ports. Raw material extraction draws from Chinese porcine processing, German chemoenzymatic pilot facilities, and Indian pharmaceutical manufacturing clusters. Single-source vulnerability concentrates in Zhejiang slaughterhouse networks. Distribution runs through hospital pharmacy direct contracting with integrated plasma processors for end-to-end FDA pharmacovigilance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic heparin substitution represents an existential threat that incumbent animal-derived suppliers must navigate through manufacturing scale investment and regulatory compliance differentiation.
For Market Incumbents: Insulate market position by accelerating backward integration into porcine mucosa processing operations in Shandong province and securing ISO 13485 certification for medical device-grade heparin coatings. Synthetic chemoenzymatic alternatives threaten core revenue streams; captive raw material supply and premium coating applications defend margin pools against commoditization. For New Entrants and Emerging Players: India's underpenetrated dialysis markets offer white-space expansion as CDSCO regulatory harmonization with ICH guidelines reduces import authorization barriers. Target Maharashtra and Gujarat pharmaceutical manufacturing clusters with low molecular weight heparin formulations for outpatient anticoagulation clinics. Partner with regional medical distributors for just-in-time delivery infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward integrated plasma processors with validated aseptic manufacturing partnerships and end-to-end batch traceability systems. Long-term viability hinges on synthetic heparin manufacturing scale economics maturing across the analysis window. Monitor EMA pharmacovigilance framework expansion for adverse event reporting mandates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Heparin Scale-Up | Pfizer and Sanofi pilot facilities in Germany and France validate chemoenzymatic production eliminating animal-source dependency. |
| Regulatory Compliance Investment | FDA pharmacovigilance mandates for batch-level traceability consolidate procurement toward certified quality management systems. |
| Dialysis Infrastructure Partnership | Fresenius SE & Co. KGaA protocol-standard positioning in licensed treatment centers locks in extracorporeal circuit anticoagulation volume. |
| Medical Device Certification | ISO 13485 quality certification opens premium pricing tiers for catheter and stent coating applications beyond pharmaceutical anticoagulation. |
| Centralized Compounding Alliance | Academic medical centers in Boston and Houston deploy automated partnerships reducing contamination risk in hospital pharmacy preparation. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, regulatory affairs leads, dialysis clinic directors, and pharmaceutical manufacturing executives and refined through secondary validation. FDA 483 inspection observations, EMA pharmacovigilance databases, NMPA GB standard filings, and hospital formulary databases anchored quantitative triangulation. Bottom-up patient-volume modeling and top-down pharmaceutical revenue reconciliation cross-verified segment sizing.
Demand-supply-balance framing across the analysis window integrated cardiovascular surgical procedure volumes, dialysis center licensing trajectories, and synthetic heparin manufacturing capacity buildouts. Segmentation dimensions spanned molecular weight pharmacokinetics, clinical protocol requirements, and regional regulatory clusters. CAGRs derived from procedure growth elasticities and pricing trajectory assumptions calibrated against porcine mucosa supply constraints and substitution adoption curves.
Practitioners should monitor synthetic heparin pilot facility output rates and REACH registration compliance timelines for non-EU suppliers as early signals. Forecasts reflect assumptions around chemoenzymatic manufacturing scale economics and dialysis infrastructure expansion trajectories. Material shifts in porcine mucosa supply disruption or EMA pharmacovigilance framework stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Advanced Parenteral Drug Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market