
 Europe Heparin Market | 2026-2036
Europe Heparin Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Heparin Market Foresight
CE marking under the EU Medical Device Regulation is unwinding access for heparin device and combination product manufacturers that lack notified body certifications. Fresenius Kabi AG leverages its parenteral manufacturing infrastructure to sustain supply continuity across German and Austrian hospital networks. Sanofi dominates the Low Molecular Weight Heparin segment through decades of enoxaparin brand strength and direct distribution to European pharmacy chains.
Heparin denotes a family of sulfated glycosaminoglycan anticoagulants derived from porcine intestinal mucosa or bovine lung tissue, with unfractionated forms averaging molecular weights of 15,000 daltons and functioning primarily through antithrombin III-mediated inhibition of thrombin and Factor Xa. Low Molecular Weight Heparin variants, produced through controlled enzymatic or chemical depolymerization, command the largest revenue pool due to predictable pharmacokinetics and reduced monitoring requirements in orthopedic surgery prophylaxis. Injectable delivery modes retain structural dominance in hospital settings, while subcutaneous formulations are gaining traction in home care transitions post-discharge.
The European Medicines Agency enforces stringent batch release protocols for heparin APIs through its Official Medicines Control Laboratories network, while REACH and the EU Green Deal drive scrutiny of porcine sourcing sustainability and supply chain traceability. National regulators including Germany's Paul-Ehrlich-Institut and France's ANSM maintain supplementary inspection regimes that shape market access timelines for new entrants. Stakeholders must monitor evolving EMA guidance on nitrosamine impurity thresholds and heparin-derived biosimilar interchangeability criteria to anticipate competitive repositioning.
Market Dynamics
Hospital procurement centralization across German, French, and British acute care networks is compressing supplier margins while amplifying volume concentration effects for heparin manufacturers. This purchasing consolidation is the dominant structural force reshaping competitive positioning in European anticoagulant supply.
Growth Catalysts
- Rising orthopedic surgery volumes:Knee and hip replacement procedures in Germany and France are expanding prophylactic heparin utilization across university hospital networks.
- EU Medical Device Regulation compliance deadlines:MDR transition timelines are accelerating notified body certifications for combination device manufacturers, filtering out marginal competitors.
- Home care transition protocols:Post-discharge subcutaneous administration pathways in the United Kingdom are extending therapy duration beyond hospital stays.
Market Restraints
- Porcine mucosa supply concentration:Over 80% of active pharmaceutical ingredient sourcing depends on Spanish and Dutch slaughterhouse byproduct streams, creating geographic vulnerability.
- REACH sustainability audits:ECHA documentation requirements for animal-derived raw materials are extending qualification timelines for new suppliers by 12-18 months.
- Synthetic anticoagulant substitution:Direct oral anticoagulants from Bayer and Bristol Myers Squibb are capturing venous thromboembolism prophylaxis share in French outpatient settings.
Strategic Opportunities
- Poland and Czech Republic hospital modernization:EU cohesion fund investments are upgrading surgical capacity in Warsaw and Prague, creating new high-volume accounts.
- Biosimilar interchangeability frameworks:EMA guidance on heparin-derived biosimilar substitution criteria will enable pharmacy-level switching protocols.
- Prefilled syringe device convergence:Integration of safety-engineered needle systems with LMWH formulations is opening premium positioning in Scandinavian markets.
Industry Challenges
- Analytical chemistry talent scarcity:Nitrosamine impurity testing and molecular weight distribution validation require specialized chromatography expertise that outpaces European university output.
- Legacy batch record system integration:German and Austrian manufacturers face friction connecting paper-based quality systems to EMA-mandated electronic data submission portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Heparin Market |
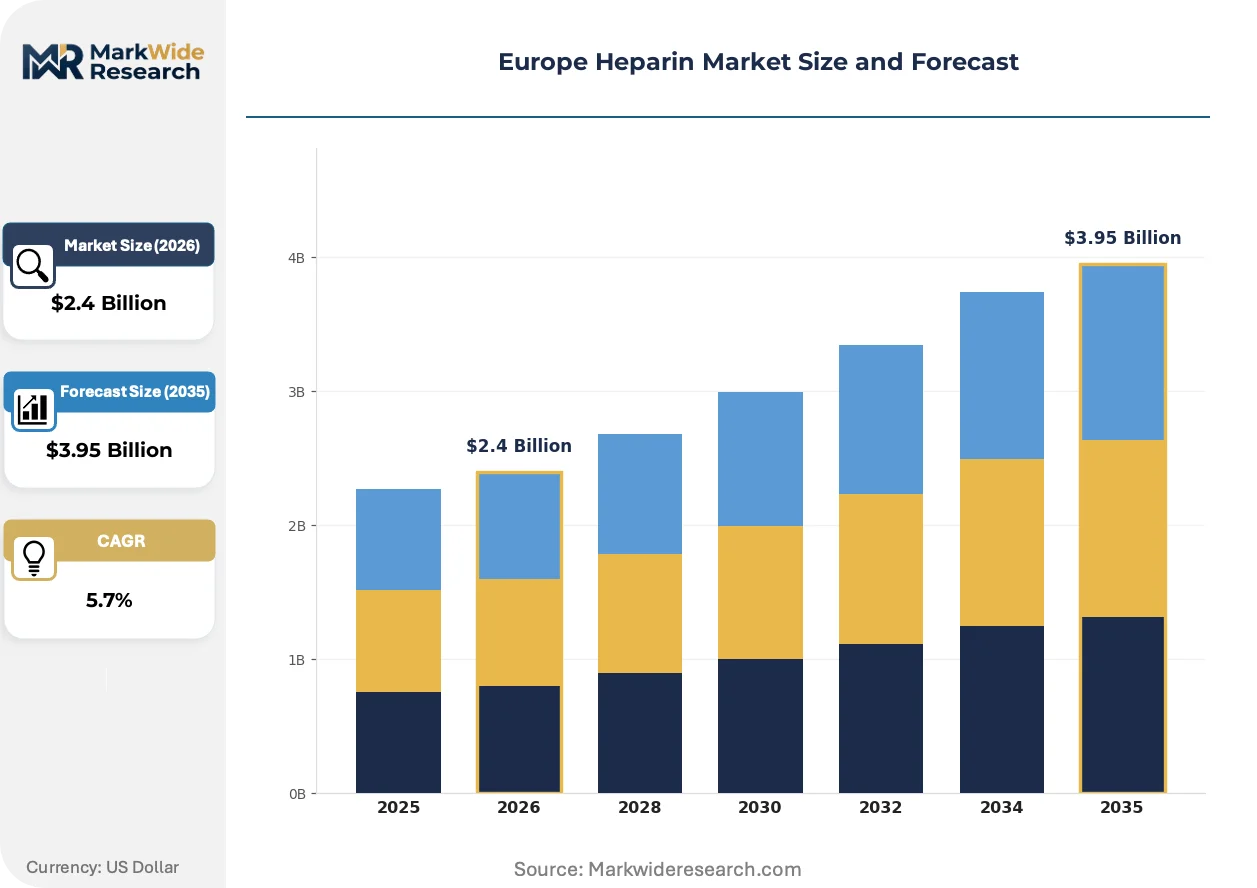
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfractionated Heparin, Low Molecular Weight Heparin, Biosimilar Heparin, Others Therapy Area: Cardiovascular Disorders, Orthopedic Surgery, Pulmonary Diseases, Others Delivery Mode: Injectable, Intravenous, Subcutaneous, Others End User: Hospitals, Clinics, Specialty Pharmacies, Home Care |
| Companies Covered | B. Braun Melsungen AG, Novartis AG, Fresenius Kabi AG, Pfizer Inc., GlaxoSmithKline plc., Sanofi, LEO Pharma A/S, OPOCRIN S.P.A., F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Heparin Market Shifts & Advancements
European heparin manufacturing is undergoing a dual transformation: process analytical technology is displacing offline quality testing, while sustainability traceability is becoming a procurement gate. These shifts are compressing legacy operational models.
Continuous manufacturing platforms for heparin sodium API production are bifurcating the supplier base. Fresenius Kabi and specialized CMOs in Germany are installing real-time release testing equipment that eliminates traditional batch quarantine periods. This technology is compressing working capital requirements for adopters while marginalizing facilities dependent on end-point testing protocols.
EMA's tightened nitrosamine impurity thresholds under its 2023-2025 guidance program are forcing reformulation investments across the supply chain. Manufacturers must deploy high-sensitivity mass spectrometry for N-nitrosodimethylamine detection in heparin salts. Low molecular weight heparin producers with legacy depolymerization chemistries face the steepest compliance costs, particularly in Italy and Spain where facility ages exceed 25 years.
Centralized tendering through hospital purchasing cooperatives is consolidating account access across France and the United Kingdom. University Hospital Southampton and Assistance Publique-Hôpitaux de Paris are migrating to multi-year framework agreements that bundle unfractionated and low molecular weight heparin volumes. This procurement compression is eliminating spot-market sales channels and favoring manufacturers with dedicated key account management teams in London and Paris.
Europe Heparin Market Segmentation
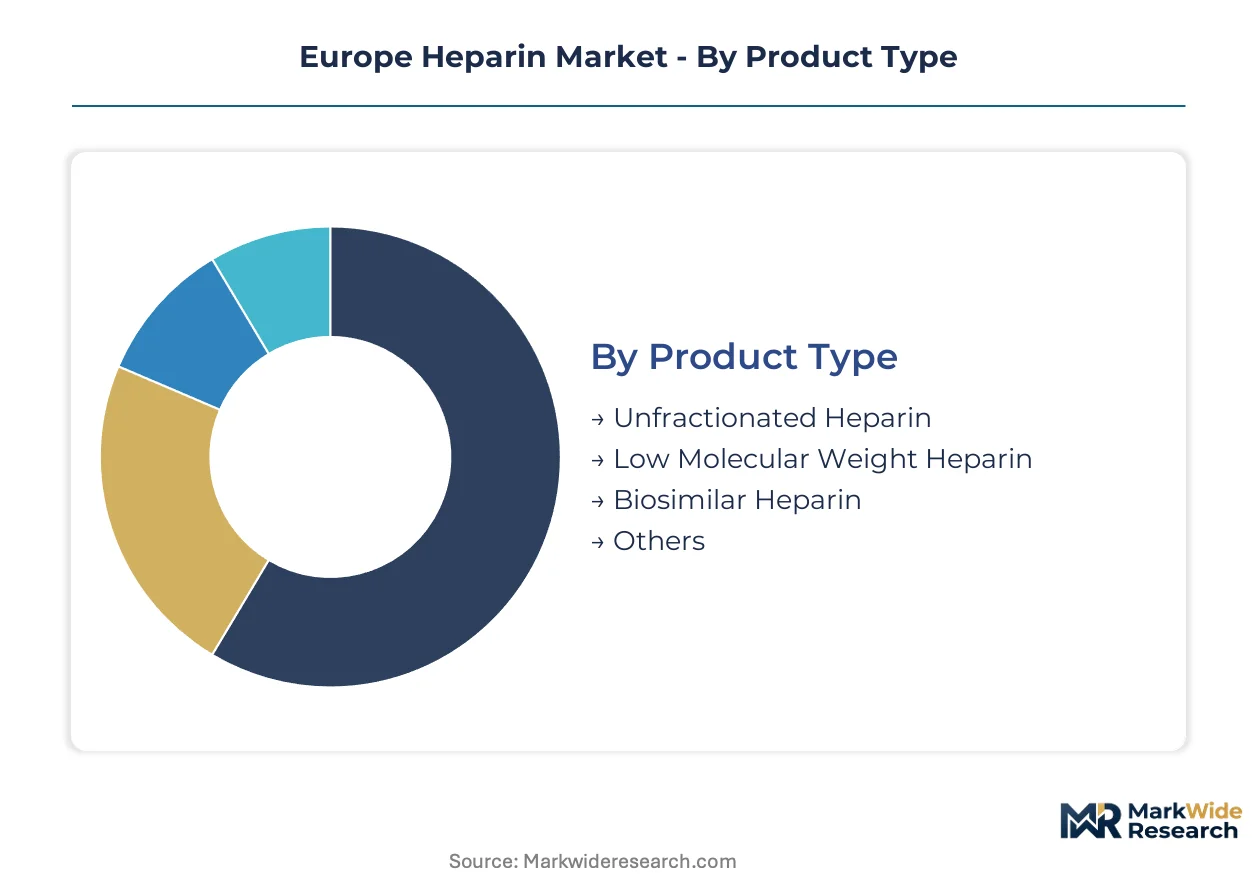
Heparin procurement patterns diverge sharply across product chemistry, clinical setting, and delivery mechanism. Understanding these fault lines reveals where pricing power concentrates and which segments face substitution pressure from novel anticoagulants.
Product Type:
Margin pools concentrate in molecularly standardized formulations that reduce monitoring burden and hospital pharmacy labor costs.
- Low Molecular Weight Heparin:Controlled enzymatic depolymerization yields predictable pharmacokinetics with reduced bleeding risk profiles. German and French university hospitals are expanding prophylactic protocols for knee and hip replacement patients, driving volume concentration in orthopedic surgery networks.
- Unfractionated Heparin:Sulfated glycosaminoglycan chains averaging 15,000 daltons require activated partial thromboplastin time monitoring but retain dominance in acute coronary syndrome management and cardiac catheterization laboratories across British NHS trusts.
- Biosimilar Heparin:EMA interchangeability guidance is enabling pharmacy-level substitution in Scandinavian markets with mature generic frameworks.
- Others:Ultra-low molecular weight variants and chemically modified heparinoids serve niche indications in specialized thrombosis centers.
The dominant share belongs to Low Molecular Weight Heparin, while Biosimilar Heparin is closing the gap fastest as tendering authorities accelerate substitution protocols.
Therapy Area:
Procedure volume trajectories and reimbursement intensity determine where manufacturers allocate medical affairs resources.
- Orthopedic Surgery:Knee and hip arthroplasty volumes in Germany and France generate sustained prophylactic demand with standardized dosing protocols that favor formulary consolidation.
- Cardiovascular Disorders:Acute myocardial infarction and unstable angina management in British and Italian catheterization laboratories preserves unfractionated heparin utilization despite direct oral anticoagulant encroachment in outpatient settings.
- Pulmonary Diseases:Pulmonary embolism treatment in emergency departments maintains parenteral anticoagulation bridges before oral agent initiation.
- Others:Cancer-associated thrombosis and obstetric indications require specialized dosing algorithms with limited standardization.
Orthopedic Surgery commands the largest volume commitment, though Cardiovascular Disorders retains the steepest expansion trajectory as acute care networks expand interventional capacity.
Delivery Mode:
Administration setting transitions are reshaping device requirements and supply chain configurations.
- Injectable:Prefilled syringe formats with safety-engineered needle systems dominate hospital formulary approvals across German and Austrian procurement cooperatives.
- Subcutaneous:Post-discharge administration protocols in United Kingdom home care programs are extending therapy duration beyond index hospitalization.
- Intravenous:Continuous infusion pumps in intensive care units require pharmacy-compounded solutions with real-time titration protocols.
- Others:Topical and inhaled formulations remain experimental with limited commercial traction.
Injectable formats retain the dominant position, while Subcutaneous delivery is gaining share fastest as early discharge protocols proliferate.
End User:
Purchasing centralization intensity varies dramatically across care settings, fragmenting go-to-market requirements.
- Hospitals:Multi-year framework agreements through French Assistance Publique-Hôpitaux de Paris and British NHS Supply Chain are bundling unfractionated and low molecular weight volumes into single-source contracts.
- Home Care:United Kingdom district nursing services and German Hausarzt networks are building subcutaneous administration capabilities for extended prophylaxis.
- Specialty Pharmacies:Outpatient anticoagulation clinics in the Netherlands and Belgium manage therapy transitions with patient education programs.
- Clinics:Ambulatory surgical centers in Poland and Czech Republic are upgrading thromboprophylaxis protocols with EU cohesion fund support.
Hospitals control the dominant procurement volume, while Home Care is expanding most quickly as reimbursement shifts toward post-acute settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU cohesion fund allocations for hospital modernization are redirecting procurement volumes toward Central European surgical networks while CE marking deadlines under the EU Medical Device Regulation filter device-capable suppliers from marginal competitors.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia are expanding knee and hip arthroplasty volumes, driving prophylactic Low Molecular Weight Heparin consumption. The Paul-Ehrlich-Institut enforces supplementary batch inspection regimes that extend market access timelines for new API suppliers. Fresenius Kabi AG leverages parenteral manufacturing infrastructure in Hessen to sustain supply continuity across German and Austrian procurement cooperatives.
France
Assistance Publique-Hôpitaux de Paris operates centralized tendering that bundles unfractionated and Low Molecular Weight Heparin volumes into multi-year framework agreements. ANSM maintains inspection protocols for nitrosamine impurity detection that shape qualification requirements for Spanish-sourced porcine mucosa APIs. The Île-de-France region concentrates cardiovascular procedure volumes that preserve unfractionated heparin utilization in acute coronary syndrome management.
United Kingdom
NHS Supply Chain migration toward single-source contracts is eliminating spot-market sales channels for heparin formulations. Early discharge protocols in University Hospital Southampton networks extend subcutaneous administration into district nursing services post-discharge. The Medicines and Healthcare products Regulatory Agency aligns with EMA guidance on heparin-derived biosimilar interchangeability criteria.
Poland
Warsaw hospital modernization funded through EU cohesion investments is upgrading orthopedic surgical capacity and thromboprophylaxis protocols. The Office for Registration of Medicinal Products aligns nitrosamine testing requirements with EMA 2023-2025 guidance programs. Regional procurement cooperatives in Mazovia are consolidating account access for manufacturers with dedicated Warsaw-based key account management.
Italy
Agenzia Italiana del Farmaco enforces EMA-mandated electronic data submission requirements that create friction for facilities with legacy paper-based batch record systems. Lombardy and Emilia-Romagna host Low Molecular Weight Heparin production facilities exceeding 25 years of operational age, facing steep compliance costs for reformulation investments. The Italian Medicines Agency coordinates with EMA Official Medicines Control Laboratories for API batch release protocols.
Europe Heparin Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with parenteral manufacturing infrastructure and specialized anticoagulant portfolios. Tiered concentration prevails with a dominant Low Molecular Weight Heparin franchise holder, mid-scale hospital supply specialists, and API-sourcing generic manufacturers competing on tender price. Strategic archetypes include vertically integrated parenteral drug manufacturers, regional hospital supply contractors, and porcine-derived API specialists with European slaughterhouse sourcing relationships. Competitive moves concentrate on notified body certification acceleration for combination devices and real-time release testing equipment installation to compress working capital cycles.
Among German-integrated parenteral manufacturers, Fresenius Kabi AG occupies a position exemplifying supply continuity focus across hospital networks. Sanofi sits within the branded anticoagulant tier, representing decades of enoxaparin franchise strength through direct pharmacy chain distribution. B. Braun Melsungen AG anchors the device-integrated delivery segment, exemplifying safety-engineered needle system convergence with prefilled syringe formats.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Novartis AG |
| Fresenius Kabi AG |
| Pfizer Inc. |
| GlaxoSmithKline plc. |
| Sanofi |
| LEO Pharma A/S |
| OPOCRIN S.P.A. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Supply & Pricing Matrix
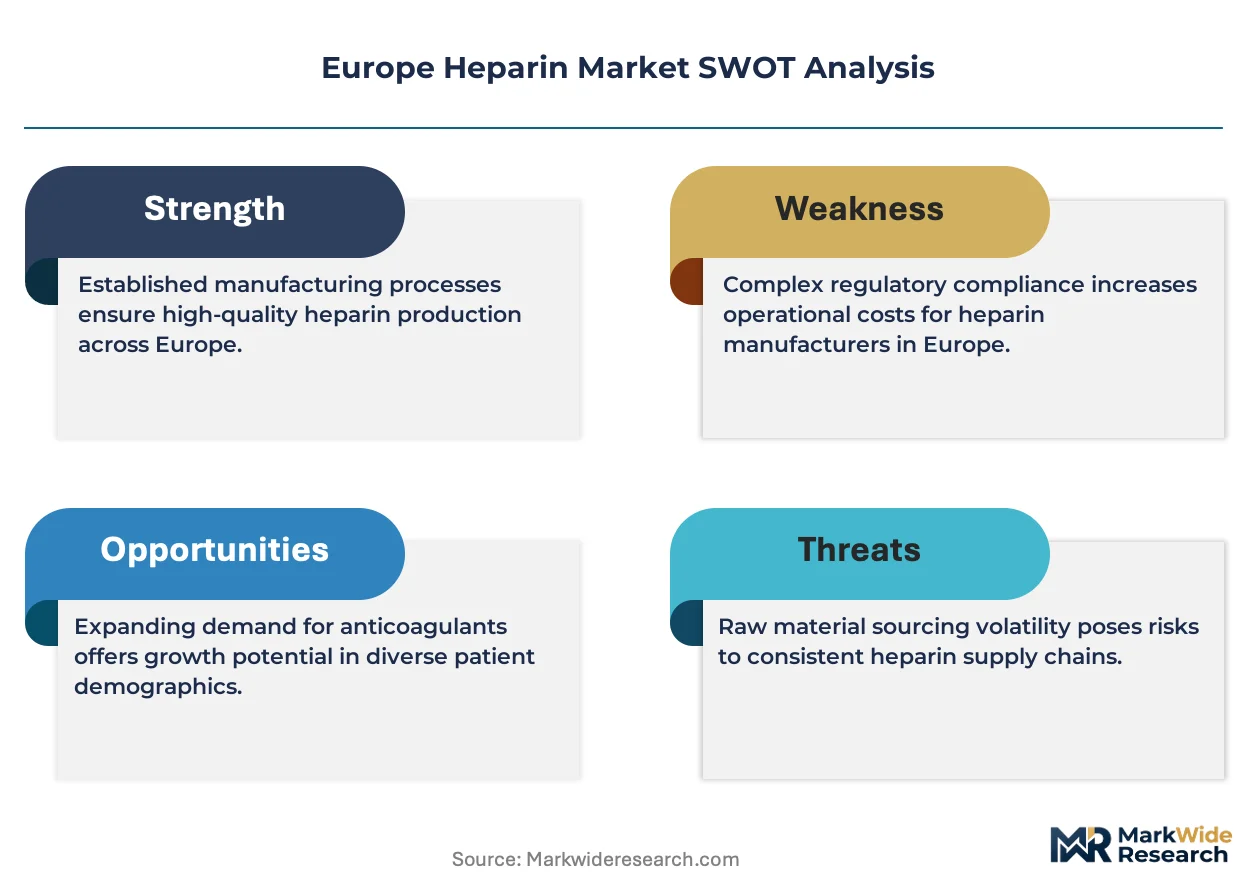
Batch-scale economies in heparin API manufacturing compress unit costs for facilities operating above 10,000-kilogram annual throughput, concentrating supply power among Spanish and Dutch slaughterhouse-integrated processors while establishing price floors that marginalize sub-scale competitors. This scale dynamic binds pricing trajectories to mucosa sourcing density and notified body certification density across European manufacturing networks.
Pricing Analysis
Certification level creates the primary spread between CE-marked device-integrated formulations and commodity API grades. Three-tier pricing structure across premium, standard, and economy levels reflects MDR compliance investment, real-time release testing capability, and safety-engineered needle system bundling. Cost compression in standard-tier unfractionated heparin is intensifying because Polish and Czech hospital purchasing cooperatives are consolidating tender volumes. Home care providers exhibit highest price sensitivity due to reimbursement caps on extended prophylaxis, while German university hospital networks prioritize supply continuity over unit cost.
Supply Chain Analysis
Spanish and Dutch slaughterhouse byproduct streams constitute the dominant chokepoint for porcine intestinal mucosa API feedstock. Heparin sodium production draws from enzymatic depolymerization reagents sourced from German chemical suppliers and chromatography resins manufactured in Sweden. Single-source vulnerability concentrates in the 80%-plus dependency on Iberian and Dutch mucosa streams for European API requirements. Distribution runs through hospital purchasing cooperatives in France and Germany, with secondary channels serving United Kingdom district nursing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe heparin market sits in a cyclical recovery phase as orthopedic surgery backlogs from pandemic-era deferrals clear through German and French hospital networks. This procedural volume normalization supports pricing stabilization for prophylactic Low Molecular Weight Heparin formulations.
For Market Incumbents: Fortify notified body certification pipelines for combination device submissions under EU MDR transition timelines. Capture backward integration into Spanish mucosa sourcing through long-term slaughterhouse supply agreements to defend against REACH-driven qualification delays. Accelerate real-time release testing installation to compress working capital cycles below 45-day batch quarantine periods. For New Entrants and Emerging Players: CE marking fast-track partnerships with German notified bodies offer the most penetrable access point for device-integrated LMWH formulations. Target Warsaw and Prague hospital modernization programs funded through EU cohesion allocations, where procurement cooperatives lack incumbent supplier lock-in. Lead with prefilled syringe safety systems bundled with biosimilar enoxaparin to differentiate on device ergonomics rather than molecule parity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors parenteral manufacturing specialists with installed continuous processing platforms and EMA-registered API facilities. Acquisition target archetype: mid-scale German or Austrian CMOs with Paul-Ehrlich-Institut inspection history and underutilized aseptic filling capacity. Monitor EMA guidance publication timelines on nitrosamine impurity thresholds as the inflection signal for reformulation investment waves.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR transition deadlines filter device-capable suppliers from marginal competitors across German notified body networks. |
| Backward Integration | Captive mucosa sourcing from Spanish slaughterhouses insulates against REACH documentation delays and supply interruption. |
| Real-Time Release Testing | Eliminates batch quarantine periods for Fresenius Kabi and specialized CMOs, compressing working capital requirements. |
| Hospital System Partnership | Multi-year framework agreements through Assistance Publique-Hôpitaux de Paris bundle volumes and eliminate spot-market channels. |
| Reimbursement Strategy | United Kingdom early discharge protocols extend subcutaneous therapy duration into district nursing reimbursement codes. |
Research Methodology
A spread of perspectives from hospital procurement managers, regulatory affairs leads at parenteral manufacturers, formulary directors in German university networks, and EMA quality assessors converged on the working assumptions. Secondary validation drew from EMA Official Medicines Control Laboratories batch release records, Paul-Ehrlich-Institut inspection reports, NHS Supply Chain tender documentation, and REACH registration dossiers. Bottom-up volume modeling triangulated against top-down pharmaceutical expenditure data from national health accounts.
Segmentation dimensions modeled span molecular weight category, therapy area, delivery mechanism, and end-user setting across the projection horizon. CAGRs were derived from procedure volume trajectories, tender price evolution patterns, and substitution elasticity estimates for direct oral anticoagulants. Forecast inputs incorporated orthopedic surgery scheduling data from German hospital planning offices and nitrosamine testing compliance cost curves from analytical chemistry service providers.
Underlying assumptions cover MDR transition adherence timelines, REACH documentation completion rates, and EU cohesion fund disbursement schedules for Central European hospital modernization, with deviation risk concentrated in porcine disease outbreak scenarios and EMA guidance revision cycles. Practitioners should keep alternative scenarios live as notified body capacity constraints and biosimilar interchangeability criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market