
 Global Wood Cement Boards Market | 2026-2036
Global Wood Cement Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood Cement Boards Market Intelligence
A scarcity of certified installers trained in specialized wood cement board fastening and finishing techniques is redrawing the competitive landscape. Eltomation B.V. specializes in the production technology itself, giving it a unique position in the value chain. VIVALDA differentiates through its fabrication and distribution network in the United Kingdom. Fibretex India Pvt. Ltd. leverages its manufacturing scale to serve high-volume residential projects in South Asia.
Wood cement boards are composite panels made by combining wood fibers with Portland cement under pressure. This process yields a material with high density, exceptional fire resistance, and superior performance against moisture, serving as a durable construction alternative. Fiber cement boards represent the largest product segment, valued for versatility in exterior applications. While residential construction drives volume, commercial complexes offer higher-margin opportunities for specialized laminated boards.
Market access hinges on adherence to performance standards like ASTM specifications in the United States and CE marking in Europe. Fire resistance and material composition rules, enforced by bodies like the European Committee for Standardization, directly influence product design. Stakeholders must decide whether to prioritize investment in sustainable binders for green building certifications or focus on production cost optimization for mass-market competition.
Market Dynamics
The market's core tension lies between the push for sustainable building practices and the operational realities of construction. Demand for fire-resistant, durable materials in residential projects is pulling the market forward, while a scarcity of specialized installation skills creates significant friction.
Growth Catalysts
- Stricter Building Codes:New fire safety regulations for multi-family residential and commercial buildings in Europe and North America mandate materials with high fire-resistance ratings, directly benefiting wood cement boards.
- Construction Activity in Southeast Asia:A surge in new residential and infrastructure projects in nations like Vietnam and the Philippines creates consistent, high-volume demand for durable and moisture-resistant building panels.
- Green Building Certifications:The pursuit of certifications such as LEED and BREEAM encourages the use of materials with sustainable components, including wood fibers from managed sources, positioning these boards favorably.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of Portland cement, a primary raw material, directly impact production costs and create pricing instability for manufacturers and distributors.
- Installation Complexity:The material's high density requires specialized cutting tools and fastening techniques, limiting the pool of qualified installers and increasing labor costs compared to lighter alternatives.
- Substitution from Fiber Cement:In applications where fire resistance is less critical, standard fiber cement boards offer a lower-cost, lighter-weight alternative, capturing market share in exterior siding and backer board segments.
Strategic Opportunities
- Prefabricated Systems:Development of modular wall panels and prefabricated building components for commercial and residential construction can reduce on-site labor needs and accelerate project timelines.
- Acoustic and Thermal Formulations:Engineering specialized boards with enhanced acoustic dampening or thermal insulation properties opens higher-margin opportunities in schools, hospitals, and high-performance housing.
- Low-Carbon Binders:Investing in research for alternative, low-carbon binders to replace a portion of Portland cement can create a strong competitive advantage for projects targeting the highest green building standards.
Industry Challenges
- Installer Training Deficit:A significant shortage of contractors trained in the specific fastening and finishing protocols for wood cement boards leads to installation errors and limits adoption.
- Logistical Hurdles:The high weight and density of the boards increase freight costs and require specialized handling equipment on job sites, adding complexity to supply chain management.
- Performance Certification Timelines:Securing and maintaining compliance with performance standards like ASTM in the U.S. and CE marking in Europe is a costly and lengthy process for new products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood Cement Boards Market |
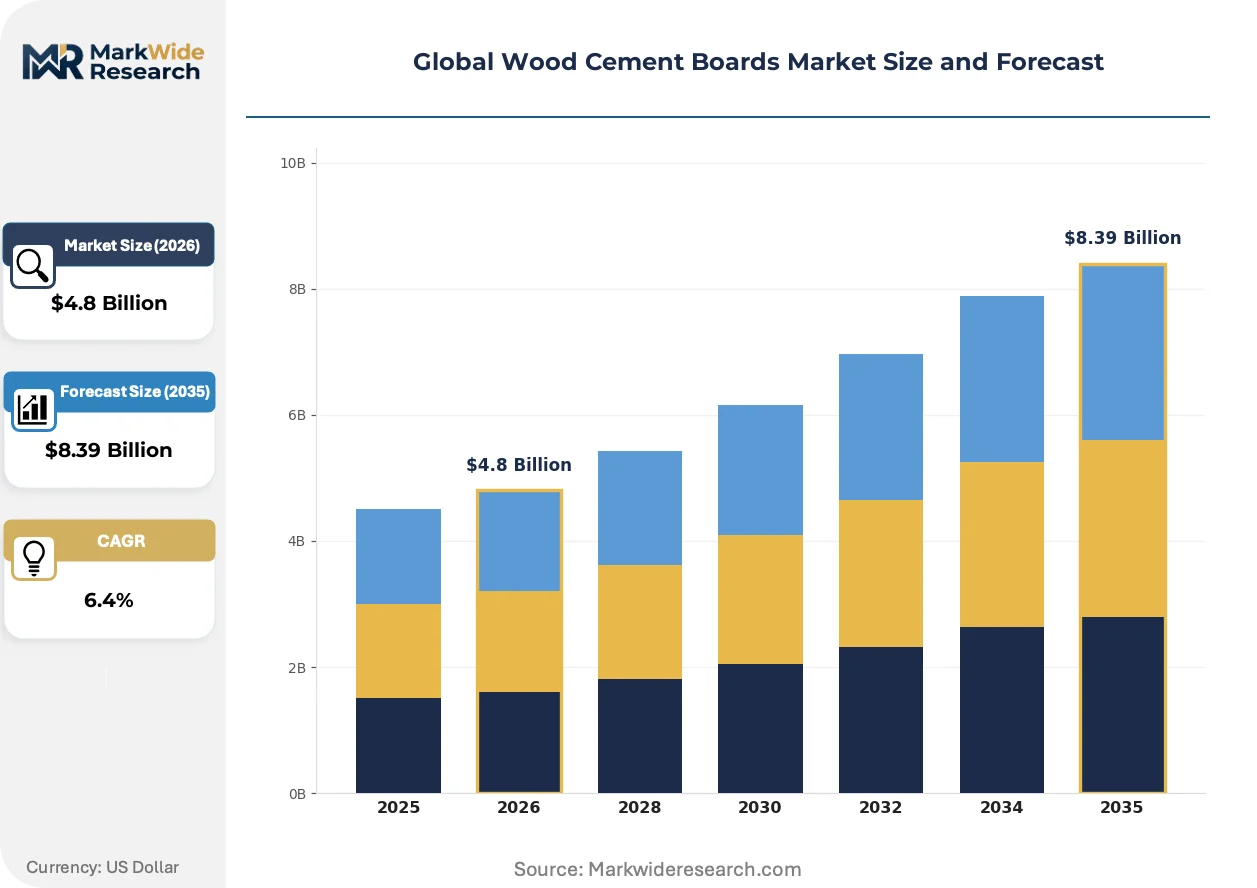
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Cement Board, Sandwich Board, Cement Particle Board, Laminated Board, Reinforced Cement Board Application: Residential Construction, Commercial Complexes, Institutional Buildings, Industrial Facilities, Public Infrastructure End User: General Contractors, Building Developers, Interior Decorators, Government Agencies, Architectural Firms Distribution Channel: Direct Sales, Dealers & Distributors, Online Retailers, Wholesale Suppliers, Specialty Stores |
| Companies Covered | Fibretex India Pvt. Ltd., VIVALDA, Smart Wood Boards, Shahsahib Woodwool Enterprises, Foshan Tiange Science and Technology Co., Ltd., Trusus Technology (Beijing) Co., Limited, Right Angle Interior Pvt. Ltd., Fibroplit, Ltd., Eltomation B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood Cement Boards Market Strategic Shifts & Innovations
Product evolution is shifting from a focus on pure durability to a more nuanced balance of performance, sustainability, and ease of installation. This change is driven by regulatory pressures for greener materials and end-user demand for solutions that reduce on-site labor complexity.
Lightweight aggregate technology involves incorporating materials like expanded clay or perlite into the cement-wood mixture to reduce panel density. This innovation is gaining traction among builders of multi-story structures who need to manage overall structural load. The development of different density classes is fragmenting the market, creating distinct segments for high-impact durability versus ease of handling and installation.
European Union regulations under the Green Deal framework are compelling manufacturers to increase transparency in material sourcing and end-of-life planning. These policies directly influence product development, favoring boards made with recycled content or designed for disassembly and reuse. The laminated and decorative board segments, often specified in public and commercial projects, are most affected and are adapting by documenting their circular economy credentials.
Specification-driven purchasing by architects and fire-safety engineers is becoming more common than bulk procurement by general contractors. This shift disrupts traditional, volume-based distribution models, favoring suppliers who can provide detailed technical data, BIM objects, and installation support. This trend is most pronounced in the North American and Western European commercial construction sectors, where project liability and stringent code adherence are primary concerns.
Global Wood Cement Boards Market Segmentation
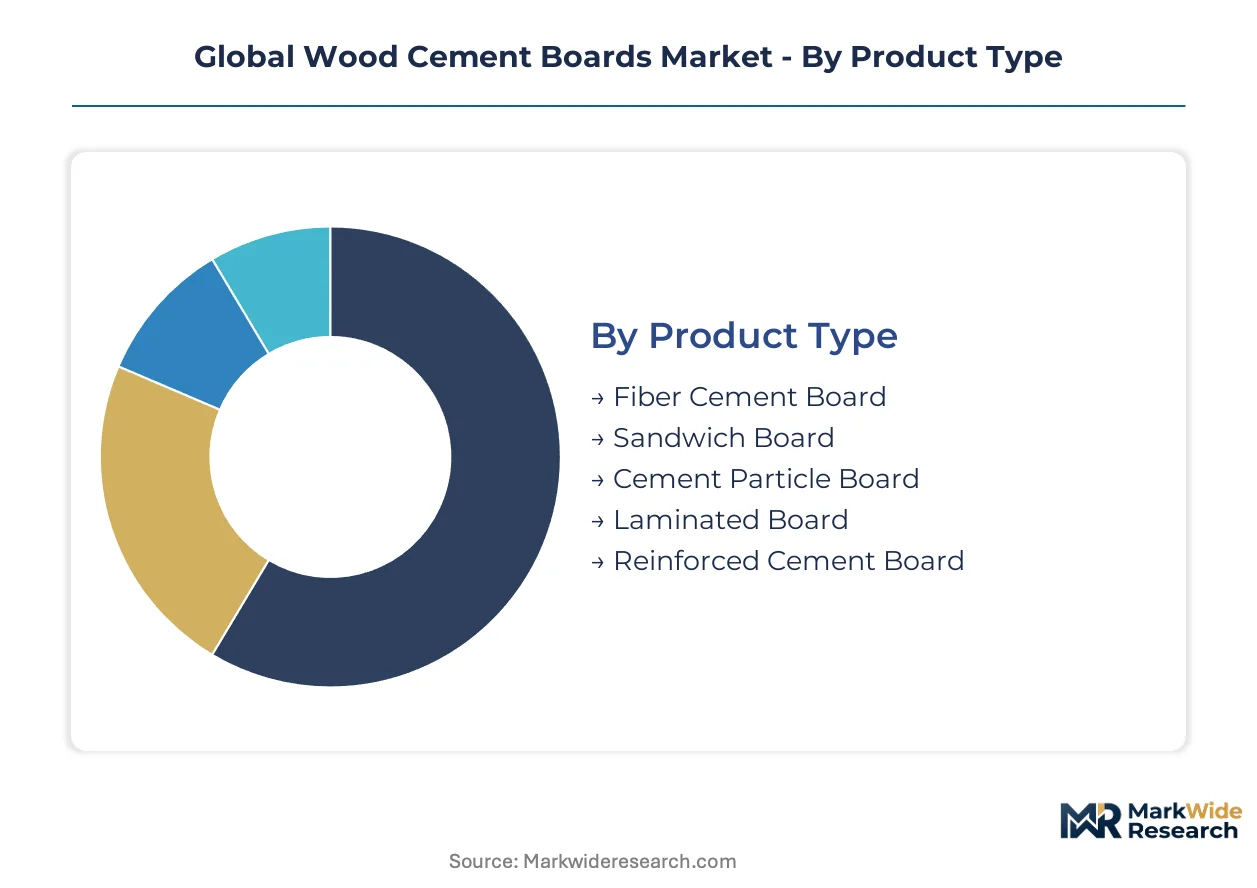
The wood cement boards market segments distinctively by product composition, end-use application, and the specific client types driving procurement decisions. Understanding these divisions is essential for manufacturers to align product development with evolving performance standards and for distributors to optimize supply chains for diverse construction project requirements.
Product Type:
Product types exhibit varying degrees of geographic adoption, with certain formulations favored in domestic markets due to local building codes, while others are export-led for specialized projects.
- Fiber Cement Board:These composite panels combine cellulose fibers, Portland cement, sand, and water, offering high durability and fire resistance. Demand for fiber cement boards concentrates in exterior applications across Southeast Asian nations, driven by new residential and commercial construction activity.
- Laminated Board:Laminated boards feature a decorative or protective layer bonded to a wood cement core, enhancing aesthetics and surface properties. These higher-margin products see significant demand in commercial complexes in North America and Europe, where architects specify them for interior finishes and feature walls.
- Sandwich Board:Sandwich boards incorporate an insulating core between two wood cement board layers, providing enhanced thermal and acoustic performance.
- Cement Particle Board:Composed of wood particles and cement, these boards offer good structural integrity and fire resistance, often used in flooring and wall lining applications.
- Reinforced Cement Board:These boards integrate additional reinforcement, such as mesh or fibers, to improve impact resistance and structural strength for demanding environments.
Fiber Cement Board commands the established base. The steepest expansion runs through Laminated Board.
Application:
Application segments reflect different margin profiles, with specialized uses often commanding premium pricing due to performance requirements and lower volume, contrasting with high-volume, cost-sensitive general construction.
- Residential Construction:This segment includes single-family homes and multi-unit dwellings, utilizing wood cement boards for fire-resistant sheathing, flooring, and exterior siding. Volume demand in residential construction is particularly strong in developing economies like Vietnam and the Philippines, where rapid urbanization drives new housing projects.
- Commercial Complexes:Commercial complexes encompass office buildings, retail centers, and hotels, where wood cement boards are specified for durability, fire safety, and aesthetic finishes. Higher-margin opportunities exist within this segment for specialized laminated and acoustic boards, particularly in European and North American markets with stringent building codes.
- Institutional Buildings:This category covers schools, hospitals, and government facilities, requiring materials with high fire ratings and robust performance for public safety.
- Industrial Facilities:Industrial settings use wood cement boards for their durability and resistance to harsh conditions, including fire protection in warehouses and manufacturing plants.
- Public Infrastructure:Applications in public infrastructure include transport hubs and utility structures, where material longevity and resistance to environmental factors are critical.
Demand in Residential Construction underpins market volume, while Commercial Complexes present the highest value opportunities.
End User:
The end-user landscape is fragmented by customer type, with some entities focusing on direct installation and others on material specification, influencing sales channels and product requirements.
- General Contractors:These entities manage overall construction projects, making procurement decisions based on cost-effectiveness, material availability, and ease of installation. General contractors in North America often prioritize materials that meet ASTM specifications and can be integrated into prefabricated systems to reduce labor costs.
- Architectural Firms:Architectural firms specify building materials based on design aesthetics, performance criteria, and adherence to sustainability standards like LEED. These firms frequently drive demand for specialized, higher-margin products, such as laminated boards with specific finishes, particularly in European commercial projects.
- Building Developers:Building developers focus on project profitability and speed of construction, often seeking cost-effective and readily available wood cement board solutions for large-scale developments.
- Interior Decorators:Interior decorators select wood cement boards for their aesthetic qualities and finish options, primarily for decorative wall panels and ceiling applications in residential and commercial interiors.
- Government Agencies:Government agencies procure wood cement boards for public buildings and infrastructure projects, emphasizing compliance with fire safety regulations and long-term durability.
General Contractors drive project execution, whereas Architectural Firms shape material specification.
Distribution Channel:
Distribution channels vary by volume and market reach, with traditional networks handling bulk orders and emerging channels catering to specialized or smaller-scale purchases.
- Dealers & Distributors:These channels represent the primary route for high-volume sales, stocking a wide range of wood cement board products and serving a broad customer base. Dealers and distributors leverage established logistics networks to serve residential and commercial projects across diverse geographies, including the rapidly expanding Southeast Asian market.
- Direct Sales:Manufacturers engage in direct sales for large-scale projects or to supply specialized products directly to major contractors and architectural firms. This channel allows for customized orders and direct technical support, particularly for high-value commercial and institutional projects in Europe.
- Online Retailers:Online platforms provide a convenient channel for smaller purchases and niche products, often targeting individual builders or specialized contractors seeking specific board types.
- Wholesale Suppliers:Wholesale suppliers serve as intermediaries, providing bulk quantities of wood cement boards to smaller dealers, contractors, and building material retailers.
- Specialty Stores:These outlets cater to specific market niches, offering curated selections of wood cement boards for particular applications, such as decorative panels or acoustic solutions.
Volume sales primarily flow through Dealers & Distributors, with Direct Sales gaining share in niche markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global wood cement boards market exhibits varying consumption patterns, with Southeast Asian nations prioritizing volume for new residential construction, while European and North American markets focus on higher-value, specialized applications. This regional differential influences product development and distribution strategies. Market access regulations also differ significantly across these key geographies.
Vietnam
Rapid urbanization and new residential and infrastructure projects drive significant demand for durable wood cement boards in Vietnam. Government initiatives promoting sustainable construction encourage environmentally friendly material adoption. Development in Ho Chi Minh City particularly leverages these panels for moisture and fire resistance.
United States
Residential construction for fire-resistant sheathing and commercial complexes demanding specialized boards fuel market expansion in the United States. Adherence to ASTM specifications ensures product quality and safety in diverse building applications. Major metropolitan areas like New York City and Chicago drive innovation in high-performance building solutions.
Germany
Higher-margin opportunities for specialized laminated and acoustic boards characterize the German market, particularly within commercial complexes. CE marking and the EU Green Deal framework directly influence product design and material sourcing. Architectural firms in Munich and Hamburg specify advanced wood cement board solutions for sustainable projects.
India
High-volume residential projects, especially in rapidly developing urban centers, create consistent demand for cost-effective and durable wood cement boards across India. BIS standards for construction materials ensure quality and promote local manufacturing capabilities. Urbanization in Mumbai and Chennai particularly fuels the need for cement particle boards.
China
Extensive new construction, encompassing both residential and commercial sectors, along with significant infrastructure development, underpins robust demand in China. GB standards for building materials and the nation's dual carbon goals promote sustainable wood cement board alternatives. Industrial hubs within the Pearl River Delta actively incorporate these boards into large-scale building initiatives.
Global Wood Cement Boards Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the wood cement boards market, creating a tiered competitive structure. The competitive landscape fragments across raw material technology providers, specialized fabrication and distribution networks, and large-scale volume manufacturers, each occupying distinct value chain positions. Key competitive moves include strategic partnerships for distribution expansion and continuous investment in product innovation to meet evolving performance standards and green building certifications.
Specialists in production technology, such as Eltomation B.V., exemplify companies that provide foundational manufacturing processes and intellectual property to the industry. VIVALDA, with its established fabrication and distribution network, represents firms focused on market access and delivering tailored solutions in specific geographies like the United Kingdom. Fibretex India Pvt. Ltd. anchors the high-volume manufacturing segment, serving large residential projects through economies of scale and efficient supply chains across South Asia.
| Leading Market Players |
|---|
| Fibretex India Pvt. Ltd. |
| VIVALDA |
| Smart Wood Boards |
| Shahsahib Woodwool Enterprises |
| Foshan Tiange Science and Technology Co., Ltd. |
| Trusus Technology (Beijing) Co., Limited |
| Right Angle Interior Pvt. Ltd. |
| Fibroplit, Ltd. |
| Eltomation B.V. |
| Others |
Cost & Logistics Intelligence
Project-based contracts, common in large construction, lock in both supply access and price visibility for wood cement boards, influencing procurement strategies. This structure helps manage input cost volatility for manufacturers and ensures material availability for major developments.
Pricing Analysis
Project-based pricing dominates the wood cement boards market, particularly for large residential and commercial undertakings. Price differentiation stems from adherence to performance standards like ASTM specifications and CE marking, alongside volume scale for bulk orders. Cost compression intensifies due to fluctuations in Portland cement prices and competition from lower-cost fiber cement alternatives. General contractors exhibit high price sensitivity, while architectural firms prioritize performance and aesthetic differentiation for specialized laminated boards.
Supply Chain Analysis
Managing inventory levels presents a challenge for wood cement board manufacturers due to the material's high weight and density, impacting logistics. Supply concentration centers in China, India, and Southeast Asian nations like Vietnam, which possess significant manufacturing scale. The industry relies heavily on a consistent supply of Portland cement and wood fibers. Logistics hurdles and raw material price volatility represent key structural risks. Distribution primarily runs through dealers and distributors for high-volume sales, with direct sales serving specialized commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wood cement boards market is entering a cyclical recovery phase, driven by renewed residential and commercial construction activity, particularly across Southeast Asia. This upswing presents opportunities for strategic positioning across the value chain.
For Market Incumbents: Secure market share by investing heavily in certified installer training programs to mitigate the significant installer deficit. Optimize logistics and supply chain management for high-density materials to counteract rising freight costs and maintain competitive pricing against fiber cement substitutes. Reinforce channel control through strategic partnerships with key dealers and distributors, ensuring consistent market access and technical support for complex specifications.
For New Entrants and Emerging Players: Gaps in specialized technical support and integrated solutions offer white-space opportunities for new entrants. Target the commercial complexes segment with prefabricated wall panels and enhanced acoustic or thermal board formulations. Provide comprehensive BIM objects and installation support to architectural firms and general contractors, addressing the complexity of wood cement board applications. Focus initial efforts on North American and European markets where specification-driven purchasing dominates.
For Investors and Strategic Acquirers: The market sits at an expansion phase that favors vertically integrated specialists capable of delivering high-performance, sustainable solutions. Long-term viability, spanning the next 5-10 years, remains strong due to increasing demand for durable and fire-resistant building materials. Target acquisition profiles include production technology providers like Eltomation B.V. and established fabrication and distribution networks such as VIVALDA. The signal to watch for accelerated growth is the commercial adoption rate of low-carbon binder technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Installer Certification | This initiative addresses the installer training deficit, reducing installation errors and boosting product adoption. |
| Develop Lightweight Formulations | Lightweight aggregate technology reduces structural load in multi-story buildings, expanding application scope. |
| Expand Prefabricated Systems | Modular wall panels accelerate project timelines and reduce on-site labor needs for general contractors. |
| Research Low-Carbon Binders | Alternative binder investment supports green building certifications and aligns with EU Green Deal regulations. |
| Strengthen Distribution Networks | Enhanced dealer and distributor partnerships improve market access, especially in Southeast Asian growth regions. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry association reports, building code databases, and government construction statistics. Primary interviews engaged architects, general contractors, material scientists, and building code officials to gather qualitative insights. This approach integrated bottom-up market intelligence with top-down validation, ensuring comprehensive data integrity.
Product type, application, end-user, distribution channel, and regional regulatory compliance formed the segmentation dimensions modeled across the analysis window. The analytical framework projected market growth by correlating historical trends with future construction spend forecasts and anticipated fire safety regulation updates. Compound annual growth rates were derived from a multi-variant regression model incorporating these factors.
Forecasts assume regulatory continuity in the EU, United States, and India; material policy shifts would require re-modeling. These projections reflect current market dynamics and are subject to revision based on input cost volatility and installer skill shortages. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Australia Steel Rebar Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
US Metal Stadium Seating Market
Building & Construction Materials
Liquid Applied Roofing Market