
 Cement Board Market | 2026-2036
Cement Board Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Board Market Outlook
Performance-based warranty and installation-support subscriptions is restructuring how cement board manufacturers capture lifetime value from contractors. James Hardie Industries Plc leverages its color-plus prefinished systems to lock in specification loyalty across residential channels. Etex Group anchors European supply through dedicated fiber cement plants in Belgium and regional distribution hubs. Saint-Gobain competes with integrated gypsum-cement hybrid solutions that reduce trade coordination on multi-family jobsites.
Cement board is a flat panel manufactured from cement, silica, and cellulose fibers pressed under high pressure and cured to form a dense, dimensionally stable sheet resistant to moisture, fire, and termite damage, primarily serving as an exterior cladding substrate, tile backer, or structural sheathing in buildings. The product typically achieves flexural strengths exceeding 15 MPa and maintains dimensional stability under cyclic wet-dry exposure, making it suitable for facade systems in humid climates. Fire-resistant board leads volume in commercial high-rise construction where code mandates non-combustible exterior walls, while water-resistant board posts the fastest growth in residential renovation projects replacing moisture-damaged gypsum in kitchens and baths. Structural board commands premium positioning in prefabricated panel systems where combined shear and weather barrier functions reduce material layers.
The US EPA regulates formaldehyde emissions from composite wood products under TSCA Title VI, indirectly steering specification toward cement-based alternatives that contain no resin binders. ECHA's REACH restrictions on crystalline silica in construction materials are forcing European manufacturers to reformulate fiber cement mixes or invest in wet-processing dust controls. ASTM C1186 and EN 12467 govern product classification and testing protocols, creating compliance barriers for new entrants lacking certified laboratory relationships. Stakeholders must monitor evolving silica exposure limits and embodied carbon disclosure rules, as these will determine which product formulations retain specification access in public procurement channels.
Market Dynamics
The US EPA's TSCA Title VI formaldehyde emission standards are systematically displacing resin-bound composite wood products from residential construction specifications, redirecting builder procurement toward inorganic cement-based substrates that carry no volatile organic compound exposure liability.
Growth Catalysts
- Hurricane-resistant building codes:The southeastern United States enforces stricter moisture-barrier requirements after repeated storm seasons, mandating water-resistant exterior substrates in coastal zones.
- REACH silica reformulation mandates:ECHA's crystalline silica restrictions are accelerating wet-processing dust control investments across European fiber cement manufacturing.
- Prefabricated panel systems:Structural cement board combines shear resistance and weather barrier functions, eliminating material layers in offsite construction.
Market Restraints
- Portland cement input volatility:Energy-intensive clinker production faces carbon pricing pressure and feedstock cost swings that compress manufacturer margins.
- Belgium-Germany production concentration:Etex Group and Saint-Gobain anchor European supply from Benelux plants, creating geographic vulnerability to regional logistics disruptions.
- Gypsum-cement hybrid substitution:Saint-Gobain's integrated gypsum solutions reduce trade coordination on multi-family jobsites, capturing specification share in vertical residential.
Strategic Opportunities
- Color-plus prefinished systems:Specification loyalty programs lock residential channel contractors through warranty-backed installation support subscriptions.
- India coastal urbanization:Monsoon-exposed metros Mumbai and Chennai present untapped demand for moisture-resistant tile backing and exterior cladding.
- Embodied carbon disclosure rules:Public procurement channels in California and the European Union are prioritizing low-carbon cement formulations with Environmental Product Declarations.
Industry Challenges
- Certified installer scarcity:Proper cement board fastening and flashing execution demands trained trades, creating bottlenecks in high-velocity residential markets.
- ASTM C1186 compliance timelines:New entrants lacking established laboratory relationships face extended product certification cycles before specification access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Board Market |
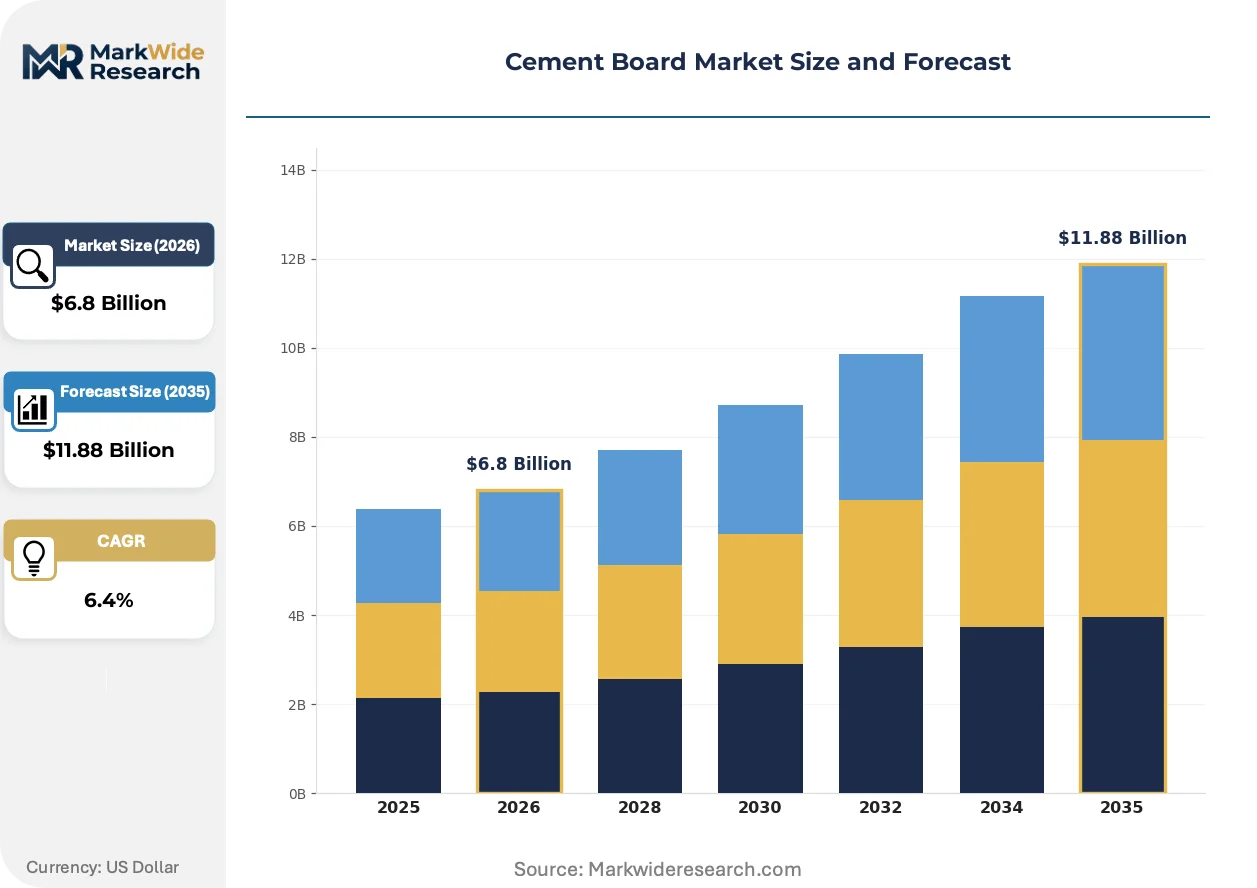
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Resistant Board, Fire-Resistant Board, Structural Board, Non-Structural Board End Use: Commercial Construction, Residential Construction, Industrial Applications, Renovation Projects Thickness: 6 mm, 9 mm, 12 mm, 15 mm Application: Wall Sheathing, Backer Board, Ceiling Tiles, Flooring |
| Companies Covered | James Hardie Industries Plc, Etex Group, Saint-Gobain, Siam Cement Public Company Limited, Nichiha Corporation, Johns Manville Corp., HIL Limited, Everest Industries Limited, Allura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Board Market Strategic Shifts
Product formulation and specification capture models are converging around performance guarantees and prefinished system integration, compressing traditional material procurement cycles and redefining contractor loyalty mechanisms.
Fiber-cement composite technology is unifying structural sheathing, weather barrier, and finished surface functions into single-source panel systems. Multi-family developers in Florida and Texas are specifying these integrated assemblies to accelerate enclosure schedules. The technology is unifying previously separate trade scopes, reducing coordination friction and capturing premium positioning in vertical construction.
REACH crystalline silica exposure limits are forcing reformulation of traditional dry-mix fiber cement production across European manufacturing. Wet-processing dust suppression systems now absorb significant capital allocation. Belgian and German plants face the steepest compliance curves, with reformulated mixes entering specification trials in 2024-2025 building seasons.
Builder procurement patterns are compressing toward single-source envelope solutions that bundle material, warranty, and installation support. Regional distributors in the southeastern United States are consolidating specification influence through contractor training programs and inventory guarantees. The shift is most visible in hurricane-prone coastal counties where code enforcement density rewards pre-certified system providers.
Cement Board Market Segmentation
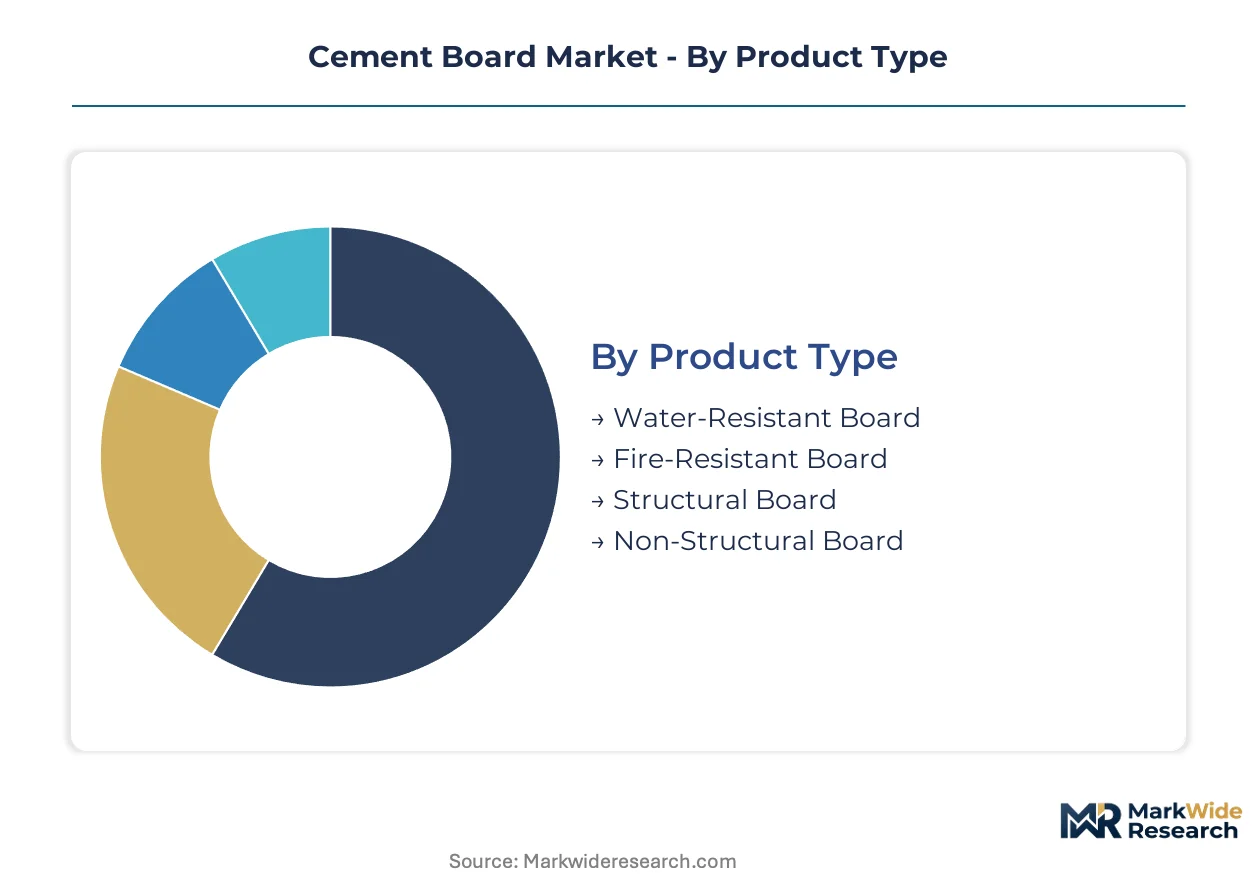
Cement board manufacturers configure production lines around performance grades that align with distinct code environments and trade contractor workflows. Segmentation reveals where formulation investments concentrate capacity and which specification channels reward premium positioning over commodity supply.
Product Type:
Supply concentration tilts toward performance-differentiated formulations that command specification loyalty in code-intensive building envelopes.
- Water-Resistant Board:Formulated with hydrophobic additives and dense fiber matrices that block moisture ingress through cyclic wet-dry exposure. Demand clusters in southeastern United States coastal counties where hurricane-resistant building codes mandate exterior substrates with demonstrated moisture-barrier performance after repeated storm seasons.
- Fire-Resistant Board:Engineered with elevated cement-to-fiber ratios and mineral fillers that achieve non-combustible ratings under ASTM E136 testing protocols. Commercial high-rise construction in jurisdictions with strict facade fire safety mandates—particularly California and New York—specify these boards for exterior wall assemblies where code prohibits combustible materials above specified heights.
- Structural Board:Reinforced with high-tensile cellulose fibers and manufactured to shear wall racking resistance standards, serving prefabricated panel systems that combine structural and weather barrier functions.
- Non-Structural Board:Standard-density formulations for interior tile backing and decorative cladding where flexural strength requirements remain below structural thresholds.
Fire-resistant board absorbs the bulk of installed capacity in commercial manufacturing lines; water-resistant board is expanding most quickly in residential renovation channels.
End Use:
Cost tier segmentation separates specification-driven commercial procurement from price-sensitive residential volume plays.
- Commercial Construction:Encompasses office towers, healthcare facilities, and institutional buildings where extended warranty terms and certified installer networks influence procurement decisions. Fire-rated assemblies dominate this segment.
- Residential Construction:Single-family and multi-family housing where moisture-resistant siding substrates face accelerating code adoption in hurricane-exposed Florida and Texas markets. Builders prioritize prefinished systems that compress enclosure schedules.
- Industrial Applications:Manufacturing plants, warehouses, and agricultural buildings requiring chemical-resistant cladding and high-impact wall surfaces. Specifications emphasize durability over aesthetic finish.
- Renovation Projects:Retrofit activity replacing moisture-damaged gypsum in kitchens, baths, and below-grade spaces. Homeowner-direct procurement patterns dominate with emphasis on readily available stock-keeping units.
Commercial construction commands the highest margin tier through specification complexity; renovation projects represent the steepest expansion trajectory as housing stock ages and moisture damage claims accumulate.
Thickness:
Volume distribution across thickness grades reflects the layering logic of multi-component wall assemblies and the structural demands of floor and roof applications.
- 6 mm:Thin-profile board for interior tile backing and ceiling applications where weight reduction and space economy outweigh structural requirements. Standard in residential bathroom renovations.
- 9 mm:Mid-weight formulation serving as the default exterior cladding substrate in single-family residential construction. Balances fastening hold strength with manageable panel weight for two-person installation crews.
- 12 mm:Heavy-duty grade specified for structural sheathing in prefabricated wall panels and floor underlayment in multi-story construction. Shear wall applications in seismic zones favor this thickness.
- 15 mm:Maximum-density board for industrial flooring, impact-resistant wall surfaces, and fire-rated shaft wall assemblies. Limited production runs command premium pricing.
9 mm thickness dominates residential production volumes; 12 mm is gaining share fastest in offsite construction and panelized building systems.
Application:
Customer type segmentation distinguishes between trade-specialized specification channels and general contractor procurement patterns.
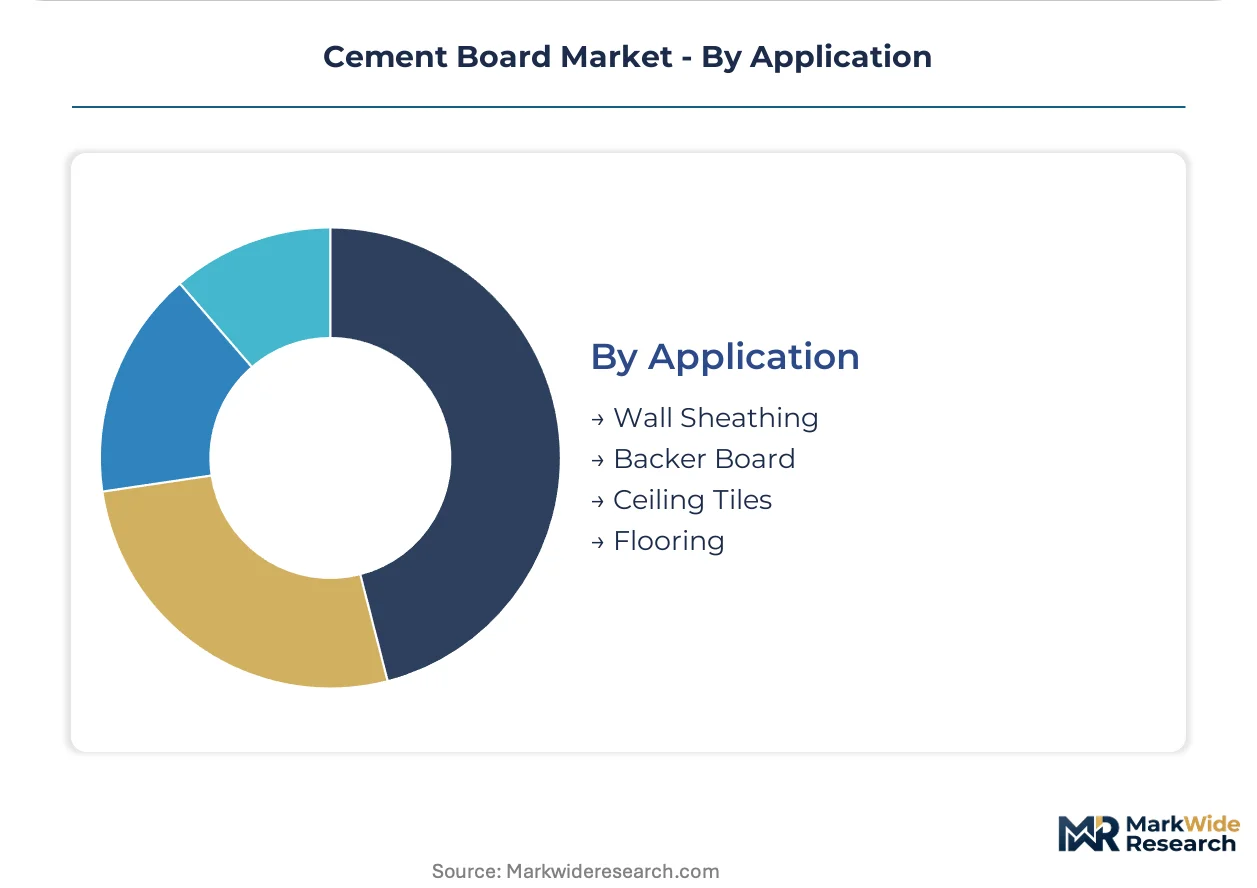
- Wall Sheathing:Exterior substrate applications where cement board serves as the primary weather-resistant barrier beneath finished cladding. Hurricane-prone coastal markets drive specification toward water-resistant grades with demonstrated fastener retention.
- Backer Board:Tile substrate for wet-area installations in bathrooms, kitchens, and commercial food service spaces. Residential renovation demand concentrates in moisture-damage replacement cycles.
- Ceiling Tiles:Suspended and direct-applied ceiling systems requiring lightweight panels with sag resistance in humid environments. Commercial and institutional buildings specify fire-rated formulations.
- Flooring:Underlayment and finished floor applications in moisture-exposed and high-traffic environments. Industrial facilities and residential basements represent primary demand centers.
Wall sheathing commands the largest share of cement board shipments; backer board is expanding most quickly in residential renovation markets replacing failed gypsum substrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium and Germany concentrate European fiber cement manufacturing capacity, while the United States and India absorb the bulk of incremental demand growth. Production geography and consumption patterns diverge sharply, with coastal construction codes driving specification intensity in import-dependent markets.
United States
Hurricane-resistant building codes in Florida and Texas mandate water-resistant exterior substrates in coastal counties. The EPA's TSCA Title VI formaldehyde emission standards systematically displace resin-bound composite wood products from residential specifications. Southeastern distributors consolidate influence through contractor training programs and inventory guarantees in storm-exposed markets.
Belgium
Etex Group anchors European supply from dedicated fiber cement plants serving Benelux and adjacent export markets. ECHA's REACH crystalline silica restrictions force wet-processing dust control investments across manufacturing lines. Belgian plants face steep compliance curves as reformulated mixes enter specification trials for the 2024-2025 building seasons.
Germany
Industrial flooring and fire-rated shaft wall applications command premium pricing for maximum-density board grades. The country's construction regulator enforces strict facade fire safety mandates that specify non-combustible materials above threshold heights. Manufacturing clusters in North Rhine-Westphalia supply integrated gypsum-cement hybrid solutions for multi-family vertical construction.
India
Monsoon-exposed metros Mumbai and Chennai present untapped demand for moisture-resistant tile backing and exterior cladding. The Bureau of Indian Standards (BIS) certification requirements create compliance barriers for imported board formulations. Western India manufacturing corridors near Gujarat expand capacity to serve coastal urbanization in Maharashtra and Karnataka.
China
Prefabricated panel system adoption accelerates enclosure schedules for multi-family developers in coastal provinces. The Ministry of Ecology and Environment (MEE) enforces dual carbon goals that pressure energy-intensive clinker production. Yangtze River Delta construction clusters specify structural cement board for combined shear and weather barrier functions in offsite building systems.
Cement Board Market Competitive Environment
Capital-heavy producers compete with asset-light designers in a market that rewards specification loyalty through integrated system offerings. The vendor base clusters around three strategic archetypes: integrated building materials conglomerates with captive distribution, specialized fiber cement manufacturers with regional production concentration, and diversified construction product suppliers with hybrid gypsum-cement portfolios. Dominant competitive moves include backward integration into raw material sourcing and geographic expansion through dedicated plant investments in high-growth coastal markets.
Within the integrated conglomerate tier, James Hardie Industries Plc and Saint-Gobain exemplify divergent approaches to specification capture—one through color-plus prefinished systems with warranty-backed installation support, the other through gypsum-cement hybrids that reduce trade coordination friction. Etex Group occupies a position as the European production anchor with Belgian and German manufacturing concentration. These three entities represent the primary competitive vectors: system integration, material hybridization, and regional supply security.
| Leading Market Players |
|---|
| James Hardie Industries Plc |
| Etex Group |
| Saint-Gobain |
| Siam Cement Public Company Limited |
| Nichiha Corporation |
| Johns Manville Corp. |
| HIL Limited |
| Everest Industries Limited |
| Allura |
| Others |
Value Chain & Pricing Dynamics
Multi-family developers in hurricane-prone coastal counties concentrate procurement power through specification bundling, forcing manufacturers toward project-based contract pricing that locks volume commitments against raw material volatility. This buyer concentration compresses spot-market premiums and rewards integrated system providers with captive installer networks.
Pricing Analysis
Margin tightening in standard-grade board reflects Portland cement input volatility and carbon pricing pressure on clinker production. Pricing stratifies across fire-rated premium tiers, certified structural grades, and commodity tile-backer stock, with differentiation anchored in ASTM C1186 certification level and regional delivery logistics. Cost-down pressure accelerates as gypsum-cement hybrid solutions capture multi-family specification share. Renovation contractors exhibit highest price sensitivity; commercial high-rise developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in the southeastern United States operate hub-and-spoke patterns radiating from Tampa and Houston to serve storm-exposed coastal counties. Manufacturing concentrates in Belgium, Germany, and the United States, with Belgian plants anchoring European supply through Etex Group's dedicated fiber cement facilities. Raw material dependencies center on Portland cement clinker, cellulose pulp, and crystalline silica feedstocks. Single-source vulnerability concentrates in Benelux production clusters exposed to ECHA REACH compliance disruptions. Distribution runs through contractor-training distributors who consolidate specification influence via inventory guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cement board market sits in a formulation-transition phase as wet-processing dust controls and low-carbon clinker substitutes displace legacy dry-mix production. Fiber-cement composite technology unifying structural and weather barrier functions is capturing specification share from multi-layer assemblies.
For Market Incumbents: Cement specification loyalty through color-plus prefinished systems that bundle warranty-backed installation support, defending against gypsum-cement hybrid substitution in multi-family vertical construction. Deepen backward integration into cellulose fiber sourcing to buffer pulp price volatility. Prioritize wet-processing capital deployment at Belgian and German plants ahead of REACH silica enforcement curves.
For New Entrants and Emerging Players: Launch via regional distributor partnerships in India's western manufacturing corridors near Gujarat, targeting monsoon-exposed Mumbai and Chennai metros with BIS-certified moisture-resistant grades. White-space concentrates in prefabricated panel system supply for offsite construction, where structural board commands premium positioning. Bypass incumbent installer networks by embedding training modules within distributor contracts.
For Investors and Strategic Acquirers: The window for entry favors specialized fiber cement manufacturers with regional production concentration and established laboratory certification relationships. Long-term viability hinges on low-carbon formulation pipelines aligned with California and European Union embodied carbon disclosure rules. Watch ECHA silica exposure limit enforcement timelines as the inflection signal for capacity rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Wet-Processing Dust Control Investment | ECHA REACH compliance at Belgian plants preserves European specification access against reformulated mix trials. |
| Color-Plus Prefinished System Expansion | James Hardie's warranty-backed installation support locks residential channel contractor loyalty across southeastern distributors. |
| Low-Carbon Clinker Formulation Development | Environmental Product Declarations secure California and EU public procurement priority for cement board specifications. |
| Prefabricated Panel System Partnership | Structural board shear-wall integration captures premium positioning in Florida and Texas offsite construction. |
| India Coastal Manufacturing Footprint | Western India capacity expansion serves monsoon-exposed Maharashtra and Karnataka urbanization under BIS certification. |
Study Parameters
Document review covered ASTM C1186 and EN 12467 certification databases, EPA TSCA Title VI regulatory filings, and ECHA REACH restriction timelines, complemented by interviews with plant managers at fiber cement manufacturing facilities, procurement leads at multi-family developers, distribution channel partners in southeastern hurricane zones, and technical R&D directors overseeing silica reformulation programs. Secondary validation drew from customs trade data, SEC 10-K disclosures of building materials conglomerates, and construction permit databases in Florida and Texas coastal counties. Bottom-up volume estimates triangulated against top-down addressable market sizing.
Cross-referencing historical shipment patterns against panel input from contractor training program directors and prefabricated panel system engineers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product performance grade, end-use construction type, thickness specification, and application channel. CAGRs derived from elasticity-adjusted demand curves incorporating code adoption timelines and renovation cycle replacement rates. Forecast inputs integrated hurricane-resistant building code enforcement density and silica exposure limit compliance cost curves.
Regulatory enforcement delays, Portland cement price spikes, and certified installer network expansion bottlenecks are the dominant revision risks that could compress or extend projected trajectories. Forecasts reflect assumptions around ECHA reformulation timelines and EPA formaldehyde standard displacement rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Acoustic Damping Tiles Market
Building Materials
United Kingdom White Cement Market
Building Materials
Brick Adhesive Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Global Facade Market
Building Materials
Dutch Brick Market
Building Materials
Cellular Concrete Market
Building Materials
Latin America Facade Market
Building Materials
Basalt Rock Market
Building Materials
LAMEA Engineered Stone Market
Building Materials
South Africa White Cement Market
Building Materials
Europe Fiber Cement Market
Building Materials
Europe Concealed Cistern Market
Building Materials
China Aluminum Door and Window Market
Building Materials
East Africa White Cement Market
Building Materials
Zinc Polycarboxylate Cement Market