
 Fiber Cement Market | 2026-2036
Fiber Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Cement Market Analysis
Wood and vinyl siding is restructuring competitive economics across exterior cladding as fiber cement gains specification share on durability and insurance-premium reductions. James Hardie Building Products Inc. dominates North American production capacity with vertically integrated fiber sourcing and pigment operations. Etex Group leverages European manufacturing scale to supply fire-rated panels meeting stringent facade codes. Nichiha Corporation anchors Asian demand through specialized architectural panels targeting commercial facades.
Fiber cement comprises a composite of Portland cement, cellulose fibers, silica sand, and additives formed under high-pressure steam curing into dimensionally stable boards and sheets. The material delivers Class A fire ratings, moisture resistance, and dimensional stability across temperature extremes from minus forty to one hundred eighty degrees Fahrenheit, serving primarily as exterior cladding, roofing underlayment, and interior wet-area sheathing. Siding occupies the largest value pool in residential new construction and reroofing cycles, while panels command premium pricing in commercial facade applications where fire ratings and design flexibility intersect. Exterior cladding applications outpace interior walls on code-driven replacement cycles and insurance-industry preference for non-combustible assemblies.
EPA emissions standards for fiber-cement manufacturing shape kiln technology investment and plant siting decisions across the United States. California Building Standards Code Title 24 and Australia's National Construction Code mandate non-combustible exterior materials in designated fire zones, directly expanding addressable demand. Stakeholders must monitor evolving wildfire-risk maps and corresponding code adoptions to anticipate regional demand inflections and capacity placement.
Market Dynamics
Code-driven specification of non-combustible exterior cladding is restructuring competitive positioning across residential and commercial construction, as insurance underwriters and municipal building departments elevate fiber cement above combustible alternatives in high-risk zones.
Growth Catalysts
- California Title 24 wildland-urban interface mandates:Non-combustible exterior material requirements in designated fire zones directly expand specification volume for fiber cement siding and panels.
- Hurricane-prone coastal residential construction:Moisture resistance and wind-load performance drive builder preference over vinyl and wood in southeastern United States new construction cycles.
- Australia's National Construction Code fire-rated facade standards:Stringent combustibility ratings for mid-rise and high-rise exteriors accelerate fiber cement panel adoption in commercial and multi-family segments.
Market Restraints
- Cellulose fiber input cost volatility:Pulp price fluctuations and forestry supply constraints compress manufacturing margins and complicate long-term contract pricing.
- Capital-intensive autoclave curing infrastructure:High-pressure steam curing systems require substantial upfront investment, limiting new entrant capacity expansion.
- Silica dust exposure regulations:OSHA respirable crystalline silica standards impose costly ventilation and PPE compliance burdens across cutting and fabrication operations.
Strategic Opportunities
- India's affordable housing and infrastructure build-out:Durability requirements in monsoon-prone regions create addressable demand for moisture-resistant exterior cladding alternatives to conventional materials.
- Prefabricated panel system integration:Offsite construction methods favor dimensionally stable, fire-rated facade components that reduce field labor and inspection cycles.
- EU Green Deal embodied carbon disclosure requirements:Extended service life and lower replacement frequency position fiber cement favorably against shorter-lifecycle alternatives in environmental product declarations.
Industry Challenges
- Skilled installer shortage for specialized cutting equipment:Dust-suppression saw systems and proper fastening techniques require trained labor pools that remain underdeveloped in emerging demand regions.
- Legacy vinyl and wood siding incumbent relationships:Established distribution channels and contractor familiarity with alternative materials create switching friction in reroofing and renovation cycles.
- Multi-jurisdictional fire-rating certification complexity:Divergent testing protocols across ASTM, EN, and local standards extend product approval timelines and increase compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Cement Market |
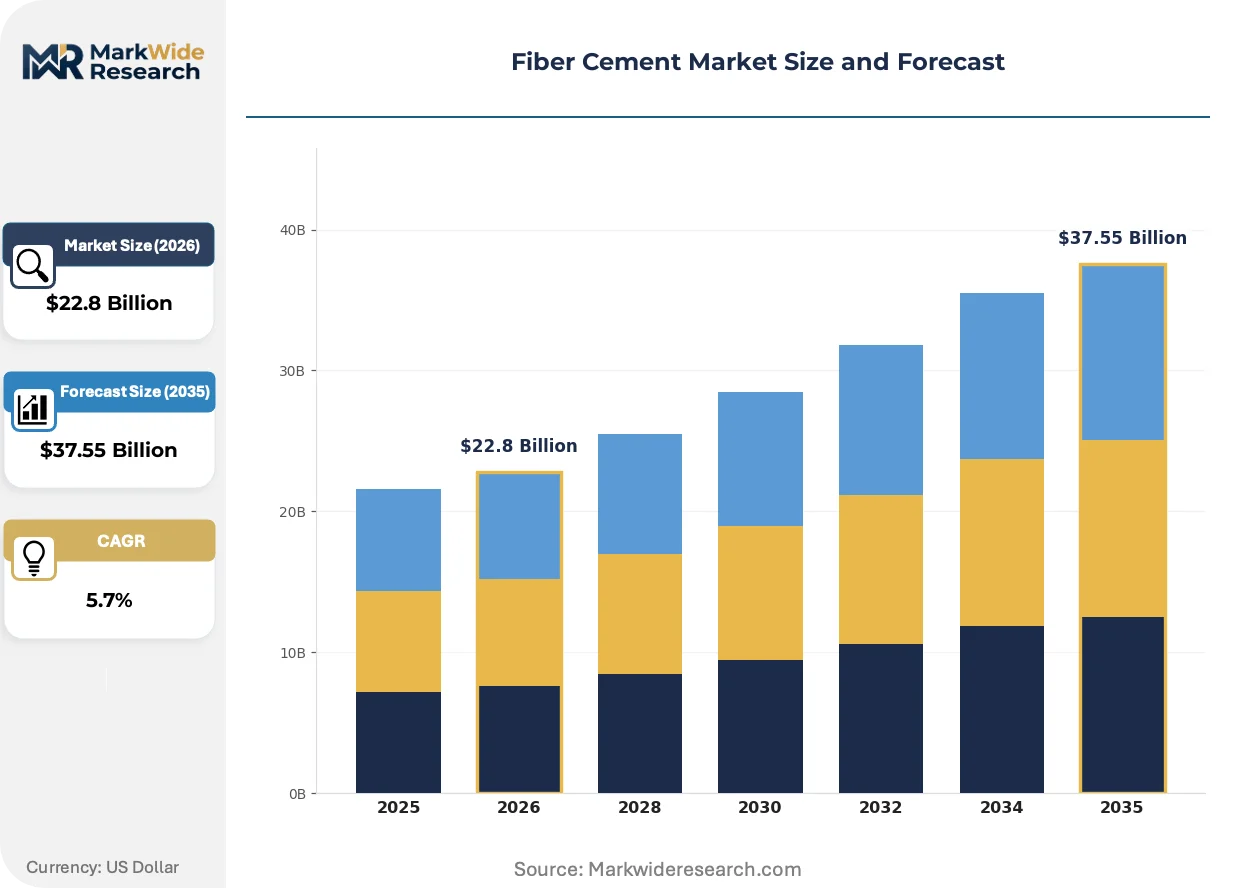
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $37.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Siding, Roofing, Panels, Flooring End User: Residential Construction, Commercial Construction, Infrastructure, Renovation Application: Exterior Cladding, Interior Walls, Decking, Ceilings Distribution Channel: Direct Sales, Retail, Distributors, Online Sales |
| Companies Covered | CSR Limited, Allura, James Hardie Building Products Inc., Nichiha Corporation, SCG International Corporation, Etex Group, GAF Materials Corporation, American Fiber Cement Corporation, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Cement Market Emerging Trajectories
Material science advances and digital specification tools are compressing design-to-installation cycles while expanding fiber cement's addressable application set beyond traditional residential siding.
Pre-finished color-through fiber cement formulations are decentralizing the regional paint-and-coat value chain by embedding pigment during high-pressure steam curing rather than post-manufacture field application. Large-scale residential developers and multi-family builders in the United States are specifying factory-finished systems to compress construction schedules and eliminate on-site painting subcontractor coordination. This shift is decentralizing regional paint contractor networks and capturing margin that previously flowed to field-applied coating services.
REACH restrictions on hazardous substance content in construction materials are tightening permissible additive chemistries in European fiber cement production, driving reformulation investments across Etex Group and continental manufacturers. The regulatory pressure is accelerating substitution of traditional process aids with bio-based alternatives and tightening supply chain documentation requirements for silica and cellulose sourcing. Panel products destined for EU commercial facade applications bear the most significant compliance burden, with certification timelines extending six to twelve months for new formulations.
Builder procurement patterns are fragmenting across direct manufacturer relationships, national distributor networks, and pro-contractor retail channels, with specification influence shifting toward regional production homebuilders with centralized material sourcing authority. Large production builders in the southeastern United States are consolidating purchases through direct mill agreements that bypass traditional two-step distribution, compressing channel margins and favoring manufacturers with vertically integrated pigment and fiber operations. This concentration of buying power is most visible in Florida and Texas metropolitan markets where annual housing starts exceed fifty thousand units and material standardization delivers logistics efficiencies.
Fiber Cement Market Segmentation
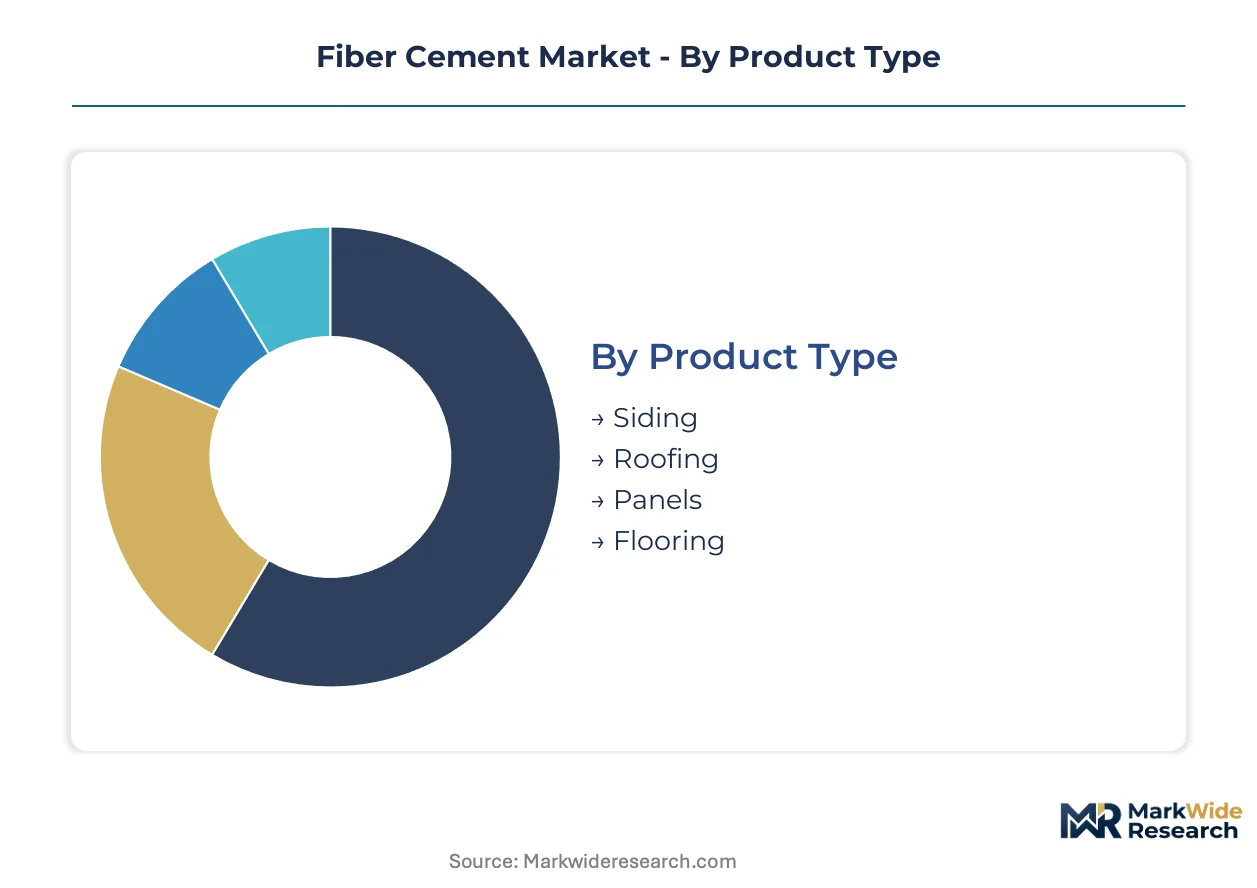
Fiber cement's composite chemistry enables specification across structurally distinct use cases, from hurricane-rated residential envelopes to fire-resistant commercial facades. Segmentation reveals how formulation and curing variations align product forms with divergent performance requirements and channel economics.
Product Type:
Volume concentration sits with siding, while panels capture premium pricing through architectural specification and code-driven fire ratings.
- Siding:Formed as lap boards and shingles through high-pressure steam curing, this segment dominates residential new construction and reroofing cycles. Demand concentrates in Florida, Texas, and California where moisture resistance, termite immunity, and Class A fire ratings displace vinyl and wood alternatives. Builder procurement consolidation through direct mill agreements compresses channel margins and rewards vertically integrated manufacturers with captive fiber and pigment operations.
- Panels:Large-format boards serve commercial facades and multi-family mid-rise construction where ASTM E84 and EN 13501-1 fire ratings intersect with design flexibility. Australia's National Construction Code and California Title 24 wildland-urban interface mandates directly expand specification volume, with certification timelines extending six to twelve months for new formulations entering EU markets under REACH restrictions.
- Roofing:Underlayment and shingle alternatives leverage dimensional stability across temperature extremes from minus forty to one hundred eighty degrees Fahrenheit.
- Flooring:Specialized formulations target wet-area sheathing in bathrooms and utility spaces where moisture resistance supersedes traditional subfloor materials.
Today's leader: Siding. Tomorrow's challenger: Panels.
End User:
Application maturity runs from established residential replacement cycles to emerging infrastructure durability specifications.
- Residential Construction:Single-family and multi-family new builds specify fiber cement for exterior cladding in hurricane-prone coastal zones and wildland-urban interface fire zones. Southeastern United States production builders consolidate purchases through direct manufacturer relationships, bypassing traditional two-step distribution.
- Commercial Construction:Mid-rise offices, healthcare facilities, and educational buildings specify fire-rated panels meeting stringent facade codes. Australia's National Construction Code and California Building Standards Code Title 24 mandate non-combustible exterior materials, directly expanding addressable demand.
- Infrastructure:Transportation hubs, utility buildings, and public works projects specify fiber cement for durability in high-traffic and exposed environments.
- Renovation:Reroofing and recladding cycles replace legacy vinyl and wood siding, though incumbent contractor relationships and distribution channel familiarity create switching friction.
Residential construction anchors current volume. Commercial construction offers the steepest expansion trajectory as fire codes tighten across multiple jurisdictions.
Application:
Exterior exposure commands premium specification against interior utility applications, with code cycles driving replacement frequency.
- Exterior Cladding:Primary value pool serving as rainscreen, siding, and facade systems. Insurance underwriters and municipal building departments elevate fiber cement above combustible alternatives in high-risk zones, accelerating code-driven replacement cycles.
- Interior Walls:Wet-area sheathing in bathrooms, kitchens, and utility spaces leverages moisture resistance and dimensional stability. Lower specification frequency and less stringent code drivers compress margins relative to exterior applications.
- Decking:Specialized formulations target elevated outdoor platforms requiring rot resistance and load-bearing capacity.
- Ceilings:Architectural panels serve commercial and institutional interior spaces where fire ratings and acoustic properties intersect.
Exterior cladding captures dominant value share. Interior walls expand most quickly as moisture-resistant alternatives penetrate residential wet-area specification.
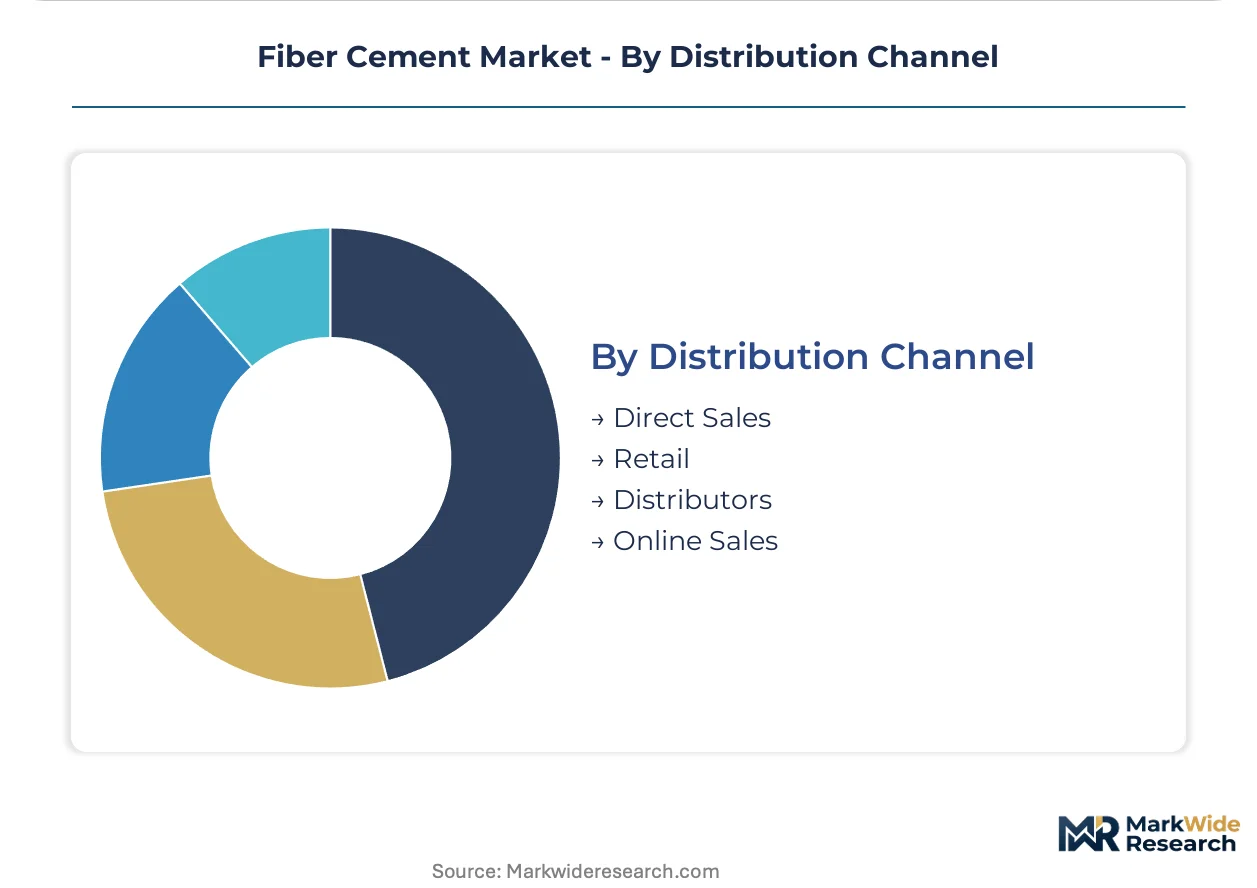
Distribution Channel:
Channel power is fragmenting as large production builders consolidate procurement authority and bypass traditional intermediaries.
- Direct Sales:National and regional production builders in Florida, Texas, and California metropolitan markets execute direct mill agreements for annual housing starts exceeding fifty thousand units. Material standardization delivers logistics efficiencies and compresses channel margins for manufacturers with vertically integrated operations.
- Distributors:Two-step distribution through building material wholesalers serves smaller regional builders and specialty contractors. This channel retains influence in renovation cycles and markets without concentrated production builder presence.
- Retail:Pro-contractor lumberyards and home improvement centers capture repair-and-remodel demand and smaller residential projects.
- Online Sales:Digital specification tools and direct-to-contractor platforms are compressing design-to-installation cycles, particularly for pre-finished color-through formulations.
Direct sales command the largest volume flows. Online sales are gaining share fastest as procurement digitization accelerates specification efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern United States manufacturing corridor anchors global fiber cement production capacity, with clustered autoclave facilities serving Atlantic and Gulf Coast construction markets. Regulatory divergence across fire-prone and hurricane-exposed geographies reshapes regional demand patterns and capacity placement decisions.
United States
Florida and Texas metropolitan markets drive specification volume through production builder procurement consolidation. California Building Standards Code Title 24 mandates non-combustible exterior materials in wildland-urban interface zones, directly expanding addressable demand. The Atlanta-Charlotte corridor hosts concentrated manufacturing capacity serving southeastern residential construction cycles.
Australia
National Construction Code fire-rated facade standards accelerate fiber cement panel adoption in mid-rise commercial and multi-family segments. Stringent combustibility ratings for high-rise exteriors create specification pull from Sydney and Melbourne development corridors. Brisbane-Gold Coast construction activity concentrates demand for moisture-resistant cladding in subtropical conditions.
China
GB standards for building materials and dual carbon goals reshape exterior cladding specifications in high-density urban development. Yangtze River Delta and Pearl River Delta construction markets absorb large-format panel production for commercial facade applications. Shanghai municipal building codes increasingly reference fire-performance ratings in high-rise residential envelopes.
Germany
EU Green Deal embodied carbon disclosure requirements position extended-service-life materials favorably in environmental product declarations. REACH restrictions on hazardous substance content drive reformulation investments across continental manufacturers. The Rhine-Ruhr industrial region maintains specialized production for fire-rated architectural panels serving Benelux and French export markets.
India
Affordable housing and infrastructure build-out creates addressable demand for moisture-resistant exterior cladding in monsoon-prone regions. BIS certification requirements for construction materials shape product approval timelines for imported and domestic manufacturers. Mumbai-Pune and Bengaluru-Chennai corridors concentrate commercial construction activity driving panel specification.
Fiber Cement Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and code-certification depth, producing a tiered structure where vertically integrated fiber and pigment operations confer logistics advantages. Market concentration sits with North American and European producers holding dominant shares in their home jurisdictions. Two archetypes define competitive positioning: integrated building materials conglomerates with captive raw material sourcing, and specialized cladding fabricators focused on architectural specification. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing direct mill agreements with large production builders to bypass traditional distribution.
Among Asia-Pacific headquartered manufacturers, Nichiha Corporation and SCG International Corporation exemplify the regional champion archetype, anchoring demand in specialized architectural panels and Southeast Asian construction markets respectively. James Hardie Building Products Inc. occupies a position as the North American volume leader, with Etex Group representing the European integrated conglomerate model. These three named entities collectively illustrate how geographic origin and corporate structure map to distinct strategic postures across the competitive landscape.
| Leading Market Players |
|---|
| CSR Limited |
| Allura |
| James Hardie Building Products Inc. |
| Nichiha Corporation |
| SCG International Corporation |
| Etex Group |
| GAF Materials Corporation |
| American Fiber Cement Corporation |
| Saint-Gobain |
| Others |
Supply Flow & Price Mechanics
Production homebuilders in Florida and Texas metropolitan markets command pricing leverage through direct mill agreements that bypass traditional two-step distribution. This procurement concentration rewards manufacturers with captive cellulose fiber and pigment operations while compressing margins for intermediaries.
Pricing Analysis
Cellulose fiber input cost pass-through dominates contract negotiations, with pulp price volatility from forestry supply constraints compressing manufacturing margins. Pricing stratifies across premium, standard, and economy tiers based on fire-rating certification level and volume scale commitments. Cost compression in standard-grade siding is intensifying because of builder procurement consolidation. Small regional contractors exhibit highest price sensitivity, while national production builders with standardized specifications show lowest sensitivity due to logistics efficiency gains.
Supply Chain Analysis
Skilled autoclave operator availability constrains capacity expansion in the southeastern United States manufacturing corridor. Supply concentrates in the United States, Australia, and Germany, with raw material sourcing drawing from Canadian pulp forests, domestic silica sand deposits, and European additive suppliers. Single-source vulnerability sits with cellulose fiber supply from concentrated forestry regions. Distribution runs through direct manufacturer relationships for large builders, two-step wholesalers for regional contractors, and pro-contractor retail for repair-and-remodel demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber cement market represents a late-cycle quality story as code-driven replacement cycles shift demand toward Class A fire-rated and pre-finished premium specifications. This specification upgrade path favors manufacturers with vertically integrated operations and certification depth.
For Market Incumbents: To counter cellulose fiber cost volatility and skilled installer shortages, secure captive pulp supply through backward integration into forestry assets or long-term offtake agreements with Canadian suppliers. Expand certified installer training programs in emerging demand regions to preempt labor bottlenecks. For New Entrants and Emerging Players: Capture specification share in India's monsoon-prone affordable housing corridor and EU Green Deal-driven renovation cycles by positioning moisture-resistant panels with embodied carbon advantages. Target direct relationships with modular construction integrators seeking fire-rated facade components for offsite assembly. For Investors and Strategic Acquirers: Building materials conglomerates with captive raw material sourcing are the most active acquirer in this space, seeking regional champions with code-certification depth in fire-prone jurisdictions. Monitor wildfire-risk map revisions and corresponding code adoptions as the signal to watch for regional demand inflections.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Fiber Supply | Captive pulp sourcing from Canadian forestry regions insulates margin compression from commodity volatility. |
| Pre-finished Color-Through Capacity Expansion | Factory-cured pigment systems capture margin from field-applied coating services in Florida and Texas markets. |
| Fire-Rating Certification Investment | ASTM E84 and EN 13501-1 approvals unlock California Title 24 and Australia National Construction Code specification volume. |
| Modular Construction Partnership | Dimensionally stable panel supply agreements with offsite fabricators reduce field labor and inspection cycles. |
| Installer Training Program Deployment | Dust-suppression saw certification builds qualified labor pools in underpenetrated Southeast Asian and Indian markets. |
Methodological Framework
Direct dialogue with plant managers at autoclave facilities, procurement leads at national production builders, distribution channel partners, and technical R&D directors at formulation laboratories grounded qualitative findings. Secondary validation drew from EPA emissions filings, California Building Standards Code documentation, Australian National Construction Code amendments, and customs trade data for cellulose fiber imports. Bottom-up volume modeling triangulated against top-down construction starts data across the analysis window.
Segment-level projections incorporated product type, end-user vertical, application exposure, and distribution channel dynamics throughout the forecast period. CAGRs derived from regression analysis against housing starts, code adoption timelines, and insurance industry loss data. Modeled inputs included wildfire-risk map expansion rates, hurricane frequency indices, and pulp futures pricing curves.
Regulatory code delays, cellulose fiber supply disruptions, and installer labor pool development shortfalls are the dominant revision risks to modeled outputs. Material deviation in these named triggers warrants pause and re-evaluation of capacity placement and pricing assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Block Paving Market
Building Materials
Plaster Accelerator Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Global Pozzolan Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
Rubbing Bricks Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Europe Cement Market
Building Materials
India Cement Market
Building Materials
Timber Frames Market
Building Materials
Construction Materials Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Italy Facade Market
Building Materials
Roofing and Insulation Market