
 Steel Sandwich Panels Market | 2026-2036
Steel Sandwich Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Sandwich Panels Market Analysis
Cold storage operators is rotating toward higher-specification insulated panels as e-commerce grocery fulfillment drives demand for temperature-controlled warehousing. Kingspan Group leverages its polyurethane core technology leadership to capture premium specifications in European refrigerated builds. ArcelorMittal anchors supply through captive steel production and integrated panel fabrication across multiple continents. Tata Steel competes on cost-efficient mineral wool solutions for industrial roofing in South Asian manufacturing zones.
Steel sandwich panels consist of two metallic face sheets bonded to a lightweight core material, typically achieving thermal conductivity values between 0.020 and 0.040 W/m·K depending on core composition and thickness. These composite assemblies serve primarily as structural envelope elements where strength-to-weight ratio, thermal insulation, and rapid installation converge in commercial and industrial construction. Insulated panels dominate value capture due to stringent energy codes, while fire-resistant variants command margin premiums in high-occupancy and hazardous-material facilities. Refrigerated building applications represent the fastest-expanding demand pool as cold chain infrastructure multiplies across food and pharmaceutical distribution networks.
The EU Green Deal and REACH frameworks tighten material content and end-of-life recovery obligations for construction composites across European markets. EMA and national health regulators in Germany, France, and Italy impose fire-safety classifications that directly determine product eligibility for public infrastructure and healthcare facility contracts. China's MEE enforces dual carbon goals that elevate low-emission steel and recycled core materials in building procurement guidelines. Stakeholders must monitor evolving carbon border adjustments and core material substitution trajectories to preserve qualification for publicly funded construction programs.
Market Dynamics
The EU Green Deal's building energy performance standards are compressing thermal envelope specifications across member states, forcing panel fabricators to upgrade core formulations and certification portfolios or exit publicly funded construction programs.
Growth Catalysts
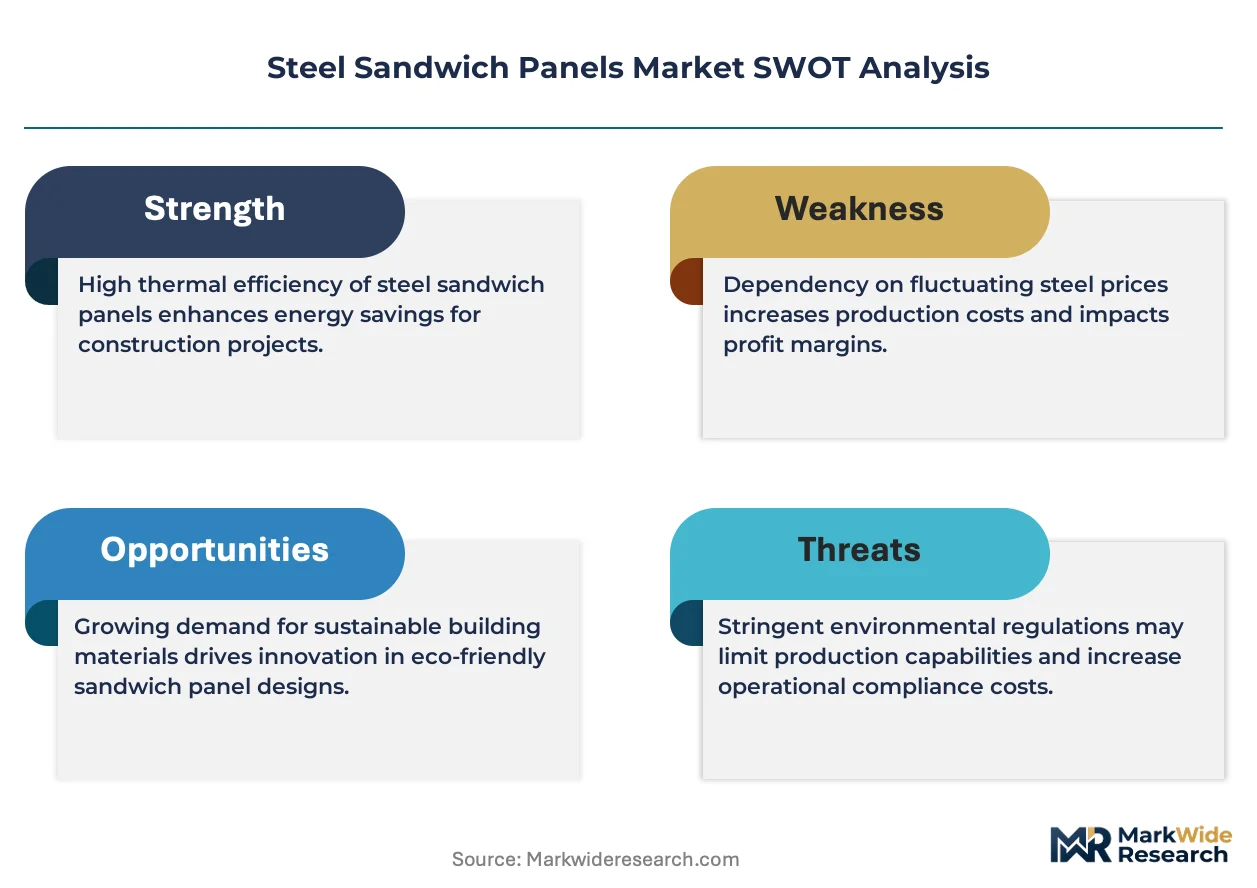
- REACH framework compliance:End-of-life recovery obligations for construction composites in European markets are accelerating demand for recyclable core materials and closed-loop fabrication processes.
- Cold chain infrastructure:E-commerce grocery fulfillment networks are expanding temperature-controlled warehousing requirements, pulling higher-specification insulated panels into refrigerated build specifications.
- Industrial corridor concentration:Germany's warehouse construction and food processing infrastructure investments are creating procurement pull for fire-rated and thermally efficient envelope systems.
Market Restraints
- Steel input volatility:ArcelorMittal and Tata Steel captive production advantages create cost asymmetry for non-integrated fabricators dependent on spot steel markets.
- Core material substitution limits:Polyurethane and mineral wool thermal performance gaps restrict specification flexibility in sub-zero refrigeration applications.
- Fire-safety classification friction:EMA and national health regulators in Germany, France, and Italy impose divergent testing protocols that fragment product eligibility across adjacent markets.
Strategic Opportunities
- Carbon border adjustment positioning:China's MEE dual carbon goals and procurement guidelines favor low-emission steel and recycled core materials, creating qualification premiums for early adopters.
- Pharmaceutical distribution expansion:Vaccine and biologics cold chains are extending into secondary cities, opening specification opportunities for validated panel systems with enhanced thermal monitoring integration.
- Modular construction channel:Offsite fabrication contractors are consolidating envelope procurement, creating direct specification relationships that bypass traditional distributor networks.
Industry Challenges
- Fire-safety certification timelines:Extended testing protocols for reaction-to-fire classifications delay product launches and lock fabricators out of time-sensitive infrastructure tenders.
- Core-to-facing bond durability:Adhesive formulation failures in high-humidity environments create warranty exposure and reputation risk for panel assemblers without captive R&D facilities.
- Installation skill scarcity:Thermal bridge-free detailing and vapor barrier continuity require specialized contractor training that outpaces workforce development in emerging construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Sandwich Panels Market |
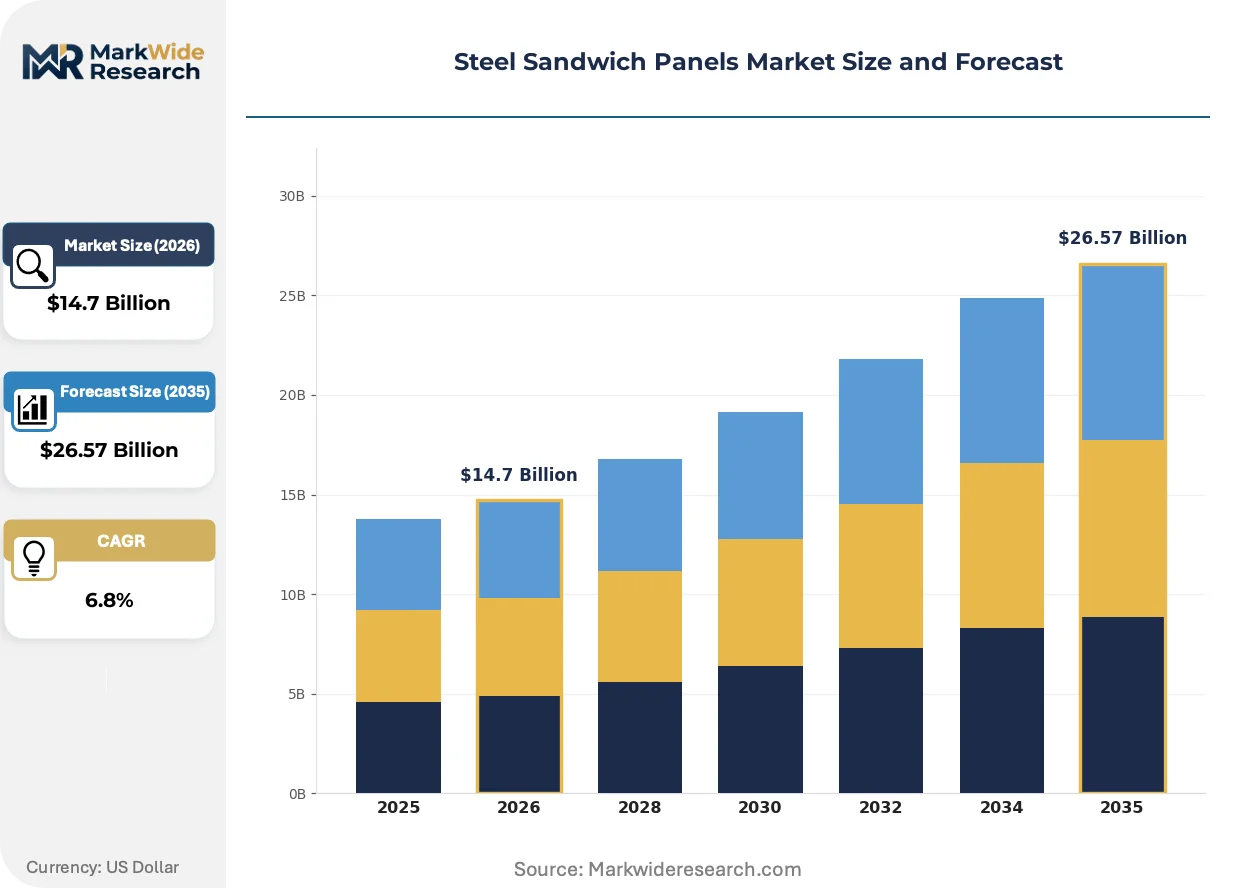
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Panels, Non-Insulated Panels, Fire-Resistant Panels, Acoustic Panels Application: Walls, Roofs, Ceilings, Refrigerated Buildings End User: Construction, Cold Storage, Automotive, Aerospace Core Material: Polyurethane, Polystyrene, Mineral Wool, Others |
| Companies Covered | Kingspan Group, ArcelorMittal, Tata Steel, Nucor Corporation, Metecno, Assan Panel, Isopan, NCI Building Systems, Cornerstone Building Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Sandwich Panels Market Emerging Trajectories
Refrigerated building specifications are fragmenting across performance tiers as end-users balance capital constraints against tightening energy codes and insurance-driven fire-safety requirements.
Vacuum-insulated panel technology is fragmenting traditional polyurethane-dominated specifications in ultra-low-temperature applications. Pharmaceutical cold chain operators in Switzerland and the Netherlands are piloting VIP-cored sandwich assemblies for compact distribution hubs. This diffusion is compressing viable specification windows for conventional high-density foam cores in premium refrigerated builds.
REACH and the EU Green Deal are tightening material content declarations and mandating recycled steel thresholds in public procurement. Panel fabricators serving German and French infrastructure contracts must now document core material provenance and end-of-life recovery pathways. Mineral wool and bio-based alternatives are capturing specification share in projects targeting net-zero operational carbon.
Buyer consolidation among cold storage facility operators is compressing specification cycles and unbundling after-sales service from initial panel supply. Large European logistics REITs are centralizing envelope procurement through framework agreements with direct fabrication access. This concentration is marginalizing regional distributors and forcing mid-tier panel assemblers to demonstrate installation capability or exit the specification chain.
Steel Sandwich Panels Market Segmentation
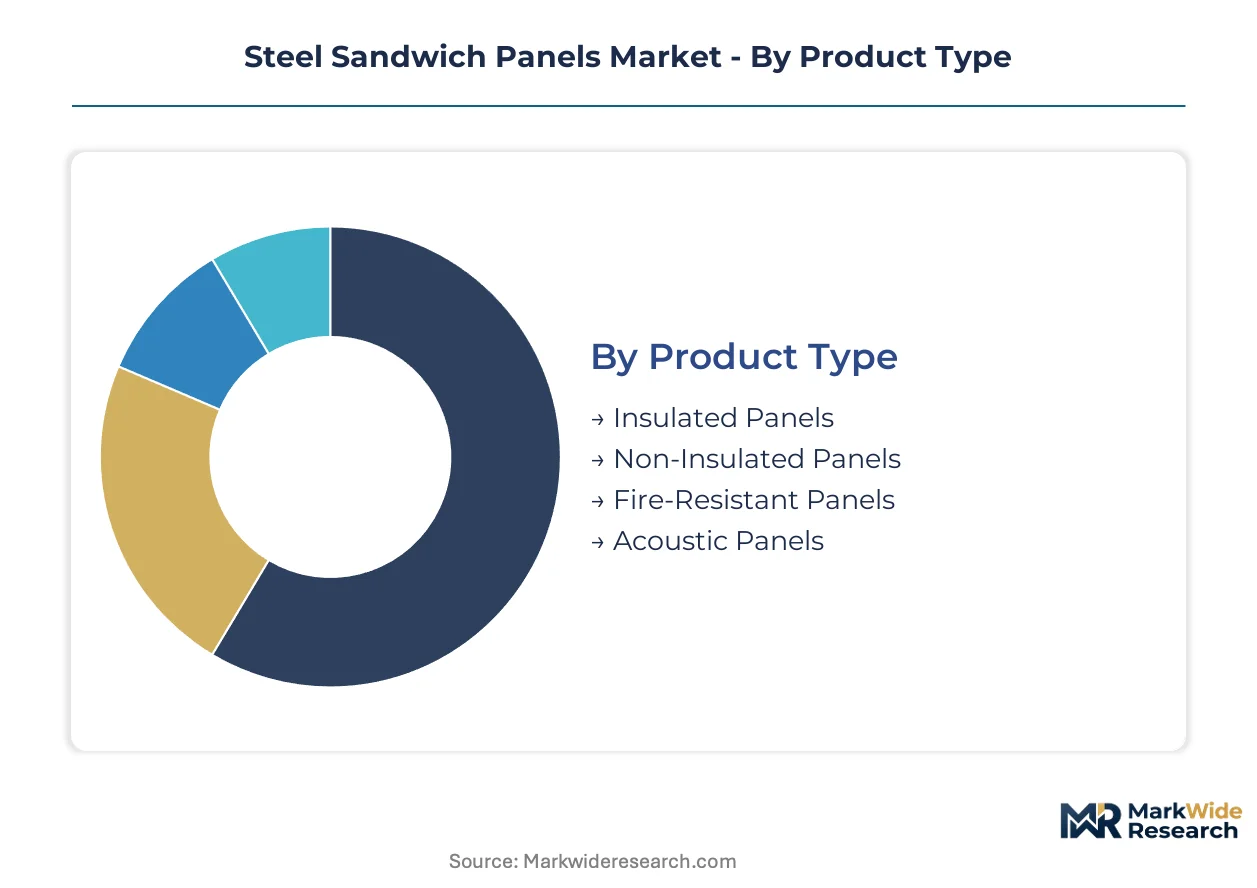
Steel sandwich panel segmentation reflects divergent thermal, acoustic, and fire-safety certification requirements across construction verticals. Specification trajectories separate energy-code-driven insulated demand from hazard-rated industrial applications with distinct regulatory compliance burdens.
Product Type:
REACH and EU Green Deal frameworks differentiate eligibility through thermal performance thresholds and end-of-life recovery documentation.
- Insulated Panels:Polyurethane and polystyrene cores bonded to steel facings deliver thermal conductivity values between 0.020 and 0.040 W/m·K. Germany's warehouse construction boom and France's cold storage expansion pull specification volume toward higher R-value assemblies meeting stringent envelope standards.
- Fire-Resistant Panels:Mineral wool or specially formulated cores achieve reaction-to-fire classifications required for healthcare facilities and hazardous material storage. Italy's national health regulator and Germany's KBA impose divergent testing protocols that fragment product eligibility across adjacent European markets.
- Non-Insulated Panels:Structural envelope elements without thermal cores serve cost-sensitive industrial roofing in South Asian manufacturing zones where energy codes remain permissive.
- Acoustic Panels:Damped core constructions address noise attenuation requirements for airport hangars and heavy machinery enclosures near urban boundaries.
Established volume favors Insulated Panels; emerging adoption favors Fire-Resistant Panels.
Application:
Installation complexity and thermal bridge risk create margin tiering across envelope positions.
- Refrigerated Buildings:Ultra-low-temperature specifications demand validated panel systems with integrated thermal monitoring for vaccine and biologics distribution. Swiss and Dutch pharmaceutical operators pilot vacuum-insulated panel technology for compact secondary-city hubs.
- Walls:Vertical envelope assemblies dominate volume through warehouse and food processing facility construction across Germany's industrial corridor.
- Roofs:Structural loading requirements and condensation risk drive specification toward thicker core assemblies with enhanced vapor barrier continuity.
- Ceilings:Interior partition applications concentrate in cleanroom and controlled-atmosphere manufacturing where acoustic and thermal performance converge.
Refrigerated Buildings climb the fastest; Walls retain the deepest specification base.
End User:
Procurement consolidation patterns separate framework-agreement buyers from spot-market purchasers.
- Cold Storage:E-commerce grocery fulfillment networks expand temperature-controlled warehousing requirements. Large European logistics REITs centralize envelope procurement, compressing specification cycles and unbundling after-sales service from initial supply.
- Construction:General commercial and industrial building applications dominate unit volume through standardized wall and roof specifications.
- Automotive:Paint shop enclosures and press line housings require fire-rated panels with oil-resistant surface treatments.
- Aerospace:Hangar and maintenance facility specifications prioritize wide-span roof capabilities and corrosion-resistant coatings.
Construction maintains the broadest installed base; Cold Storage gains share fastest through logistics infrastructure investment.
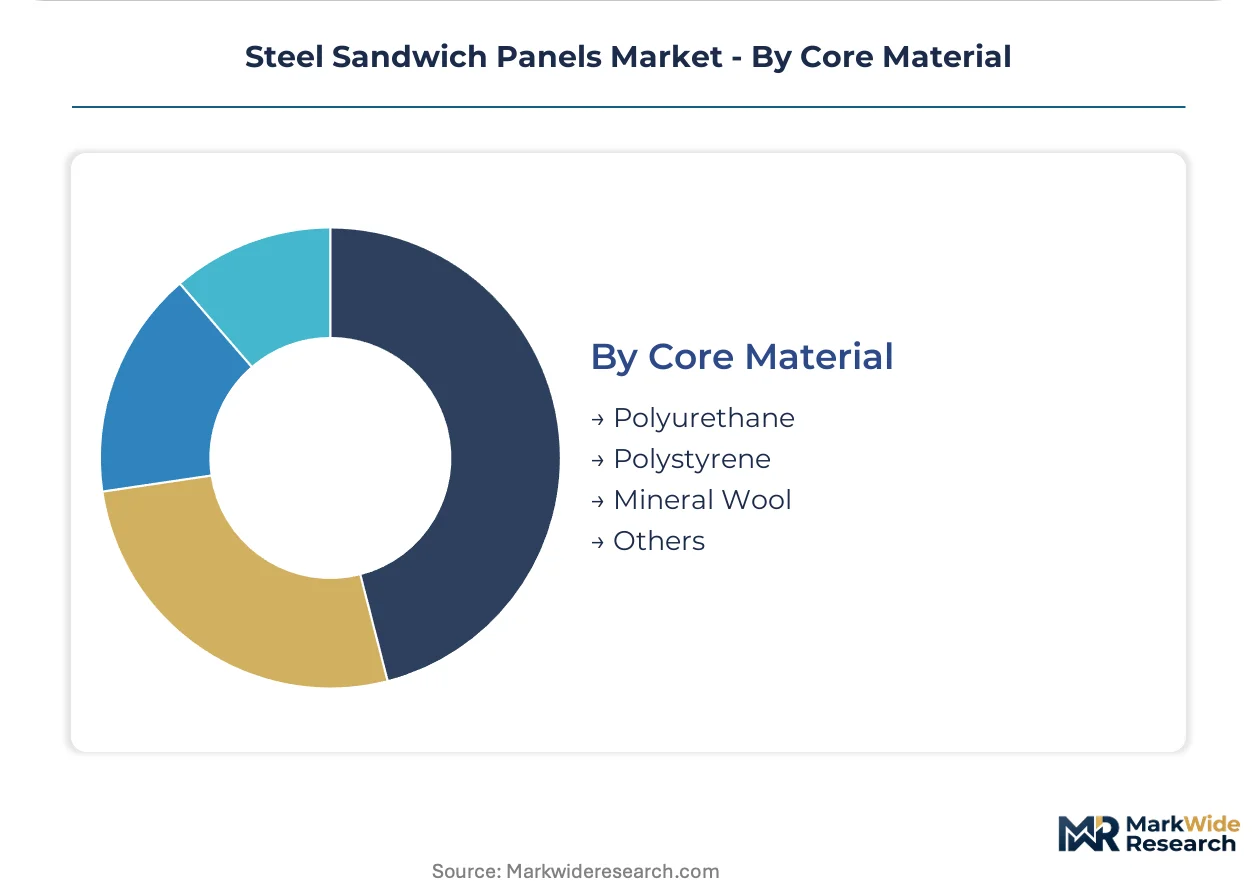
Core Material:
Carbon border adjustments and recycled content mandates reconfigure material qualification pathways.
- Polyurethane:Closed-cell foam chemistry achieves the lowest thermal conductivity values, anchoring premium refrigerated build specifications. China's MEE dual carbon goals elevate scrutiny of blowing agent emissions and core material provenance.
- Mineral Wool:Inorganic fiber cores command fire-safety premiums in high-occupancy and public infrastructure contracts across France and Italy.
- Polystyrene:Cost-efficient expanded and extruded formulations serve standard industrial roofing where thermal performance requirements permit higher conductivity values.
- Others:Bio-based alternatives and emerging vacuum-insulated panel technology capture specification share in net-zero carbon targeting projects.
Polyurethane dominates refrigerated applications; mineral wool expands fastest through fire-code tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators supply insulated steel sandwich panels to cold storage operators across France and the Netherlands, while Chinese producers export mineral wool-cored assemblies to Southeast Asian manufacturing zones. Trade corridors concentrate premium refrigerated specifications in Northern Europe and cost-optimized roofing systems in South Asia.
Germany
Warehouse construction and food processing infrastructure investments pull procurement volume toward fire-rated and thermally efficient envelope systems. The KBA imposes reaction-to-fire classifications that determine product eligibility for public infrastructure contracts. The industrial corridor spanning North Rhine-Westphalia and Lower Saxony hosts accelerated cold storage facility development.
France
Cold storage expansion drives specification volume toward higher R-value assemblies meeting stringent envelope standards. ANSM and national health regulators impose fire-safety classifications that directly determine healthcare facility contract eligibility. The Île-de-France region concentrates pharmaceutical distribution hub construction with validated panel requirements.
China
Dual carbon goals elevate scrutiny of blowing agent emissions and core material provenance in building procurement guidelines. The MEE enforces low-emission steel and recycled core material thresholds across publicly funded construction programs. The Yangtze River Delta cluster anchors domestic panel fabrication for regional cold chain infrastructure.
United States
E-commerce grocery fulfillment networks expand temperature-controlled warehousing requirements across secondary distribution markets. The EPA and OSHA maintain workplace safety and environmental compliance frameworks affecting panel installation and material handling. The Southeast region spanning Florida and Georgia hosts accelerated logistics facility construction.
India
Industrial roofing demand concentrates in South Asian manufacturing zones where energy codes remain permissive. BIS standards govern structural and fire-safety performance for construction composites in commercial applications. Gujarat and Maharashtra host cost-efficient mineral wool solution procurement for manufacturing facility envelopes.
Steel Sandwich Panels Market Vendor Landscape
Player mix skews toward integrated steel producers with captive panel fabrication capabilities and specialized insulation technology developers. Market structure tiers between premium specification leaders and cost-optimized regional fabricators. Two dominant strategic archetypes emerge: steel majors leveraging upstream raw material control, and insulation specialists commanding core formulation differentiation. Competitive moves center on backward integration into steel production and technology licensing for vacuum-insulated panel diffusion.
Within the integrated steel producer tier, ArcelorMittal and Tata Steel exemplify archetypes of upstream-controlled supply spanning multiple continents. Kingspan Group occupies a position representing polyurethane core technology leadership in European refrigerated builds. These three anchors illustrate the bifurcation between raw material security and specification premium capture.
| Leading Market Players |
|---|
| Kingspan Group |
| ArcelorMittal |
| Tata Steel |
| Nucor Corporation |
| Metecno |
| Assan Panel |
| Isopan |
| NCI Building Systems |
| Cornerstone Building Brands |
| Others |
Supply Flow & Price Mechanics
Long-term framework agreements with direct fabrication access lock in steel input pricing for cold storage operators expanding temperature-controlled warehousing across Germany and France. These contracts secure polyurethane core supply while compressing specification cycles for panel fabricators serving European logistics REITs.
Pricing Analysis
Conventional polyurethane-cored panels command premium positioning against mineral wool alternatives in refrigerated builds, while vacuum-insulated panel technology opens ultra-low-temperature pricing tiers for pharmaceutical distribution. Price differentiation separates fire-rated assemblies meeting KBA classifications from standard industrial roofing specifications. Cost compression in non-integrated fabricator tiers stems from ArcelorMittal and Tata Steel captive production advantages. Cold storage operators show lowest price sensitivity due to energy-code compliance mandates, while South Asian manufacturing zones drive economy-tier volume.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian mineral wool core distribution to Indian manufacturing zones. Steel supply concentrates in China, Germany, and India, with polyurethane chemistry anchored in European and Chinese production clusters. Raw material dependencies span coated steel coils, isocyanate blowing agents, and mineral wool fiber. Tariff exposure on Chinese steel inputs threatens cost structures for non-integrated panel assemblers. Distribution runs through offsite fabrication contractors consolidating envelope procurement and bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation capability and thermal monitoring integration represent faster-expanding revenue layers than hardware supply alone, as large European logistics REITs unbundle after-sales service from initial panel procurement.
For Market Incumbents: Compound specification share by deepening captive R&D facilities for adhesive formulation resilience in high-humidity environments. Secure backward integration into low-emission steel production to meet China's MEE dual carbon thresholds and preserve qualification for publicly funded construction programs. Vacuum-insulated panel technology licensing poses substitution threat requiring rapid core formulation response. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany and France unlocks healthcare facility contract eligibility fragmented by divergent national testing protocols. Target secondary-city pharmaceutical distribution hubs in Switzerland and the Netherlands piloting validated panel systems with enhanced thermal monitoring integration. Go-to-market leverage rests on modular construction channel relationships with offsite fabrication contractors. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier panel assemblers demonstrating installation capability or captive core technology differentiation rather than commodity roofing suppliers. Long-term viability favors fabricators with documented end-of-life recovery pathways under REACH framework compliance. Watch carbon border adjustment implementation timelines as inflection indicator for low-emission steel qualification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Production | ArcelorMittal's captive supply anchors cost asymmetry against spot-market-dependent fabricators. |
| Vacuum-Insulated Panel Technology Licensing | Swiss pharmaceutical operators pilot VIP-cored assemblies for compact secondary-city distribution hubs. |
| Fire-Safety Certification Investment | KBA and ANSM divergent protocols fragment product eligibility across adjacent European markets. |
| Modular Construction Channel Partnership | Offsite fabrication contractors consolidate envelope procurement and marginalize regional distributors. |
| End-of-Life Recovery Pathway Documentation | REACH compliance mandates recycled steel thresholds in German and French public infrastructure contracts. |
Methodological Framework
A standing panel of cold storage facility operators, thermal envelope specification engineers, logistics REIT procurement directors, and modular construction contractors provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Green Deal regulatory filings, ECHA REACH substance databases, German KBA technical approvals, and customs trade data on steel-coated product flows. Bottom-up project pipeline analysis triangulated against top-down construction spend forecasts across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, application, end user, and core material segmentation dimensions. CAGRs derived from modeled annual progression rates incorporated steel input cost trajectories, energy-code tightening schedules, and cold chain infrastructure investment patterns. Forecast inputs included e-commerce grocery fulfillment network expansion timelines and pharmaceutical distribution hub construction pipelines.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continued cold storage investment momentum; material deviation in carbon border adjustment implementation or core material substitution trajectories would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal building energy performance standards and REACH end-of-life recovery obligations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Door Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Europe Geogrids Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Global Roofing Market