
 Mineral Wool Ceiling Tiles Market | 2026-2036
Mineral Wool Ceiling Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Wool Ceiling Tiles Market Intelligence
China is reshaping supply dynamics through expanded mineral wool substrate capacity in Shandong and Hebei provinces. Saint-Gobain leverages its integrated glass wool supply chain to control raw material costs across European distribution networks. ROCKWOOL International anchors its position through specialized stone wool formulations that meet stringent Nordic fire-resistance certifications.
Mineral wool ceiling tiles are non-combustible panels manufactured from spun molten rock or slag fibers, typically bonded with phenolic resin and finished with painted or flocked surfaces for acoustic absorption coefficients up to 0.95 NRC. These installations primarily manage reverberation and thermal performance in commercial and institutional buildings where occupant comfort intersects with code-mandated safety thresholds. Acoustic tiles dominate volume flows in open-plan commercial offices where speech intelligibility standards drive specification, while fire-resistant tiles command premium positioning in high-rise egress corridors and atrium spaces. Suspended ceiling systems retain the largest installation share due to their compatibility with MEP integration and future accessibility requirements.
EPA emissions standards for formaldehyde-based binders and REACH restrictions on phenolic resin constituents are tightening formulation requirements across North American and European supply chains. China's GB 8624 classification system for building material combustibility creates parallel certification demands for exporters serving state-funded infrastructure projects. Stakeholders must monitor divergence between regional fire-test protocols and binder chemistry restrictions when configuring product platforms for multi-territory deployment.
Market Dynamics
Acoustic performance mandates embedded in building energy codes are compressing specification cycles for mineral wool ceiling tiles, forcing manufacturers to pre-certify products against evolving multi-jurisdictional fire and emissions standards before bidding on commercial projects.
Growth Catalysts
- Commercial office retrofits:Open-plan workspace redesigns in Germany and Poland are driving replacement demand for high-NRC ceiling systems that meet DIN 18041 speech intelligibility criteria.
- REACH phenolic resin compliance:Reformulated low-emission binders now qualify for LEED v4.1 and BREEAM credits, expanding specification eligibility in Nordic public procurement frameworks.
- Shandong-Hebei production clusters:Expanded substrate capacity in these Chinese provinces is redirecting export flows toward Middle East and Southeast Asian infrastructure projects.
Market Restraints
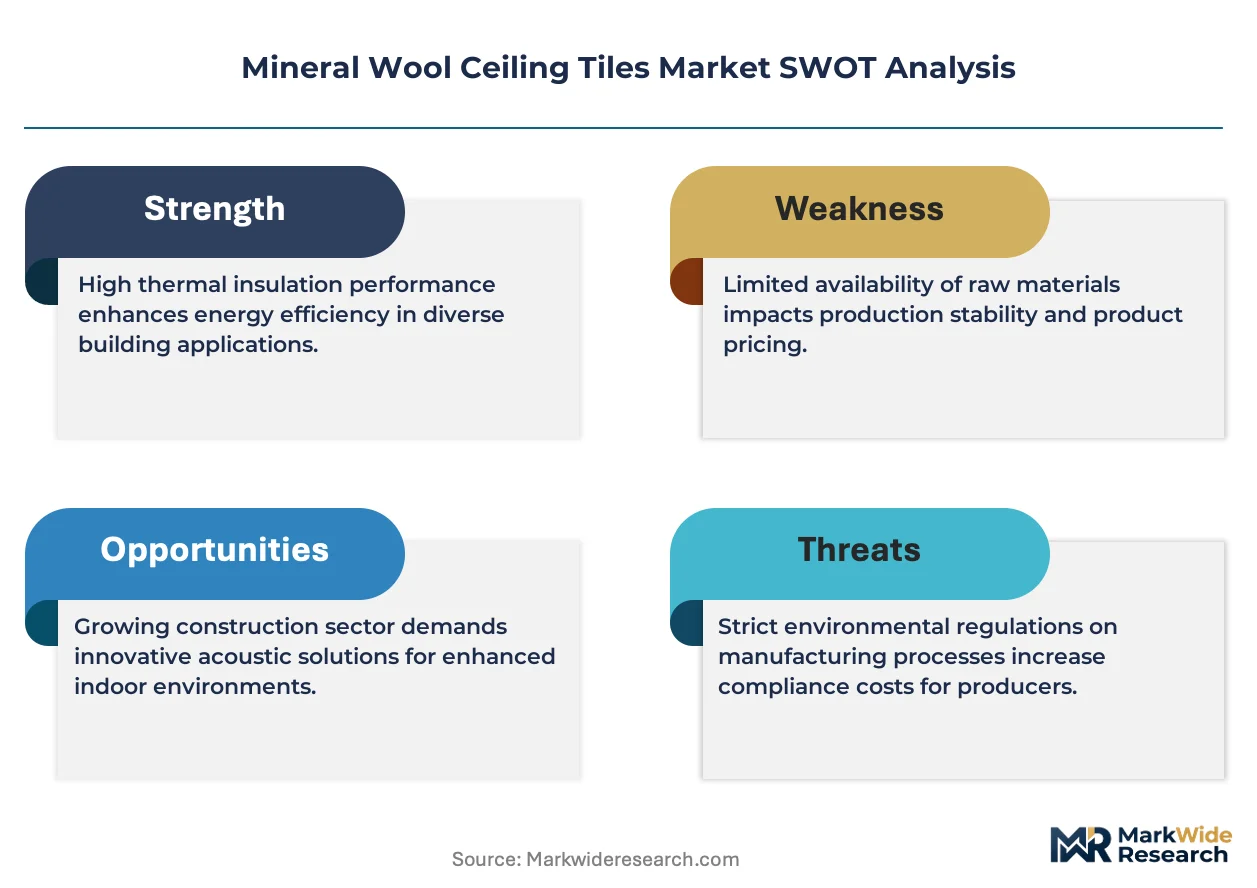
- Slag and basalt input volatility:Steel production fluctuations in blast furnace operations create irregular mineral wool feedstock availability and pricing instability.
- Single-region binder supply:Concentrated phenolic resin production in the US Gulf Coast exposes European and Asian manufacturers to freight cost spikes and force majeure disruptions.
- Gypsum board substitution:Improved acoustic gypsum formulations with integrated glass mat facings are capturing mid-market suspended ceiling specifications in cost-sensitive commercial segments.
Strategic Opportunities
- Healthcare renovation pipelines:Hospital HVAC modernization programs in France and Italy are specifying stone wool tiles with integrated antimicrobial surface treatments for infection control zones.
- EU Green Deal embodied carbon tracking:Environmental Product Declaration requirements for construction materials are creating first-mover advantage for manufacturers with verified lifecycle data.
- Direct-to-contractor digital platforms:B2B procurement portals are disintermediating traditional distribution layers for standardized acoustic tile SKUs in mid-size commercial fit-outs.
Industry Challenges
- Multi-protocol fire testing:Reconciling ASTM E84, EN 13501-1, and GB 8624 certification timelines strains R&D bandwidth and delays product launches by 8-14 months.
- Specialized installation labor:Precision cutting and MEP integration skills for complex atrium geometries face shortages in Polish and Romanian construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Wool Ceiling Tiles Market |
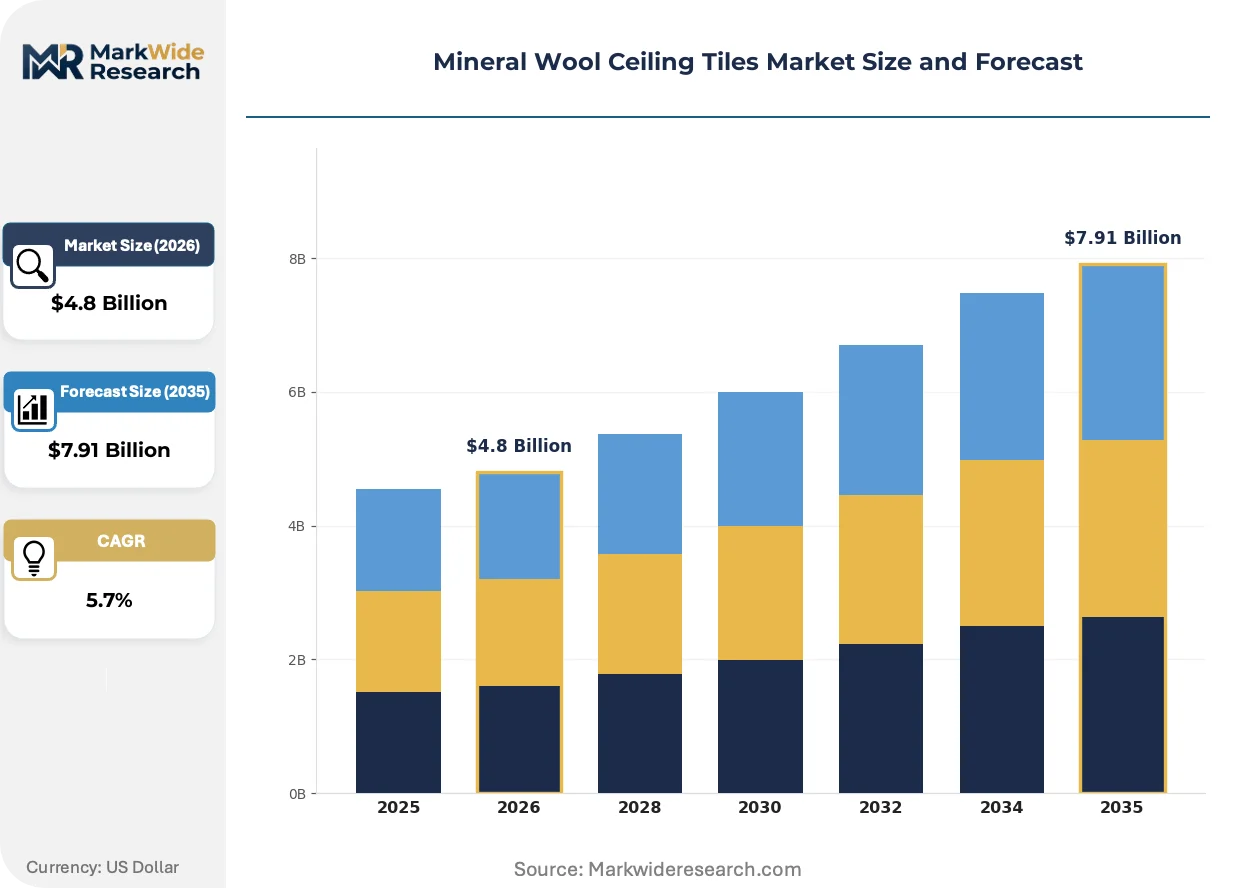
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Tiles, Fire-Resistant Tiles, Thermal Insulation, Decorative Tiles End User: Residential Buildings, Commercial Offices, Educational Institutions, Industrial Facilities Installation Type: Suspended Ceiling, Directly Applied, Mixed Installation, Modular Thickness: Thin Panels, Thick Panels, Standard Panels, Custom Thickness |
| Companies Covered | Saint-Gobain, AWI Licensing LLC, Armstrong World Industries, Owens Corning, Hunter Douglas, USG Corporation, Knauf, Johns Manville, ROCKWOOL International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Wool Ceiling Tiles Market Strategic Shifts & Innovations
Formulation chemistry and surface engineering are converging to produce ceiling tiles that simultaneously satisfy acoustic, fire, and air quality performance thresholds previously requiring layered system designs.
Bio-based binder technologies are migrating from pilot-scale demonstration to commercial production lines. These phenolic-alternative formulations derived from lignin and tannin extracts reduce formaldehyde emissions below EPA TSCA Title VI thresholds. Healthcare and education facility managers in California and New York are specifying these systems for occupied renovation projects. The technology is compressing the competitive window for conventional resin-dependent manufacturers who lack reformulation capabilities.
REACH restrictions on phenol and formaldehyde constituents are tightening batch testing protocols for imported mineral wool products. ECHA's 2023-2024 substance evaluation roadmap has added mineral wool fibers to the Community Rolling Action Plan, triggering additional toxicological data requirements. European distributors are now demanding full material disclosure documentation from Turkish and Chinese suppliers before customs clearance.
Facility managers are consolidating ceiling system specifications across multi-site portfolios to simplify maintenance inventory and reduce lifecycle costs. This standardization behavior favors manufacturers with broad geographic service networks and consistent product availability. The shift is most visible in US and UK retail and hospitality chains where capital project teams negotiate enterprise pricing agreements covering 50-200 location rollouts annually.
Mineral Wool Ceiling Tiles Market Segmentation
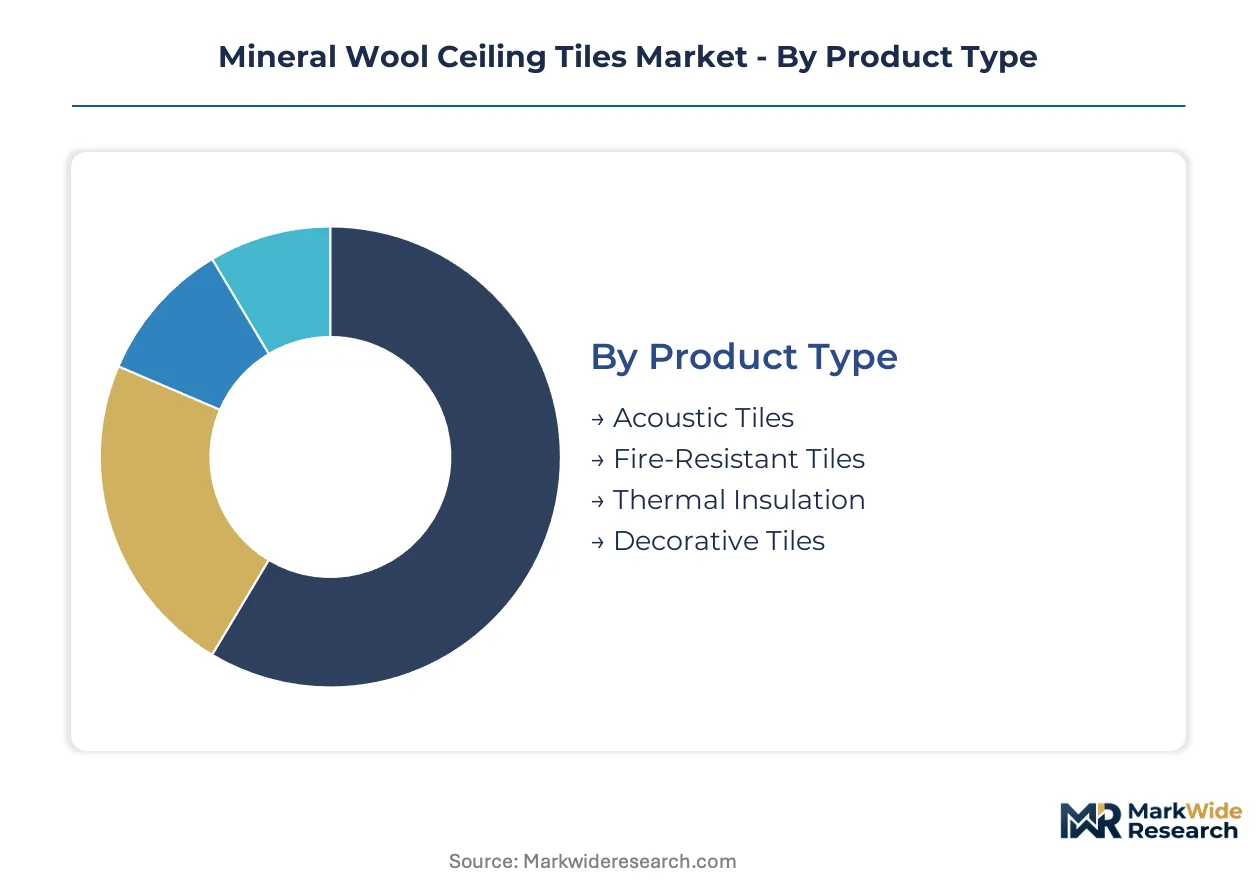
Segmentation in mineral wool ceiling tiles reveals how specification requirements diverge across building codes, acoustic performance thresholds, and installation constraints. Manufacturers configure product platforms around these dimensions to capture recurring demand from distinct construction verticals.
Product Type:
Mature acoustic formulations dominate specification volumes while fire-resistant and thermal variants represent emerging technology investments responding to tightening safety mandates.
- Acoustic Tiles:Engineered with NRC ratings up to 0.95 through flocked or perforated surfaces bonded to mineral wool substrates. Open-plan commercial offices in Germany and Poland specify these under DIN 18041 speech intelligibility standards for workplace productivity.
- Fire-Resistant Tiles:Stone wool formulations achieving Euroclass A1 or A2-s1,d0 ratings under EN 13501-1 certification. High-rise egress corridors and atrium spaces in Nordic markets command premium positioning due to stringent national fire codes.
- Thermal Insulation:Laminated composites integrating vapor barriers for HVAC efficiency in climate-controlled environments.
- Decorative Tiles:Surface-printed or textured finishes targeting hospitality and retail interiors where aesthetic integration overrides pure functional specification.
Acoustic tiles retain volume leadership; fire-resistant tiles hold the steepest expansion curve.
End User:
Cost tier differentiation separates institutional procurement frameworks from speculative commercial development and residential retrofit economics.
- Commercial Offices:Large-format suspended systems specified through facilities management frameworks at multinational corporations. LEED v4.1 and BREEAM compliance requirements in Nordic public procurement are accelerating low-emission binder adoption.
- Educational Institutions:Classrooms and lecture halls requiring speech intelligibility control alongside durability for high-traffic maintenance cycles.
- Residential Buildings:Limited penetration due to competing gypsum and wood-fiber alternatives; growth concentrates in multi-family mid-rise construction with shared noise transmission concerns.
- Industrial Facilities:Corrosion-resistant and wash-down rated tiles for food processing and pharmaceutical cleanrooms.
Commercial offices retain volume leadership; educational institutions hold the steepest expansion curve.
Installation Type:
Volume concentration favors systems enabling MEP accessibility, while emerging modular approaches address speed-to-occupancy pressures in fast-track construction.
- Suspended Ceiling:T-bar grid systems accommodating lighting, HVAC, and fire suppression integration with future accessibility for maintenance. This configuration dominates hospital modernization programs in France and Italy where infection control zones require frequent above-ceiling access.
- Directly Applied:Adhesive-mounted panels for soffit applications and height-constrained renovations where plenum space is unavailable.
- Mixed Installation:Hybrid approaches combining suspended zones over circulation corridors with direct application in perimeter offices.
- Modular:Pre-engineered cassette systems reducing on-site labor hours for standardized commercial fit-outs.
Suspended ceiling retains volume leadership; modular holds the steepest expansion curve.
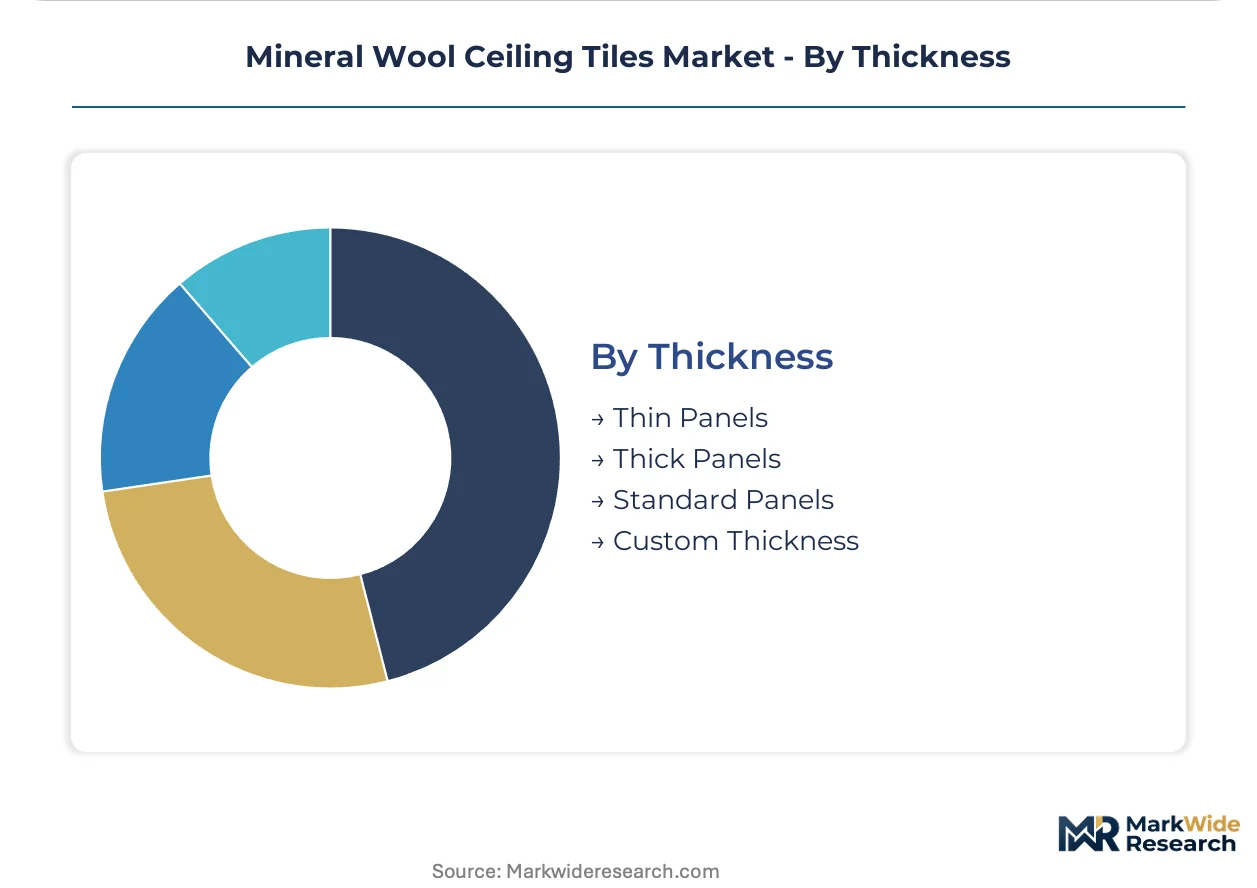
Thickness:
Supply concentration in standard panel formats creates margin pressure, while custom and thick variants capture specification premiums in specialized acoustic and fire-rated applications.
- Standard Panels:15-25mm thickness satisfying baseline acoustic and thermal performance for typical commercial suspended ceiling grids. Polish and Romanian distributors stock these SKUs for rapid-turnaround contractor procurement.
- Thick Panels:40mm+ configurations achieving enhanced low-frequency absorption for performance spaces and broadcast studios.
- Thin Panels:Reduced-depth options for retrofit applications with constrained plenum clearance.
- Custom Thickness:Project-specific fabrication for atrium geometries and non-standard structural bays requiring precision cutting capabilities.
Standard panels retain volume leadership; thick panels hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network underwrites Germany's position as the primary demand hub for mineral wool ceiling tiles, channeling specification-grade products into commercial construction clusters across the Benelux and northern Italy.
Germany
Commercial office retrofits in Berlin and Hamburg drive specification for DIN 18041-compliant acoustic systems. The country's updated building energy codes mandate higher acoustic performance ratings for open-plan workspaces. ROCKWOOL International operates expanded production capacity in Denmark to serve this demand concentration.
China
State-funded infrastructure projects in Beijing and Shanghai require GB 8624-certified fire-resistant ceiling systems for high-rise construction. The Ministry of Ecology and Environment enforces dual carbon goals that favor low-emission building materials. Shandong and Hebei provinces host expanded mineral wool substrate capacity redirecting export flows toward Middle East and Southeast Asian markets.
United States
Healthcare renovation pipelines in California and New York specify stone wool tiles with integrated antimicrobial surface treatments. EPA TSCA Title VI emissions standards for formaldehyde-based binders tighten formulation requirements for occupied renovation projects. The US Gulf Coast concentrates phenolic resin production, exposing manufacturers to freight cost volatility.
France
Hospital HVAC modernization programs in Paris and Lyon drive demand for infection-control ceiling systems in healthcare zones. The EU Green Deal's embodied carbon tracking requirements create first-mover advantage for manufacturers with verified Environmental Product Declarations. Auvergne-Rhône-Alpes hosts specialized fabrication capacity for custom atrium geometries.
Poland
Fast-track commercial fit-outs in Warsaw and Krakow accelerate procurement of standardized acoustic tile SKUs through direct-to-contractor digital platforms. REACH restrictions on phenolic resin constituents trigger additional toxicological data requirements for imported products. Knauf operates expanded production capacity to serve German and Nordic export demand.
Mineral Wool Ceiling Tiles Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying mineral wool substrates and binder formulations to finished goods manufacturers. The market structure consolidates around vertically integrated building materials conglomerates with captive raw material sourcing and distributed fabrication networks. Three archetypes dominate: stone wool specialists with fire-certification expertise, glass wool-integrated diversified players controlling supply chain costs, and regional fabricators serving cost-sensitive mid-market segments. Capacity expansion and bio-based binder reformulation represent the dominant competitive moves as manufacturers pre-certify products against evolving multi-jurisdictional standards.
Within the stone wool specialist tier, ROCKWOOL International and Knauf exemplify platform-scale players with Nordic fire-resistance certification anchoring premium positioning. Saint-Gobain represents the glass wool-integrated diversified archetype, leveraging backward control over raw material costs across European distribution networks. These three entities collectively illustrate how mineral wool ceiling tile competition stratifies between certification-driven premium positioning and supply chain-integrated cost management.
| Leading Market Players |
|---|
| Saint-Gobain |
| AWI Licensing LLC |
| Armstrong World Industries |
| Owens Corning |
| Hunter Douglas |
| USG Corporation |
| Knauf |
| Johns Manville |
| ROCKWOOL International |
| Others |
Cost & Logistics Intelligence
Phenolic resin supply concentration along the US Gulf Coast determines both pricing tier spreads and supply chain shape for mineral wool ceiling tile manufacturers. REACH compliance costs and freight volatility from this single-source dependency compress margins in the standard tier while amplifying premiums for certified low-emission formulations.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement frameworks from spot-market contractor purchases. Three-tier pricing stratifies across premium A1 fire-rated stone wool, standard acoustic tiles with DIN 18041 certification, and economy-grade gypsum-competing SKUs. Price differentiation hinges on certification grade and geographic delivery cost, with Nordic markets commanding premiums for Euroclass A1 documentation. Pricing pressure stems from improved acoustic gypsum formulations capturing mid-market specifications. Speculative commercial developers exhibit highest price sensitivity; healthcare and education procurement frameworks with LEED mandates show lowest.
Supply Chain Analysis
Export-control regimes on formaldehyde-based binder technologies under REACH substance evaluation restrict feedstock flows into European fabrication networks. Raw material sourcing concentrates in China for mineral wool substrates, Denmark and Poland for stone wool production, and the US Gulf Coast for phenolic resin binders. Manufacturers draw from slag and basalt feedstocks, phenolic resin formulations, and antimicrobial surface treatments. Single-source vulnerability in resin supply exposes European and Asian producers to freight cost spikes and force majeure disruptions. Distribution runs through building materials distributors and emerging direct-to-contractor digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mineral wool ceiling tile market sits in a commercial construction cyclical recovery driven by post-pandemic office retrofit pipelines across Germany and Poland.
For Market Incumbents: Insulate certification portfolios against multi-protocol fire testing delays by pre-qualifying products against ASTM E84, EN 13501-1, and GB 8624 simultaneously. Backward integration into bio-based binder R&D reduces REACH compliance exposure while capturing LEED v4.1 specification premiums from California and New York healthcare developers. Capacity addition in Poland and Denmark anchors supply security for Rhine-Alpine Corridor demand clusters. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given redirected export capacity from Shandong and Hebei provinces. Hospital HVAC modernization programs in France and Italy offer specification traction for antimicrobial surface treatment specialists. Direct-to-contractor digital platforms provide the most efficient go-to-market angle for standardized acoustic tile SKUs without distributor margin stacking. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors stone wool specialists with captive fire-certification expertise and verified Environmental Product Declarations. Long-term viability over the next decade rests on embodied carbon tracking compliance under EU Green Deal mandates. The signal to watch is ECHA's Community Rolling Action Plan evaluation timeline for mineral wool fibers, which will determine toxicological data investment requirements and competitive exit barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Binder Commercialization | Lignin-derived formulations capture LEED v4.1 credits from California healthcare developers. |
| Multi-Protocol Fire Certification | Pre-qualification against ASTM E84, EN 13501-1, and GB 8624 compresses product launch timelines. |
| Direct-to-Contractor Platform Launch | Digital procurement portals disintermediate traditional distribution layers for mid-size commercial fit-outs. |
| Antimicrobial Surface Integration | Infection-control specifications from French and Italian hospital modernization programs command premium positioning. |
| Environmental Product Declaration Verification | Embodied carbon tracking under EU Green Deal creates first-mover advantage in public procurement frameworks. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across published sources. Primary interviews captured perspective from ceiling system specification engineers, facilities management directors at multinational corporations, commercial construction procurement leads, building materials distributors, and regulatory compliance officers at manufacturers. Secondary sources included EPA TSCA Title VI filings, ECHA substance evaluation databases, DIN 18041 acoustic performance standards, and trade data from Shandong and Hebei export clusters. Bottom-up project pipeline enumeration and top-down construction spending triangulation anchored volume estimates.
Forecast inputs considered product type segmentation across acoustic, fire-resistant, thermal insulation, and decorative tiles; end-user categories spanning commercial offices, educational institutions, healthcare facilities, and industrial applications; installation configurations including suspended ceiling, direct application, and modular systems; and thickness variants from standard panels to custom geometries. CAGRs were derived through regression analysis against commercial construction permit data and retrofit cycle timing across the projection horizon. Industry-specific inputs incorporated REACH phenolic resin restriction timelines and GB 8624 certification adoption rates for state-funded infrastructure.
Practitioners should monitor steel production volatility in blast furnace operations and ECHA substance evaluation roadmap updates for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
Global Steel Pipe Piles Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
Wood Shingles Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Architectural Membrane Market