
 GCC Exterior Sheathing Market | 2026-2036
GCC Exterior Sheathing Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Exterior Sheathing Market Intelligence
Modular panel bundling with insulation and weather barriers is restructuring buyer procurement across the GCC. Kingspan Group leverages its integrated insulated panel systems to anchor premium commercial contracts in Riyadh and Jeddah. Saint Gobain Group sustains manufacturing scale through regional gypsum and glass mineral wool operations. CEMEX competes on cement-based sheathing formulations tailored to Gulf humidity and salt exposure.
GCC exterior sheathing comprises rigid boards or panels applied to structural framing to provide weather resistance, thermal insulation, and substrate for exterior finishes, typically manufactured from wood fiber, glass-reinforced gypsum, cementitious compounds, or polymeric foams with specified R-values and fire ratings. The material type dimension shows cement board capturing industrial and high-rise applications where Gulf fire codes restrict combustible substrates, while fiberglass faces margin pressure from polyurethane's superior thermal performance in energy-efficient designs. Application segmentation reveals renovation projects expanding fastest as aging stock in Kuwait and Bahrain requires envelope upgrades, though residential construction still occupies the largest volume pool across Saudi giga-developments.
Saudi Building Code and UAE Fire and Life Safety Code shape product approval pathways, with SASO certification mandatory for Saudi imports and Dubai Civil Defence enforcing flame-spread ratings on exterior cladding assemblies. Abu Dhabi Department of Municipalities and Transport mandates third-party thermal testing for sheathing in government-backed developments. Stakeholders must monitor evolving green building rating tools across the six GCC states and align product portfolios with anticipated mandatory embodied carbon disclosures.
Market Dynamics
Modular panel bundling with factory-integrated insulation and weather barriers is compressing traditional multi-step installation workflows across Saudi Arabia and UAE construction corridors. This structural shift favors manufacturers with captive insulation production and penalizes standalone sheathing suppliers.
Growth Catalysts
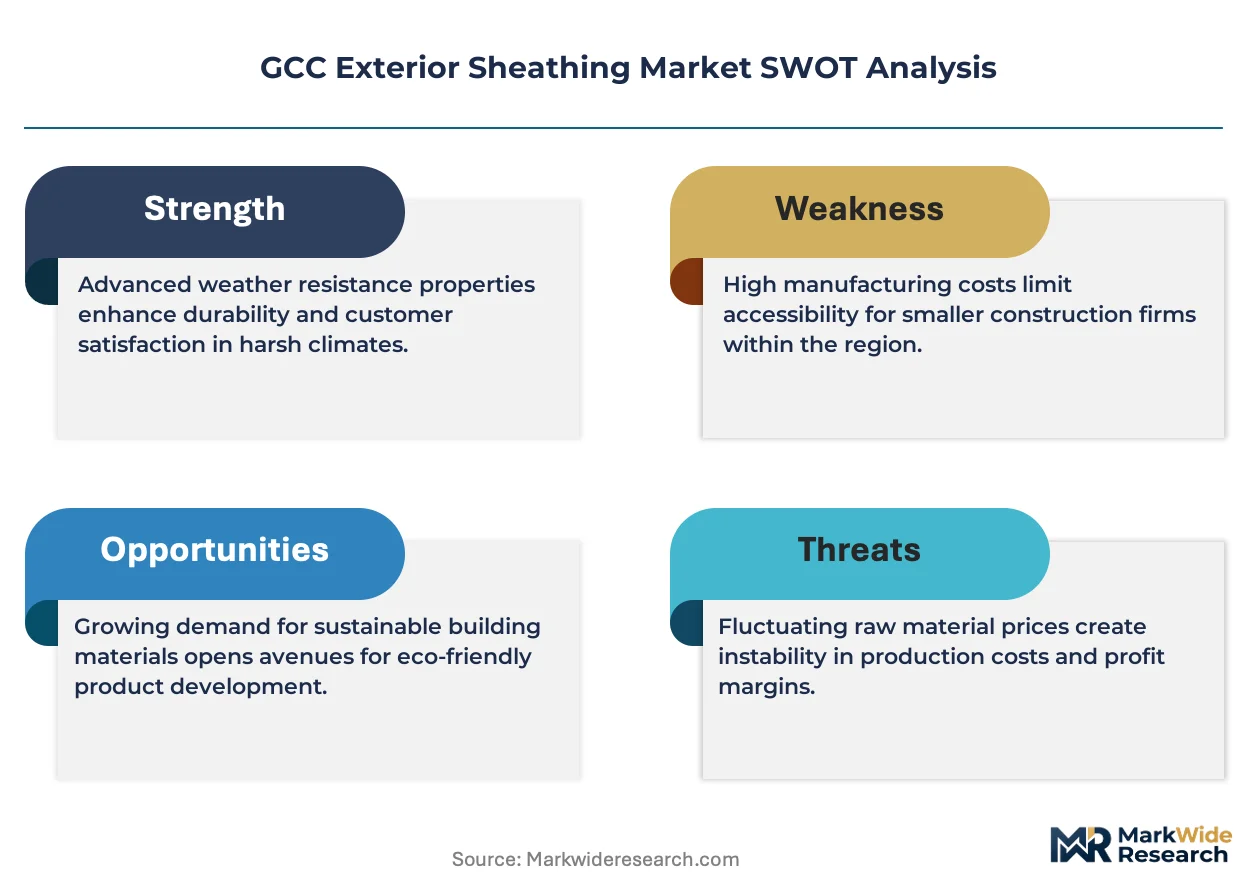
- Saudi Building Code thermal mandates:Stricter envelope performance requirements in Riyadh and Jeddah are specifying cement board and fiberglass sheathing with certified R-values above legacy wood-fiber alternatives.
- Giga-project corridors:NEOM, Red Sea Project, and Qiddiya developments are standardizing high-performance exterior assemblies across residential and hospitality verticals, creating concentrated demand pools.
- Polyurethane thermal performance:Superior insulating values in energy-efficient designs are pulling specification share from traditional fiberglass in Dubai's high-rise residential zones.
Market Restraints
- Port congestion at Jebel Ali and Dammam:Cement board imports face extended clearance timelines, inflating working capital requirements for distributors serving Kuwait and Bahrain renovation markets.
- Aluminum frame substitution:Unitized curtain wall systems with integrated insulation are capturing share in premium commercial towers, bypassing separate sheathing procurement entirely.
- SASO certification complexity:Mandatory Saudi Standards, Metrology and Quality Organization testing for fire ratings and thermal performance creates six-month approval bottlenecks for new product entrants.
Strategic Opportunities
- Oman and Bahrain renovation stock:Aging residential envelopes in Muscat and Manama require envelope upgrades, with fiberglass sheathing positioned for rapid retrofit installation.
- Embodied carbon disclosure mandates:Anticipated green building rating tool harmonization across GCC states will advantage cement-based products with lower lifecycle carbon profiles versus polymeric foams.
- Prefabrication channel convergence:Offsite construction factories in Saudi Arabia's industrial cities are consolidating sheathing-insulation-finish procurement into single-source panel contracts.
Industry Challenges
- Fire-rated assembly certification:Dubai Civil Defence flame-spread testing protocols require full-scale wall assembly burns, extending product launch timelines by eight to twelve months.
- Skilled installer scarcity:Proper cement board fastening and sealing in Gulf humidity conditions demands trained crews, with labor shortages delaying project handovers in Qatar's Lusail development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Exterior Sheathing Market |
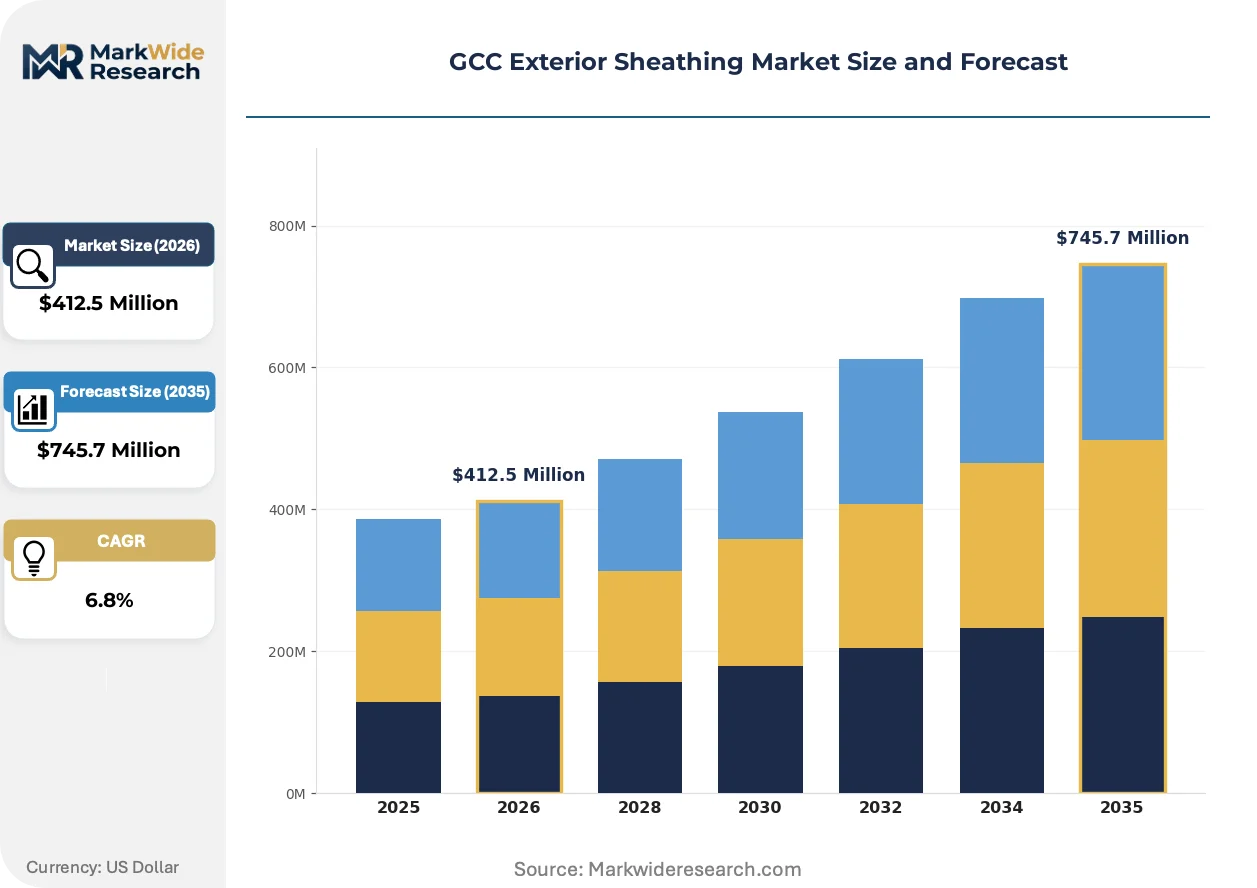
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Fiberglass, Polyurethane, Cement Board Application: Residential Construction, Commercial Buildings, Industrial Facilities, Renovation Projects Distribution Channel: Direct Sales, Retail Outlets, E-commerce, Wholesale Installation Method: Panel Installation, Sheet Installation, Prefabricated, Custom Fabrication |
| Companies Covered | Saint Gobain Group, Kingspan Group, PPG Industries LLC, CEMEX, Knauf Gips, Etex Group, Carea Group, Middle East Insulation LLC, Avenere Cladding LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Exterior Sheathing Market Strategic Shifts & Innovations
Factory-integrated building envelope solutions are collapsing the traditional separation between structural sheathing, thermal insulation, and weather-resistant barriers. This convergence is redrawing competitive boundaries and compressing value chain margins for standalone component suppliers.
Prefabricated insulated metal panels with mineral wool cores are decentralizing on-site sheathing installation across Saudi Arabia's commercial and industrial construction. General contractors in Riyadh's logistics park developments are specifying these systems for 40% faster envelope closure. The technology is decentralizing trade coordination risks and compressing project schedules that previously required sequential insulation and cladding trades.
UAE Fire and Life Safety Code amendments are tightening flame-spread rating requirements for exterior cladding assemblies above 15 meters. Manufacturers must now submit full-scale fire propagation test reports to Dubai Civil Defence for approval. Cement board producers with established third-party testing relationships are securing specification lock-in ahead of smaller competitors facing capital constraints for new certification rounds.
Consolidated procurement through engineering-procurement-construction firms is replacing fragmented distributor relationships in Saudi giga-projects. EPC contractors at NEOM and Red Sea Project are negotiating multi-year panel supply agreements with integrated manufacturers. This concentration is most visible in hospitality and residential verticals where repetitive building typologies favor standardized envelope specifications over custom material sourcing.
GCC Exterior Sheathing Market Segmentation
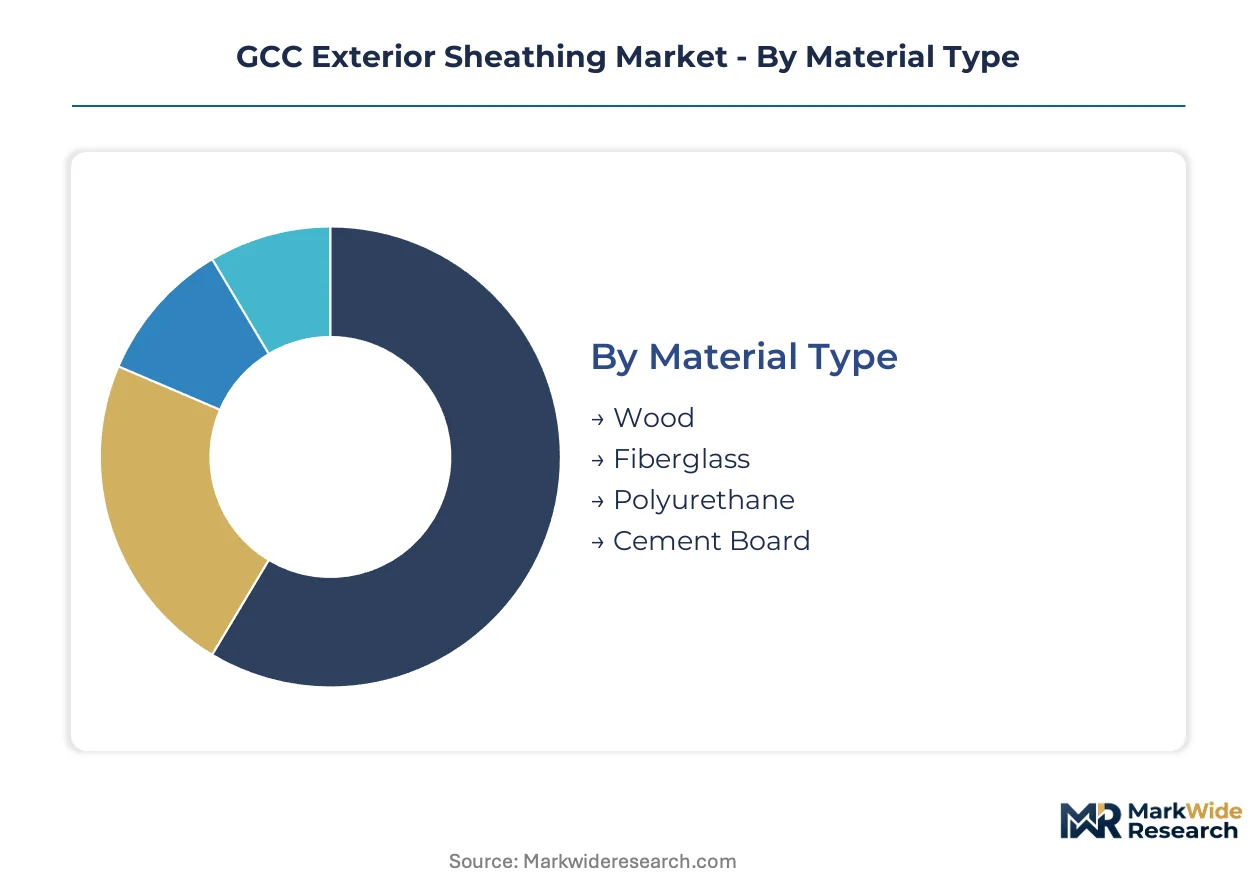
Exterior sheathing procurement patterns diverge sharply between standalone board sales and factory-integrated envelope systems across GCC construction corridors. Material selection and installation method choices determine whether contractors source discrete components or consolidated panel assemblies.
Material Type:
Integration depth varies dramatically — cement board and polyurethane dominate embedded multi-layer systems, while wood and fiberglass persist in standalone applications requiring separate insulation procurement.
- Cement Board:Portland cement and cellulose fiber composite delivers Gulf-specific humidity resistance and non-combustible substrate properties. Demand concentrates in Saudi Arabia's giga-project hospitality and high-rise residential towers where SASO fire codes restrict combustible materials. Stricter envelope performance mandates are displacing legacy gypsum alternatives in Riyadh and Jeddah developments.
- Polyurethane:Rigid closed-cell foam sheathing achieves superior thermal resistance values in slim profile assemblies. Specification is climbing fastest in Dubai's high-rise residential zones where floor-to-floor height constraints favor thin, high-R-value continuous insulation layers over bulkier fiberglass batts.
- Fiberglass:Glass-reinforced gypsum and mineral wool boards serve renovation markets in Kuwait and Bahrain with cost-sensitive retrofit budgets.
- Wood:Oriented strand board and plywood sheathing retains niche presence in low-rise Saudi residential construction with less stringent fire rating requirements.
Cement board leads volumes today; polyurethane is gaining share fastest.
Application:
Project scale and procurement concentration determine whether sheathing ships as bulk commodity or specified assembly — giga-developments favor consolidated envelope contracts while fragmented renovation work sustains distributor channels.
- Residential Construction:Saudi Arabia's giga-project corridors at NEOM, Red Sea Project, and Qiddiya standardize high-performance exterior assemblies across repetitive housing typologies. EPC contractors negotiate multi-year panel supply agreements that bypass traditional distributor relationships entirely.
- Renovation Projects:Aging envelope stock in Muscat and Manama drives fiberglass sheathing demand for rapid retrofit installation without structural modification. Kuwaiti and Bahraini contractors favor sheet products that minimize skilled labor requirements on constrained urban sites.
- Commercial Buildings:Premium towers in Dubai and Riyadh increasingly specify unitized curtain wall systems with integrated insulation, bypassing separate sheathing procurement.
- Industrial Facilities:Logistics parks across Saudi industrial cities adopt prefabricated insulated metal panels for accelerated envelope closure.
Residential construction dominates absolute volume; renovation projects expand most quickly.
Distribution Channel:
Channel structure reflects buyer sophistication — mega-developments consolidate through direct manufacturer relationships while smaller contractors depend on retail and wholesale intermediaries.
- Direct Sales:EPC firms at Saudi giga-projects negotiate multi-year supply agreements with integrated panel manufacturers. Kingspan Group and Saint-Gobain anchor premium commercial contracts through captive specification relationships.
- Wholesale:Regional distributors serve Kuwait and Bahrain renovation markets with cement board imports facing extended clearance timelines at Jebel Ali and Dammam ports.
- Retail Outlets:Independent contractors in Qatar's Lusail development source standard sheet products through building material retailers.
- E-commerce:Digital procurement channels remain nascent for sheathing categories requiring technical specification support.
Direct sales capture the largest contract value; wholesale channels handle the highest transaction frequency.
Installation Method:
Prefabrication intensity separates high-volume standardized projects from custom architectural applications requiring field-adapted solutions.
- Prefabricated:Factory-integrated insulated metal panels with mineral wool cores compress project schedules by 40% in Riyadh logistics developments. Offsite construction factories in Saudi industrial cities consolidate sheathing-insulation-finish procurement into single-source contracts.
- Panel Installation:Modular panel bundling with factory-integrated weather barriers restructures procurement across UAE commercial corridors, favoring manufacturers with captive insulation production.
- Sheet Installation:Traditional multi-step workflows persist in renovation markets where existing structural constraints demand field-cut adaptation.
- Custom Fabrication:Complex geometries in Dubai hospitality and cultural projects require CNC-cut cement board assemblies with project-specific fastening patterns.
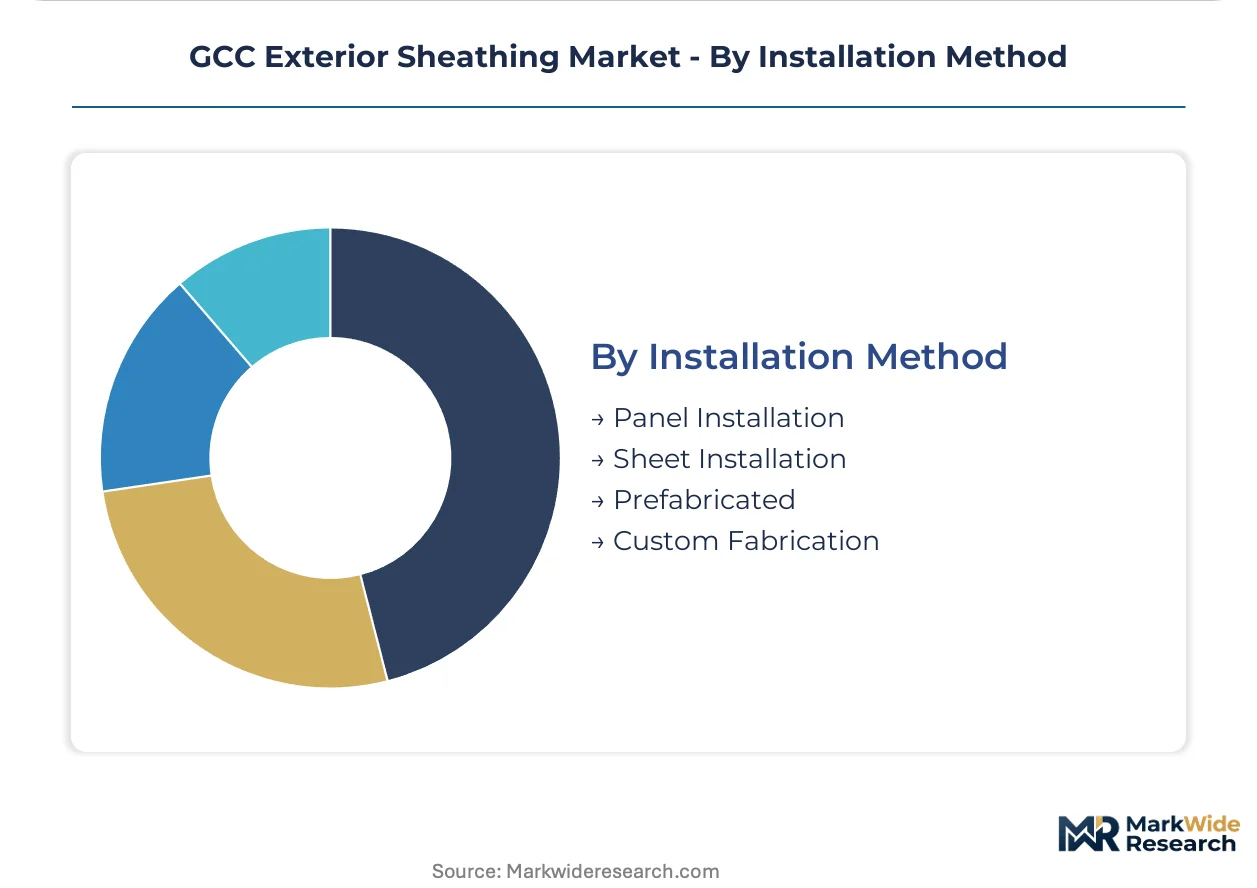
Prefabricated methods claim the steepest expansion trajectory; panel installation retains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC exterior sheathing industry traces its modern scale to Saudi Arabia's 1970s infrastructure buildout, when cement-based board imports first standardized construction practices across Aramco housing and government developments. This foundation established the Kingdom as the regional demand anchor long before UAE commercial towers and Qatar World Cup construction accelerated specification sophistication.
Saudi Arabia
NEOM, Red Sea Project, and Qiddiya developments concentrate multi-billion dollar envelope procurement into standardized high-performance assemblies. SASO certification mandates six-month testing cycles for fire ratings and thermal performance, filtering import channels. Riyadh and Jeddah giga-project corridors now specify cement board and polyurethane systems exclusively, displacing legacy materials through EPC-negotiated multi-year supply agreements.
United Arab Emirates
Dubai's high-rise residential zones and Abu Dhabi's government-backed developments drive premium thermal performance specifications. Dubai Civil Defence enforces full-scale flame-spread testing for assemblies above 15 meters, extending product launch timelines eight to twelve months. Abu Dhabi Department of Municipalities and Transport mandates third-party thermal testing, concentrating specification authority among pre-approved manufacturers with established testing relationships.
Qatar
Lusail development and World Cup legacy infrastructure sustain demand for rapid-installation envelope systems. Skilled installer scarcity delays project handovers, pushing contractors toward prefabricated panel solutions that compress on-site trade coordination. Doha's logistics constraints favor direct manufacturer relationships over distributor intermediaries for large-scale commercial contracts.
Kuwait
Aging residential stock in Kuwait City and surrounding governorates drives renovation-driven fiberglass sheathing demand. Extended port clearance timelines at regional hubs inflate working capital requirements for distributors serving cost-sensitive retrofit budgets. Contractors favor sheet products minimizing skilled labor requirements on constrained urban sites with limited crane access.
Oman
Muscat's aging residential envelopes and emerging industrial city developments create bifurcated demand pools. Fiberglass sheathing captures rapid retrofit installation in established neighborhoods, while cement board penetrates new logistics and manufacturing facilities in Duqm and Sohar. The country's building code evolution lags Saudi and UAE stringency, preserving material flexibility absent in neighboring markets.
GCC Exterior Sheathing Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and factory-integrated system capabilities. The market structures around three tiers: multinational building material conglomerates with captive insulation production, regional cement and gypsum specialists with Gulf-specific formulation expertise, and standalone sheathing distributors dependent on port-access efficiency. Two competitive moves dominate: backward integration into mineral wool and polyurethane core production, and multi-year EPC supply agreements that lock out spot-market competitors.
Within the multinational tier, Saint Gobain Group and Kingspan Group exemplify divergent strategic positions. Saint Gobain anchors scale through regional gypsum and glass mineral wool operations, sustaining manufacturing presence without full Gulf integration. Kingspan occupies the premium-systems vector through insulated panel architectures that collapse sheathing, thermal barrier, and weather protection into factory-delivered assemblies. CEMEX represents the cement-specialist archetype, competing on humidity-resistant and salt-tolerant formulations tailored to Gulf environmental stressors rather than thermal performance alone.
| Leading Market Players |
|---|
| Saint Gobain Group |
| Kingspan Group |
| PPG Industries LLC |
| CEMEX |
| Knauf Gips |
| Etex Group |
| Carea Group |
| Middle East Insulation LLC |
| Avenere Cladding LLC |
| Others |
Cost & Logistics Intelligence
Multi-year EPC supply agreements at Saudi giga-projects are compressing spot-market pricing power and forcing standalone distributors to absorb port clearance cost volatility or cede share to integrated manufacturers with captive logistics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates factory-integrated panel systems from commodity board sales and distributor spot transactions. Premium tier pricing rests on SASO certification depth and Dubai Civil Defence flame-spread approval, while economy tiers compete on port-access efficiency for Kuwait and Bahrain renovation markets. Cost compression in standard-grade cement board is intensifying because Saudi EPC contractors are consolidating procurement into direct manufacturer contracts. Price sensitivity concentrates among independent contractors in Qatar's Lusail development, whereas premium commercial towers in Dubai exhibit specification-driven purchasing with limited price elasticity.
Supply Chain Analysis
Freight cost differentials between Jebel Ali and Dammam port corridors are redrawing competitive boundaries for cement board imports serving Kuwait and Bahrain. Manufacturing concentration centers on Saudi Arabia's industrial cities, UAE's Jebel Ali free zone, and European parent-plant exports for premium integrated systems. Raw material flows draw from regional gypsum deposits, imported cellulose fiber, and captive mineral wool production. Single-source vulnerability sits with port clearance bottlenecks that extend working capital cycles for distributors. Distribution runs through direct manufacturer relationships for giga-project volumes and wholesale intermediaries for fragmented renovation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strategic positioning in this market functions as a geographic-arbitrage play: manufacturers with Saudi-based production capture margin advantage from SASO certification proximity, while import-dependent competitors face six-month approval timelines and working capital strain.
For Market Incumbents: Hedge against aluminum frame substitution in Dubai commercial towers by deepening captive insulation production and securing multi-year EPC panel contracts at NEOM and Red Sea Project. Anchor specification lock-in through accelerated Dubai Civil Defence flame-spread testing investments before smaller competitors clear capital constraints for certification rounds. For New Entrants and Emerging Players: Enter via Oman's renovation corridor in Muscat and emerging Duqm industrial city developments, where building code stringency lags Saudi and UAE standards and preserves material flexibility. Target fiberglass sheathing for rapid retrofit installation in aging residential envelopes with minimal structural modification requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with cement-specialist manufacturers possessing Gulf-specific humidity-resistant formulations and established third-party testing relationships. Long-term viability hinges on embodied carbon disclosure readiness as green building rating tools harmonize across GCC states. Watch for SASO certification timeline compression as the signal indicating regulatory barrier reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Wool | Captive core production secures panel margin at Saudi giga-projects against commodity insulation volatility. |
| SASO Certification Fast-Track Investment | Six-month approval compression filters import channels and locks out capital-constrained competitors from Riyadh specifications. |
| Prefabricated Panel Joint Venture | Offsite construction factory partnerships in Saudi industrial cities consolidate sheathing-insulation-finish procurement. |
| Renovation Channel Distribution Expansion | Wholesale presence in Kuwait and Bahrain captures aging envelope retrofit demand with sheet-product logistics. |
| Embodied Carbon Disclosure Program | Lifecycle certification readiness advantages cement-based products ahead of anticipated GCC green building mandates. |
Research Approach
Direct dialogue with EPC procurement directors, cement board plant managers, Dubai Civil Defence approval specialists, and Kuwaiti renovation contractors grounded qualitative assessment in operational reality. Secondary validation drew from SASO certification registries, Dubai Department of Economic Development trade data, Saudi Ports Authority clearance statistics, and GCC national building code amendments. Bottom-up demand modeling triangulated against top-down construction spend forecasts across material type and application dimensions.
Top-down macroeconomic anchoring combined with bottom-up project pipeline enumeration across NEOM, Red Sea Project, Qiddiya, Lusail, and Muscat developments. Segmentation modeling tracked material type, application, installation method, and distribution channel dynamics throughout the forecast period. CAGRs derived from installation volume trajectories and specification share shifts, with thermal performance code evolution and prefabrication adoption as primary demand elasticity inputs.
Inputs from EPC contractors and regulatory approval bodies were available through the study window; gaps in real-time port clearance duration data and contractor bid-level pricing introduce uncertainty bands around working capital and margin projections. Stakeholders should weight assumptions against their own operating context and supply chain exposure to certification timeline variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
North America Industrial Flooring Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
North America Concrete Superplasticizer Market