
 Saudi Arabia Tiles Market | 2026-2036
Saudi Arabia Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Tiles Market Outlook
SASO certification under the Saudi Building Code is bifurcating the competitive landscape between qualified domestic producers and import-dependent distributors. Saudi Ceramic Company leverages integrated manufacturing from Riyadh to control supply security for large-format porcelain. Alfanar Ceramics anchors its position through specialized production serving electrical infrastructure-adjacent tiling needs. RAK Ceramics competes via regional Gulf manufacturing scale that sustains cost positioning across premium porcelain segments.
Tiles are fired clay or mineral-based surfacing materials, typically measuring 300x300mm to 800x800mm, produced through dry pressing and kiln firing at 1,100-1,250°C for floor and wall coverage in built environments. Porcelain commands structural priority due to lower water absorption rates below 0.5% that suit Saudi Arabia's humidity and temperature cycling. Residential application leads volume absorption through government-backed mortgage expansion, while commercial application concentrates margin pools around giga-project specification tiers. Large-format sizes above 600x1200mm are displacing medium formats in premium developments across the Kingdom's western corridor.
SFDA material safety protocols and SASO quality mandates govern ceramic product entry, with the Ministry of Municipal and Rural Affairs enforcing compliance through construction permit linkages. The Saudi Green Building Forum's evolving standards are embedding sustainability criteria into procurement specifications for public projects. Stakeholders must monitor how giga-project delivery timelines reshape inventory planning and specification flexibility across the supply base.
Market Dynamics
Giga-project construction under Vision 2030 is compressing specification cycles and forcing tile suppliers to align production capacity with accelerated delivery timelines for hospitality and residential developments.
Growth Catalysts
- Vision 2030 Giga-Projects:NEOM, Red Sea Project, and Qiddiya are generating concentrated demand for large-format porcelain in hospitality and luxury residential segments.
- SASO Certification Expansion:The Saudi Building Code enforcement by the Ministry of Municipal and Rural Affairs is filtering substandard imports and elevating domestic manufacturer market access.
- Mortgage Subsidy Programs:Government-backed housing finance expansion is stimulating residential tile consumption across Riyadh and Jeddah corridors.
Market Restraints
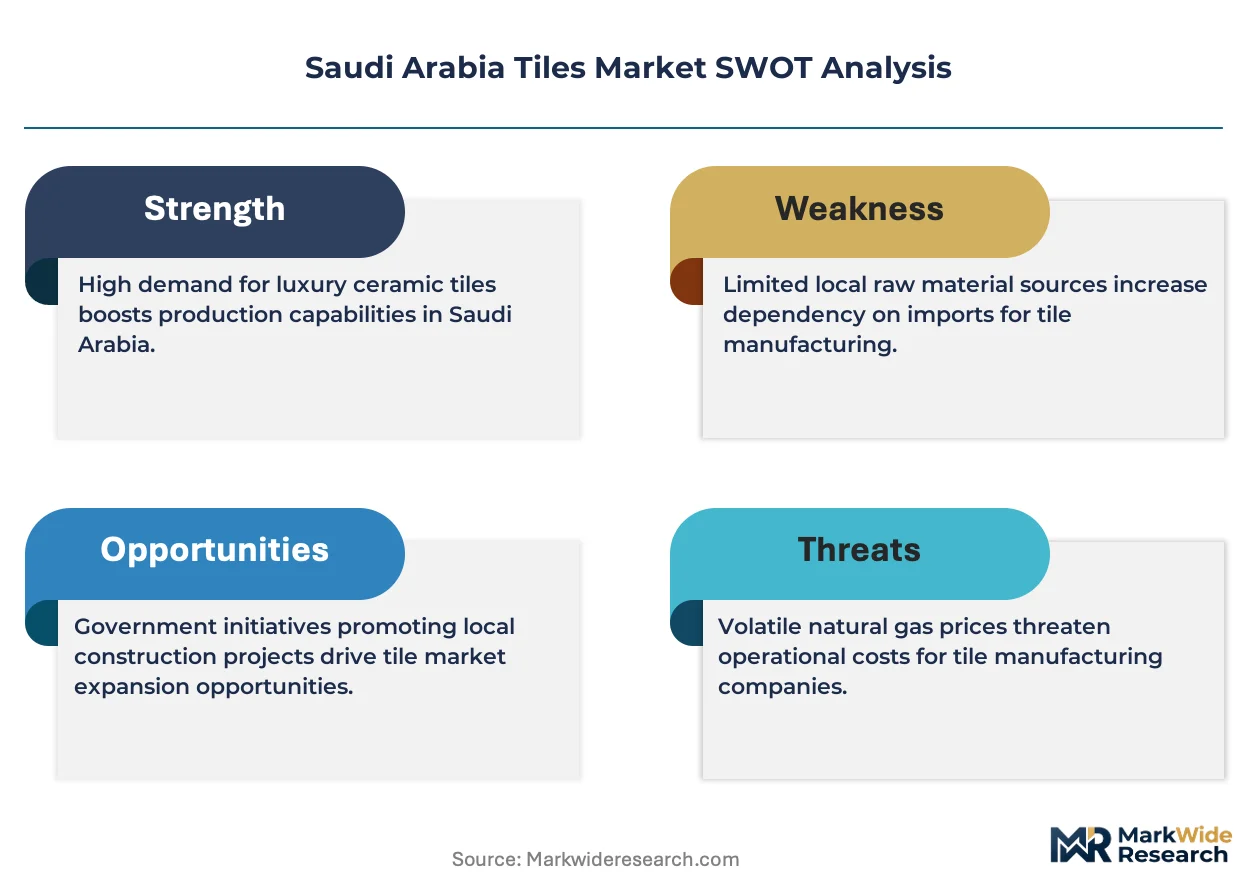
- Feldspar and Clay Input Volatility:Raw material cost fluctuations from Egyptian and Indian supply sources are compressing margin predictability for ceramic producers.
- Import Dependency for Glazes:Specialized inkjet glaze formulations concentrate among Italian and Spanish suppliers, creating supply security vulnerabilities.
- Natural Stone Substitution:Marble and travertine preferences in ultra-premium developments limit porcelain penetration in specification tiers above SAR 500 per square meter.
Strategic Opportunities
- Tabuk and Northern Borders Expansion:NEOM-adjacent logistics infrastructure is opening new distribution nodes beyond traditional Riyadh-Jeddah concentration.
- Digital Specification Platforms:BIM-integrated tile selection tools are enabling direct architect-manufacturer engagement, bypassing distributor markups.
- Saudi Green Building Forum Alignment:Evolving sustainability procurement criteria for public projects are creating first-mover advantages for low-carbon ceramic producers.
Industry Challenges
- Kiln Technician Shortage:Specialized firing process expertise for large-format porcelain remains scarce in the Eastern Province manufacturing base.
- SASO Testing Bottlenecks:Certification timeline delays of 8-12 weeks are constraining inventory planning for giga-project procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Tiles Market |
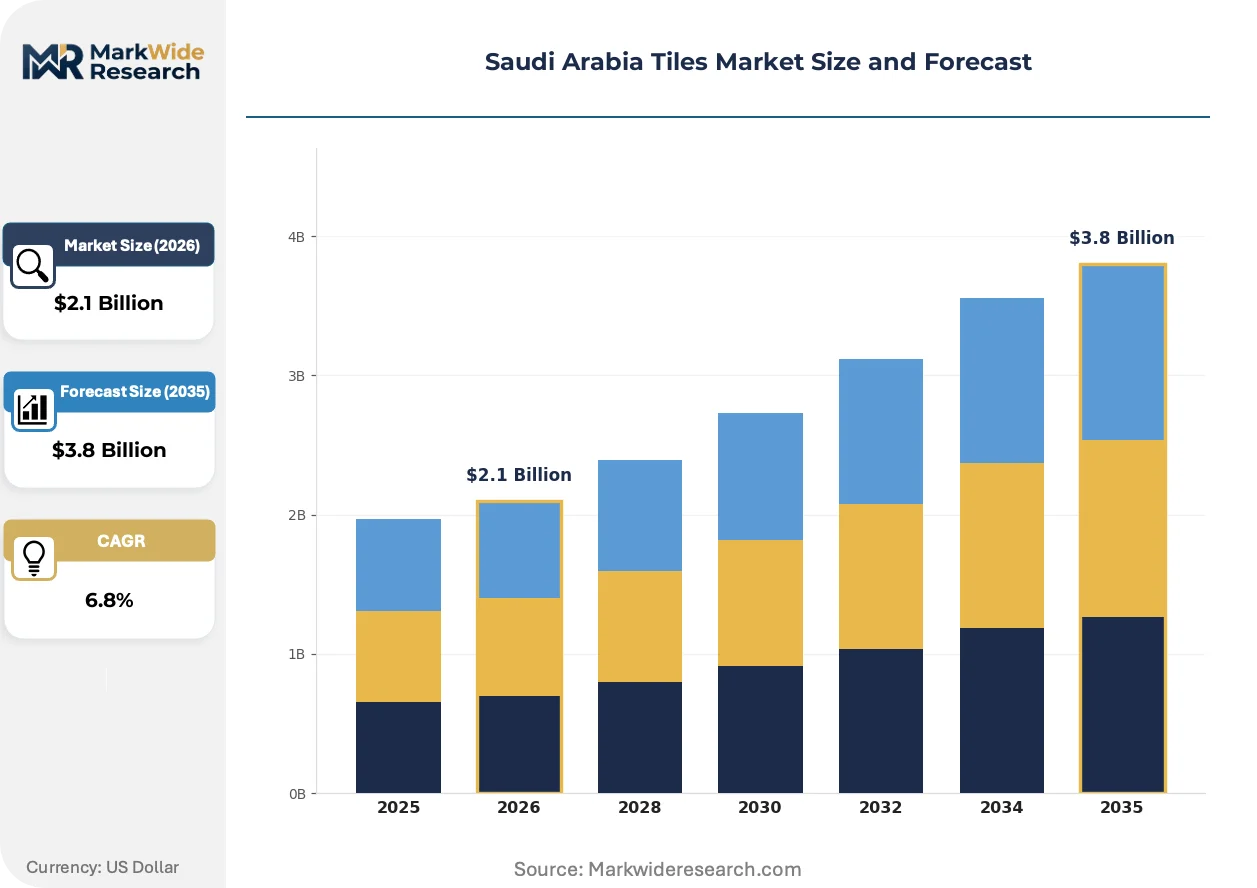
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Porcelain, Glass, Stone Application: Residential, Commercial, Industrial, Outdoor Size: Small, Medium, Large, Custom Distribution Channel: Online, Retail, Wholesale, Direct |
| Companies Covered | Alfanar Ceramics, Al Jawdah Ceramic Tiles Company, Saudi Ceramic Company, Al Khaleej Ceramics, Forsan Ceramics, RAK Ceramics, Arabian Tile Co., Riyadh Ceramics Factory, Future Ceramics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Tiles Market Strategic Shifts
Digital manufacturing integration and specification platform adoption are compressing traditional distributor channels while enabling mass customization at production scale across the Kingdom's western corridor.
Thin large-format porcelain slabs exceeding 1600x3200mm are decomposing traditional natural stone specification in luxury hospitality lobbies and executive residential developments. Five-star hotel operators in Jeddah are specifying these materials for seamless wall-to-floor transitions. The technology is decomposing the historical price premium commanded by imported marble in commercial projects above 10,000 square meters.
Saudi Building Code enforcement by the Ministry of Municipal and Rural Affairs is mandating water absorption thresholds below 0.5% for exterior cladding applications. This regulatory pressure is accelerating domestic kiln upgrades toward European firing standards. Premium porcelain segments in Riyadh's northern developments are responding with accelerated SASO pre-certification investments.
Architects and developers are consolidating procurement through direct manufacturer relationships rather than traditional distributor networks. This channel compression is displacing legacy tile importers who lack production assets. The shift is most visible in NEOM and Red Sea Project developments where specification consistency requirements override price sensitivity.
Saudi Arabia Tiles Market Segmentation
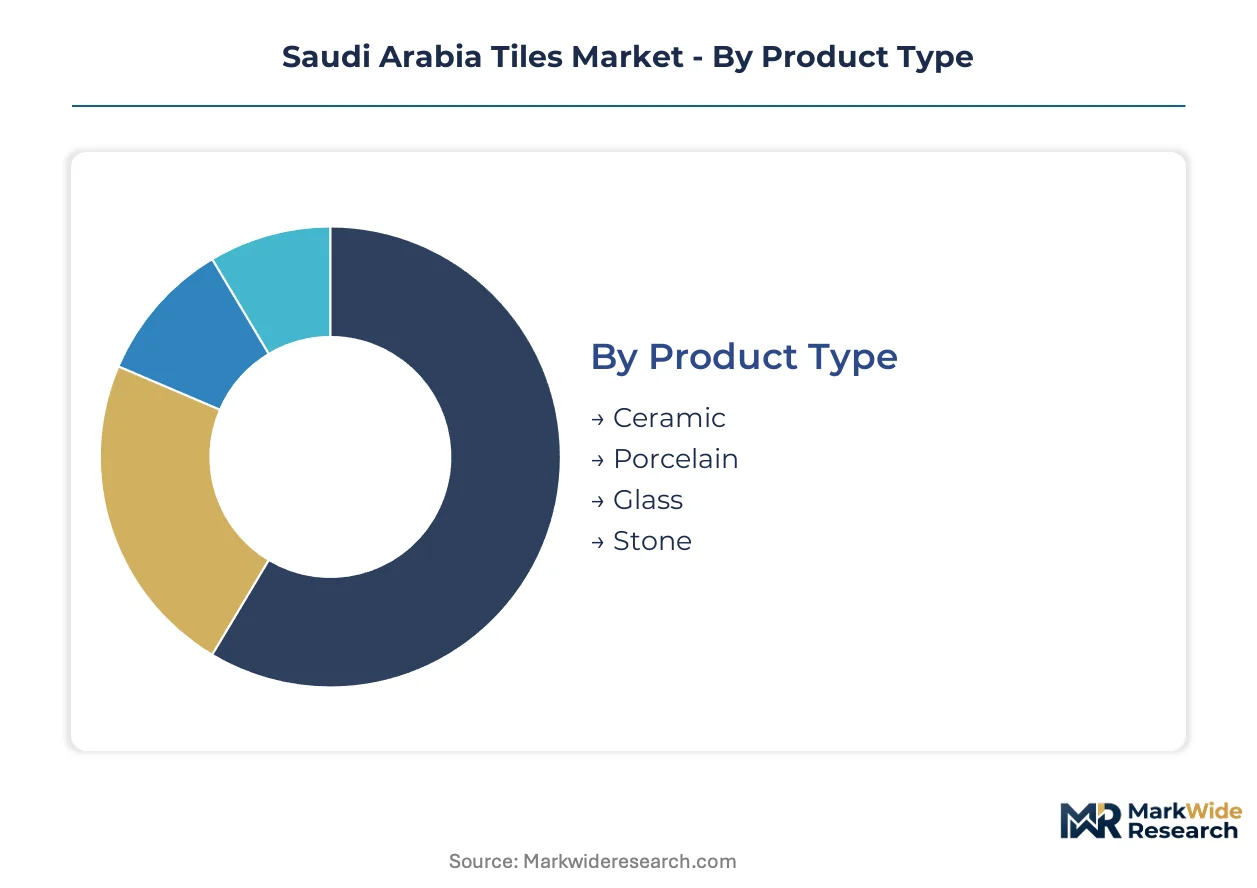
Saudi Arabia's tiles market segments across material composition, end-use application, dimensional specification, and procurement channel. Each dimension carries distinct margin profiles and regulatory requirements under SASO certification mandates.
Product Type:
Porcelain dominates domestic manufacturing output from Riyadh-based kilns, while ceramic and glass categories retain significant import dependency.
- Porcelain:Fired at 1,100-1,250°C with water absorption below 0.5%, meeting Saudi Building Code exterior cladding mandates. NEOM and Red Sea Project hospitality specifications are concentrating procurement in Jeddah and Tabuk logistics corridors.
- Ceramic:Higher porosity wall tiles serving residential mortgage-backed housing expansion across Riyadh's northern developments. SASO testing bottlenecks of 8-12 weeks constrain inventory planning for this segment.
- Glass:Decorative mosaic and backsplash applications in premium residential fit-outs, imported primarily from Italian suppliers.
- Stone:Travertine and marble alternatives for ultra-premium developments above SAR 500 per square meter, competing directly with thin-format porcelain substitution.
Porcelain holds the largest share; momentum sits with large-format porcelain slabs exceeding 1600x3200mm.
Application:
Cost tier stratification separates giga-project commercial specifications from mass residential procurement.
- Residential:Volume absorption through government-backed mortgage programs across Riyadh and Jeddah corridors. Standard-grade ceramic and medium-format porcelain dominate this price-sensitive segment.
- Commercial:Hospitality and retail developments under Vision 2030 command premium porcelain specifications with direct manufacturer procurement bypassing distributor markups.
- Industrial:Chemical-resistant and heavy-duty flooring for manufacturing facilities in Jubail and Yanbu industrial cities.
- Outdoor:Frost-resistant and slip-rated tiles for Qiddiya entertainment district hardscaping and municipal infrastructure.
Residential commands volume leadership; commercial applications are climbing the fastest on per-square-meter value.
Size:
Specification cycles compress around large-format adoption in western corridor premium developments.
- Large:Formats above 600x1200mm and thin slabs exceeding 1600x3200mm are displacing natural stone in five-star hotel lobbies. Kiln technician scarcity in the Eastern Province constrains domestic supply expansion.
- Medium:Traditional 300x300mm to 600x600mm formats serving mass residential and standard commercial fit-outs across the Kingdom.
- Small:Mosaic and specialty accent tiles for bathroom and kitchen feature walls, often imported with specialized inkjet glaze formulations.
- Custom:Project-specific dimensions for architect-led developments requiring BIM-integrated specification platforms.
Medium formats retain installed base dominance; large formats are gaining share fastest in new construction.
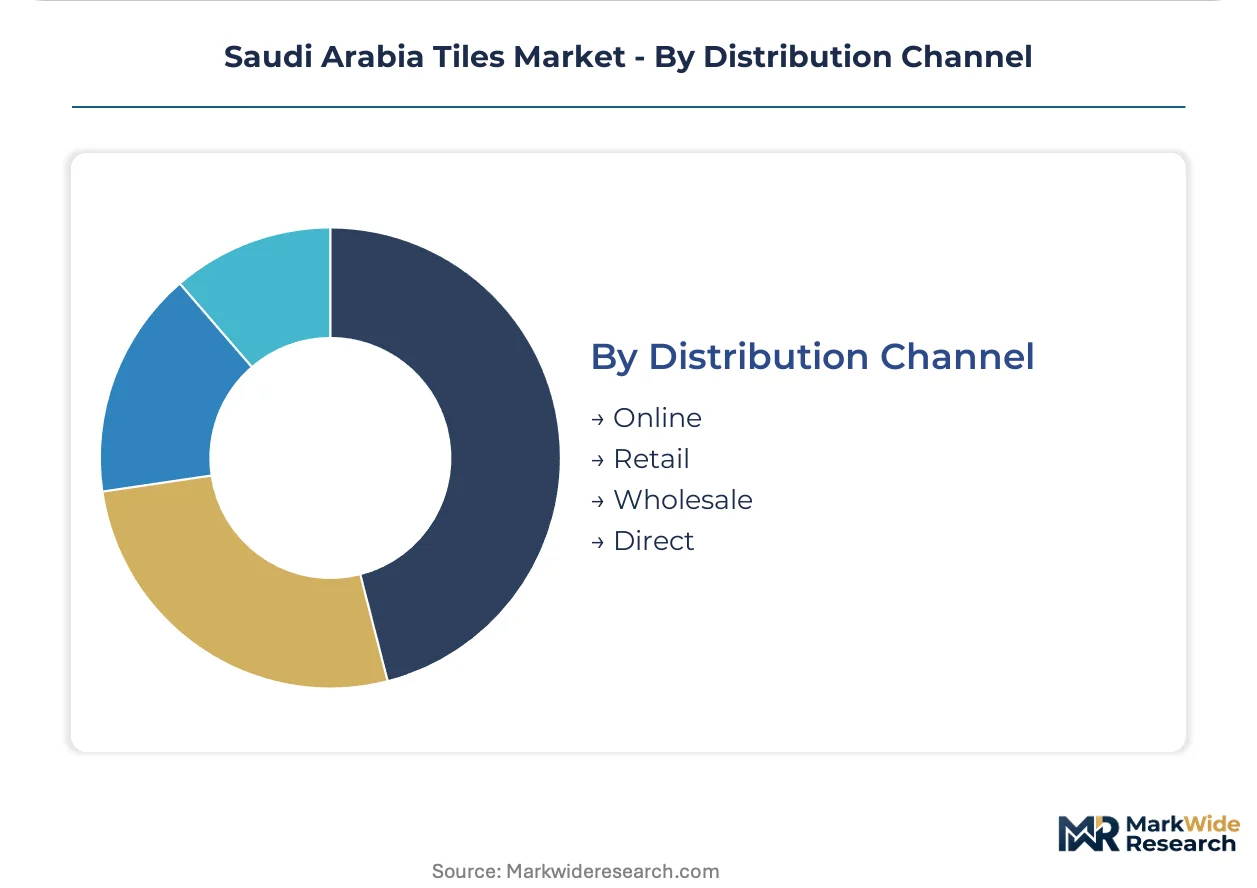
Distribution Channel:
Channel compression is accelerating as architects consolidate procurement through direct manufacturer relationships.
- Direct:Manufacturer-to-developer engagement for NEOM and Red Sea Project consistency requirements, displacing legacy importer margins.
- Wholesale:Project bundling for mid-scale contractors across traditional Riyadh-Jeddah distribution nodes.
- Retail:Showroom-based selection for residential renovation and smaller commercial fit-outs.
- Online:Digital specification platforms enabling architect-manufacturer engagement with virtual sampling and BIM integration.
Wholesale maintains transaction volume leadership; direct channels are expanding most quickly in giga-project corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vision 2030 infrastructure disbursements are redistributing tile demand across Saudi Arabia's economic corridors. The Ministry of Municipal and Rural Affairs channels construction permits through regional municipal clusters, concentrating procurement authority in high-growth zones.
Riyadh
Diriyah Gate and King Salman Park developments are absorbing large-format porcelain volumes for hospitality and cultural assets. SASO certification timelines of 8-12 weeks create inventory bottlenecks for northern corridor contractors. The Riyadh-based Saudi Ceramic Company anchors domestic supply security through integrated kiln operations serving megaproject clusters.
Eastern Province
Jubail and Ras Al-Khair industrial cities generate chemical-resistant flooring demand for petrochemical facilities. The region suffers kiln technician scarcity constraining large-format porcelain supply expansion. Dammam logistics nodes handle glaze imports from Italian suppliers for specialized hospitality specifications.
Western Region
Jeddah's Red Sea Project corridor commands premium thin-slab porcelain for five-star hotel lobbies. King Abdullah Economic City construction is compressing specification cycles to 90-day delivery windows. Makkah residential developments absorb medium-format ceramic through government-backed mortgage programs.
NEOM Northwest
THE LINE and Oxagon construction is forcing direct manufacturer procurement bypassing traditional distributor networks. Tabuk logistics infrastructure is opening distribution nodes beyond Riyadh-Jeddah concentration. The zone's sustainability procurement criteria favor low-carbon ceramic producers with SASO pre-certification.
Saudi Arabia Tiles Market Competitive Environment
Player mix skews toward integrated domestic manufacturers with Riyadh-based kiln assets and regional Gulf producers leveraging scale economies. The competitive structure bifurcates between qualified domestic producers meeting SASO mandates and import-dependent distributors facing certification barriers. Two strategic archetypes dominate: vertically integrated manufacturers controlling raw material through finished product, and regional scale players optimizing cross-border logistics. Capacity expansion and direct architect-manufacturer engagement represent the dominant competitive moves displacing legacy importer margins.
Within the integrated domestic tier, Saudi Ceramic Company and Alfanar Ceramics exemplify supply security strategies through captive manufacturing assets. Among regional Gulf fabricators, RAK Ceramics occupies a position leveraging cross-border production scale for cost positioning in premium porcelain segments. Specialist producers such as Forsan Ceramics and Al Khaleej Ceramics sit within mid-market tiers serving residential mortgage-backed housing expansion. The competitive dynamic concentrates around SASO certification pre-investment as a barrier to giga-project specification access.
| Leading Market Players |
|---|
| Alfanar Ceramics |
| Al Jawdah Ceramic Tiles Company |
| Saudi Ceramic Company |
| Al Khaleej Ceramics |
| Forsan Ceramics |
| RAK Ceramics |
| Arabian Tile Co. |
| Riyadh Ceramics Factory |
| Future Ceramics |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Saudi Ceramic Company and NEOM developers lock in both supply access and price visibility for large-format porcelain volumes, compressing spot-market exposure for qualified domestic producers while elevating procurement costs for import-dependent distributors facing SASO certification delays.
Pricing Analysis
Certification level creates the primary spread between SASO-prequalified domestic output and import-dependent ceramic offerings. Three-tier pricing structure across premium, standard, and economy levels reflects water absorption thresholds, with sub-0.5% porcelain commanding structural premiums for exterior cladding compliance. Cost compression in standard-grade ceramic is intensifying because Egyptian feldspar input volatility feeds directly into margin pressure. Mass residential mortgage-backed buyers exhibit highest price sensitivity, while NEOM hospitality developers prioritize specification consistency over unit cost.
Supply Chain Analysis
Egypt and India anchor feldspar and clay feedstock supply for Saudi kiln operations, while Italy and Spain concentrate specialized inkjet glaze formulations. Raw material dependencies center on Egyptian feldspar, Indian ball clay, and European glaze chemistry. Single-source vulnerability in Italian glaze supply creates procurement risk for premium hospitality specifications. Distribution runs through Riyadh-Jeddah wholesale nodes with emerging Tabuk logistics infrastructure serving NEOM-adjacent demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's tiles market represents a high-growth disruption driven by Vision 2030 giga-project construction, where SASO certification mandates and compressed specification cycles are restructuring competitive access faster than capacity expansion can match.
For Market Incumbents: Compound domestic manufacturing advantage through captive feldspar sourcing and kiln technician training programs in the Eastern Province. SASO testing bottlenecks threaten inventory positioning for giga-project procurement cycles. Backward integration into Egyptian raw material offtake secures margin predictability against input volatility.
For New Entrants and Emerging Players: Anchor in Tabuk logistics infrastructure and NEOM-adjacent distribution nodes beyond traditional Riyadh-Jeddah concentration. Northern Borders expansion offers penetrable white space with sustainability procurement criteria favoring low-carbon ceramic producers. Direct architect engagement through BIM-integrated specification platforms bypasses legacy distributor markups.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with Riyadh-based kiln assets and SASO pre-certification investments. Long-term viability hinges on alignment with giga-project delivery timelines and specification tier access. Watch for SASO enforcement intensity as the inflection indicator for import-dependent distributor margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Riyadh-based kiln upgrades meet Saudi Building Code water absorption mandates for exterior cladding. |
| Backward Integration | Egyptian feldspar offtake agreements reduce exposure to raw material cost volatility from Indian supply. |
| SASO Pre-Certification Investment | Early compliance secures giga-project specification access before certification bottlenecks intensify. |
| Direct Architect Engagement | BIM-integrated specification platforms compress traditional distributor channels in NEOM corridors. |
| Green Manufacturing Transition | Low-carbon kiln operations align with Saudi Green Building Forum procurement criteria for public projects. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SASO certification databases, Ministry of Municipal and Rural Affairs construction permit records, and trade flow documentation from Egyptian and Indian supply sources. Primary interviews engaged plant managers at Riyadh-based kilns, procurement leads at NEOM and Red Sea Project developments, distributor channel partners across Jeddah wholesale nodes, and technical R&D directors specializing in large-format porcelain firing. Bottom-up volume triangulation from kiln capacity utilization and top-down validation against construction disbursement data ensure cross-verified outputs.
Segmentation dimensions modeled include material composition tier, end-use application category, dimensional specification format, and procurement channel structure across the analysis window. CAGRs derive from regression-based projection of construction activity indices against tile intensity coefficients. Industry-specific forecast inputs incorporate Vision 2030 giga-project delivery timelines and SASO certification throughput capacity.
Material uncertainties — giga-project schedule slippage, Egyptian feldspar export restrictions, and kiln technician labor pool expansion — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement consistency and raw material supply continuity. Recalibration cycles align with material shifts in construction disbursement velocity and SASO testing capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Building and Construction Sealants Market