
 Fire Rated Glass Market | 2026-2036
Fire Rated Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Rated Glass Market Intelligence
Healthcare facility construction is restructuring demand patterns across the fire rated glass supply base. SCHOTT AG leverages its ceramic glass technology leadership to anchor premium specification tiers in European hospital projects. SAFTI FIRST specializes in domestically manufactured, UL Listed assemblies that compete on code-compliance speed for North American healthcare contractors. Guardian Glass extends its tempered glass capacity across multiple certification standards to occupy mid-market commercial segments.
Fire rated glass consists of specially engineered transparent or translucent assemblies designed to maintain structural integrity and limit heat transfer during standardized fire exposure periods, typically achieving ratings from 20 minutes to 3 hours depending on core composition and framing integration. Ceramic variants incorporate monolithic borosilicate or clear ceramic layers that withstand thermal shock without shattering, serving primarily to compartmentalize building zones while preserving visual access for emergency response. Laminated glass configurations command margin concentration due to their dual fire-resistance and impact-safety certification, while wired glass faces structural decline as building codes phase out its use in high-traffic applications. Tempered glass segments lead volume throughput in commercial curtain wall installations where moderate fire ratings satisfy code minimums.
The EU's Construction Products Regulation and EN 13501-1 classification system mandate systematic fire performance testing for all marketed glazing assemblies, creating compliance barriers that favor established certification holders. NFPA 80 and UL 9/UL 10C standards in the United States govern fire door and window assembly acceptance, with FDA facility guidelines indirectly shaping pharmaceutical manufacturing plant specifications. Stakeholders must monitor divergence between regional test protocols and emerging demands for combined fire-resistance with ballistic or blast mitigation properties.
Market Dynamics
Healthcare construction procurement is restructuring fire-rated glass demand toward multi-certification assemblies that combine fire resistance with impact safety and ballistic ratings, compressing specification cycles and favoring suppliers with integrated testing capabilities.
Growth Catalysts
- EU Construction Products Regulation updates:Tightened performance declarations for fire-resistant glazing assemblies are mandating systematic third-party testing, elevating certified suppliers and disqualifying marginal producers from hospital and laboratory tenders.
- Ceramic glass technology maturation:Monolithic borosilicate and clear ceramic layers now withstand thermal shock without shattering, enabling compartmentalization with visual access for emergency response in high-occupancy buildings.
- Germany's hospital buildout programs:Federal and state-level healthcare infrastructure investment is concentrating specification authority among large contracting consortia seeking single-source transparent barrier solutions.
Market Restraints
- Borosilicate raw material concentration:Specialty glass substrate production clusters in Central European manufacturing corridors, exposing buyers to energy cost volatility and logistics bottlenecks.
- Wired glass phase-out momentum:Building codes across multiple jurisdictions are prohibiting traditional wired glass in high-traffic applications, forcing premature replacement cycles and stranding installed base value.
- Dual certification cost burden:Simultaneous UL 9/UL 10C and EN 13501-1 testing requirements impose redundant engineering validation expenses on suppliers seeking cross-border market access.
Strategic Opportunities
- Combined fire-ballistic glazing convergence:Integration of fire-resistance ratings with bullet-resistant and blast-mitigation properties opens specification tiers in government, embassy, and critical infrastructure verticals previously served by separate product categories.
- Digital specification platforms:Building information modeling-integrated product libraries are compressing architect and contractor discovery cycles, rewarding early-mover suppliers with parametrically embedded fire-rated assemblies.
- India's healthcare infrastructure expansion:National hospital accreditation standards are incorporating fire-safety transparent barriers, creating first-mover positioning for certified suppliers in an underpenetrated specification environment.
Industry Challenges
- Fire test engineer scarcity:Specialized technicians capable of conducting standardized furnace testing to EN 1363 and ASTM E119 protocols are concentrated among legacy certification bodies, extending product development timelines.
- Framing system integration complexity:Fire-rated glass performance depends on proprietary perimeter sealing and expansion joint engineering, complicating contractor sourcing and field coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Rated Glass Market |
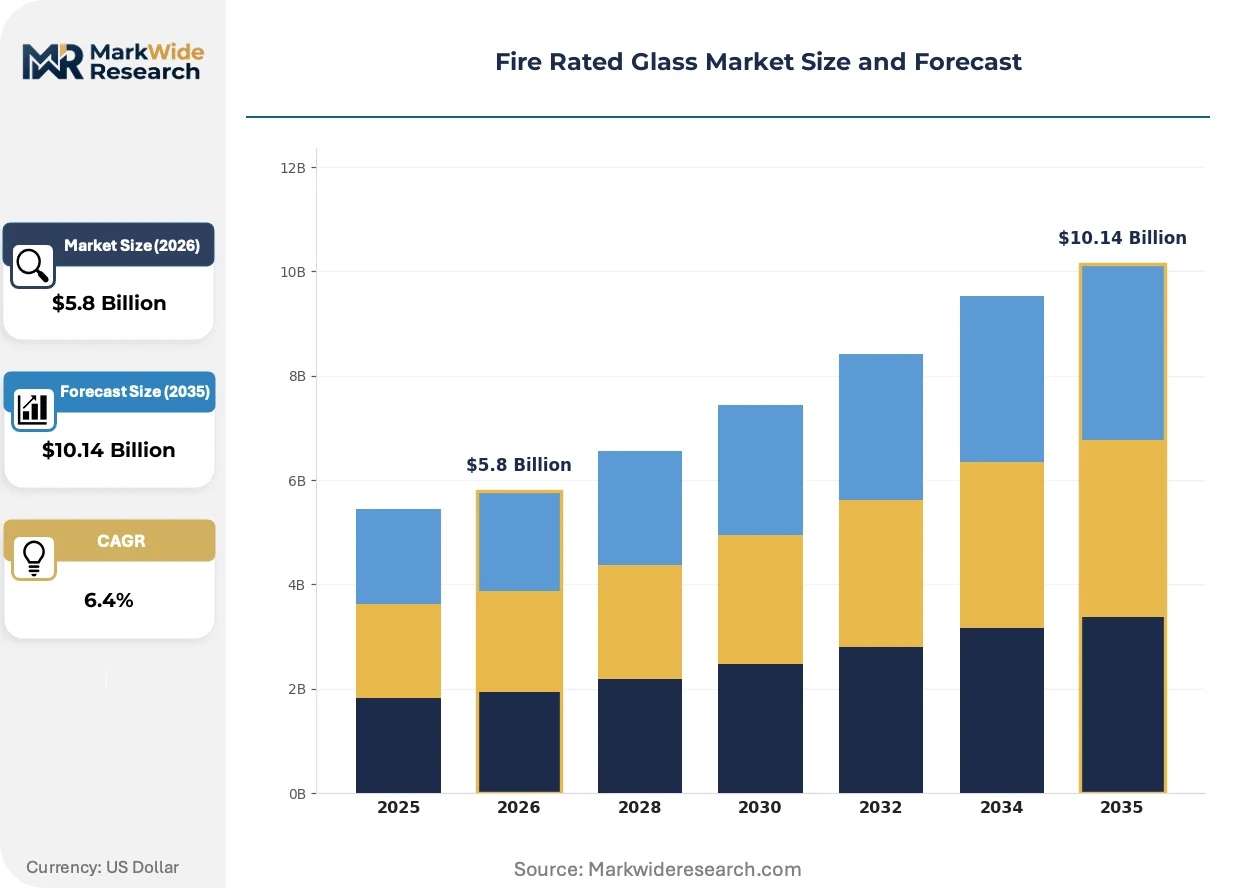
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Glass, Ceramic Glass, Tempered Glass, Laminated Glass End User: Commercial Buildings, Residential Properties, Industrial Facilities, Educational Institutions Certification: UL Listed, BS476, EN 13501-1, NFPA Installation Type: Interior, Exterior, Curtain Wall, Partition |
| Companies Covered | Saint-Gobain, SCHOTT AG, Guardian Glass, Vetrotech Saint-Gobain International AG, Pilkington, AGC Inc., Nippon Sheet Glass Co., Ltd., Pyroguard Ltd., SAFTI FIRST, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Rated Glass Market Strategic Shifts & Innovations
Transparent barrier engineering is converging around multi-hazard performance certification, compressing the traditional separation between fire safety, security, and architectural glazing disciplines into unified specification frameworks.
Monolithic ceramic glass technology is consolidating specification authority in premium healthcare and laboratory segments. German hospital contractors now specify ceramic assemblies for 90-minute and 180-minute ratings as standard. This consolidation is compressing market share for traditional laminated alternatives in high-visibility applications.
REACH chemical restriction expansions are reshaping interlayer material selection for laminated fire-rated configurations. ECHA scrutiny of halogenated flame retardants is accelerating migration toward phosphorus-based and inorganic alternatives. Laminated glass producers serving EU hospital projects are reformulating product lines to maintain CE marking compliance.
Specification authority is concentrating among large healthcare contracting consortia with centralized procurement functions. These buyers now demand bundled fire-resistance, impact safety, and acoustic performance from single-source suppliers. Germany's university hospital construction programs exhibit the most advanced consolidation of transparent barrier requirements.
Fire Rated Glass Market Segmentation
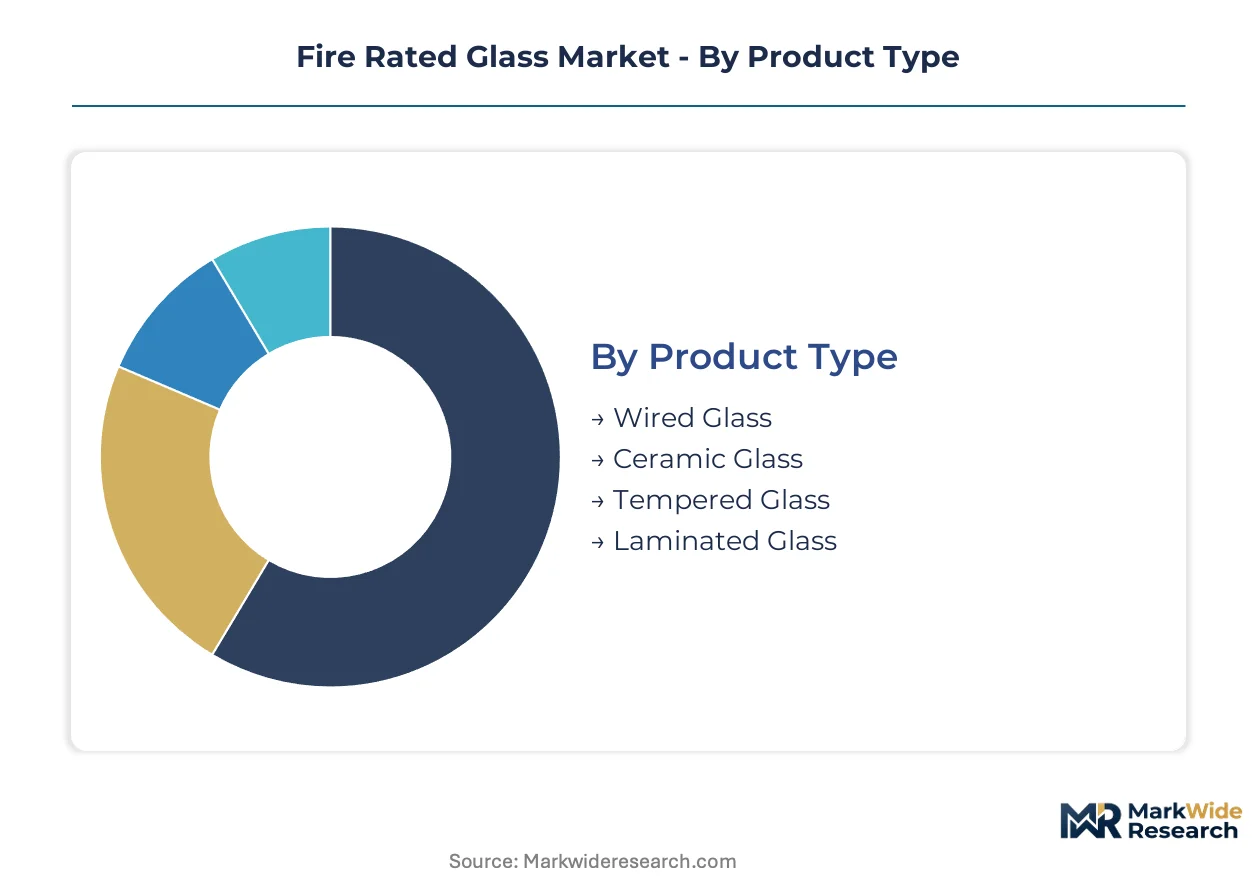
Fire rated glass procurement decisions hinge on certification compatibility, installation complexity, and end-use hazard profiles. Specification authority concentrates among contractors who bundle transparent barrier requirements across multiple performance dimensions.
Product Type:
Capital intensity varies sharply across manufacturing processes, with ceramic glass requiring specialized borosilicate melting furnaces and extended thermal conditioning cycles that constrain entry.
- Ceramic Glass:Monolithic borosilicate or clear ceramic layers withstand thermal shock without shattering, enabling compartmentalization with visual access. German hospital contractors now specify ceramic assemblies for 90-minute and 180-minute ratings as standard procurement practice.
- Laminated Glass:Dual fire-resistance and impact-safety certification commands margin concentration. REACH chemical restrictions are forcing reformulation toward phosphorus-based interlayers to maintain CE marking compliance for EU healthcare projects.
- Tempered Glass:Volume leader in commercial curtain wall installations where moderate fire ratings satisfy code minimums.
- Wired Glass:Faces structural decline as building codes phase out its use in high-traffic applications across multiple jurisdictions.
Tempered glass absorbs the bulk of installed capacity; ceramic glass is expanding most quickly.
End User:
Application risk profiles determine specification stringency, with occupancy density and evacuation complexity driving rating requirements.
- Commercial Buildings:Curtain wall and atrium applications dominate volume, with tempered glass satisfying 20-45 minute ratings for office towers. Procurement favors suppliers with UL 9 and EN 13501-1 dual certification to streamline cross-border project execution.
- Educational Institutions:K-12 and university construction prioritizes impact safety alongside fire ratings. Laminated configurations gain specification share as wired glass phase-outs accelerate in corridor and common-area applications.
- Industrial Facilities:Pharmaceutical manufacturing plants incorporate FDA facility guidelines into transparent barrier specifications.
- Residential Properties:High-rise multifamily construction drives demand for 60-90 minute rated assemblies in exit enclosures.
Commercial buildings anchor current procurement volume; educational institutions are climbing the fastest as code enforcement tightens.
Certification:
Testing protocol divergence creates redundant engineering validation expenses for suppliers seeking cross-border market access.
- EN 13501-1:EU Construction Products Regulation mandates systematic fire performance testing for all marketed glazing assemblies. ECHA scrutiny of halogenated flame retardants is reshaping interlayer material selection for laminated configurations.
- UL Listed:UL 9/UL 10C standards govern fire door and window assembly acceptance in North American healthcare construction. SAFTI FIRST specializes in domestically manufactured assemblies that compete on code-compliance speed.
- NFPA:NFPA 80 standards provide installation and maintenance requirements for fire-rated opening protectives.
- BS476:British Standard fire tests remain relevant for UK-specific projects and Commonwealth legacy specifications.
EN 13501-1 absorbs the bulk of third-party testing investment; UL Listed certification is gaining share fastest in North American healthcare verticals.
Installation Type:
Field coordination complexity escalates with perimeter sealing and expansion joint engineering requirements that tie glass performance to proprietary framing systems.
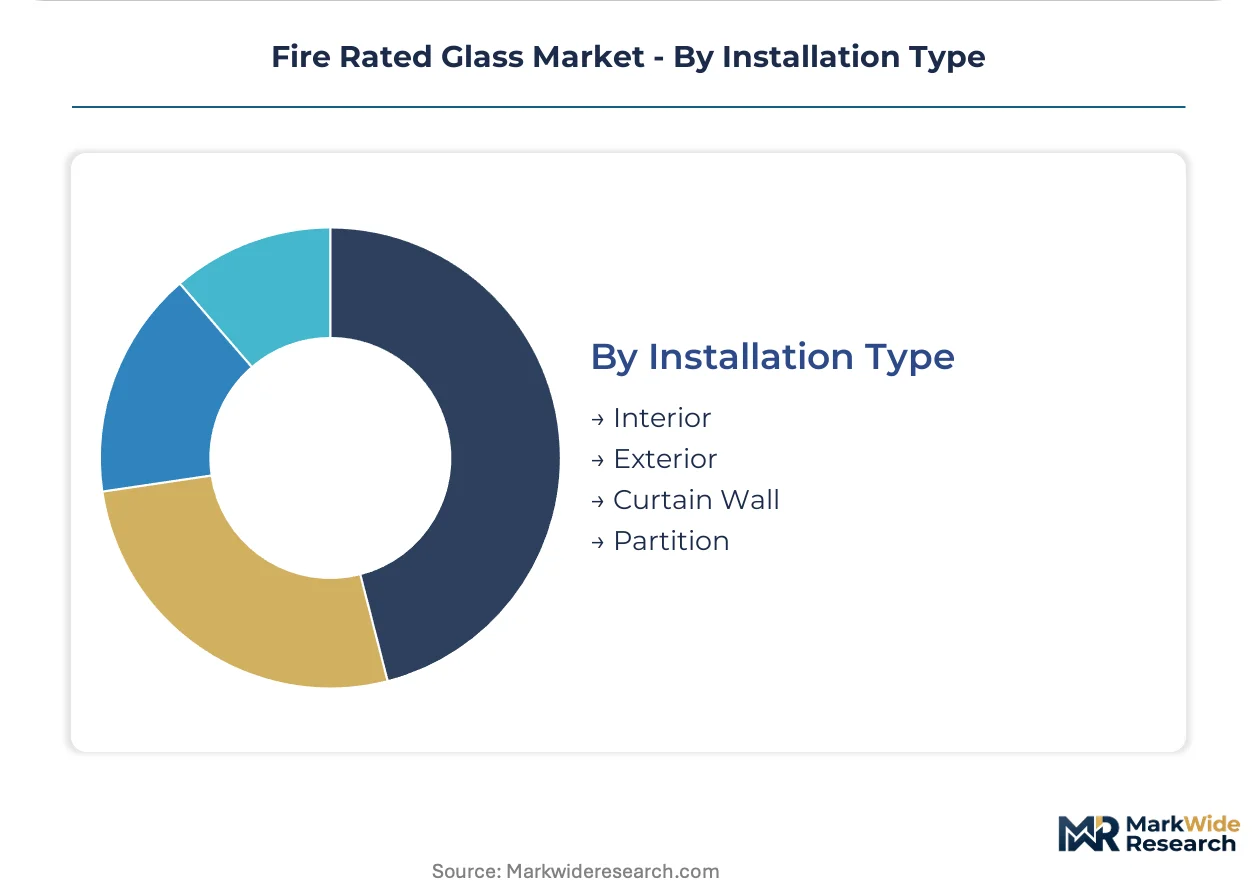
- Curtain Wall:Large-format ceramic panels enable 90-180 minute ratings in high-visibility healthcare atriums. German university hospital construction programs exhibit the most advanced consolidation of transparent barrier requirements in this category.
- Partition:Interior compartmentalization demands combine fire resistance with acoustic performance. Large healthcare contracting consortia now demand bundled specifications from single-source suppliers.
- Interior:Corridor and exit enclosure applications face wired glass replacement cycles as codes prohibit traditional products.
- Exterior:Façade applications require weathering resistance alongside fire performance, complicating material selection.
Curtain wall installations absorb the bulk of premium ceramic glass volume; partition applications are expanding most quickly as healthcare procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German free economic zones around Stuttgart and Munich concentrate specialty borosilicate melting capacity for ceramic fire-rated glass production. Federal hospital infrastructure programs channel procurement through centralized contracting consortia seeking integrated transparent barrier solutions.
Germany
Federal hospital buildout programs and university medical center expansions drive specification demand for 90-180 minute rated ceramic assemblies. The EU Construction Products Regulation mandates EN 13501-1 certification for all marketed glazing, elevating established testing holders. Stuttgart and Munich industrial corridors host concentrated borosilicate substrate production serving premium healthcare verticals.
United States
Healthcare facility construction and pharmaceutical manufacturing plant upgrades propel demand for UL Listed fire-rated assemblies. NFPA 80 and UL 9/UL 10C standards govern fire door and window acceptance, with FDA facility guidelines shaping transparent barrier specifications. Northeast and California metropolitan construction markets exhibit the tightest code enforcement for high-occupancy building retrofits.
China
Urban hospital infrastructure expansion and high-rise residential exit enclosure regulations accelerate tempered glass volume procurement. GB standards for fire-resistant building materials mandate systematic testing, with provincial construction bureaus tightening enforcement in tier-one cities. Yangtze River Delta manufacturing clusters supply moderate fire-rated curtain wall glass for commercial tower developments.
India
National hospital accreditation standards are incorporating fire-safety transparent barriers into healthcare infrastructure guidelines. BIS certification requirements for fire-resistant glazing create compliance entry barriers for imported assemblies. Maharashtra and Karnataka state-level medical college construction programs concentrate specification authority among large contracting entities.
United Kingdom
Educational institution retrofits and high-rise residential remediation programs displace legacy wired glass installations. BS476 fire tests remain relevant alongside EN 13501-1 for domestic projects, with London boroughs enforcing the strictest corridor and common-area specifications. Midlands manufacturing bases supply laminated configurations combining fire resistance with impact safety certification.
Fire Rated Glass Market Key Industry Players
Top-tier vendors anchor premium specification tiers in European healthcare projects, while mid-market fabricators compete on certification breadth and domestic manufacturing proximity. The vendor base stratifies across ceramic technology specialists, tempered glass volume producers, and laminated configuration engineers. Three strategic archetypes dominate: borosilicate substrate specialists, multi-certification assembly integrators, and curtain wall system bundlers. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as procurement consolidates around single-source transparent barrier suppliers.
Within the ceramic technology tier, SCHOTT AG exemplifies monolithic borosilicate specialization for extended fire ratings in hospital atriums. SAFTI FIRST occupies a position among North American fabricators emphasizing domestically manufactured UL Listed assemblies. Saint-Gobain and its Vetrotech International AG subsidiary anchor integrated glass-to-system supply positions across European and global healthcare verticals.
| Leading Market Players |
|---|
| Saint-Gobain |
| SCHOTT AG |
| Guardian Glass |
| Vetrotech Saint-Gobain International AG |
| Pilkington |
| AGC Inc. |
| Nippon Sheet Glass Co., Ltd. |
| Pyroguard Ltd. |
| SAFTI FIRST |
| Others |
Cost & Logistics Intelligence
German hospital contracting consortia anchor procurement volume for fire-rated glass, compressing specification cycles and favoring suppliers with integrated testing capabilities who can command premium positioning through bundled certification packages.
Pricing Analysis
Short lead-time premiums separate urgent healthcare project procurement from standard commercial schedules, with ceramic glass assemblies for 90-180 minute ratings commanding substantial markups over tempered alternatives. Three-tier pricing structure across premium ceramic, standard laminated, and economy tempered levels reflects certification complexity and raw material grade. Cost compression in mid-market segments is intensifying because REACH-compliant interlayer reformulation adds engineering validation expense. Educational institutions exhibit the highest price sensitivity due to budget-constrained wired glass replacement cycles, while German university hospital programs show lowest sensitivity given federal infrastructure funding.
Supply Chain Analysis
Dual-sourcing requirements from large European healthcare contractors mandate multi-supplier qualification for borosilicate substrate and ceramic melting capacity, mitigating single-source vulnerability in Central European manufacturing corridors. Production gravity centers on Germany, China, and the United States for finished assemblies, with specialty borosilicate melting concentrated in Stuttgart and Munich industrial zones. Raw material feeds from soda ash, boron compounds, and specialized ceramic frits draw from established chemical supply bases. Energy cost volatility in EU manufacturing corridors represents the dominant supply chain risk. Distribution runs through specification-influencing architectural glazing distributors and direct contracting relationships with healthcare construction consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire-rated glass competitive dynamics have shifted into a vertical-integration race, with control over borosilicate melting capacity and in-house furnace testing capabilities determining specification access in premium healthcare verticals.
For Market Incumbents: Lock in ceramic technology leadership by securing captive borosilicate supply agreements and expanding EN 13501-1 testing capacity ahead of EU Construction Products Regulation enforcement waves. Defend against emerging multi-hazard glazing specialists by accelerating fire-ballistic certification convergence. Prioritize backward integration into specialty glass substrate production to isolate margin from energy cost volatility. For New Entrants and Emerging Players: Enter via India's underpenetrated healthcare infrastructure vertical, where national hospital accreditation standards are newly incorporating fire-safety transparent barriers without entrenched incumbent relationships. Target state-level medical college construction programs in Maharashtra and Karnataka as specification entry points. Pursue BIS certification partnerships with established testing bodies to compress compliance timelines. For Investors and Strategic Acquirers: The window for entry favors ceramic technology specialists with existing EN 13501-1 and UL 9/UL 10C dual certification assets, as regulatory barriers steepen and fire test engineer scarcity extends product development timelines. Monitor German federal hospital infrastructure budget allocations as the critical inflection signal for demand acceleration in premium rating tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Glass Capacity Expansion | Captures 90-180 minute rating demand from German hospital buildout programs. |
| Multi-Certification Integration | Combines EN 13501-1, UL 9/UL 10C, and ballistic ratings for government vertical access. |
| Borosilicate Supply Agreement | Secures raw material flow from Stuttgart and Munich melting corridors. |
| Digital Specification Platform | Embeds parametric fire-rated assemblies in BIM libraries for architect discovery. |
| India Market Entry Partnership | Navigates BIS certification requirements through local testing body relationships. |
Research Approach
Document review covered regulatory filings from ECHA and FDA, customs trade databases, and hospital procurement records, complemented by interviews with architectural specification consultants, healthcare contracting consortium procurement directors, fire test laboratory engineers, and ceramic glass manufacturing plant managers. Secondary validation drew from EN 13501-1 certification registries, UL Listed product directories, and EU Construction Products Regulation compliance databases. Bottom-up volume estimates from installation type and end-use segmentation were cross-referenced against top-down market sizing from industry association reports.
Historical shipment data was cross-referenced against expert panel input from specification influencers and testing body technical directors. Segmentation modeling incorporated product type, end user vertical, certification standard, and installation configuration dimensions across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement timelines and infrastructure program funding cycles. Industry-specific inputs included German federal hospital construction budgets and REACH chemical restriction implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt energy cost spikes or accelerated wired glass phase-out enforcement. Deviation in EU Construction Products Regulation third-party testing capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Customized Shopfitting Materials Market