
 Residential Elevator Market | 2026-2036
Residential Elevator Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Elevator Market Analysis
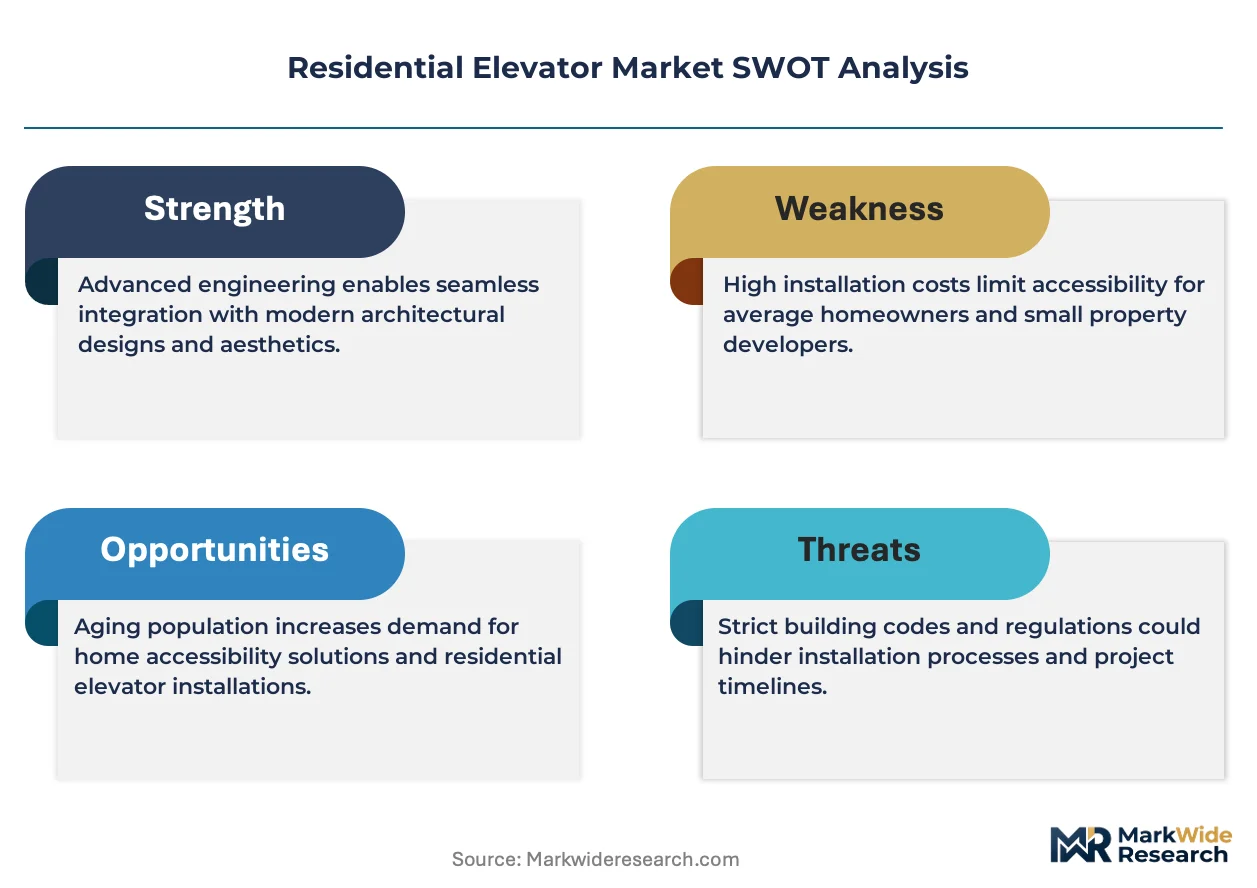
The price-performance gap between premium custom installations and standard modular systems is hardening across the residential elevator landscape. TK Elevator leverages its German engineering heritage to dominate high-rise residential retrofit projects in dense urban cores. Savaria anchors the North American accessibility segment through specialized vertical platform and wheelchair lift integration. Schindler Elevator Corporation extends its service network advantage to capture recurring maintenance revenue from installed base expansion.
A residential elevator is a vertically transporting device engineered for private dwelling use, typically rated for capacities between two and eight persons with travel speeds under one meter per second and machine-room-less or compact machine-room configurations. Its primary purpose is to provide mobility access across multiple floor levels within single-family homes, townhouses, and small multi-unit residential buildings. Traction systems now lead value generation due to energy efficiency gains and reduced pit depth requirements in retrofit applications. Hydraulic technology retains dominance in heavy-load custom installations where smooth acceleration control and cost-effective maintenance cycles matter most to residential developers. Pneumatic and vacuum alternatives occupy niche positions where space constraints eliminate traditional hoistway infrastructure entirely.
The American Society of Mechanical Engineers governs safety codes through ASME A17.1/CSA B44 standards, while the EU Machinery Directive mandates CE conformity assessment and the European Committee for Standardization publishes EN 81-41 for private-use lifts. These frameworks shape product design, installation liability, and cross-border market access for manufacturers serving multiple jurisdictions. Stakeholders must monitor evolving accessibility mandates from the Department of Justice and state-level building codes that progressively extend elevator requirements beyond wheelchair users to broader mobility-impaired populations. The regulatory trajectory points toward harmonized safety standards that will favor manufacturers with pre-certified platform architectures and documented compliance traceability.
Market Dynamics
The retrofit imperative is compressing installation timelines across aging housing stock in suburban United States corridors, forcing manufacturers to engineer machine-room-less traction systems that minimize structural modification requirements.
Growth Catalysts
- Aging-in-place demographics:Florida and Arizona retirement clusters are driving single-family home elevator retrofits as mobility-impaired homeowners seek multi-floor accessibility without relocating.
- ASME A17.1/CSA B44 harmonization:Unified North American safety standards are reducing certification duplication costs for manufacturers serving cross-border residential construction markets.
- Traction drive efficiency:Regenerative motor technology and reduced pit depth specifications are opening retrofit applications previously closed to hydraulic alternatives.
Market Restraints
- Steel and copper input volatility:Hoistway structural components and electrical winding materials face commodity price swings that compress margin predictability for custom installation contractors.
- German and Swiss supply concentration:Precision gearbox and controller module sourcing clusters in Central European manufacturing basins create geopolitical exposure for North American and Middle Eastern project timelines.
- Hoistway dimensional constraints:Pre-1980s residential construction with narrow stairwell footprints limits traction system retrofit feasibility without major structural intervention.
Strategic Opportunities
- United Arab Emirates luxury villa segment:High-net-worth developers in Dubai and Abu Dhabi are specifying private lift installations as standard amenity packages for aging-in-place marketing positioning.
- CE marking pathway expansion:EU Machinery Directive conformity assessment pre-certification creates first-mover advantage for manufacturers targeting European single-family accessibility retrofits.
- Pneumatic-vacuum convergence:Glass cylinder self-supporting designs eliminate pit and machine room requirements entirely, opening heritage building adaptations where structural preservation mandates apply.
Industry Challenges
- Certified elevator technician scarcity:Journeyman licensure requirements and apprenticeship pipeline gaps in Florida, Arizona, and Texas extend installation backlogs beyond twelve months for specialty contractors.
- Legacy hydraulic system integration:Maintenance revenue capture from installed base requires proprietary controller compatibility that conflicts with open-architecture traction retrofit sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Elevator Market |
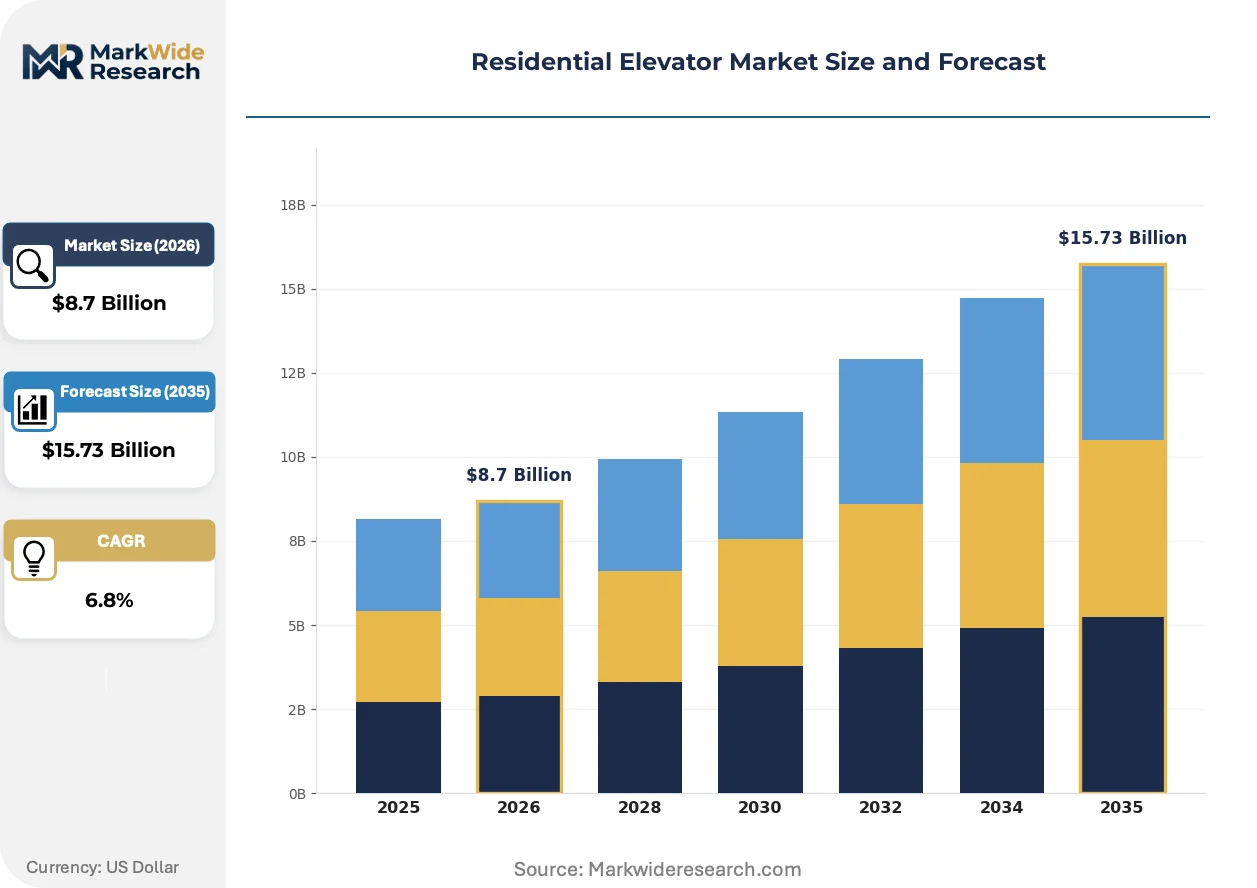
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Traction, Pneumatic, Vacuum Installation Type: Indoor, Outdoor, Modular, Custom Capacity: 2 Persons, 4 Persons, 6 Persons, 8 Persons Power Source: Electric, Solar, Hybrid, Manual |
| Companies Covered | Cambridge Elevating, Lifeway Mobility, Inclinator, TK Elevator, AmeriGlide, Savaria, Arrow Lift, Schindler Elevator Corporation, Stannah, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Elevator Market Emerging Trajectories
Digital control architectures and predictive maintenance platforms are redefining how residential elevator manufacturers capture lifetime value beyond initial equipment sales.
Machine-room-less traction technology is decentralizing installation site preparation requirements across North American suburban retrofit markets. Custom home builders in Florida retirement corridors are specifying these systems for their reduced pit depth and overhead clearance demands. The structural consequence is decentralizing project timelines from traditional six-month hoistway construction windows to three-week mechanical installation cycles.
EU Machinery Directive enforcement is tightening CE conformity assessment documentation for private-use lift manufacturers exporting into European markets. The European Committee for Standardization's EN 81-41 framework now mandates traceable safety component certification that extends liability to installation contractors. German and Italian residential developers are responding by pre-specifying pre-certified platform architectures to accelerate building permit approvals.
After-sales service unbundling is fragmenting traditional maintenance contract structures in United States suburban markets. Independent service contractors in Arizona and Florida are capturing annual inspection and repair revenue through third-party controller diagnostics platforms. This behavioral shift is most visible in Sun Belt retirement communities where homeowners association governance structures favor competitive bidding over manufacturer-captive service agreements.
Residential Elevator Market Segmentation
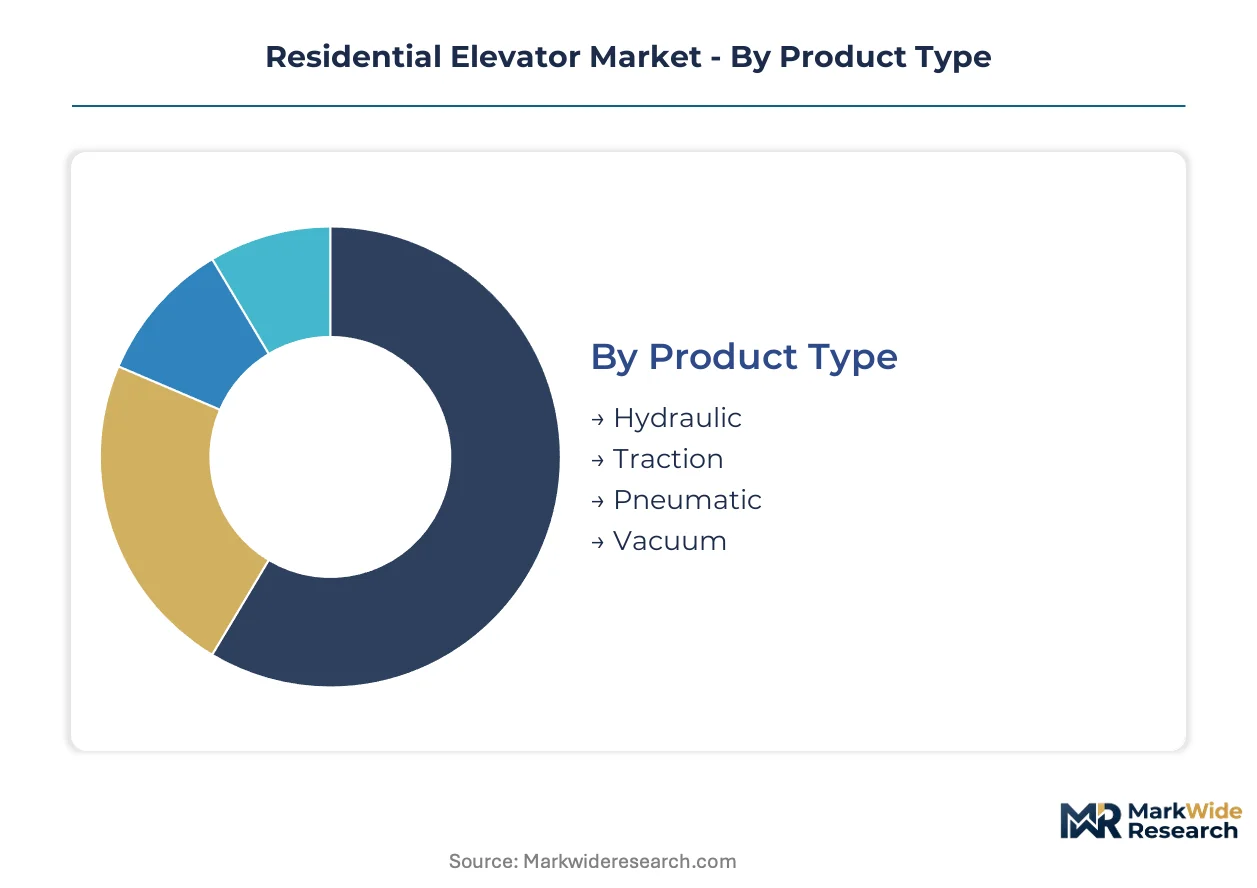
Residential elevator procurement diverges sharply between retrofit accessibility projects and new luxury construction. Segment boundaries reflect technical constraints, structural feasibility, and homeowner mobility requirements across single-family and multi-unit dwellings.
Product Type:
Traction systems command the volume tier through energy efficiency and reduced pit requirements, while hydraulic installations retain the premium tier for heavy-load custom applications.
- Hydraulic:Piston-driven lifting mechanisms using fluid pressure deliver smooth acceleration control for capacities exceeding 450 kg. Demand concentrates in United Arab Emirates luxury villa developments where developers prioritize ride quality and cost-effective maintenance cycles for aging-in-place marketing.
- Traction:Counterweight-equipped electric drives with regenerative motor technology eliminate machine room requirements entirely. Florida and Arizona retirement corridors are driving adoption as narrow stairwell footprints in 1970s-era construction limit hydraulic retrofit feasibility without structural intervention.
- Pneumatic:Air pressure differential systems operate within self-supporting polycarbonate cylinders requiring no pit or hoistway.
- Vacuum:Turbine-based suction mechanisms lift cab assemblies through vertical tubes for heritage building adaptations.
Mature deployment sits with hydraulic technology. Newer deployment is concentrated in traction systems.
Installation Type:
Indoor specifications dominate retrofit volume, while outdoor and custom installations capture premium margins through weatherproofing and architectural integration.
- Indoor:Hoistway-integrated systems within conditioned building envelopes represent standard residential configurations. Arizona and Florida suburban clusters are accelerating single-family retrofits as homeowners seek multi-floor accessibility without relocation.
- Outdoor:Weather-sealed shaft structures with marine-grade finishes attach to building exteriors where interior footprint constraints eliminate conventional placement.
- Modular:Pre-engineered self-contained units with factory-built hoistways compress on-site construction timelines to under three weeks.
- Custom:Architect-specified cab finishes, door configurations, and control interfaces align with interior design schemes.
Volume procurement favors modular systems. Architectural differentiation drives custom specification.
Capacity:
Four-person ratings capture the accessibility retrofit core, while two-person units and six-to-eight person configurations serve opposite ends of the dwelling size spectrum.
- 2 Persons:Compact cab dimensions of 0.9m by 1.2m accommodate wheelchair users with single attendants in narrow townhouses.
- 4 Persons:Standard 320 kg rated capacity with 1.1m by 1.4m platform dimensions serves single-family home retrofits. United States suburban corridors are concentrating demand here as aging-in-place demographics seek mobility solutions for multi-level residences.
- 6 Persons:450 kg ratings support multi-generational households with frequent passenger traffic.
- 8 Persons:630 kg maximum residential ratings address luxury estate requirements with entertainment and service staff mobility needs.
Accessibility mandates anchor four-person deployment. Estate-scale construction is expanding most quickly in eight-person configurations.
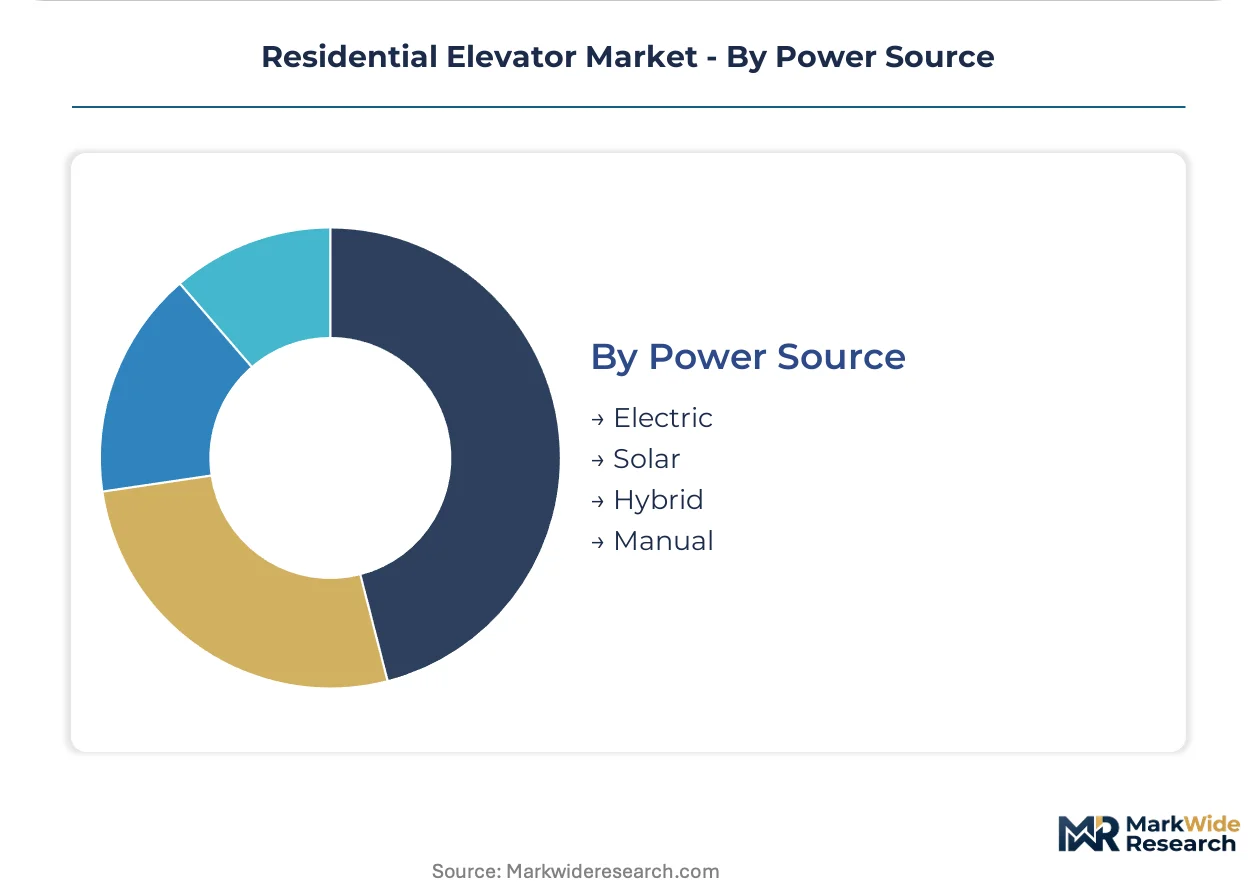
Power Source:
Electric drives dominate through grid connectivity and controller precision, while solar and hybrid alternatives address off-grid and sustainability positioning.
- Electric:Three-phase or single-phase motor controllers with variable frequency drives deliver precise floor leveling and regenerative braking. Standard specification across all installation types due to utility infrastructure ubiquity.
- Solar:Photovoltaic panel arrays with battery storage eliminate grid dependency for rural properties beyond utility service boundaries.
- Hybrid:Grid-tied primary systems with solar backup maintain operation during outage events.
- Manual:Hand-cranked or counterweight-assisted mechanisms serve emergency egress requirements where power failure protocols mandate backup operation.
Grid-tied electric systems anchor current deployment. Solar-hybrid configurations are gaining share fastest in remote luxury construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's retirement corridors anchor residential elevator demand as aging-in-place demographics reshape suburban accessibility infrastructure across single-family housing stock.
United States
Arizona and Florida suburban clusters are accelerating single-family retrofits as mobility-impaired homeowners seek multi-floor accessibility without relocation. ASME A17.1/CSA B44 harmonization reduces certification duplication costs for manufacturers serving cross-border construction markets. Dallas-Fort Worth metroplex contractors report twelve-month installation backlogs due to certified technician scarcity.
Germany
Precision gearbox and controller module sourcing concentrates in Central European manufacturing basins, creating supply chain exposure for export-dependent projects. EU Machinery Directive enforcement tightens CE conformity assessment documentation for private-use lift manufacturers. Stuttgart industrial corridor firms leverage German engineering heritage to dominate high-rise residential retrofit specifications.
United Arab Emirates
Luxury villa developers in Dubai and Abu Dhabi are specifying private lift installations as standard amenity packages for aging-in-place marketing positioning. MOHAP safety certification protocols align with international accessibility standards for high-net-worth residential construction. Sharjah emerging as secondary fabrication hub for modular system assembly serving Gulf Cooperation Council markets.
Japan
Compact machine-room-less traction systems address narrow urban footprints in Tokyo and Osaka metropolitan housing stock. METI building efficiency mandates favor regenerative motor technology in residential retrofits. Nagoya industrial belt manufacturers supply precision drive components to domestic accessibility renovation contractors.
Canada
CSA B44 adoption harmonizes with ASME standards for cross-border equipment certification in Ontario and British Columbia retirement communities. Health Canada accessibility guidelines extend elevator requirements beyond wheelchair users to broader mobility-impaired populations. Vancouver metropolitan area sees concentrated demand for outdoor weather-sealed shaft installations in coastal climate conditions.
Residential Elevator Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the residential elevator landscape. The vendor base fragments across three strategic tiers: German-engineered premium specialists, North American accessibility-focused integrators, and modular system fabricators serving volume retrofit markets. Consolidation pressure concentrates among service network operators seeking recurring maintenance revenue from installed base expansion. Dominant competitive moves include geographic expansion into Sun Belt retirement corridors and portfolio diversification toward machine-room-less traction platforms.
Among German-engineered specialists, TK Elevator and Schindler Elevator Corporation exemplify the premium-tier archetype through heritage positioning in dense urban cores. Savaria anchors the North American accessibility segment as a representative of the specialized vertical platform integration archetype. These three firms occupy positions that reflect contrasting strategic emphases: engineering pedigree, service network scale, and segment-specific accessibility focus respectively.
| Leading Market Players |
|---|
| Cambridge Elevating |
| Lifeway Mobility |
| Inclinator |
| TK Elevator |
| AmeriGlide |
| Savaria |
| Arrow Lift |
| Schindler Elevator Corporation |
| Stannah |
| Others |
Supply Flow & Price Mechanics
Luxury villa developers in the United Arab Emirates anchor premium pricing power through bundled amenity specifications that tie elevator costs to aging-in-place marketing outcomes. Their procurement concentration around German-engineered systems sustains value-based pricing tiers while compressing margin negotiation space for modular alternatives.
Pricing Analysis
Uptime-guaranteed service contracts anchor value-based pricing for traction system retrofits in Florida and Arizona retirement corridors. Three-tier pricing structure across premium custom installations, standard modular systems, and economy accessibility lifts stratifies buyer segments by certification grade and after-sales bundling. Cost compression in economy tiers intensifies because independent service contractors unbundle maintenance revenue through third-party diagnostics platforms. Accessibility-focused homeowners exhibit highest price sensitivity, while luxury estate developers demonstrate lowest sensitivity to base equipment costs.
Supply Chain Analysis
Dual-sourcing requirements from North American project developers mandate qualified suppliers for precision gearboxes in both Germany and Switzerland alongside controller modules from Italy. Steel and copper winding materials draw from German, Japanese, and South Korean metallurgical suppliers. Single-source vulnerability concentrates in Central European manufacturing basins for compact machine-room-less drive components. Distribution runs through manufacturer-captive service networks in dense urban cores and independent contractors in suburban retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential elevator market sits in a technology-transition phase as machine-room-less traction systems displace legacy hydraulic infrastructure across aging housing stock. Regenerative motor efficiency and reduced pit depth specifications are accelerating this substitution curve.
For Market Incumbents: Cement service network density in Sun Belt retirement corridors to capture recurring maintenance revenue from installed base expansion. Prioritize backward integration into controller module production to preserve proprietary compatibility against open-architecture traction retrofit threats. Lock in certified technician apprenticeship pipelines in Florida, Arizona, and Texas to resolve twelve-month installation backlogs.
For New Entrants and Emerging Players: Capture pneumatic-vacuum niche applications in heritage building adaptations where structural preservation mandates eliminate conventional hoistway requirements. Target United Arab Emirates luxury villa developers with glass cylinder self-supporting designs as standard amenity packages. Lead with CE marking pre-certification to accelerate European single-family accessibility retrofit permit approvals.
For Investors and Strategic Acquirers: Distressed-cycle entries favor modular system fabricators with pre-certified platform architectures in North American volume retrofit markets. Long-term viability hinges on manufacturers with documented compliance traceability across ASME A17.1 and EU Machinery Directive frameworks. Watch for inflection in steel and copper commodity volatility as margin predictability signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine-Room-Less Traction Platform Expansion | Opens 1970s-era suburban retrofits previously closed to hydraulic systems in Florida corridors. |
| CE Marking Pre-Certification Investment | Accelerates building permit approvals for European private-use lift exports under EN 81-41. |
| Certified Technician Apprenticeship Pipeline | Resolves installation backlogs exceeding twelve months in Arizona and Texas markets. |
| Pneumatic-Vacuum Heritage Adaptation Line | Captures structural preservation mandates eliminating conventional hoistway infrastructure. |
| Independent Service Contractor Diagnostics Platform | Unbundles maintenance revenue from manufacturer-captive agreements in Sun Belt communities. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with elevator installation contractors, certified technician training program directors, luxury home developers, and accessibility renovation specialists combined with ASME standards documentation, EU Machinery Directive enforcement records, and building permit databases. Bottom-up project pipeline tracking and top-down construction spending triangulation validated volume estimates.
Granularity-level modeling disaggregated traction, hydraulic, pneumatic, and vacuum technologies across indoor, outdoor, modular, and custom installation types. Capacity segmentation at 2-person, 4-person, 6-person, and 8-person ratings intersected with electric, solar, hybrid, and manual power sources across the analysis window. CAGRs derived from housing stock age profiles, demographic mobility impairment incidence, and retrofit feasibility matrices. Commodity price volatility indices for steel and copper informed margin sensitivity scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASME A17.1 harmonization timing and EU Machinery Directive enforcement intensity. Deviation in certified technician licensure pipeline expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Composite Roof Shingle Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market