
 Cement Roofing Sheets Market | 2026-2036
Cement Roofing Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Roofing Sheets Market Insights
Preventive maintenance contracts and extended warranty services is realigning how cement roofing sheets get monetized beyond the initial product sale. Everest Industries leverages its dealer network to bundle installation support with material supply across South Asian markets. CRH plc anchors its European footprint through captive distribution to large contractor accounts. Onduline differentiates via polymer-modified cement blends that extend service intervals in tropical climates.
Cement roofing sheets are rigid building envelope components manufactured from Portland cement composites or fiber-reinforced cement matrices, typically formed under high-pressure extrusion or Hatschek process rolling to achieve corrugated, flat, or interlocking profiles with water resistance and thermal insulation. Their primary purpose spans residential, commercial, and agricultural structures requiring durable, fire-resistant roof coverage at lower lifecycle cost than metal alternatives. Corrugated sheets dominate volume due to decades of builder familiarity and minimal tooling requirements for installation. Fiber cement compositions command premium positioning as asbestos phasedown regulations tighten across multiple jurisdictions. Agricultural sheds represent the fastest-growing end-use application as mechanized farming expands storage infrastructure in emerging economies.
India's BIS and the EU's REACH framework both constrain asbestos cement formulations while accelerating fiber cement substitution. India's CEA building energy codes and the EU Green Deal embodied-carbon thresholds are reshaping material specifications and import access conditions. Stakeholders must monitor evolving national bans on asbestos content and corresponding raw material certification requirements to anticipate sourcing disruptions and product line transitions.
Market Dynamics
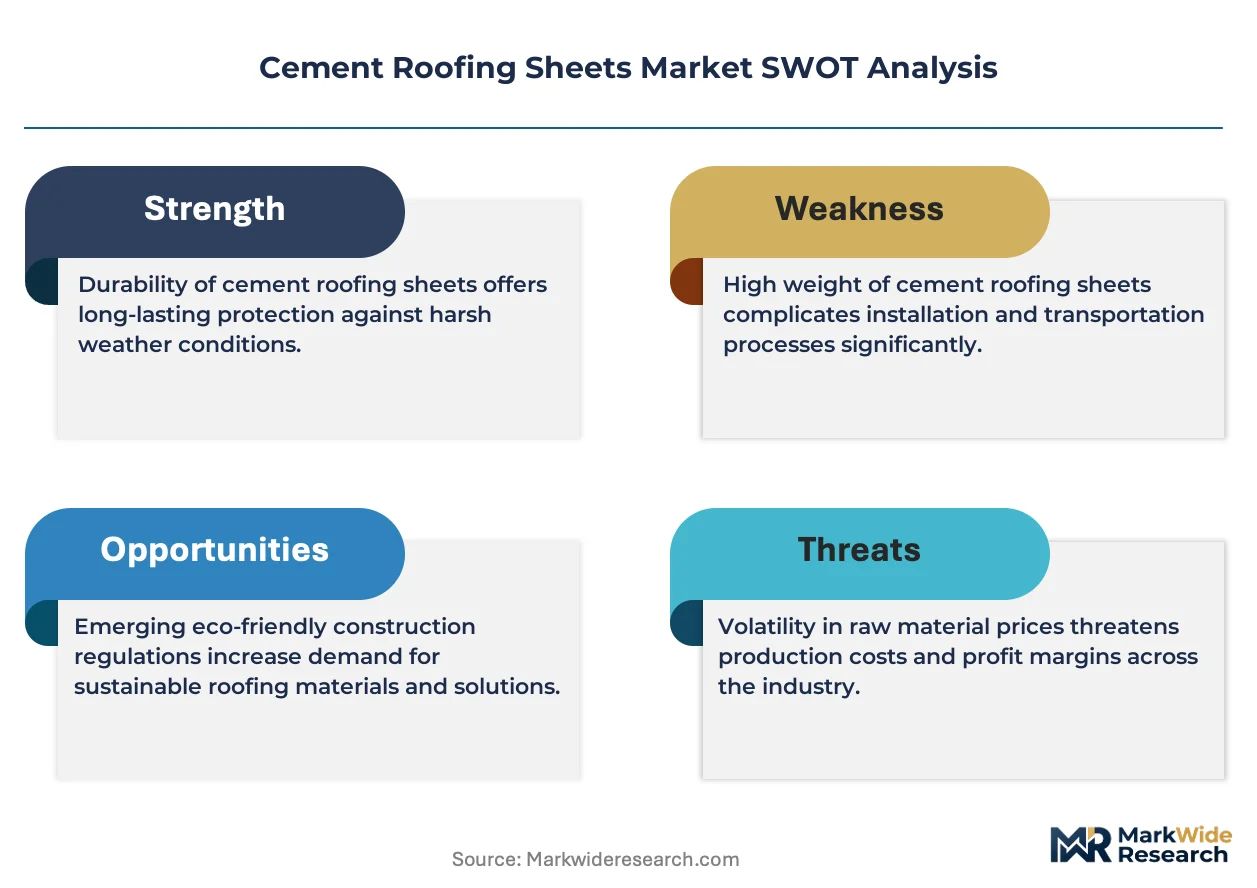
Asbestos phasedown mandates across multiple jurisdictions are forcing a raw material transition toward cellulose and synthetic fiber reinforcements, compressing legacy supply chains while opening premium positioning for compliant manufacturers.
Growth Catalysts
- Agricultural mechanization:Farm equipment storage sheds in India's Maharashtra and Gujarat states are absorbing corrugated fiber cement volumes as rural infrastructure investment accelerates.
- REACH framework constraints:The EU's tightened asbestos restrictions are eliminating non-compliant imports and redirecting procurement toward certified fiber cement suppliers.
- CEA building energy codes:India's thermal performance mandates for roofing assemblies are specifying cement composite materials over metal alternatives in commercial construction.
Market Restraints
- Portland cement price volatility:Clinker and energy input costs fluctuate with carbon pricing mechanisms in European production zones.
- Specialized fiber supply concentration:Pulp and polypropylene reinforcement suppliers cluster in Southeast Asian manufacturing hubs.
- Weight-to-strength ratio limitations:Cement roofing sheets require heavier structural support than polymer or metal alternatives, constraining retrofit applications.
Strategic Opportunities
- Rural electrification corridors:India's PLI scheme for solar manufacturing is pairing rooftop installations with cement sheet substrates in agricultural zones.
- Polymer-modified cement blends:Hybrid formulations combining acrylic modifiers with cement matrices extend service intervals in tropical humidity cycles.
- Preventive maintenance contracting:Bundled installation and extended warranty services create recurring revenue streams beyond material supply.
Industry Challenges
- Hatschek process technician scarcity:Fiber cement sheet manufacturing requires specialized wet-forming expertise that training pipelines have not replenished.
- BIS certification timeline compression:India's standards body has lengthened product testing queues while tightening asbestos content verification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Roofing Sheets Market |
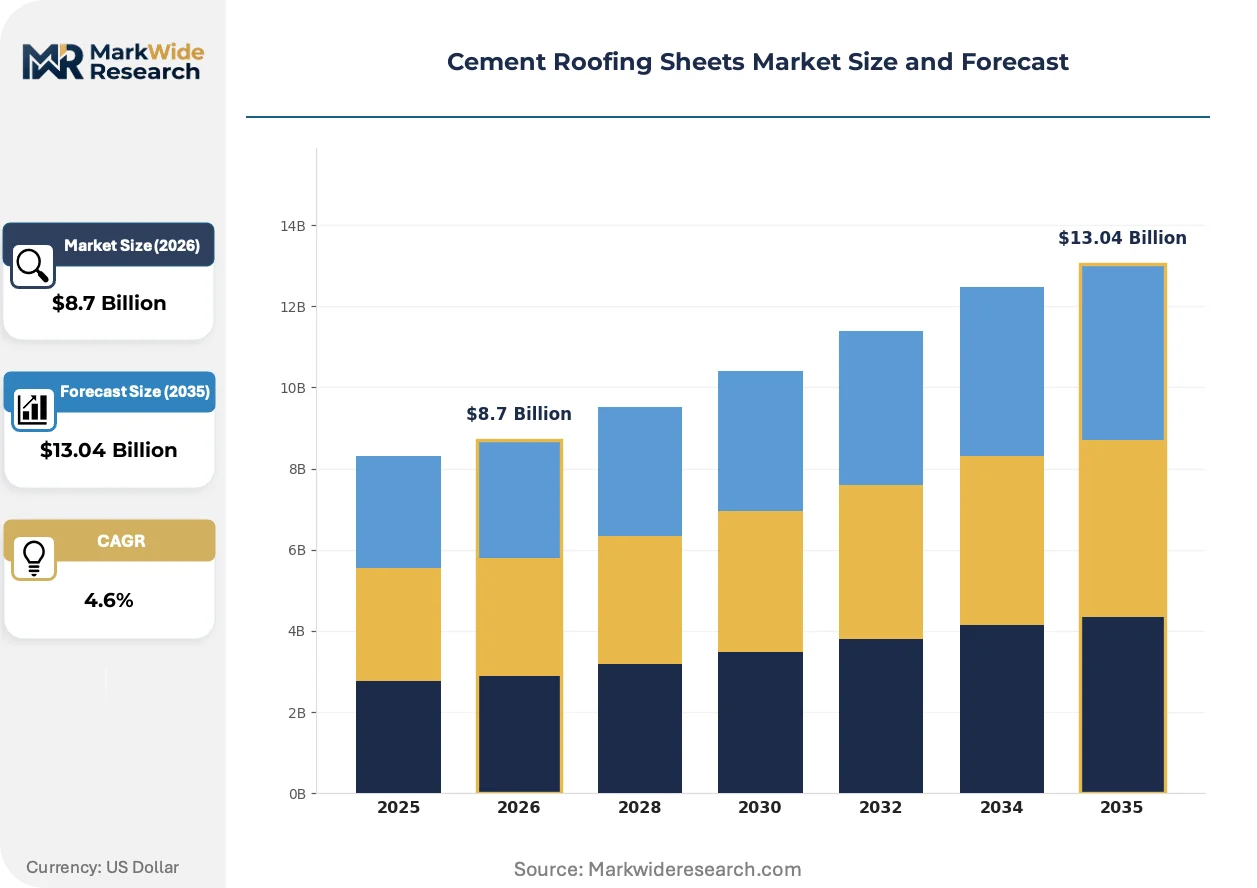
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Sheets, Flat Sheets, Interlocking Sheets, Channel Sheets Material Composition: Asbestos Cement, Fiber Cement, Portland Cement Composite, Calcium Silicate End Use Application: Residential Structures, Commercial Buildings, Agricultural Sheds, Institutional Facilities Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Construction Contractors |
| Companies Covered | Eternit, Tata Steel, Hindalco, Everest Industries, Onduline, CRH plc, BMI Group, Corrugated Roofing Sheets, A.S. Roofing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Roofing Sheets Market Trends and Innovations
Material science convergence with digital specification tools is compressing product development cycles and reshaping how architects and contractors select roofing assemblies.
Polymer-modified cement composites incorporating acrylic and styrene-butadiene latex are electrifying product performance expectations. Agricultural shed builders in India's humid coastal districts are specifying these blends for 25-year service guarantees. The technology is compressing replacement cycles and displacing conventional asbestos-cement in price-sensitive segments.
REACH authorization requirements for chrysotile asbestos are eliminating legacy formulation options across EU member states. Manufacturers must reformulate with cellulose or PVA fibers to maintain market access. Fiber cement categories are capturing volume share as roofing contractors in Poland and Romania switch specifications.
Specification workflows now route through BIM-enabled platforms where thermal performance data drives material selection. Large contractor accounts in Germany and France are embedding embodied-carbon thresholds into procurement criteria. Agricultural cooperatives in India are following this pattern as CEA codes tighten enforcement.
Cement Roofing Sheets Market Segmentation
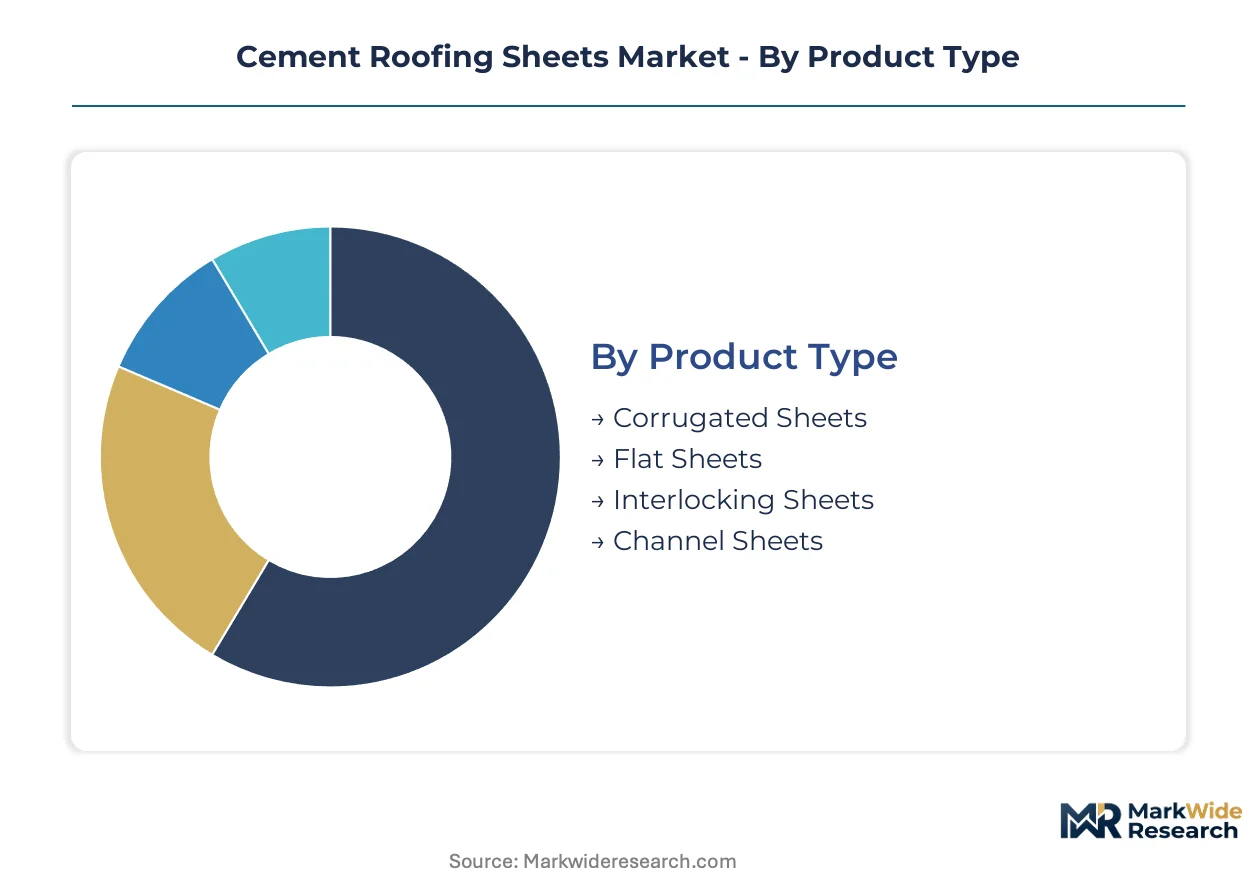
Cement roofing sheets segment across multiple dimensions that determine manufacturing investment, regulatory exposure, and margin structure. Product geometry and material composition dictate capital requirements and compliance pathways. End-use applications and distribution channels shape pricing power and customer acquisition costs.
Product Type:
Corrugated profiles demand the heaviest upfront tooling investment due to roll-forming complexity and profile-specific die requirements.
- Corrugated Sheets:Sinusoidal or trapezoidal profiles formed through continuous roll-forming deliver superior water runoff and structural rigidity with minimal material thickness. Agricultural shed builders in Maharashtra and Gujarat specify these for mechanized equipment storage as rural infrastructure investment accelerates.
- Flat Sheets:Planar cement panels require precision grinding and surface treatment equipment for architectural-grade finishes. Commercial building contractors in Indian metropolitan zones favor these for contemporary facade applications where thermal performance mandates under CEA codes specify cement composites over metal alternatives.
- Interlocking Sheets:Tongue-and-groove edge profiles enable rapid installation without mechanical fasteners.
- Channel Sheets:U-shaped or box-profile configurations provide integrated drainage channels.
Corrugated sheets absorb the bulk of installed capacity; agricultural shed applications are expanding most quickly.
Material Composition:
Raw material certification requirements and reformulation timelines segment manufacturers by compliance readiness and R&D expenditure intensity.
- Asbestos Cement:Chrysotile-reinforced formulations face phasedown mandates across multiple jurisdictions. India's BIS certification protocols now require extended testing queues and tightened asbestos content verification, compressing viable production timelines for legacy manufacturers.
- Fiber Cement:Cellulose, PVA, or polypropylene fiber matrices command premium positioning as REACH framework constraints eliminate non-compliant imports across EU member states. Roofing contractors in Poland and Romania redirect procurement toward certified fiber cement suppliers.
- Portland Cement Composite:Blended binders with supplementary cementitious materials reduce clinker intensity.
- Calcium Silicate:Autoclaved formulations offer lightweight alternatives with fire-resistant properties.
Fiber cement captures the steepest expansion trajectory; asbestos cement retains residual volume in price-sensitive rural segments.
End Use Application:
Project scale and specification authority determine whether procurement routes through contractor networks or direct manufacturer relationships.
- Residential Structures:Individual homeowner purchases prioritize cost minimization and installation simplicity. Retail store networks and local construction contractors dominate distribution in India's tier-2 and tier-3 cities where housing stock expansion concentrates.
- Agricultural Sheds:Mechanized farming infrastructure in Maharashtra and Gujarat drives specification of corrugated fiber cement for equipment storage. India's PLI scheme for solar manufacturing pairs rooftop installations with cement sheet substrates in electrification corridors.
- Commercial Buildings:Developer-led procurement with embodied-carbon thresholds under EU Green Deal constraints.
- Institutional Facilities:Public sector tendering with extended warranty and preventive maintenance contracting requirements.
Residential structures dominate unit volume; agricultural sheds are climbing the fastest on rural infrastructure investment.
Distribution Channel:
Customer scale and technical support requirements segment channels by working capital intensity and service bundling capabilities.
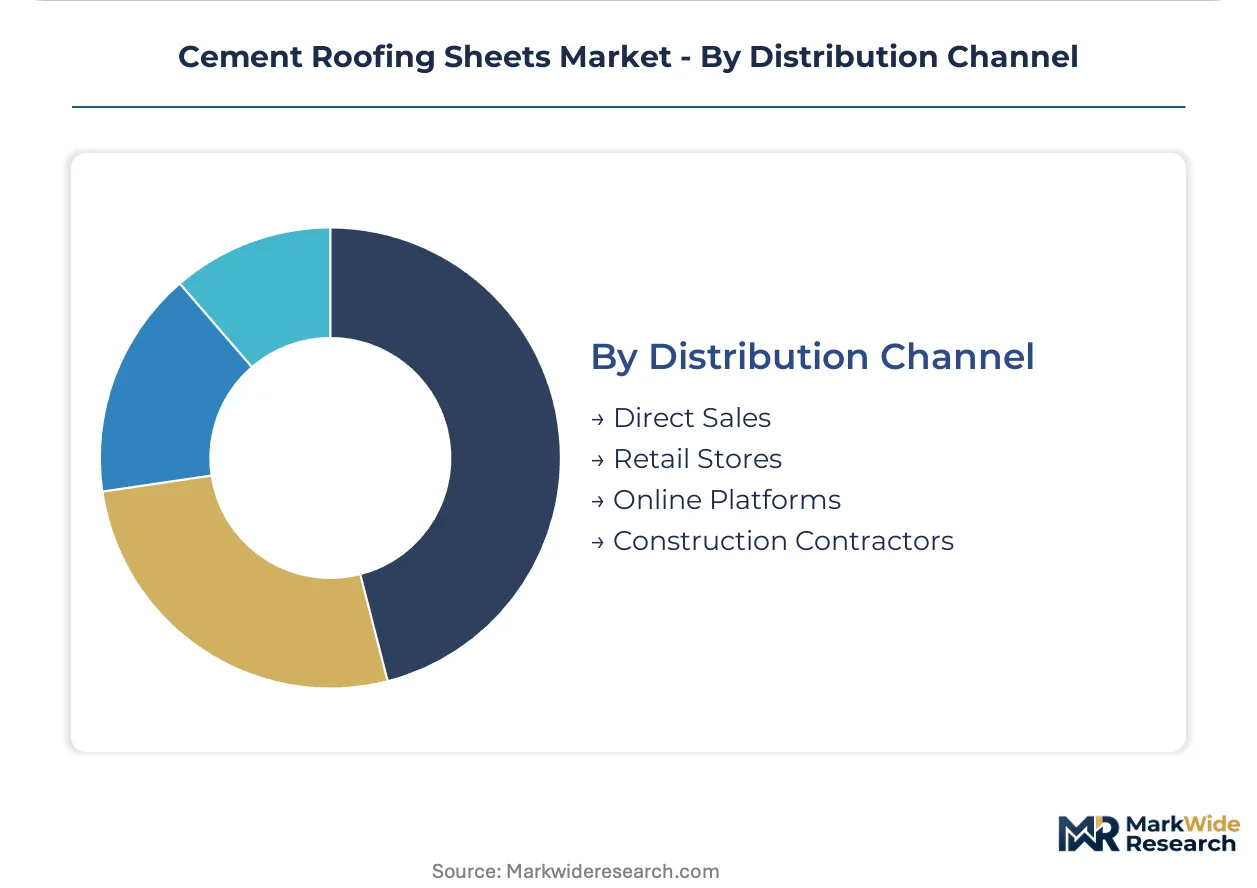
- Direct Sales:Manufacturer-managed relationships with large contractor accounts and agricultural cooperatives enable bundled installation support and extended warranty services. Everest Industries leverages dealer networks across South Asian markets to capture recurring revenue beyond material supply.
- Construction Contractors:Specifier influence and project-scale procurement concentrate volume with firms capable of Hatschek process expertise and specialized wet-forming knowledge. CRH plc anchors European footprint through captive distribution to large contractor accounts embedding thermal performance data into BIM-enabled specification workflows.
- Retail Stores:Counter sales to individual builders and small-scale renovators with immediate availability requirements.
- Online Platforms:Digital specification tools with embodied-carbon calculators and thermal performance databases.
Construction contractors channel the greatest revenue concentration; direct sales are gaining share fastest on service bundling economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes the largest cement roofing sheet volumes while European manufacturers absorb the steepest compliance costs. China's production clusters feed regional export demand. Brazil and Mexico anchor Latin American consumption patterns. The United States maintains residual specialty demand for fiber cement architectural panels.
India
Maharashtra and Gujarat states drive corrugated fiber cement absorption through mechanized farming infrastructure expansion. The BIS certification protocols now mandate extended asbestos content verification queues that compress legacy manufacturer timelines. Agricultural cooperatives across Pune and Ahmedabad industrial corridors pair solar rooftop installations with cement sheet substrates under PLI scheme incentives.
Germany
Commercial building contractors embed embodied-carbon thresholds into procurement criteria through BIM-enabled specification workflows. The EU Green Deal constraints eliminate non-compliant imports and redirect large contractor accounts toward certified fiber cement suppliers. Industrial clusters around Düsseldorf and Stuttgart concentrate specification authority for thermal performance-mandated roofing assemblies.
China
Rural housing stock renovation and agricultural modernization programs sustain corrugated sheet demand across interior provinces. The country's national building materials regulator enforces dual carbon goals that reshape clinker intensity requirements for cement composite manufacturers. Production gravity concentrates in Shandong and Jiangsu provinces where wet-forming expertise clusters around legacy Hatschek process facilities.
Brazil
Mechanized soybean and corn storage infrastructure expansion across Mato Grosso and Goiás states absorbs fiber cement volumes for equipment sheds. The national agricultural development bank channels subsidized credit toward rural construction materials that meet fire-resistant roofing mandates. São Paulo-based distribution networks capture contractor procurement for commercial building envelope specifications.
Mexico
Affordable housing programs and agricultural modernization initiatives sustain corrugated cement sheet demand across central and southern states. The national standards body aligns asbestos phasedown timelines with North American trade integration commitments. Manufacturing clusters around Mexico City and Puebla supply domestic consumption while exporting to Central American markets.
Cement Roofing Sheets Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across tiered market positions. The vendor base fragments between integrated manufacturers with captive fiber supply and regional assemblers dependent on third-party reinforcement sourcing. Three archetypes dominate: diversified building materials conglomerates with captive distribution, specialized fiber cement producers with formulation expertise, and regional roll-forming specialists serving price-sensitive rural segments. M&A activity concentrates on fiber reinforcement supply chain control while geographic expansion targets agricultural mechanization corridors.
Among European-based building materials groups, CRH plc and BMI Group occupy positions emphasizing large contractor account relationships and thermal performance specification authority. Everest Industries exemplifies the Asia-Pacific integrated manufacturer archetype with dealer network leverage across South Asian agricultural markets. These three anchors demonstrate how geographic footprint and distribution channel control separate premium-tier positioning from commodity volume competition.
| Leading Market Players |
|---|
| Eternit |
| Tata Steel |
| Hindalco |
| Everest Industries |
| Onduline |
| CRH plc |
| BMI Group |
| Corrugated Roofing Sheets |
| A.S. Roofing |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap producers across Gujarat and Maharashtra states anchor supply discipline through captive clinker grinding capacity, translating upstream control into pricing power over corrugated fiber cement volumes in agricultural corridors. Their concentrated ownership structures resist short-term margin compression, sustaining premium positioning against roll-up distributors dependent on third-party Hatschek process tolling.
Pricing Analysis
Margin tightening in standard-grade corrugated sheets reflects Portland cement input volatility under European carbon pricing mechanisms. Three-tier pricing structure across BIS-certified premium, standard-grade fiber cement, and residual asbestos-cement economy levels segments buyer archetypes. Agricultural cooperatives in Maharashtra exhibit highest price sensitivity, while German commercial contractors embedding embodied-carbon thresholds into BIM workflows accept premium positioning. Pricing pressure intensifies in economy tiers as BIS certification queues compress legacy manufacturer timelines.
Supply Chain Analysis
India's PLI scheme domestic-content requirements for solar manufacturing are reshaping reinforcement fiber sourcing toward in-country pulp and polypropylene suppliers. Manufacturing gravity centers on India, China, and Vietnam where wet-forming expertise clusters around legacy Hatschek process facilities. Clinker, cellulose pulp, and synthetic fiber dependencies create exposure to Southeast Asian logistics chokepoints. Distribution runs through construction contractor networks for large agricultural and commercial accounts, with retail store penetration dominant in residential tier-2 and tier-3 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiber cement formulation technology is displacing legacy asbestos-cement matrices across jurisdictions with tightening REACH and BIS phasedown mandates, compressing viable production timelines for non-compliant manufacturers.
For Market Incumbents: Deepen backward integration into cellulose pulp and polypropylene fiber supply to secure reinforcement access as REACH authorization eliminates chrysotile alternatives. Anchor dealer network control across Maharashtra and Gujarat agricultural corridors to bundle installation services and capture recurring preventive maintenance revenue. Fortify BIS certification pipelines against testing queue compression. For New Entrants and Emerging Players: EU Green Deal embodied-carbon thresholds in Germany and France open a window for polymer-modified cement blends with 25-year tropical humidity guarantees. Agricultural solar rooftop pairings under India's PLI scheme represent the most penetrable white-space, with direct sales to electrification cooperatives offering lowest customer acquisition friction versus established contractor networks. For Investors and Strategic Acquirers: Extended BIS asbestos-content verification queues are the leading indicator that legacy manufacturer distress will accelerate fiber cement asset consolidation. Five-to-ten year viability favors specialized wet-forming specialists with captive distribution in high-growth agricultural corridors. Watch for Hatschek process technician training program announcements as inflection signal for operational scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Supply | Captive cellulose and polypropylene sourcing secures compliance-ready reinforcement against REACH phasedown timelines. |
| Polymer-Modified Cement R&D Investment | Acrylic and styrene-butadiene latex blends command premium positioning for tropical humidity service guarantees. |
| Preventive Maintenance Contracting | Bundled installation and extended warranty services displace pure material supply economics across South Asian markets. |
| BIM-Enabled Specification Partnerships | Thermal performance data integration with German and French contractor procurement workflows captures commercial volume. |
| Hatschek Process Technician Training | Wet-forming expertise pipelines address scarcity constraints compressing fiber cement manufacturing expansion. |
Research Methodology
Multi-period observation of BIS certification queue lengths, REACH authorization timelines, and agricultural mechanization investment flows anchored the trend analysis, supplemented by interviews with plant managers at fiber cement manufacturing facilities, procurement leads at Maharashtra agricultural cooperatives, distribution channel partners across South Asian retail networks, and technical R&D directors specializing in polymer-modified cement matrices. Secondary validation drew from BIS regulatory filings, EU ECHA authorization databases, Indian CEA building energy code amendments, and cement industry trade association capacity reports. Bottom-up volume modeling triangulated against top-down construction spend forecasts.
Input-output matrices mapped clinker intensity, fiber reinforcement substitution rates, and Hatschek process capacity utilization across product geometry and material composition segments over the projection horizon. CAGRs derived from regression against agricultural infrastructure investment indices and regulatory compliance cost curves. Modeled dimensions spanned corrugated-flat-interlocking profiles, asbestos-fiber-Portland cement-composite material tiers, residential-agricultural-commercial-institutional end uses, and direct-contractor-retail-online channel pathways.
The model assumes a particular technology adoption path; alternative pathways for cellulose versus synthetic fiber reinforcement substitution would alter the outlook for raw material cost trajectories and regional manufacturing competitiveness. Forecasts reflect documented assumptions regarding BIS timeline compression and EU Green Deal enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Acoustic Panel Market
Building & Construction Materials
Aluminum Board Raised Access Floor Market
Building & Construction Materials
Magnesium Oxide Boards Market