
 Oriented Strand Board (OSB) Market | 2026-2036
Oriented Strand Board (OSB) Market Size, Share, and Industry Trends Forecast 2026-2036
Oriented Strand Board (OSB) Market Intelligence
Multi-family developers is bifurcating from single-family contractors as the dominant volume purchaser in several regional markets. Georgia-Pacific leverages its integrated pulp-to-panel supply chain to maintain cost discipline across the southeastern United States. Louisiana-Pacific Corporation anchors its position through specialty product lines targeting moisture-resistant applications. West Fraser Timber Co. Ltd. competes via scale advantages in Canadian softwood fiber access and cross-border distribution infrastructure.
Oriented Strand Board consists of layered wood strands arranged in cross-oriented directions and bonded with waterproof phenol-formaldehyde or polymeric diphenylmethane diisocyanate resin under heat and pressure, yielding structural panels rated for load-bearing wall, roof, and floor assemblies. Moisture-Resistant OSB commands expanding specification in coastal and humid-climate construction where extended exposure tolerance reduces job-site waste and callback risk. Fire-Retardant OSB occupies a narrower but higher-margin niche in commercial and multi-story residential projects where code-mandated flame-spread ratings exceed standard panel performance. The 7/16 inch and 1/2 inch thickness grades dominate residential wall sheathing volume, while 3/4 inch panels penetrate commercial flooring and engineered I-joist flange applications.
The APA — The Engineered Wood Association governs structural performance certification and quality testing protocols that determine builder acceptance and code compliance across U.S. jurisdictions. EPA formaldehyde emission standards under TSCA Title VI constrain resin chemistry choices and elevate compliance costs for domestic manufacturers and importers alike. Builders, distributors, and panel producers must monitor evolving state-level embodied carbon disclosure requirements and green building certification thresholds that increasingly influence material specification in public and institutional construction procurement.
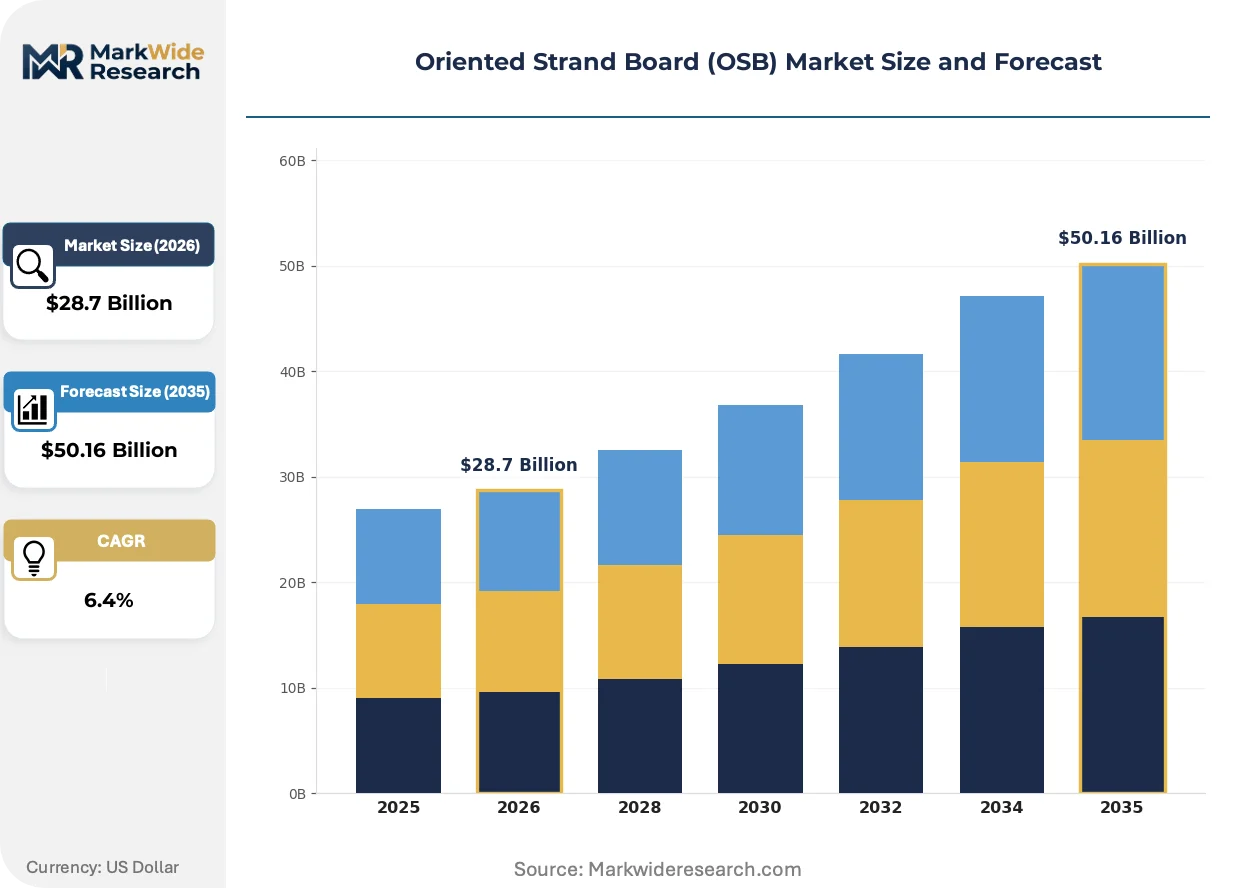
Market Dynamics
Residential construction specification is tightening structural performance requirements for wall sheathing and subflooring systems, pulling OSB producers toward APA-certified premium grades while compressing commodity panel margins.
Growth Catalysts
- EPA TSCA Title VI formaldehyde emission standards:Stricter resin chemistry compliance is accelerating plant upgrades among domestic manufacturers, creating technical barriers that protect compliant producers from low-cost import competition.
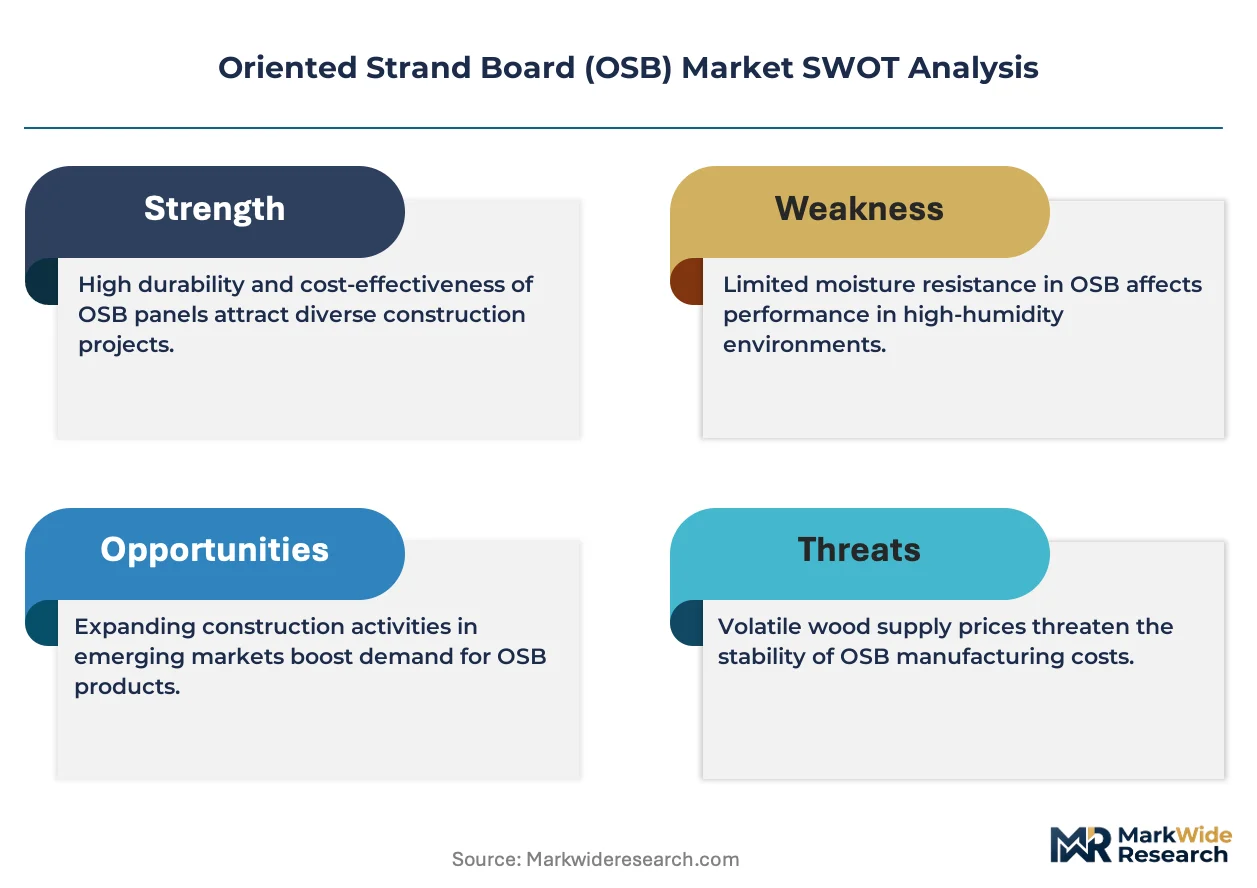
- Moisture-resistant panel specification:Coastal and humid-climate builders are expanding tolerance-rated OSB use to reduce job-site waste and callback exposure.
- Single-family housing starts concentration:United States residential construction absorbs substantial structural panel volumes, with repair-and-remodel activity providing counter-cyclical demand stability.
Market Restraints
- Softwood fiber cost volatility:Canadian lumber supply fluctuations and beetle-kill timber quality degradation compress input cost predictability for strand production.
- Phenol-formaldehyde resin price exposure:Petrochemical feedstock volatility elevates bonding agent costs, squeezing margins on standard-grade commodity panels.
- Cross-laminated timber substitution:Mass timber construction systems in commercial mid-rise projects displace OSB sheathing in select structural applications.
Strategic Opportunities
- Fire-retardant panel development:Code-mandated flame-spread ratings in multi-story residential and commercial verticals create higher-margin specification niches.
- State-level embodied carbon disclosure requirements:California and New York procurement rules increasingly favor low-carbon engineered wood in public construction bids.
- I-joist flange integration:3/4 inch panel penetration into engineered floor system manufacturing deepens captive demand from component producers.
Industry Challenges
- APA certification timeline compression:Accelerated quality testing protocols strain laboratory capacity, extending product qualification cycles for new plant startups.
- Resin formulation IP complexity:Polymeric MDI bonding patents held by chemical suppliers create licensing friction for producers seeking moisture-performance differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oriented Strand Board (OSB) Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softwood OSB, Hardwood OSB, Fire-Retardant OSB, Moisture-Resistant OSB Application: Roofing, Wall Sheathing, Flooring, Furniture Thickness: 7/16 inch, 1/2 inch, 5/8 inch, 3/4 inch End User: Construction, Furniture Manufacturers, Packaging, Transportation |
| Companies Covered | Kronospan Ltd., Georgia-Pacific, Louisiana-Pacific Corporation, Swiss Krono Group, Huber Engineered Woods LLC, West Fraser Timber Co. Ltd., EGGER Holzwerkstoffe Brilon GmbH & Co. KG, Norbord Inc., Weyerhaeuser Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oriented Strand Board (OSB) Market Strategic Shifts & Innovations
Panel manufacturing is splitting between commodity volume production and specialty-grade certification, with technology investments concentrating where structural performance premiums justify capital deployment.
Moisture-resistant OSB technology is bifurcating the specification landscape between coastal builders demanding extended exposure tolerance and inland contractors prioritizing cost minimization. Large multi-family developers in Florida and Gulf Coast states are mandating moisture-rated panels for all exterior sheathing. This technical segmentation is compressing commodity-grade pricing power while enabling specialty producers to defend margin through certified performance differentiation.
EPA formaldehyde emission standards under TSCA Title VI are constraining resin chemistry choices for domestic manufacturers and importers. The regulation elevates compliance costs through third-party certification requirements and quarterly testing protocols. Small and mid-scale producers lacking in-house laboratory capacity face disproportionate burden, accelerating consolidation toward integrated chemical-pulp-panel operations.
Builder procurement patterns are consolidating volume commitments through direct mill relationships, bypassing traditional two-step distribution. Large national homebuilders in the southern United States are negotiating annual offtake agreements with Georgia-Pacific and Louisiana-Pacific facilities. This channel compression is squeezing regional distributor margins while rewarding producers with scale-advantaged logistics and multi-plant coverage networks.
Oriented Strand Board (OSB) Market Segmentation
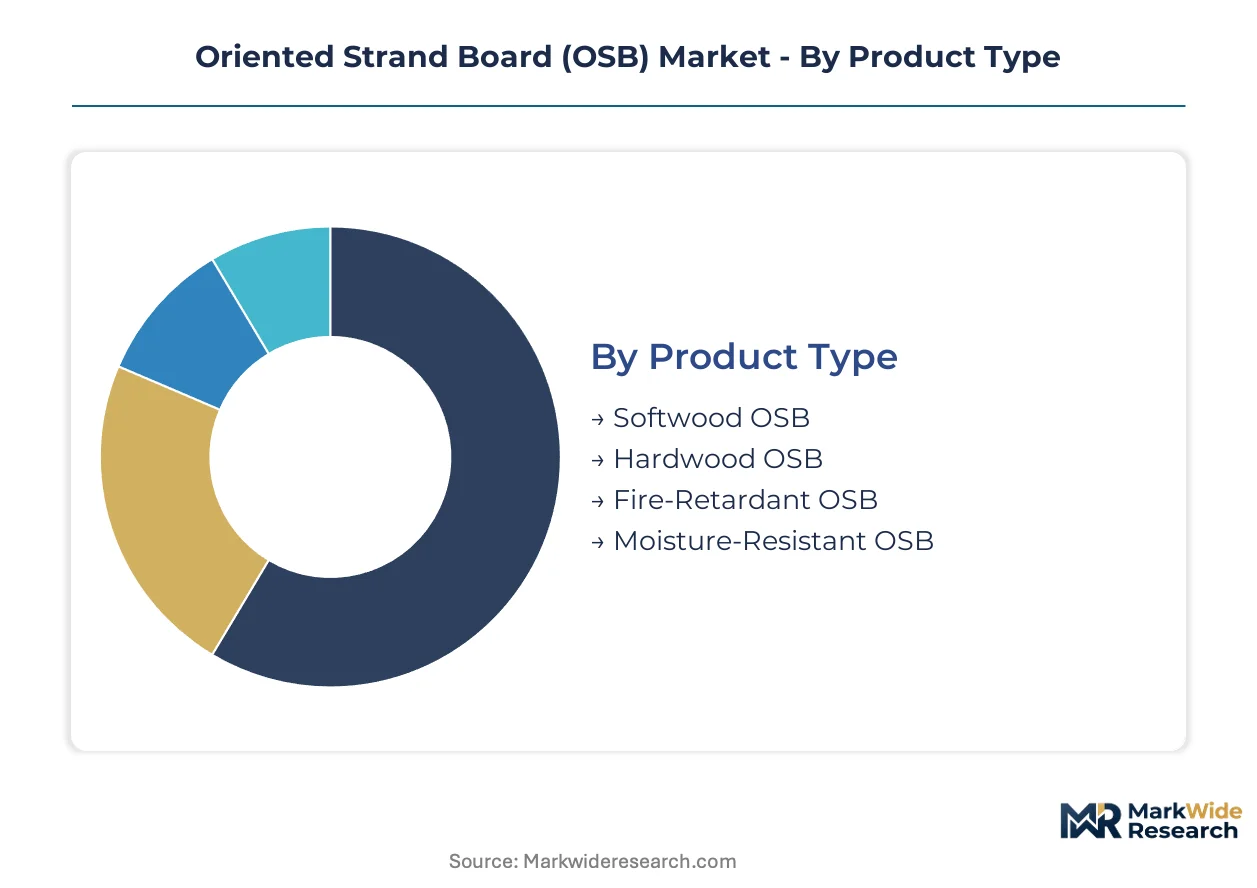
OSB demand fragments across performance tiers that trade off cost against code compliance and exposure tolerance. Builders sort specifications by structural load requirements, climate exposure, and flame-spread ratings rather than uniform commodity substitution.
Product Type:
Fire-Retardant OSB faces acute substitution pressure from cementitious sheathing in multi-story commercial projects where code mandates exceed standard panel performance, while commodity grades confront cross-laminated timber displacement in institutional construction.
- Softwood OSB:Manufactured from aspen, pine, and spruce strands cross-oriented in three to five layers with phenol-formaldehyde resin bonding. Single-family housing starts across the southeastern United States absorb the majority of volume, with repair-and-remodel activity providing demand stability during construction downturns.
- Moisture-Resistant OSB:Engineered with polymeric MDI resin systems and edge-sealing treatments that extend exposure tolerance to 180 days. Coastal builders in Florida and Gulf Coast states mandate this grade for all exterior sheathing to reduce job-site waste and moisture-related callback exposure.
- Fire-Retardant OSB:Impregnated with intumescent chemical treatments achieving Class A flame-spread ratings under ASTM E84 testing protocols.
- Hardwood OSB:Utilizes denser oak and maple fiber for specialized industrial applications requiring higher screw-holding strength.
Softwood OSB anchors the volume base while Moisture-Resistant OSB gains share at the steepest rate.
Application:
Wall sheathing commands the thickest margin spreads between APA-certified structural grades and commodity panels, concentrating producer R&D investment where performance premiums justify formulation complexity.
- Wall Sheathing:Structural panels rated for lateral load resistance in platform-frame construction, with 7/16 inch and 1/2 inch thickness grades dominating residential specification. United States single-family builders specify this application for approximately three-quarters of new housing starts, with APA certification serving as the non-negotiable procurement threshold.
- Flooring:3/4 inch panels penetrate subfloor assemblies and engineered I-joist flange applications where concentrated load distribution demands higher stiffness ratings. Component manufacturers in the Pacific Northwest and southeastern manufacturing corridors represent captive demand concentrations that insulate this segment from spot-market volatility.
- Roofing:Rated sheathing for rafter and truss applications requiring span ratings up to 48 inches on center.
- Furniture:Lower-density panels serving ready-to-assemble and core material applications.
Wall sheathing generates the largest revenue pool while Flooring expands most quickly through engineered wood system integration.
Thickness:
Thickness selection correlates directly with span rating requirements and labor cost tradeoffs, with thinner grades penetrating volume residential construction where material cost minimization dominates procurement criteria.
- 7/16 inch:The dominant residential wall sheathing specification, rated for 24-inch stud spacing under APA performance protocols. United States production lines optimize around this dimension, with Georgia-Pacific and Louisiana-Pacific facilities in the Southeast achieving lowest delivered cost through integrated pulp-to-panel supply chains.
- 3/4 inch:Required for commercial flooring, heavy-duty roof decking, and I-joist flange stock where concentrated loads demand higher bending stiffness. Canadian softwood fiber access through West Fraser Timber's British Columbia and Alberta operations supports cost-competitive supply into United States engineered floor system manufacturers.
- 1/2 inch:Intermediate specification for residential roof decking and higher wind-load zones.
- 5/8 inch:Selected for fire-rated assemblies and commercial wall applications requiring enhanced acoustic performance.
7/16 inch thickness commands the production volume base while 3/4 inch climbs the fastest through commercial and component manufacturing penetration.
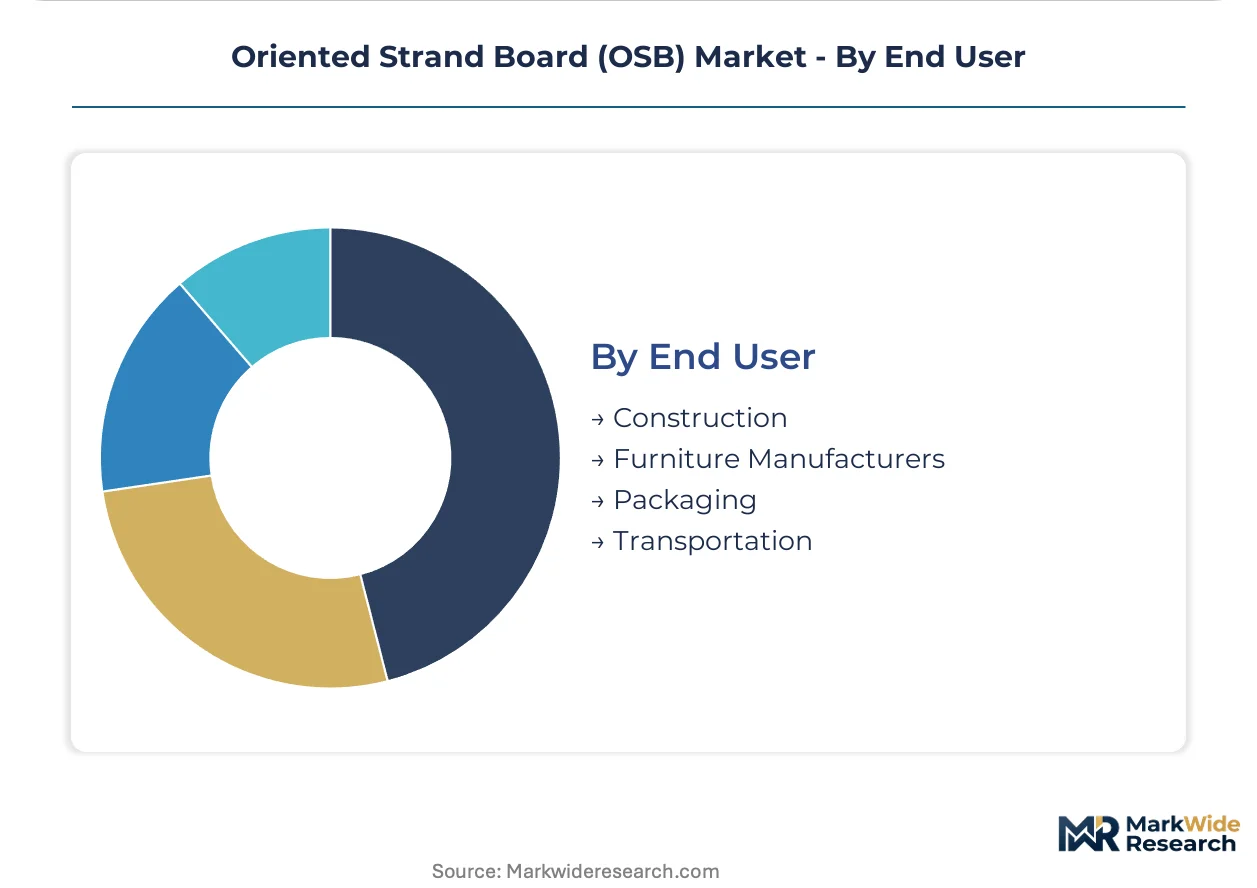
End User:
Construction sector procurement is consolidating through direct mill relationships that bypass traditional distribution, squeezing regional distributor margins while rewarding producers with multi-plant logistics networks.
- Construction:Residential and commercial builders specifying structural panels for sheathing, subflooring, and roof decking under IRC and IBC code jurisdictions. Large national homebuilders negotiate annual offtake agreements directly with Georgia-Pacific and Louisiana-Pacific, compressing channel margins and demanding consistent multi-regional supply.
- Furniture Manufacturers:Ready-to-assemble and case goods producers utilizing OSB as core material beneath veneer or laminate surfaces. Southeast Asian manufacturing clusters represent growing demand concentration as furniture production migrates from domestic facilities.
- Packaging:Industrial crating and pallet applications requiring lower structural ratings.
- Transportation:Trailer flooring and rail car interior panels subject to abrasion resistance specifications.
Construction anchors the volume base while Furniture Manufacturers expand most quickly through offshore manufacturing migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Vancouver's container terminals and rail interchanges to Chicago and Dallas underpin Canadian softwood fiber access that supplies cross-border OSB distribution into the United States. This infrastructure anchors North American panel logistics while European producers rely on Rhine River barge networks and Baltic port capacity for continental distribution.
United States
Single-family housing starts in Texas and Florida absorb substantial structural panel volumes, with repair-and-remodel activity providing demand stability. EPA TSCA Title VI formaldehyde emission standards constrain resin chemistry choices and elevate compliance costs through third-party certification requirements. Georgia-Pacific's integrated pulp-to-panel facilities across the southeastern states achieve lowest delivered cost through captive fiber supply.
Canada
West Fraser Timber's British Columbia and Alberta operations leverage beetle-kill timber recovery programs to maintain fiber cost discipline. The country's national forestry regulator enforces sustainable harvest certification that underpins APA — The Engineered Wood Association quality protocols accepted in U.S. jurisdictions. Vancouver and Prince George manufacturing corridors concentrate strand production capacity with direct rail links to U.S. Midwest distribution hubs.
Germany
EGGER Holzwerkstoffe's Brilon facility exemplifies European engineered wood manufacturing scale, serving renovation-driven demand across the continent. EU Green Deal embodied carbon disclosure requirements increasingly influence public procurement specifications for low-carbon building materials. The Rhine-Ruhr industrial corridor hosts chemical resin suppliers that reduce bonding agent logistics costs for regional panel producers.
China
Rapid urbanization in the Yangtze River Delta and Pearl River Delta generates construction panel demand, though domestic OSB penetration lags North American specification intensity. GB standards for formaldehyde emission in wood-based panels constrain import acceptance and elevate domestic manufacturing compliance requirements. Shandong Province manufacturing clusters concentrate particleboard and fiberboard capacity with emerging OSB line investments.
Brazil
Industrial construction in São Paulo and Rio de Janeiro states creates specification opportunities for structural panels in commercial warehousing and logistics facilities. The country's national forestry regulator enforces sustainable plantation management certification that underpins export acceptance to European markets. Paraná and Santa Catarina states concentrate pine plantation resources that support emerging strand board fiber supply.
Oriented Strand Board (OSB) Market Key Industry Players
Concentration sits with integrated forest products conglomerates that control pulp-to-panel supply chains across multiple jurisdictions. Three to four producers command majority capacity share in North America, while European competition fragments across national champions with strong domestic positions. Strategic archetypes include fiber-integrated volume leaders, specialty-grade differentiators, and regional cost optimizers. Capacity expansion and APA certification investments constitute the dominant competitive moves as producers defend structural performance premiums.
Among North American integrated producers, Georgia-Pacific, Louisiana-Pacific Corporation, and West Fraser Timber Co. Ltd. occupy positions that exemplify scale-advantaged logistics and multi-plant coverage networks. Swiss Krono Group and EGGER Holzwerkstoffe Brilon GmbH & Co. KG represent European archetypes with continental distribution reach and renovation-market specialization. Huber Engineered Woods LLC and Norbord Inc. sit within specialty-grade tiers where moisture-resistant and fire-retardant certification commands margin premiums over commodity panels.
| Leading Market Players |
|---|
| Kronospan Ltd. |
| Georgia-Pacific |
| Louisiana-Pacific Corporation |
| Swiss Krono Group |
| Huber Engineered Woods LLC |
| West Fraser Timber Co. Ltd. |
| EGGER Holzwerkstoffe Brilon GmbH & Co. KG |
| Norbord Inc. |
| Weyerhaeuser Company |
| Others |
Cost & Logistics Intelligence
Forty-five to sixty days of finished goods inventory at mill warehouses anchors pricing power for integrated producers while compressing margins for distributors caught between spot resin volatility and fixed annual offtake contracts. This lead-time band concentrates bargaining leverage with Georgia-Pacific and West Fraser Timber facilities that can throttle volume release during softwood fiber price spikes.
Pricing Analysis
Three-tier pricing structure across APA-certified premium, moisture-resistant specialty, and commodity economy grades stratifies the market. Price differentiation hinges on certification tier and volume scale, with large national homebuilders securing lowest delivered cost through direct mill relationships. Pricing pressure stems from phenol-formaldehyde resin cost volatility, squeezing standard-grade margins most acutely. Regional distributors exhibit highest price sensitivity due to channel compression, while multi-family developers accept premium tiers for exposure-rated specifications.
Supply Chain Analysis
Just-in-time delivery preferences dominate residential construction procurement, though coastal builders maintain strategic stockpiles of moisture-resistant grades during hurricane season windows. Supply concentrates in the United States, Canada, and Germany, with strand production drawing from aspen and pine fiber basins. Raw material dependencies rest on softwood timber, phenol-formaldehyde resin, and polymeric MDI bonding agents. Single-source vulnerability sits with Canadian beetle-kill timber quality degradation. Distribution runs through direct mill-to-builder relationships and rail-linked regional warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-laminated timber substitution in commercial mid-rise construction threatens OSB sheathing volumes, forcing incumbents to defend structural panel specification through performance certification and code advocacy.
For Market Incumbents: Shield wall sheathing specification share by accelerating APA-certified premium grade capacity additions in Texas and Florida corridors. Deepen captive resin production to offset petrochemical feedstock volatility. Defend against mass timber displacement by embedding OSB in platform-frame code committees and builder education programs.
For New Entrants and Emerging Players: Differentiate on fire-retardant certification for multi-story residential verticals where Class A flame-spread ratings command margin premiums above commodity tiers. Target the Pacific Northwest engineered I-joist flange segment where component manufacturers seek alternative 3/4 inch panel supply. Pursue state-level embodied carbon disclosure compliance as the go-to-market angle for public procurement bids in California and New York.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialty-grade certification barriers and EPA TSCA Title VI compliance costs favor scaled integrated producers over fragmented regional competitors. Acquisition target archetype: mid-scale facilities with stranded fiber access and underutilized APA laboratory capacity. Watch single-family housing permit volatility as the signal for demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive phenol-formaldehyde supply insulates margin from petrochemical volatility at Georgia-Pacific scale. |
| Moisture-Resistant Grade Capacity Expansion | Florida and Gulf Coast builder mandates for 180-day exposure tolerance defend premium pricing tiers. |
| Fire-Retardant Certification Investment | ASTM E84 Class A rating unlocks multi-story residential specification above standard panel performance. |
| Direct Mill Relationship Cultivation | Bypassing two-step distribution captures volume commitment from national homebuilder annual offtake negotiations. |
| State Carbon Disclosure Compliance | California and New York procurement rules increasingly filter engineered wood bids through embodied carbon thresholds. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with OSB plant managers, national homebuilder procurement directors, APA certification laboratory heads, and distribution channel partners; and secondary validation through APA — The Engineered Wood Association production statistics, EPA TSCA Title VI compliance filings, U.S. Census Bureau housing starts data, and customs trade records. Bottom-up strand production capacity modeling triangulated against top-down construction material demand estimation.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, application, thickness grade, and end-user segment. CAGRs derived from regression analysis against single-family housing starts, repair-and-remodel expenditure indices, and regional climate exposure specifications. Industry-specific inputs included APA certification timeline compression effects and resin formulation patent licensing friction.
Material uncertainties — softwood fiber cost volatility from Canadian beetle-kill timber degradation, phenol-formaldehyde resin price spikes, and cross-laminated timber code adoption rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained single-family construction absorption and stable EPA emission standard enforcement. Revision becomes warranted when mass timber building code adoption crosses thresholds in multi-story residential jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market