
 US Metal Stadium Seating Market | 2026-2036
US Metal Stadium Seating Market Size, Share, and Industry Trends Forecast 2026-2036
US Metal Stadium Seating Market Insights
ADA-compliant premium specification tiers is collapsing into the mainstream as baseline requirements across municipal and university procurement contracts. Southern Bleacher, Inc. dominates the custom permanent installation segment through its in-house fabrication capabilities. GT Grandstands competes aggressively on temporary and modular bleacher systems for tournament circuits. Hussey Seating Company anchors the educational institution channel with established relationships across NCAA Division I athletic departments.
US metal stadium seating comprises galvanized steel and aluminum frameworks engineered to ICC-500 storm shelter standards and IBC live-load requirements, typically fabricated through roll-forming, welding, and powder-coating processes for corrosion resistance in outdoor environments. Fixed seats occupy the largest revenue pool due to longevity and lower lifecycle replacement rates in professional venues. Modular installations represent the fastest-expanding segment as event organizers prioritize reconfigurable capacity for multi-use facilities. Bleachers sustain the highest unit volumes, though margin compression persists in commodity municipal bids.
The International Code Council mandates seismic and wind-load certifications that filter out smaller fabricators lacking testing infrastructure. OSHA workplace safety standards govern installation labor costs, while ADA Title III enforcement continues to trigger renovation cycles in pre-1990 facilities. Stakeholders must weigh captive fabrication investments against specialty outsourcing as steel price volatility and lead-time uncertainty reshape supplier economics.
Market Dynamics
ADA Title III enforcement is accelerating renovation cycles across pre-1990 facilities, compressing replacement timelines and elevating compliance specifications from premium tier to baseline procurement requirements.
Growth Catalysts
- Sun Belt construction velocity:Texas, Florida, and Arizona stadium development outpaces national averages, driving concentrated demand for fixed and modular seating systems.
- OSHA workplace safety standards:Tightened installation labor protocols are professionalizing contractor networks and filtering out informal competitors.
- Multi-use facility reconfiguration:Tournament circuits and municipal venues prioritize rapid capacity adjustment, expanding procurement of modular bleacher architectures.
Market Restraints
- Galvanized steel price volatility:Raw material cost swings compress margins on fixed-bid municipal contracts and strain working capital for mid-tier fabricators.
- ICC-500 storm shelter certification:Testing infrastructure requirements filter out smaller regional suppliers lacking capital-intensive laboratory access.
- Aluminum substitution pressure:Lightweight composite alternatives threaten share in temporary seating applications where longevity is less critical.
Strategic Opportunities
- Educational institution channel:NCAA Division I athletic department modernization programs present white space for integrated seating and sightline optimization services.
- Integrated sightline analytics:Convergence of parametric design software and modular fabrication enables custom permanent installations at scaled economics.
- Fire safety code convergence:Evolving state-level standards create upgrade mandates for legacy wooden bleacher replacement in secondary markets.
Industry Challenges
- Certification timeline compression:ICC-500 and IBC live-load testing cycles extend product development schedules, delaying revenue recognition on custom projects.
- Specialized welding labor scarcity:Qualified aluminum and galvanized steel fabrication technicians command premium wages, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Metal Stadium Seating Market |
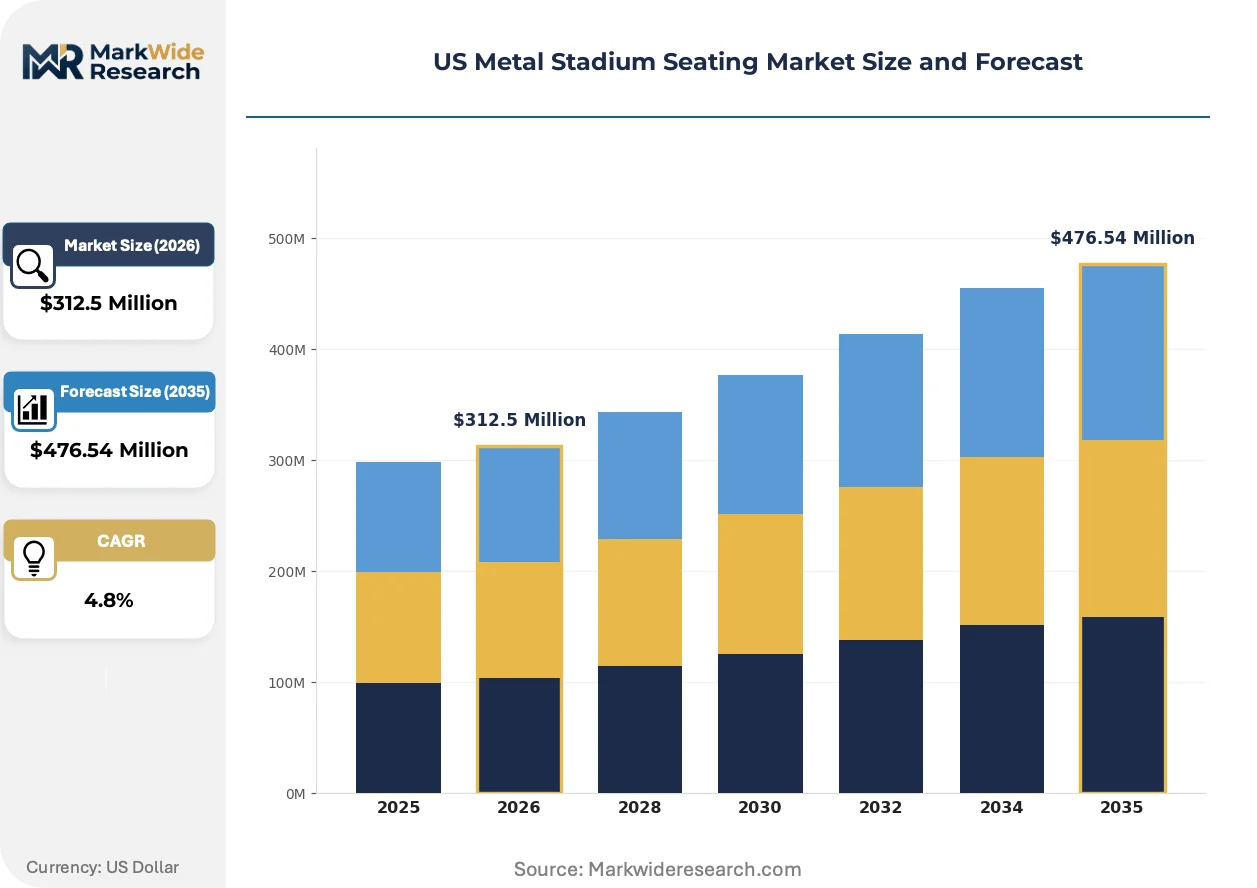
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleachers, Foldable Seats, Fixed Seats, Premium Seating End User: Stadium Owners, Event Organizers, Sports Teams, Educational Institutions Installation Type: Permanent, Temporary, Modular, Custom Material: Aluminum, Steel, Reinforced Plastic, Composite |
| Companies Covered | Southern Bleacher, Inc., GT Grandstands, Sturdisteel, E&D Specialty Stands, Inc., DANT CLAYTON, American Aluminum Seating, Inc., Delta Stadium Seating, Hussey Seating Company, Irwin Seating Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Metal Stadium Seating Market Trends and Innovations
Digital fabrication and regulatory convergence are compressing traditional competitive advantages while elevating technical specification thresholds across procurement channels.
Parametric seat design software paired with CNC roll-forming equipment is miniaturizing batch economics for custom permanent installations. Municipal and university buyers now specify sightline-optimized geometries previously reserved for professional venues. Southern Bleacher and comparable fabricators are compressing engineering-to-installation cycles from months to weeks.
OSHA workplace safety standards governing elevated platform installation have tightened liability exposure and labor cost structures. Contractors must now certify crews for fall protection and structural bolting protocols. Sun Belt states with active construction pipelines are experiencing contractor qualification bottlenecks that extend project timelines.
After-sales service unbundling is disrupting traditional equipment-plus-installation bundling. Facility managers now procure seating hardware, installation labor, and maintenance contracts through separate vendors or self-perform maintenance. Collegiate athletic departments with in-house facilities teams are driving this fragmentation, particularly in Division I conferences with dedicated capital budgets.
US Metal Stadium Seating Market Segmentation
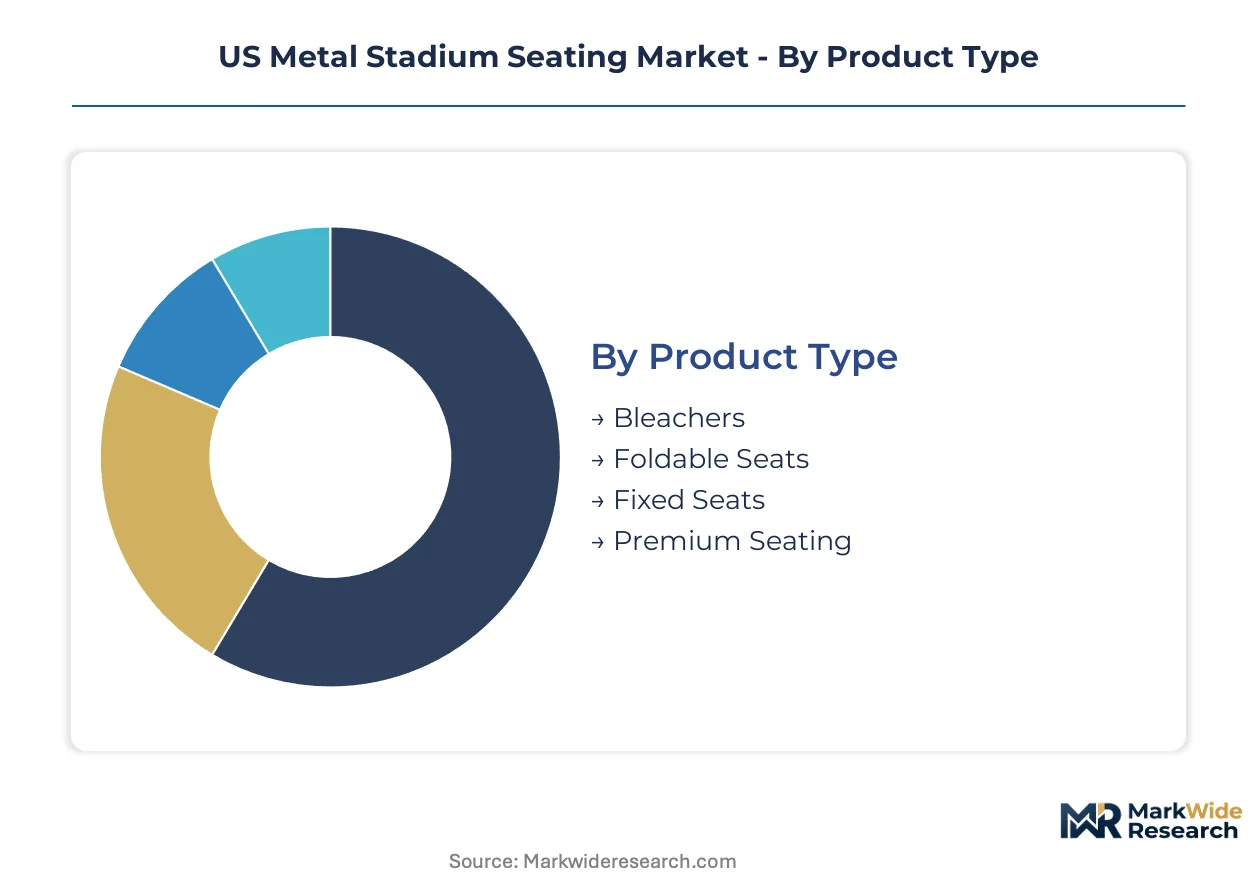
Segmentation in US metal stadium seating reveals how procurement specifications diverge across venue types and installation requirements. Distinct compliance thresholds, lifecycle expectations, and reconfiguration needs shape purchasing patterns across each category.
Product Type:
Domestic fabrication capacity concentrates on fixed and bleacher systems for permanent venues, while foldable and premium seating draw more heavily on specialized component imports.
- Fixed Seats:Galvanized steel or aluminum frameworks engineered to ICC-500 storm shelter standards and IBC live-load requirements dominate professional sports venues. Texas and Florida stadium developments sustain concentrated demand for these installations due to hurricane-zone building codes.
- Bleachers:Tiered bench seating fabricated through roll-forming and powder-coating processes serves high schools and municipal complexes across Sun Belt states. OSHA workplace safety standards governing elevated platform installation have tightened contractor qualification requirements, extending project timelines in active construction corridors.
- Foldable Seats:Retractable bench systems enable rapid capacity reconfiguration for multi-use arenas.
- Premium Seating:Club-level and suite installations with integrated amenities command elevated specification tiers.
Fixed seats hold the largest share; momentum sits with bleachers as municipal replacement cycles accelerate.
End User:
Procurement scale varies dramatically across customer types, with educational institutions and stadium owners driving contrasting specification philosophies.
- Stadium Owners:Professional venue operators prioritize longevity and sightline optimization in permanent installations. NCAA Division I athletic departments anchor sustained procurement volumes as modernization programs expand beyond Power Five conferences.
- Educational Institutions:High schools and universities balance ADA Title III compliance mandates against constrained capital budgets. Pre-1990 facilities across secondary markets trigger renovation cycles as accessibility enforcement tightens.
- Event Organizers:Tournament circuits and touring operations demand rapid-deployment seating for temporary venues.
- Sports Teams:Franchise-level buyers integrate seating procurement with broader facility development timelines.
Stadium owners command the highest contract values; educational institutions represent the broadest addressable base.
Installation Type:
Cost tier differentiation separates capital-intensive permanent builds from operational expenditure-driven temporary and modular alternatives.
- Permanent:Custom-engineered steel frameworks fabricated in-house by dominant suppliers anchor professional venue construction. Southern Bleacher and comparable fabricators compress engineering-to-installation cycles through parametric design software paired with CNC roll-forming equipment.
- Modular:Reconfigurable aluminum systems enable capacity adjustment for multi-use facilities without structural modification. Tournament circuits and municipal venues across Arizona and Texas prioritize these architectures for operational flexibility.
- Temporary:Rapid-deployment bleacher systems serve event-specific demand with minimal site preparation.
- Custom:Bespoke permanent installations integrate sightline analytics and premium amenities for signature venues.
Permanent installations capture the deepest revenue per project; modular systems are climbing the fastest as facility versatility becomes a procurement priority.
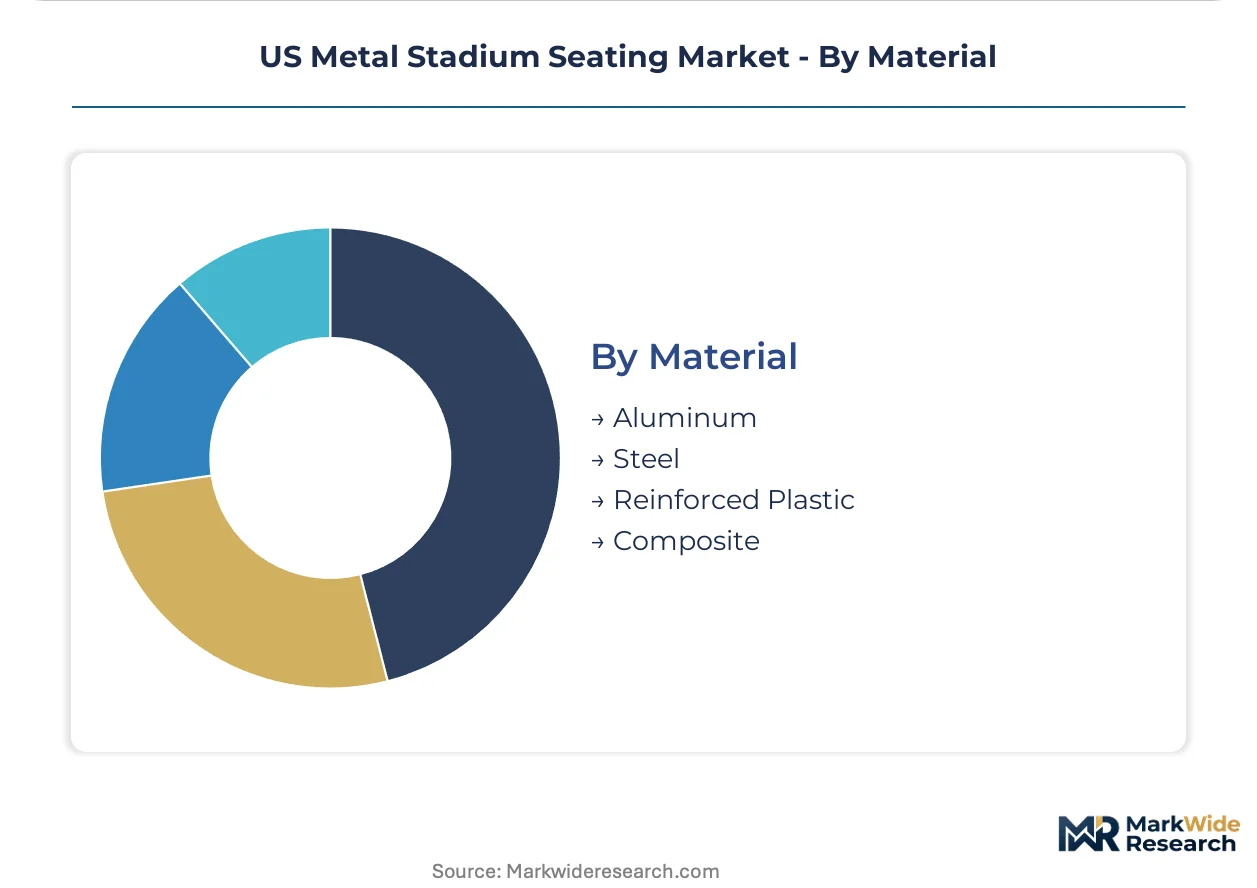
Material:
Supply concentration in domestic steel production contrasts with import dependency for specialized aluminum alloys and composite formulations.
- Steel:Galvanized frameworks dominate fixed installations due to strength-to-cost ratios and established fabrication infrastructure. Price volatility in raw material markets compresses margins on fixed-bid municipal contracts.
- Aluminum:Lightweight corrosion-resistant alloys enable modular and temporary applications where transport efficiency matters. Seismic and wind-load certifications from the International Code Council filter out fabricators lacking capital-intensive testing infrastructure.
- Reinforced Plastic:Polymer-based seating surfaces reduce thermal conductivity in extreme climates.
- Composite:Fiber-reinforced materials threaten aluminum share in temporary seating where longevity is less critical.
Steel retains the largest installed base; aluminum is gaining share fastest as weight reduction and corrosion resistance climb specification priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US metal stadium seating market operates as a net domestic producer with limited export penetration, as ICC-500 and IBC certification requirements create natural trade barriers that favor local fabrication capacity over foreign supply. Regional demand clusters concentrate in Sun Belt construction corridors where hurricane-zone building codes and rapid population growth sustain replacement and new-build cycles.
Texas
Houston and Dallas-Fort Worth metro areas anchor the nation's most active stadium development pipeline, with high school football venue construction and NCAA Division I facility upgrades driving procurement volumes. Texas Department of Insurance windstorm certification requirements exceed national ICC-500 standards, filtering out fabricators lacking enhanced testing capabilities. The I-35 corridor from San Antonio to Austin hosts concentrated bleacher manufacturing capacity serving municipal bid markets.
Florida
Orlando and Tampa Bay tournament circuits generate sustained demand for modular and temporary seating systems with rapid-deployment specifications. Florida Building Code hurricane resistance mandates require enhanced wind-load engineering that elevates compliance costs above national baselines. Miami-Dade County's stringent product approval process serves as a de facto regional gatekeeper for seating systems entering Southeast markets.
Arizona
Phoenix metropolitan expansion and spring training facility upgrades concentrate procurement activity in fixed and modular installations. Arizona Corporation Commission utility coordination requirements intersect with stadium electrical integration standards, complicating contractor qualification. The Tucson-Phoenix corridor hosts specialty aluminum fabricators serving desert climate applications where thermal expansion tolerance drives material specification.
California
Los Angeles and San Francisco Bay Area venue modernization programs prioritize ADA Title III compliance retrofits in pre-1990 facilities. California Division of Occupational Safety and Health elevated platform standards exceed federal OSHA baselines, extending installation timelines and labor cost structures. The Central Valley agricultural fairground circuit sustains niche demand for temporary bleacher systems with rapid seasonal deployment cycles.
Southeast (Georgia and Carolinas)
Atlanta's collegiate athletic conference headquarters concentration influences procurement specification standards across secondary markets. Georgia Department of Community Affairs accessibility enforcement triggers renovation waves in county-owned facilities built before federal ADA mandates. Charlotte and Raleigh municipal bond programs fund multi-use arena developments that specify modular reconfigurable seating architectures.
US Metal Stadium Seating Market Competitive Landscape
Concentration sits with integrated fabricators commanding in-house roll-forming and powder-coating infrastructure, while mid-tier contractors compete on installation speed and municipal bid responsiveness. The vendor base separates into three strategic archetypes: custom permanent installation specialists, modular system providers, and commodity bleacher fabricators. Dominant competitive moves include captive fabrication investments to offset steel price volatility and parametric design software adoption to compress engineering-to-installation cycles.
Among custom permanent installation specialists, Southern Bleacher, Inc. exemplifies the integrated fabricator archetype through its Texas-based manufacturing footprint. GT Grandstands occupies a position within the modular and temporary seating tier, while Hussey Seating Company anchors the educational institution channel with established NCAA Division I relationships. These three companies represent distinct competitive positioning vectors—geographic concentration, product architecture flexibility, and institutional sales depth—that define the market's structural segmentation.
| Leading Market Players |
|---|
| Southern Bleacher, Inc. |
| GT Grandstands |
| Sturdisteel |
| E&D Specialty Stands, Inc. |
| DANT CLAYTON |
| American Aluminum Seating, Inc. |
| Delta Stadium Seating |
| Hussey Seating Company |
| Irwin Seating Company |
| Others |
Pricing and Supply Chain Analysis
Aluminum substitution for galvanized steel in modular seating applications simultaneously redistributes fabrication activity toward Sun Belt states with specialty alloy access and compresses margin structures in fixed-bid municipal contracts. This material transition elevates transport efficiency premiums while eroding traditional cost advantages of integrated steel roll-forming operations.
Pricing Analysis
Stadium owners and NCAA athletic departments anchor project-based pricing structures with volume-scale and certification-grade differentiation. Three-tier pricing stratifies across ICC-500 storm shelter certified installations, standard IBC-compliant systems, and economy-grade municipal bleacher tiers. Cost compression in the economy tier intensifies due to galvanized steel price volatility and commodity bid aggregation. High school districts exhibit highest price sensitivity; professional venue operators prioritize sightline optimization over unit cost.
Supply Chain Analysis
Inbound logistics costs for specialty aluminum alloys from domestic primary producers in Tennessee and Kentucky feed into fabrication nodes across Texas and Arizona. Raw material dependencies center on galvanized steel coils from domestic mills, aluminum extrusions from regional smelters, and powder-coating chemicals from Gulf Coast petrochemical complexes. Single-source vulnerability concentrates in ICC-500 testing laboratory access, which filters out smaller fabricators. Distribution runs through direct-to-contractor channels for permanent installations and equipment rental networks for temporary systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US metal stadium seating market sits in early-cycle expansion as ADA Title III enforcement accelerates replacement timelines across pre-1990 facilities. This regulatory tailwind sustains procurement velocity independent of new construction cycles.
For Market Incumbents: Consolidate fabrication capacity in hurricane-zone corridors to capture Texas and Florida stadium development pipelines. Captive powder-coating investments offset steel price volatility while ICC-500 certification maintenance filters out regional competitors lacking laboratory partnerships. Sightline analytics software integration defends against parametric design entrants. For New Entrants and Emerging Players: After-sales service unbundling presents white space where incumbents over-bundle installation and maintenance. Collegiate athletic departments with in-house facilities teams represent the most penetrable segment. A direct service-contracting model bypasses traditional equipment-plus-installation bundling. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed custom fabricators holding concentrated Sun Belt customer relationships. Five-to-ten year viability hinges on parametric design capability and testing infrastructure ownership. The signal to watch is municipal bond issuance velocity for multi-use arena developments specifying modular architectures.| Strategic Initiative | Industry Significance |
|---|---|
| ICC-500 Certification Investment | Testing infrastructure access filters competitors from hurricane-zone procurement. |
| Parametric Design Software Adoption | CNC roll-forming integration compresses engineering-to-installation cycles for custom venues. |
| Captive Powder-Coating Capacity | In-house corrosion treatment offsets steel price volatility in fixed-bid contracts. |
| Educational Institution Channel Expansion | NCAA Division I relationships anchor recurring modernization program revenue. |
| Modular System Architecture Development | Reconfigurable aluminum platforms capture tournament circuit and municipal demand. |
Research Methodology
Desk research of ICC-500 certification databases, municipal procurement records, and NCAA facility capital expenditure disclosures preceded structured interviews with stadium operations directors, athletic department facilities managers, bleacher installation contractors, and aluminum fabrication plant engineers. Secondary validation drew from OSHA enforcement records, Texas Department of Insurance windstorm filings, and Florida Building Code product approval registers. Bottom-up project pipeline aggregation triangulated against top-down construction spending forecasts.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects. Segmentation dimensions span installation type, material specification, end-user category, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and new-build permit trajectories. Forecast inputs incorporate ADA Title III enforcement intensity and Sun Belt construction employment indices.
Underlying assumptions cover sustained OSHA workplace safety standard enforcement and stable ICC-500 testing laboratory capacity, with deviation risk concentrated in galvanized steel price volatility and aluminum alloy supply constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Carbon Steel IBC Market