
 Australia Steel Rebar Market | 2026-2036
Australia Steel Rebar Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Steel Rebar Market Intelligence
The transition toward higher-strength Grade 500 and Grade 600 rebar is rotating the Australia Steel Rebar Market towards value-added products that meet advanced engineering specifications. Major domestic producer InfraBuild leverages its extensive manufacturing and recycling network to serve large projects nationwide. Australian Reinforcing Company (ARC) differentiates through its focus on processed and scheduled reinforcing steel for specific construction needs. Meanwhile, Neumann Steel Pty Ltd sustains a strong presence by catering to the construction sector in Queensland and Northern New South Wales.
Steel rebar is a hot-rolled, deformed steel bar used to provide tensile strength to concrete, which is strong in compression but weak in tension. Produced primarily from carbon steel, its surface features deformations or ribs designed to create a superior mechanical bond with the surrounding concrete. This reinforcement is fundamental to the structural integrity of buildings, bridges, and other civil engineering works. High-strength deformed bars constitute the largest product category, driven by structural design codes. The infrastructure end-user segment commands significant volume for major public works, while the residential construction segment provides a consistent demand baseline.
The market operates within a strict regulatory framework overseen by bodies like Standards Australia and the Australian Building Codes Board (ABCB). Standards Australia publishes AS/NZS 4671, the mandatory standard for steel used in concrete reinforcement, defining material properties and testing protocols. The ABCB incorporates these standards into the National Construction Code, making compliance a legal requirement for building projects. Suppliers must therefore align product development and quality assurance with evolving green building standards and circular economy principles to maintain market access.
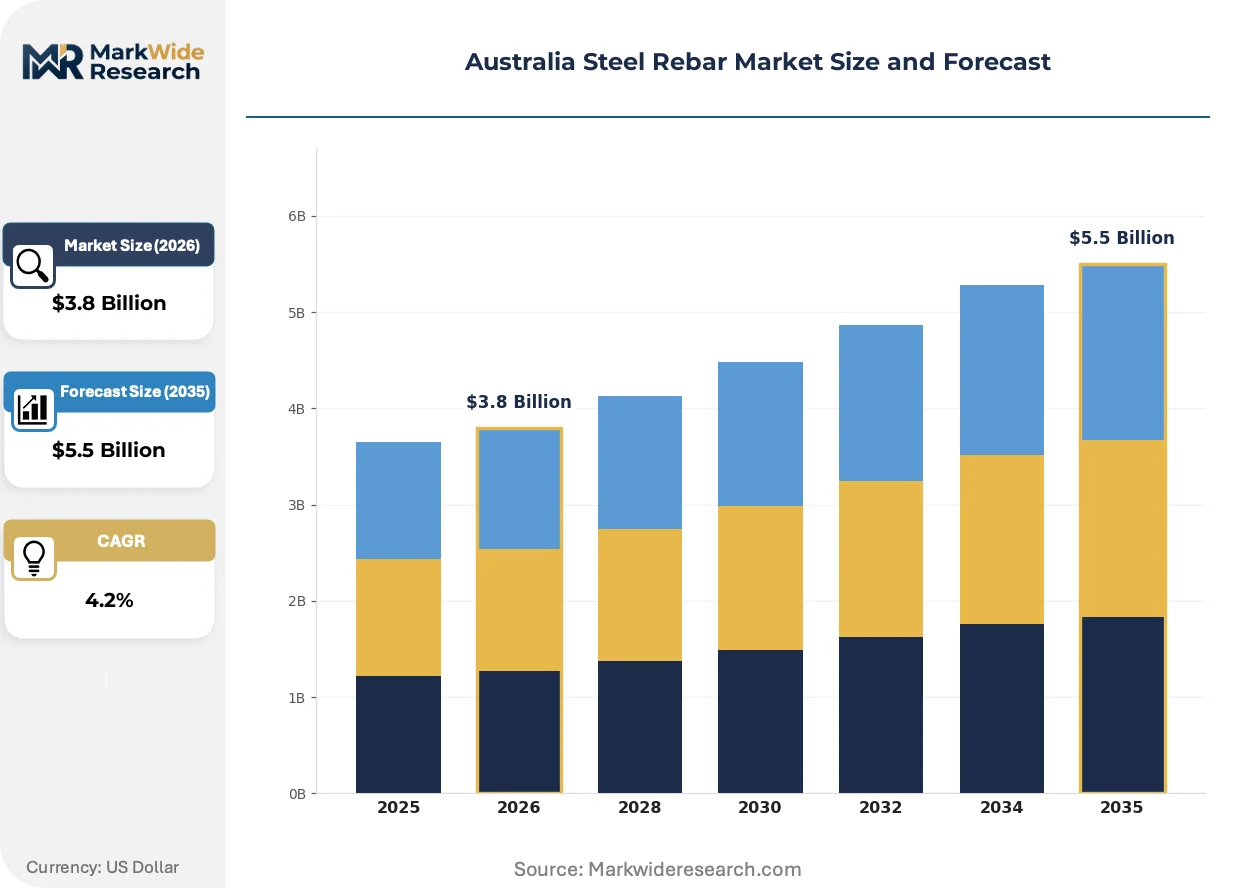
Market Dynamics
The Australian steel rebar market is defined by a structural rotation towards higher-value, specified-grade products. This movement is driven by stringent national construction codes and massive public spending on infrastructure, forcing a departure from commodity-grade steel towards engineered reinforcing solutions.
Growth Catalysts
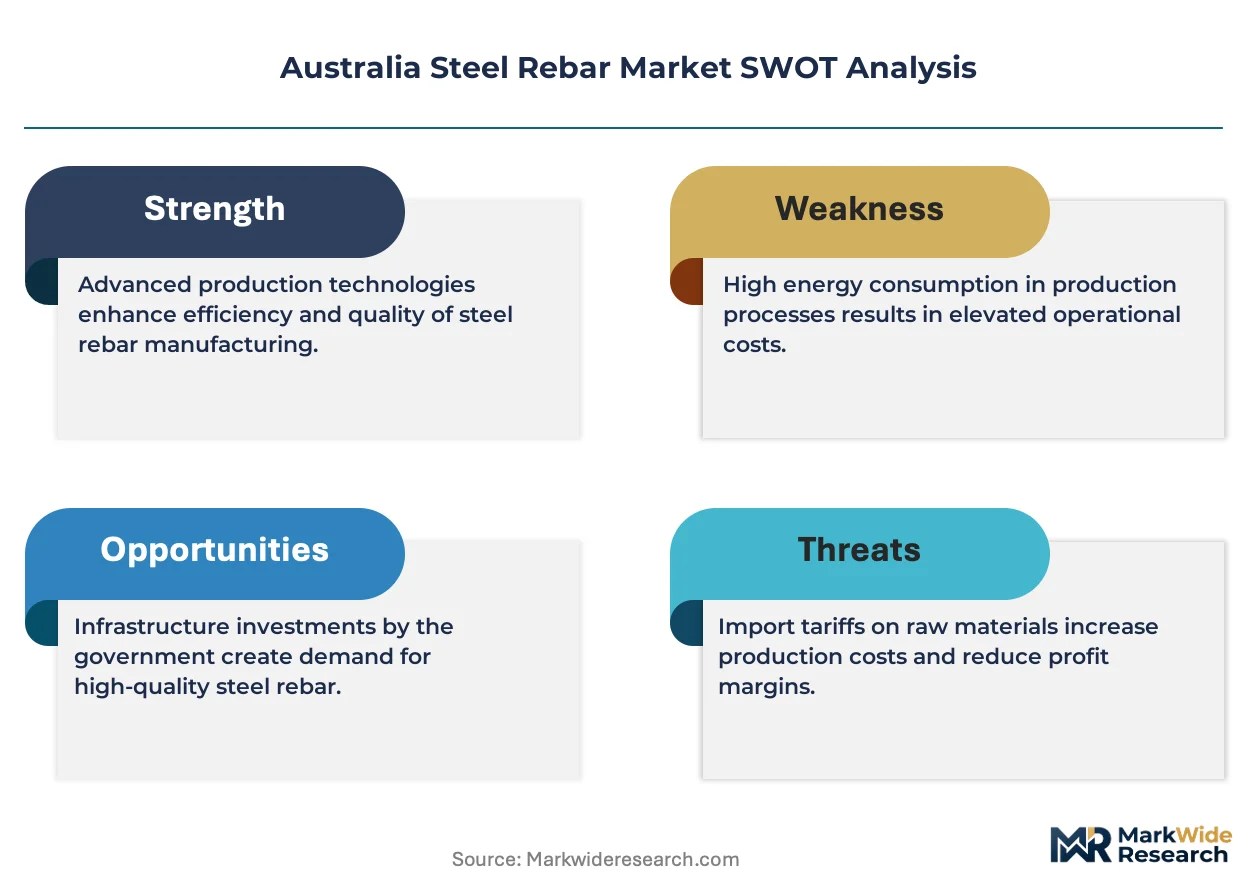
- Sustained Infrastructure Spending:Major government investment in transport and utility infrastructure, particularly in eastern states, creates a consistent, large-volume demand pipeline for high-strength reinforcing steel.
- Mandatory Quality Standards:The enforcement of AS/NZS 4671 through the National Construction Code makes the use of certified, high-quality rebar a legal requirement, protecting domestic producers from non-compliant imports.
- Urban Densification:Continued development of high-rise residential and commercial buildings in metropolitan centers like Sydney and Melbourne requires advanced, high-strength rebar to meet complex structural engineering designs.
Market Restraints
- Input Material Volatility:Fluctuations in the global prices of key raw materials, such as iron ore and coking coal, directly impact the production costs and margin stability for Australian steel mills.
- High Energy Costs:Australia's elevated industrial electricity and gas prices present a significant structural cost disadvantage for energy-intensive steel manufacturing and recycling operations.
- Import Pressure:Despite quality standards, price competition from steel producers in Asia, particularly for standard-grade products, exerts pressure on the lower end of the market.
Strategic Opportunities
- Green Steel Production:Investing in low-emission steelmaking technologies, including electric arc furnaces powered by renewables, offers a path to meet the growing demand for sustainable materials in green-certified buildings.
- Advanced Prefabrication:Expanding capacity for processed rebar, including custom-fabricated cages and mats, addresses construction industry demand for off-site solutions that improve on-site safety and productivity.
- Digital Workflow Integration:Developing digital tools that integrate with Building Information Modeling (BIM) platforms allows for more precise rebar scheduling, reducing waste and improving project management for contractors.
Industry Challenges
- Skilled Labor Deficiencies:A persistent shortage of qualified steel fixers and welders across Australia creates project bottlenecks and increases labor costs for construction contractors.
- Logistical Hurdles:Coordinating the just-in-time delivery of bulky and often customized rebar orders to congested urban construction sites poses a significant and costly logistical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Steel Rebar Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mild Steel, High Strength Deformed, Epoxy Coated, Galvanized End User: Construction, Infrastructure, Residential, Commercial Grade: Grade 400, Grade 500, Grade 600, Grade 700 Distribution Channel: Direct Sales, Wholesalers, Retailers, Online |
| Companies Covered | InfraBuild, Neumann Steel Pty Ltd, Best Bar, Australian Reinforcing Company, Apex Steel, AUSREO, Australian Steel Traders, Reozone, Duferco International Trading Holding Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Steel Rebar Market Strategic Shifts & Innovations
Advancements in material science and the digitalization of construction processes are fundamentally altering product specifications and supply chain expectations in the Australian rebar market. The focus is shifting from simple material supply to integrated reinforcing solutions that offer greater efficiency and performance.
The development of higher-strength steel alloys provides superior performance characteristics. These materials, such as Grade 600 rebar, offer enhanced tensile strength, allowing for less material usage and reduced concrete cross-sections. Structural engineers working on high-rise towers and long-span bridges are specifying these advanced grades. This adoption is bifurcating the market between standard rebar for conventional projects and premium alloys for performance-critical applications.
Regulatory updates from the Australian Building Codes Board (ABCB) are incorporating stricter environmental performance metrics into the National Construction Code. This move is forcing producers to increase transparency regarding recycled content, carbon emissions, and overall lifecycle impact. The infrastructure sector is most affected, as government tenders increasingly require Environmental Product Declarations (EPDs) to verify the sustainability claims of building materials.
A shift in project delivery models is altering rebar procurement. Integrated and collaborative contracting methods are replacing purely transactional purchasing, favoring suppliers who can provide value-added services like digital scheduling and prefabrication. This change is most visible in large-scale civil engineering projects in Victoria and New South Wales, where complexity necessitates deeper supply chain partnerships to manage risk and timelines.
Australia Steel Rebar Market Segmentation
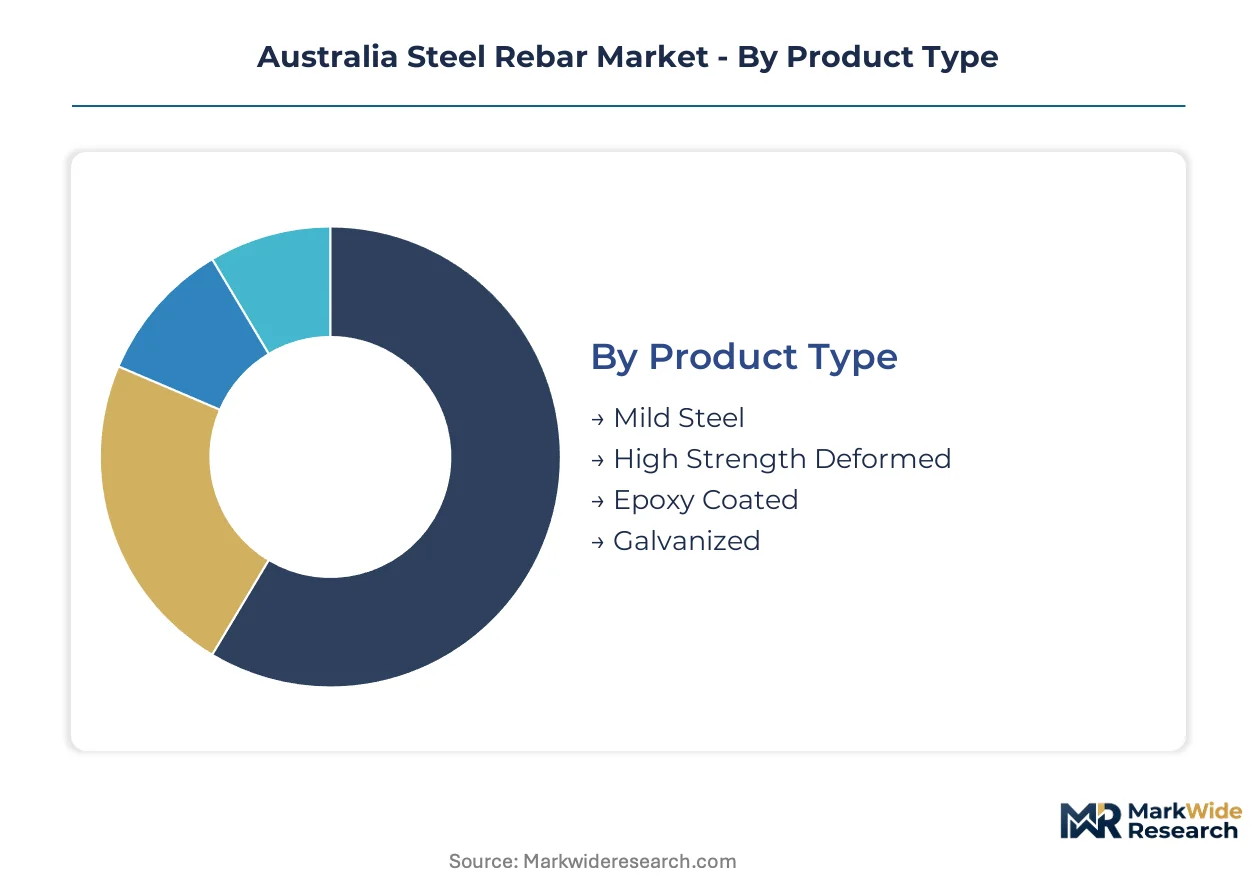
Understanding the segmentation of the Australia steel rebar market provides critical insight into demand patterns and supply chain dynamics. This granular view helps identify key product specifications, dominant end-user applications, and the preferred channels for material procurement across the nation's construction industry.
Product Type:
The product type segmentation for Australian steel rebar illustrates the distinction between locally manufactured standards and specialized imports catering to specific project demands.
- High Strength Deformed:These bars feature surface deformations designed for superior mechanical bonding with concrete, offering enhanced tensile performance. Demand concentrates heavily in large-scale civil engineering projects across New South Wales and Victoria, driven by structural design codes.
- Epoxy Coated:Coated with an epoxy resin, these rebars provide increased corrosion resistance, crucial for structures exposed to harsh environments like coastal areas or chemical agents. Their application is particularly important in marine infrastructure and critical public utilities where longevity is paramount.
- Mild Steel:Characterized by lower carbon content, mild steel rebar offers good ductility and weldability for general construction purposes. This product type primarily serves smaller residential and commercial builds requiring basic reinforcement.
- Galvanized:These rebars are zinc-coated for superior corrosion protection, extending the lifespan of concrete structures in aggressive conditions. Galvanized rebar finds specific use in projects demanding maximal durability in corrosive soil or water environments.
High Strength Deformed holds the largest share; Epoxy Coated is gaining share fastest.
End User:
End-user segments reveal where rebar applications concentrate, from foundational public works to dynamic private sector developments across Australia.
- Infrastructure:This segment encompasses major public works such as roads, bridges, tunnels, and utility networks, requiring substantial volumes of high-strength rebar. Government investment initiatives, particularly in eastern states, create consistent demand for these large-scale projects.
- Residential:Comprising single-family homes, multi-story apartments, and high-density housing, this segment provides a steady baseline demand for various rebar grades. Urban densification in metropolitan areas like Sydney and Melbourne drives consistent rebar consumption.
- Construction:This broad category includes a diverse range of non-residential building projects, including industrial facilities, warehouses, and institutional buildings. Commercial construction in growing regional centers contributes significantly to this segment's demand.
- Commercial:This segment focuses on office buildings, retail complexes, and hospitality venues, often requiring specialized rebar for complex architectural designs. High-rise commercial developments in central business districts are key drivers for this end-use.
Infrastructure is crucial for foundational projects, while Residential addresses evolving urban needs.
Grade:
The grade segmentation highlights material performance tiers, reflecting varying cost structures and engineering requirements within the Australian construction sector.
- Grade 500:This high-strength grade offers a minimum yield strength of 500 MPa, providing superior performance for structural applications. It is widely adopted in major civil engineering and high-rise construction due to its optimal balance of strength and cost-effectiveness.
- Grade 600:Representing a higher tier in strength with a minimum yield strength of 600 MPa, this grade allows for reduced material usage and lighter concrete cross-sections. Structural engineers specify Grade 600 for performance-critical applications like long-span bridges and tall buildings.
- Grade 400:Offering a minimum yield strength of 400 MPa, this grade serves as a standard for general construction where extreme loads are not the primary concern. Grade 400 is typically used in lighter structural elements and non-critical reinforcement.
- Grade 700:This advanced grade provides exceptional strength, enabling significant material optimization and innovative structural designs. Grade 700 is reserved for highly specialized projects demanding maximum performance and reduced concrete volumes.
The market is increasingly prioritizing Grade 600 for its structural advantages, pushing demand away from Grade 400.
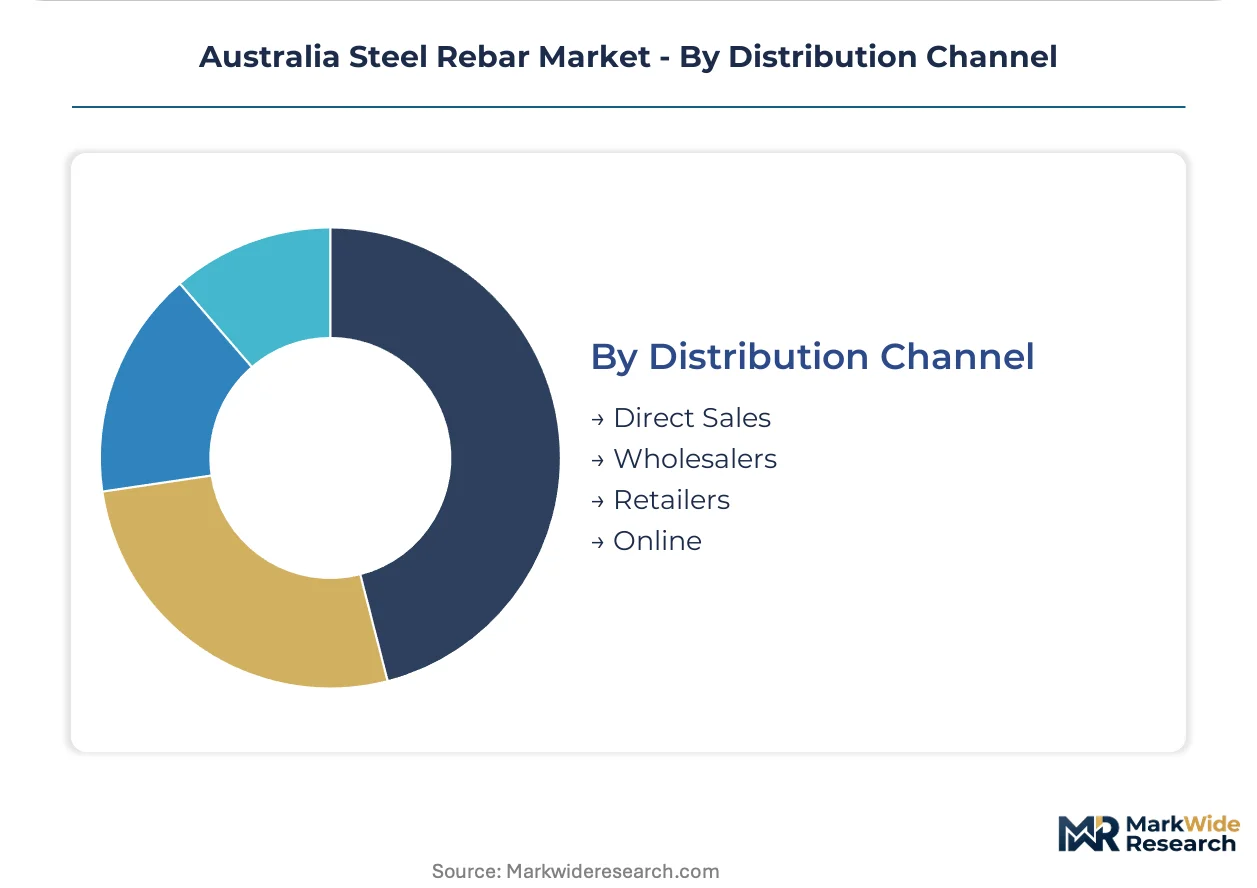
Distribution Channel:
Distribution channels reflect how Australian steel rebar reaches diverse customer types, from large-scale contractors to smaller builders and individual projects.
- Direct Sales:Major rebar producers and large-scale distributors engage in direct sales to significant construction companies and government infrastructure projects. This channel facilitates bulk orders, custom fabrication, and direct supply chain management for large volumes.
- Wholesalers:Wholesalers serve as intermediaries, purchasing rebar in bulk from manufacturers and distributing it to a network of smaller construction firms and retailers. They provide logistical support and inventory management for a broad customer base.
- Retailers:Retail outlets and building material suppliers cater to smaller contractors, individual builders, and DIY projects, offering convenient access to standard rebar sizes. This channel provides immediate availability for smaller-scale construction needs.
- Online:The online channel facilitates convenient ordering and delivery for various customers, including those seeking specialized products or efficient procurement. Digital platforms are gaining traction for managing rebar scheduling and supply for modern construction workflows.
Direct Sales remains the primary conduit for large-scale projects, with Online gaining traction for specialized requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for steel rebar varies significantly across Australia, with commodity-grade products facing higher price sensitivity compared to specialized, high-strength variants required for critical infrastructure. Buyers prioritize cost in residential and general construction, while performance and compliance dominate procurement for major public works. This bifurcation shapes regional market dynamics.
New South Wales
Major government investment in transport infrastructure and high-density residential construction drives significant rebar demand in New South Wales. The state's adherence to the National Construction Code, incorporating AS/NZS 4671, mandates high-quality reinforcing steel for all projects. Sydney's metropolitan area consistently requires advanced rebar grades for its complex structural engineering designs in high-rise developments.
Victoria
Infrastructure projects, including road and rail expansions, along with sustained urban densification, fuel rebar consumption across Victoria. The Victorian government's "Big Build" program ensures a steady pipeline of demand for certified steel products. Melbourne's expanding urban footprint and ongoing commercial developments necessitate high-strength rebar for large-scale building projects.
Queensland
Coastal infrastructure development and resource sector projects underpin rebar demand in Queensland, often requiring corrosion-resistant solutions. The state's building regulations emphasize durability for structures in harsh environments, influencing material specifications. Brisbane and the surrounding regions experience consistent rebar consumption for both public works and residential construction.
Western Australia
Mining and resource sector expansion, alongside public infrastructure upgrades, drives specific rebar requirements in Western Australia. The state's safety standards and project specifications often demand specialized rebar grades for challenging environmental conditions. Perth's urban development and regional industrial projects maintain a baseline demand for reinforcing steel.
Australia Steel Rebar Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the Australian steel rebar market. The market exhibits a tiered structure, with large integrated producers alongside specialized fabricators and distributors. Major players focus on extensive manufacturing networks and value-added services, while smaller entities compete on niche products or regional supply. Strategic partnerships and capacity expansion are dominant competitive moves among key participants.
At the scale-driven end, InfraBuild leverages its extensive manufacturing and recycling network to serve large projects nationwide, exemplifying a vertically integrated producer. Neumann Steel Pty Ltd occupies a strong position by catering to the construction sector in Queensland and Northern New South Wales, representing a regional specialist. Australian Reinforcing Company (ARC) differentiates through its focus on processed and scheduled reinforcing steel for specific construction needs, anchoring the value-added services segment.
| Leading Market Players |
|---|
| InfraBuild |
| Neumann Steel Pty Ltd |
| Best Bar |
| Australian Reinforcing Company |
| Apex Steel |
| AUSREO |
| Australian Steel Traders |
| Reozone |
| Duferco International Trading Holding Australia |
| Others |
Cost & Logistics Intelligence
Large-scale steel rebar production economies of scale dictate supply concentration among a few major domestic players, establishing price floors. This structural configuration influences procurement dynamics across Australia's construction sector.
Pricing Analysis
AS/NZS 4671 dictates the pricing tier structure for Australian steel rebar, ensuring compliance-driven cost differentiation. Project-based and contract-based long-term offtake models dominate large infrastructure procurement, with transactional pricing serving smaller residential builds. Price differentiation stems from higher strength grades like Grade 600 and specialized coatings for corrosion resistance. Pricing softness reflects intense import competition for standard-grade products, making residential construction the most price-sensitive segment compared to performance-focused infrastructure projects.
Supply Chain Analysis
Inbound logistics costs for key raw materials like iron ore and coking coal profoundly influence Australian steel rebar production. Domestic supply concentrates around integrated producers such as InfraBuild and regional specialists, complemented by imports from Asian steel mills. The market relies heavily on scrap steel for Electric Arc Furnace operations. Commodity price volatility and Australia's high energy costs present significant structural risks, while direct sales to large projects and wholesalers for broader distribution define the dominant downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power in the Australian steel rebar market is shifting towards large infrastructure contractors who consolidate procurement volumes. This trend favors suppliers offering integrated reinforcing solutions and digital workflow integration.
For Market Incumbents: Secure long-term supply contracts with major infrastructure clients in New South Wales and Victoria, leveraging extensive manufacturing and recycling networks. Invest in advanced prefabrication capabilities to counter skilled labor deficiencies and improve project efficiency. This approach helps mitigate import pressure from Asian producers by offering value-added, compliant solutions. Focus on green steel production pathways to meet evolving environmental performance metrics in government tenders. For New Entrants and Emerging Players: Certification fast-track programs for specialized, high-strength rebar grades present a clear entry point into niche segments. Target smaller, complex commercial developments in growing regional centers seeking advanced structural solutions. Offer digital tools that integrate with Building Information Modeling (BIM) platforms as a go-to-market angle, reducing waste and improving project management for contractors. This strategy avoids direct competition with established large-scale domestic producers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers offering integrated reinforcing solutions and digital services to large, ongoing infrastructure projects. Long-term viability hinges on companies that demonstrate strong compliance with AS/NZS 4671 and clear pathways to green steel production. Acquisition targets should be regional specialists with strong customer relationships or technology providers enhancing supply chain efficiency. The signal to watch is increased government funding allocations for transport and utility upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Prefabrication | Addresses skilled labor shortages and improves on-site productivity for construction contractors. |
| Investment in Green Steel Technologies | Meets stricter environmental performance metrics and secures market access for green-certified buildings. |
| Digital Integration with BIM Platforms | Enhances rebar scheduling precision, reduces material waste, and optimizes project management. |
| Long-term Offtake Agreements with Governments | Secures consistent demand pipelines for high-strength reinforcing steel in major public works. |
| Strategic Partnerships for Corrosion-Resistant Rebar | Caters to specialized demand from coastal infrastructure projects in harsh environments. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews to gather granular market insights. Structural engineers, construction project managers, rebar fabricators, and procurement officers provided critical perspectives. Secondary validation involved analysis of Standards Australia publications, Australian Building Codes Board (ABCB) reports, and government infrastructure spending plans. A robust triangulation approach, incorporating both bottom-up and top-down data, informed market sizing and segmentation.
The forecast horizon spans the analysis window, utilizing a sophisticated analytical framework to project market trajectory. Segmentation dimensions modeled include product type, end-user, rebar grade, distribution channel, and regional demand patterns. Compound Annual Growth Rates (CAGRs) were derived from historical data analysis and projected growth drivers. Key forecast inputs included anticipated government infrastructure spending and urban densification rates.
Underlying assumptions cover stable economic growth and consistent infrastructure investment, with deviation risk concentrated in global commodity price fluctuations. Forecasts reflect these foundational premises. Recalibration cycles align with material shifts in input material volatility or National Construction Code updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Composite Roof Shingle Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
PU Waterstops Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market