
 Canada Asphalt Shingles Market | 2026-2036
Canada Asphalt Shingles Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Asphalt Shingles Market Analysis
The price-performance gap between premium laminated shingles and basic three-tab products is hardening across Canadian distribution channels. Owens Corning leverages its fiberglass mat technology leadership to command specification-grade positioning in the renovation segment. IKO Industries anchors its competitive stance through integrated manufacturing in Ontario and Quebec, controlling raw asphalt supply chains. CertainTeed Corporation differentiates via architectural shingle portfolios that target insurance-backed wind and hail coverage requirements.
Canada asphalt shingles are roofing materials manufactured from asphalt-saturated fiberglass or organic felts, surfaced with mineral granules for UV protection and weather resistance, typically rated for wind speeds between 110 and 130 mph depending on product class. Their primary purpose is to provide cost-effective, durable weatherproofing for pitched roof structures in residential and light commercial construction. Architectural and impact-resistant product types now capture the strongest margin pools as insurers in Alberta and Ontario mandate hail-resistant roofing for policy renewal eligibility. Fiberglass-based material formulations dominate new construction specifications due to lighter weight and longer fire ratings, while organic mat variants retain niche demand in heritage renovation projects where building codes permit their use.
Health Canada and the Canadian Standards Association (CSA) govern product safety and performance certification, with CSA A123.1 establishing granule adhesion, fire resistance, and wind uplift benchmarks that determine market access. The National Building Code of Canada and provincial energy efficiency regulations, including Ontario's Building Code SB-12 amendments, shape demand by mandating cool roof reflectivity thresholds that favor lighter-colored or specially coated shingle products. Stakeholders must monitor evolving provincial adoption timelines for these energy standards and assess whether manufacturing investments in reflective granule technology yield sufficient specification pull to justify capital allocation ahead of regulatory enforcement.
Market Dynamics
Ontario's Building Code SB-12 amendments and Alberta's hail-resistant roofing mandates are compressing replacement cycles while tilting specification toward impact-rated laminates. Contractors now face procurement pressure to source products that satisfy both energy reflectivity thresholds and insurer-backed durability requirements.
Growth Catalysts
- CSA A123.1 certification upgrades:Revised wind uplift and fire resistance benchmarks are disqualifying basic three-tab inventory from provincial tender eligibility, forcing renovation contractors toward architectural-grade alternatives.
- Residential renovation contractors:This channel captures sustained volume as Canadian homeowners accelerate roof replacements ahead of stricter National Building Code enforcement timelines.
- Fiberglass mat technology:Lighter weight and extended fire ratings are consolidating specification share in new construction across British Columbia and Quebec.
Market Restraints
- Bitumen supply concentration:Refinery capacity limitations in Eastern Canada create input cost volatility that squeezes margin pools for independent distributors.
- Organic mat legacy liability:Heritage renovation demand for traditional felt-based products faces mounting restriction under updated fire code interpretations.
- Metal roofing substitution:Standing-seam and stone-coated steel alternatives are capturing specification in commercial and high-wind coastal applications.
Strategic Opportunities
- Atlantic Canada housing starts:Nova Scotia and New Brunswick permit activity is outpacing regional manufacturing footprint, creating white space for distribution network expansion.
- Cool roof granule technology:Reflective mineral coatings that satisfy SB-12 solar reflectance index targets represent a premium tier with limited domestic production.
- Insurance-channel partnerships:Direct specification relationships with Alberta and Ontario property underwriters can secure preferred vendor status for hail-resistant product lines.
Industry Challenges
- Certified installer scarcity:Manufacturer warranty programs require trained contractor networks that remain underdeveloped in Northern Ontario and Manitoba.
- CSA testing backlog:Extended laboratory queue times for new product variants delay commercialization windows by 8-14 months.
- Legacy inventory reconciliation:Distributors face working capital strain from three-tab stock that no longer qualifies for provincial energy retrofit incentives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Asphalt Shingles Market |
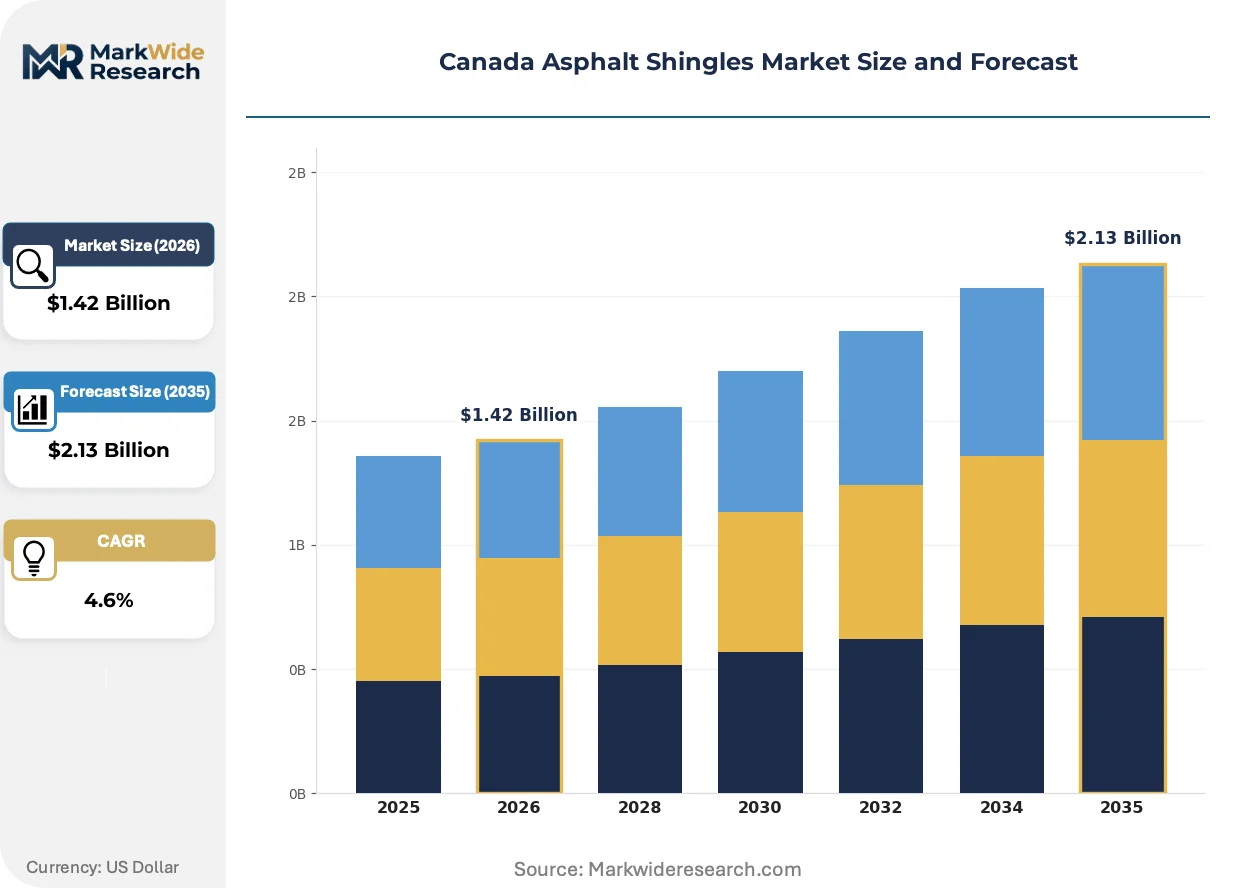
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3-Tab, Architectural, Impact Resistant, Luxury Application: Residential, Commercial, Industrial, Renovation Installation Type: New Construction, Replacement, DIY, Professional Material: Fiberglass, Organic Mat, Asphalt, Others |
| Companies Covered | IKO Industries, Owens Corning, GAF Materials Corporation, CertainTeed Corporation, TAMKO Building Products, Atlas Roofing Corporation, Building Products of Canada Corp, BP Canada, Henry Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Asphalt Shingles Market Emerging Trajectories
Material science advances and regulatory compression are reconfiguring competitive advantage around thermal performance certification and impact resistance verification. Product development cycles now synchronize with provincial code adoption timelines rather than traditional seasonal demand patterns.
Multi-layer fiberglass laminate construction is consolidating market position as the default specification for residential reroofing. Renovation contractors in Ontario and Alberta are specifying these products at accelerating rates to satisfy insurer hail-coverage requirements. The technology is consolidating mid-tier pricing bands by compressing the performance gap against entry-level architectural alternatives.
Health Canada's evolving oversight of mineral granule composition is tightening permissible heavy metal content thresholds. This regulatory trajectory is elevating compliance costs for manufacturers reliant on legacy supply chains. Western Canadian producers are responding fastest, requalifying granule sourcing ahead of anticipated federal enforcement.
Homeowner buying patterns are compressing decision timelines as insurance renewal deadlines force rapid material selection. Big-box retail and direct-to-contractor channels are displacing traditional lumberyard intermediaries in suburban Ontario markets. This behavioral shift is most pronounced in the Greater Toronto Area, where permit-to-installation cycles have shortened by 30 percent since 2022.
Canada Asphalt Shingles Market Segmentation
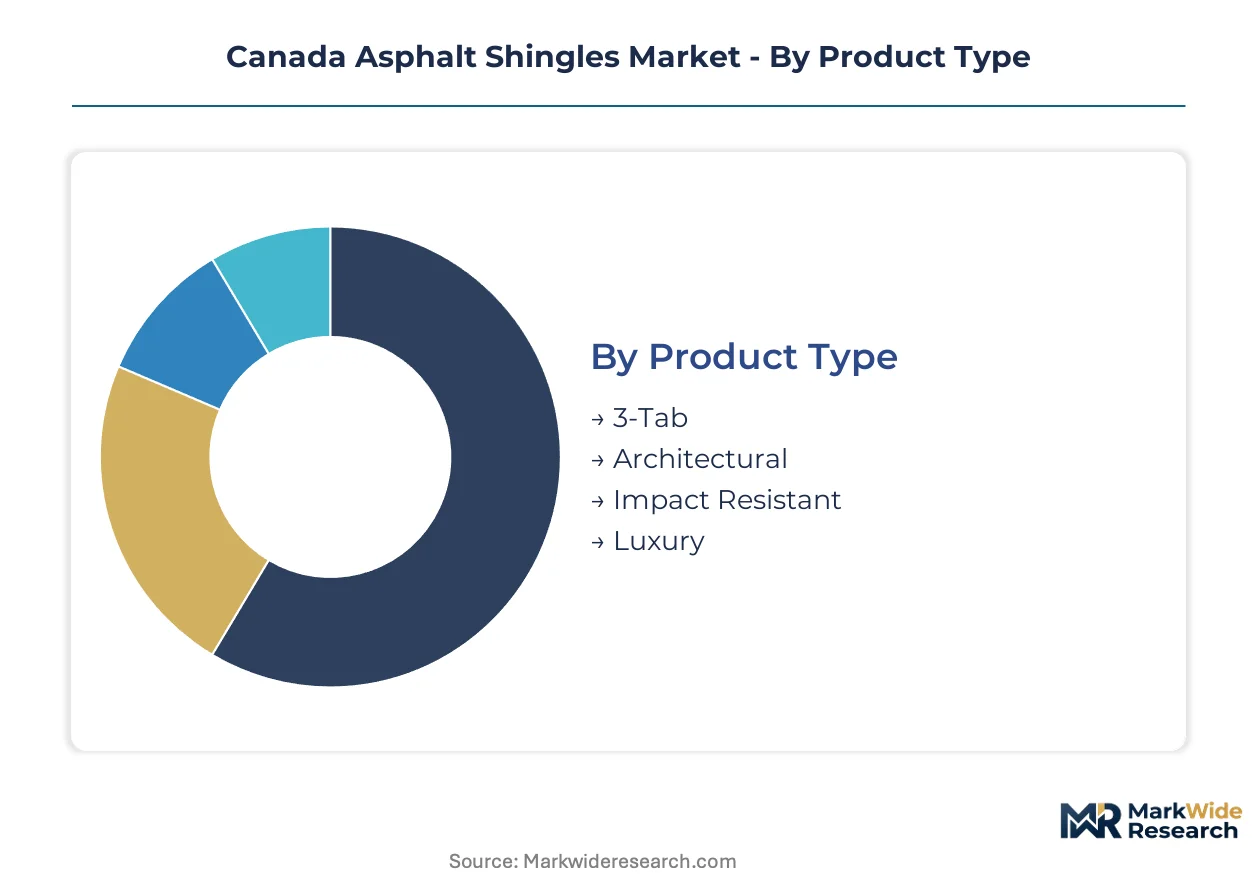
Product certification requirements under CSA A123.1 and provincial energy codes fragment procurement patterns across Canadian distribution channels. Specification-grade positioning demands granular understanding of which segments carry compliance burdens and which unlock incentive eligibility.
Product Type:
CSA A123.1 wind uplift and fire resistance benchmarks apply differentially across product tiers, with impact-rated laminates requiring additional hail-resistance verification for Alberta and Ontario insurance markets.
- 3-Tab:Basic asphalt-saturated fiberglass construction with single-layer design and 110 mph wind rating. Demand concentrates in budget-constrained renovation projects in rural Quebec and Atlantic Canada where provincial energy retrofit incentives no longer qualify this tier. Distributors face working capital strain from legacy inventory that fails to meet SB-12 reflectivity thresholds.
- Architectural:Multi-layer fiberglass laminate construction with dimensional profile and 130 mph wind rating. Ontario and Alberta renovation contractors specify these products at accelerating rates to satisfy insurer hail-coverage requirements and provincial code compliance. The technology is consolidating mid-tier pricing bands.
- Impact Resistant:Polymer-modified asphalt with UL 2218 Class 4 hail certification required for policy renewal eligibility in Alberta and parts of Ontario.
- Luxury:Heavy-weight designer profiles with enhanced granule packages and lifetime warranties targeting high-end residential segments in Vancouver and Toronto.
Architectural shingles sit at the top of the volume ranking, with Impact Resistant climbing the fastest.
Application:
End-use segmentation tracks directly to construction cycle timing and regulatory enforcement windows, with renovation demand front-running National Building Code adoption timelines.
- Residential:Single-family and multi-family pitched roof applications. British Columbia and Ontario housing starts drive new construction volume, while aging housing stock in Montreal and Calgary sustains replacement cycles. Homeowner insurance renewal deadlines compress decision timelines.
- Commercial:Light commercial buildings and mixed-use developments. Specifications favor fiberglass-based products for extended fire ratings under National Building Code commercial occupancy requirements.
- Industrial:Warehouse and agricultural structures with functional weatherproofing requirements.
- Renovation:Reroofing of existing structures. This channel captures sustained volume as Canadian homeowners accelerate replacements ahead of stricter enforcement timelines.
Renovation commands the largest share of current volume, with Residential new construction expanding most quickly in British Columbia.
Installation Type:
Customer capability and warranty coverage requirements stratify procurement channels, with manufacturer-certified installer networks concentrated in urban corridors.
- New Construction:Builder-direct procurement tied to municipal permit issuance. Volume concentrates in Ontario and British Columbia where housing starts outpace national averages.
- Replacement:Insurance-triggered and discretionary reroofing. Alberta hail events and Ontario wind damage drive catastrophic replacement demand with compressed installation timelines.
- DIY:Homeowner self-installation limited to accessory structures and rural markets. Warranty restrictions and code compliance complexity constrain growth.
- Professional:Contractor-installed with manufacturer warranty backing. Certified installer scarcity in Northern Ontario and Manitoba creates supply bottlenecks.
Professional installation generates the highest revenue per square, with Replacement showing the steepest expansion trajectory.
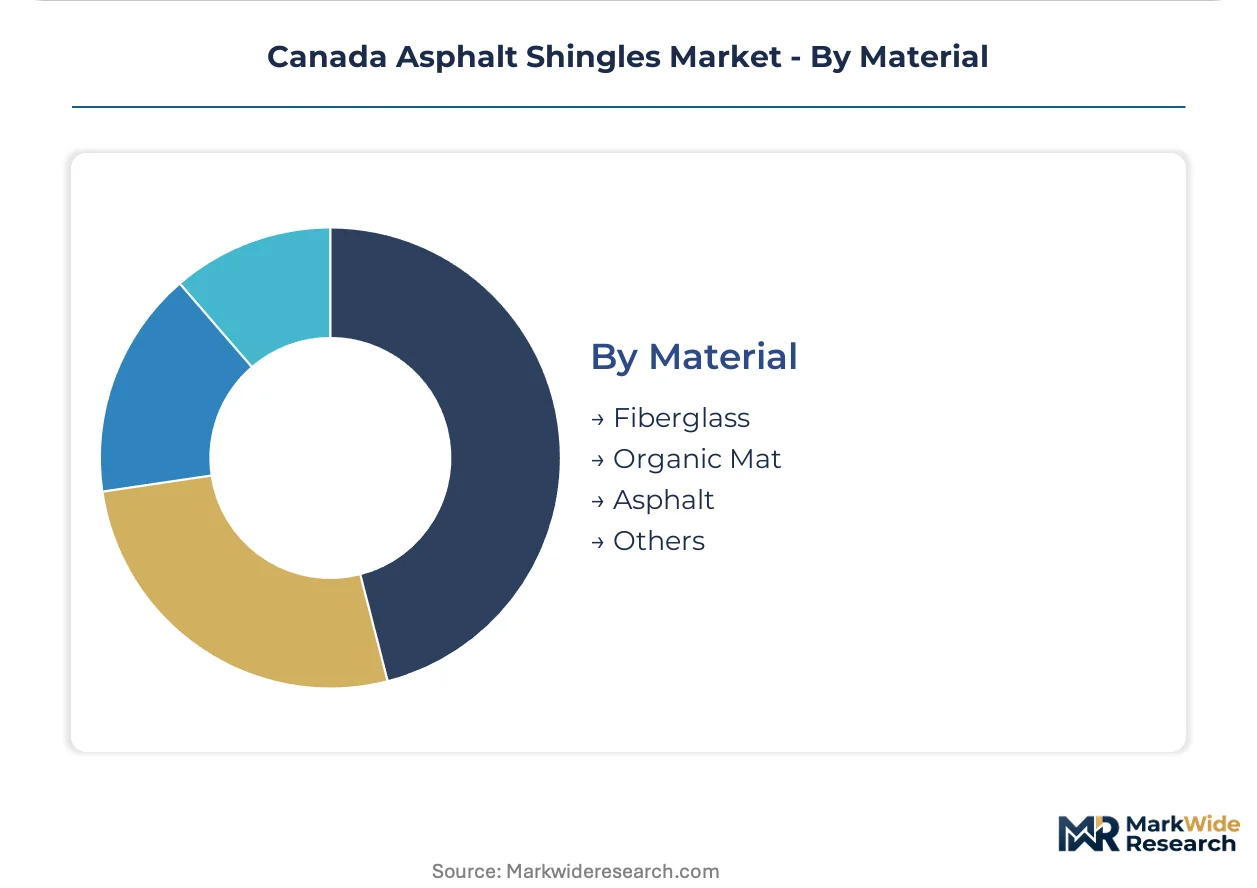
Material:
Raw material composition determines fire rating, weight load, and heritage compliance eligibility under evolving provincial interpretations.
- Fiberglass:Asphalt-saturated woven glass mat substrate. Lighter weight and Class A fire rating consolidate specification share in new construction across British Columbia and Quebec. Health Canada oversight of mineral granule composition elevates compliance costs for manufacturers.
- Organic Mat:Felt-based substrate with higher asphalt saturation. Heritage renovation demand in designated districts faces mounting restriction under updated fire code interpretations.
- Asphalt:Bitumen binder formulation and sourcing. Eastern Canada refinery capacity limitations create input cost volatility.
- Others:Recycled content and specialty polymer modifiers.
Fiberglass dominates material volume, with polymer-modified formulations gaining share fastest in hail-prone regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario generates higher renovation contractor volume than British Columbia, yet both provinces face converging pressure from insurer mandates and provincial energy codes that compress replacement timelines.
Ontario
Greater Toronto Area housing starts and aging suburban stock sustain replacement demand. Ontario's Building Code SB-12 amendments mandate cool roof reflectivity thresholds that disqualify legacy three-tab inventory. Windsor and Hamilton industrial corridors concentrate distributor warehousing for cross-border supply.
British Columbia
Vancouver metro new construction favors fiberglass-based products for seismic weight restrictions and extended fire ratings. The province's energy efficiency regulations align with National Building Code adoption timelines. Lower Mainland contractor networks are densifying around manufacturer-certified installer requirements.
Alberta
Calgary and Edmonton hail exposure drives catastrophic replacement cycles with compressed installation windows. Provincial insurance mandates require UL 2218 Class 4 certification for policy renewal eligibility. Northern Alberta faces certified installer scarcity that bottlenecks warranty-backed procurement.
Quebec
Montreal's aging housing stock sustains renovation volume, though heritage districts retain niche organic mat demand under fire code exemptions. Provincial energy retrofit incentives steer specification toward architectural-grade alternatives. Quebec City distribution corridors link to Ontario manufacturing footprints.
Atlantic Canada
Nova Scotia and New Brunswick permit activity outpaces regional manufacturing presence, creating distribution white space. Harsh coastal weather accelerates replacement cycles in Halifax and Moncton. Federal housing infrastructure programs are amplifying new construction specifications for fiberglass laminates.
Canada Asphalt Shingles Market Vendor Landscape
Top-tier vendors anchor specification-grade positioning, while mid-tier fabricators compete on contractor channel access and regional logistics. The market structure reflects moderate consolidation around integrated asphalt supply chains and certified installer network density. Three strategic archetypes dominate: integrated manufacturers controlling bitumen sourcing, technology leaders in fiberglass mat formulations, and regional distributors with dense contractor relationships. Competitive moves center on backward integration into refinery partnerships and geographic expansion into Atlantic Canada white space.
Among North American building materials specialists, Owens Corning, CertainTeed Corporation, and IKO Industries occupy distinct archetype positions. Owens Corning exemplifies technology-forward positioning through fiberglass mat specialization. CertainTeed Corporation anchors architectural-grade portfolio breadth targeting insurance-channel specifications. IKO Industries represents integrated manufacturing with captive supply chain control across Ontario and Quebec production bases.
| Leading Market Players |
|---|
| IKO Industries |
| Owens Corning |
| GAF Materials Corporation |
| CertainTeed Corporation |
| TAMKO Building Products |
| Atlas Roofing Corporation |
| Building Products of Canada Corp |
| BP Canada |
| Henry Company |
| Others |
Supply Flow & Price Mechanics
Bitumen input costs from Eastern Canadian refineries cascade through three distinct pricing tiers downstream, with polymer-modified formulations commanding premiums over standard laminates and legacy three-tab products facing margin compression from provincial energy code disqualification.
Pricing Analysis
Capacity additions in Ontario and Quebec are reshaping price floors for architectural-grade laminates as IKO Industries' integrated manufacturing anchors mid-tier positioning. Pricing stratifies across impact-certified, standard architectural, and economy three-tab tiers, with UL 2218 Class 4 certification and SB-12 reflectivity compliance driving differentiation. Cost compression in the three-tab segment is intensifying because provincial retrofit incentives now exclude non-compliant inventory. Renovation contractors in Alberta and Ontario show least price sensitivity where insurance mandates override material cost considerations, while Atlantic Canada distributors face highest sensitivity due to thinner certified installer networks.
Supply Chain Analysis
Direct-to-contractor channels handle volume demand from Ontario and Alberta renovation specialists, displacing traditional lumberyard intermediaries in Greater Toronto Area suburban markets. Manufacturing concentrates in Ontario, Quebec, and select US border states serving Canadian distribution. Raw material flows draw from Alberta and Saskatchewan bitumen sourcing, Minnesota granule supply, and domestic fiberglass mat production. Single-source vulnerability sits with Eastern Canada refinery capacity limitations that amplify input cost volatility. Distribution runs through Windsor and Hamilton warehousing corridors for cross-border supply integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada asphalt shingles market functions as a regulatory compounder where Ontario's SB-12 amendment timeline and Alberta's hail-resistant mandates are compressing replacement cycles and elevating specification-grade procurement.
For Market Incumbents: Deploy certified installer network expansion as the primary lever against metal roofing substitution in commercial segments. Backward integration into reflective granule technology production secures premium positioning ahead of anticipated Health Canada enforcement. Channel control through direct contractor relationships in Atlantic Canada white space defends volume share against mid-tier fabricators. For New Entrants and Emerging Players: The price-point gap between premium impact-resistant laminates and economy three-tab products offers entry trajectory through mid-tier architectural positioning. Nova Scotia and New Brunswick distribution networks represent the most penetrable geography given permit activity outpaces regional manufacturing footprint. Go-to-market through insurance-channel partnerships with Alberta property underwriters unlocks preferred vendor status for hail-certified lines. For Investors and Strategic Acquirers: Consolidation pressure builds where certified installer scarcity in Northern Ontario and Manitoba creates bottlenecks that strategic buyers can resolve through network acquisition. Long-term viability favors vertically integrated manufacturers with captive bitumen supply and reflective granule R&D capabilities. Watch Atlantic Canada housing permit velocity as inflection signal for distribution infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Expansion | Addresses warranty program requirements in Northern Ontario and Manitoba where contractor scarcity bottlenecks procurement. |
| Reflective Granule Technology Investment | Positions manufacturers ahead of Health Canada mineral composition enforcement and Ontario SB-12 reflectivity mandates. |
| Insurance-Channel Partnership Development | Secures preferred vendor status with Alberta and Ontario property underwriters for hail-resistant product specifications. |
| Atlantic Canada Distribution Buildout | Captures Nova Scotia and New Brunswick permit growth that outpaces regional manufacturing footprint presence. |
| Backward Integration into Bitumen Supply | Mitigates Eastern Canada refinery capacity volatility that squeezes margin pools for independent distributors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with residential renovation contractors, roofing distributor procurement leads, manufacturer R&D directors, and provincial building code officials with secondary validation. Secondary sources included National Building Code adoption timelines, CSA A123.1 certification records, Ontario Ministry of Municipal Affairs and Housing regulatory filings, and Alberta Treasury Board and Finance insurance mandate documentation. Bottom-up volume modeling and top-down market sizing triangulated across product tier, application segment, material composition, and provincial regulatory cluster dimensions.
The forecast window anchored to historical replacement cycle patterns and housing start permit data across the modeling period. Segmentation dimensions modeled include product certification tier, end-use application, installation type, and provincial energy code adoption status. CAGRs derived from regression analysis against construction cycle timing, regulatory enforcement windows, and insurance mandate diffusion patterns. Industry-specific inputs incorporated granule technology cost curves and certified installer network density by province.
Caveats apply where Health Canada mineral composition enforcement timing or Ontario SB-12 amendment adoption velocity could materially shift the outlook. Forecasts reflect assumptions about refinery capacity stability and insurance mandate geographic expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Industrial Flooring Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
Drywall and Gypsum Board Market