
 Portland Cement Market | 2026-2036
Portland Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Portland Cement Market Intelligence
Multi-source procurement among ready-mix concrete suppliers is broadening as volatility in energy and clinker costs pressures margin stability. LafargeHolcim leverages captive limestone reserves across North American quarries to sustain cost predictability. Heidelberg Materials anchors European production through kiln efficiency investments. Cemex competes in Latin American markets via integrated coastal distribution networks.
Portland cement is a hydraulic binder produced by pulverizing clinker—composed primarily of calcium silicates, aluminates, and ferrites—after firing raw materials at approximately 1,450 degrees Celsius; its primary purpose is to set and harden through hydration when mixed with water, forming the structural matrix for concrete in buildings, roads, and civil infrastructure. Ordinary Portland Cement dominates volume throughput in residential construction, where standard compressive strength grades satisfy mass housing specifications. White Cement commands premium positioning in commercial facades and architectural finishes where aesthetic performance justifies higher unit economics. Infrastructure Development applications for Portland Pozzolana Cement are expanding fastest among government agencies prioritizing sulfate resistance and reduced embodied carbon in bridge and dam foundations.
The EPA enforces National Emission Standards for Hazardous Air Pollutants at US cement kilns, while the EU Green Deal and F-Gas Regulation constrain clinker-to-cement ratios and process emissions across European plants. These frameworks elevate compliance capital requirements and favor producers with pre-calciner technology and alternative fuel integration. Stakeholders must monitor regulatory tightening in carbon-intensive jurisdictions to anticipate stranded asset risk and redirect capacity toward low-clinker product portfolios.
Market Dynamics
The EU Carbon Border Adjustment Mechanism is forcing cement importers to internalize embedded emissions costs, while kiln electrification trials and alternative fuel substitution reshape capital allocation across production bases.
Growth Catalysts
- Smart-city infrastructure mandates:India's urban mission programs are absorbing record volumes of ordinary Portland cement for metro rail, affordable housing, and water treatment facilities.
- Alternative fuel integration:Waste-derived fuels and biomass co-processing in pre-calciner kilns reduce fossil fuel exposure and align with EU Green Deal emission trajectories.
- Sulfate-resistant specification expansion:Bridge and dam foundations in coastal zones are shifting toward Portland Pozzolana Cement for durability compliance.
Market Restraints
- Clinker-to-cement ratio constraints:The EU F-Gas Regulation and national carbon budgets limit process emissions, capping output intensity at integrated plants.
- Limestone reserve concentration:High-purity carbonate deposits cluster in specific quarry regions, creating geographic supply bottlenecks for quality-grade production.
- Geopolymer substitution threat:Fly-ash and slag-based binders are capturing specification share in non-structural applications where compressive strength requirements relax.
Strategic Opportunities
- Carbon capture retrofit deployment:Post-combustion amine scrubbing and oxy-fuel kiln modifications open compliance pathways for legacy assets facing EU ETS tightening.
- White cement aesthetic premium:Commercial facade and architectural finish segments in Gulf Cooperation Council states reward higher unit economics for low-iron clinker.
- Rural road connectivity programs:India's Pradhan Mantri Gram Sadak Yojana is channeling blended cement into low-volume traffic infrastructure.
Industry Challenges
- Process engineer scarcity:Specialized expertise in pyroprocessing and alternative fuel chemistry is concentrating at established producers, constraining new entrant scale-up.
- Integrated certification timelines:Environmental Product Declarations and ISO 14001 extensions for carbon accounting extend product qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portland Cement Market |
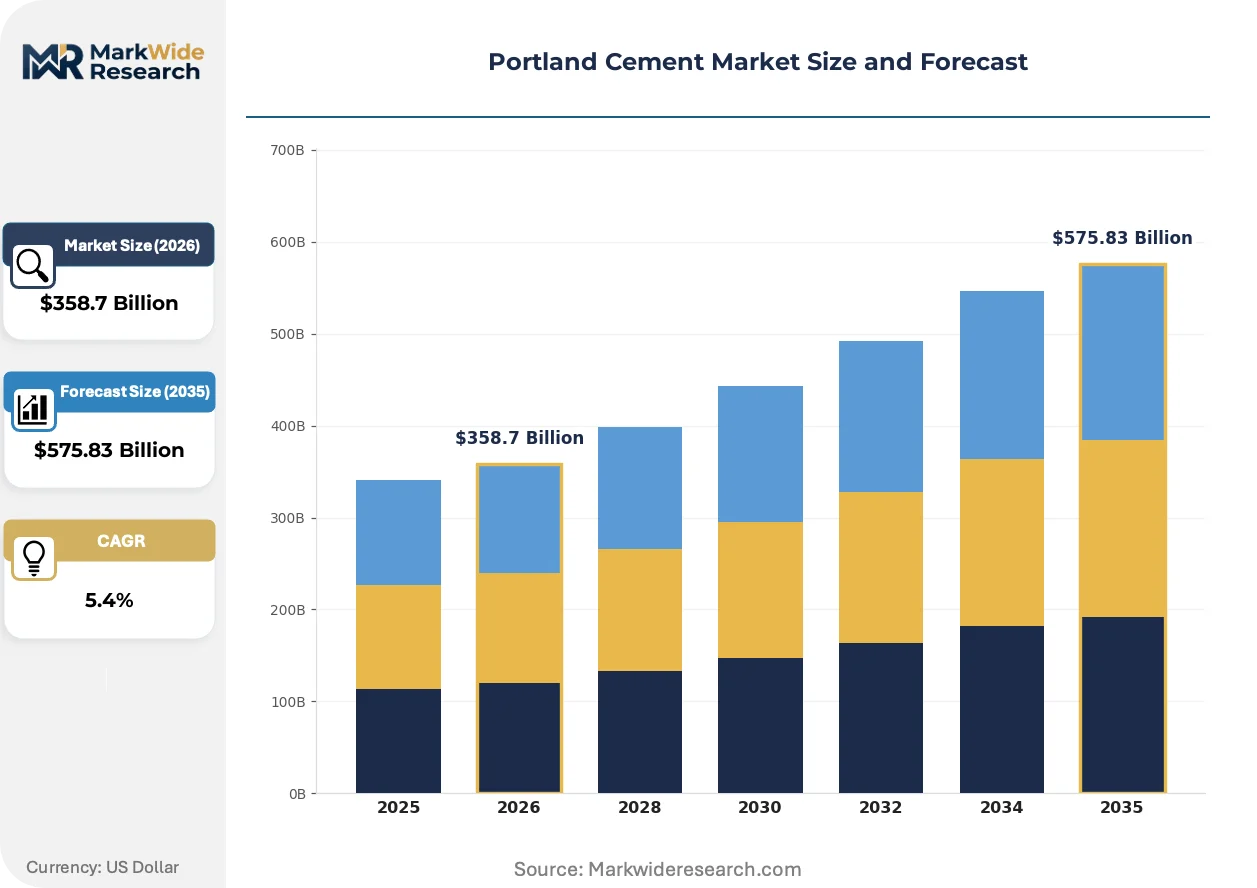
| Market Size in 2026 | $358.7 Billion |
| Market Size in 2035 | $575.83 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ordinary Portland Cement, Portland Pozzolana Cement, Sulfate Resisting Cement, White Cement Application: Residential Construction, Commercial Construction, Infrastructure Development, Road Construction Distribution Channel: Wholesale, Retail, Online Sales, Direct Sales End User: Contractors, Builders, Government Agencies, Industrial Users |
| Companies Covered | CRH plc, Eagle Materials, LafargeHolcim, Ash Grove Cement Company, Martin Marietta, Heidelberg Materials, Buzzi Unicem USA, Argos USA Corporation, Cemex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portland Cement Market Strategic Shifts & Innovations
Decarbonization imperatives are compressing technology adoption cycles across the cement value chain, with digital kiln control, alternative chemistries, and supply chain traceability emerging as concurrent transformation vectors.
Calcined clay activation is converging with limestone calcined clay cement (LC3) formulations to enable 50% clinker reduction without sacrificing early strength performance. Infrastructure contractors in Brazil and Colombia are piloting LC3 for dam and highway specifications. The technology is converging with existing grinding infrastructure, allowing producers to reconfigure finish mills rather than rebuild pyroprocessing lines.
The EU Carbon Border Adjustment Mechanism phases in full carbon cost parity for imported cement from 2026, elevating compliance documentation burdens for non-EU suppliers. Turkish and North African exporters face the steepest adjustment trajectories. Blended cement portfolios with lower clinker factors gain relative competitiveness under the new border levy structure.
Buyers are consolidating procurement volumes under long-term offtake agreements with fixed carbon-adjusted pricing clauses. Ready-mix concrete suppliers in Germany and France are displacing spot market purchasing with 3-5 year supply contracts tied to verified emission reductions. This concentration is most visible in public infrastructure tenders where embodied carbon thresholds now determine bid eligibility.
Portland Cement Market Segmentation
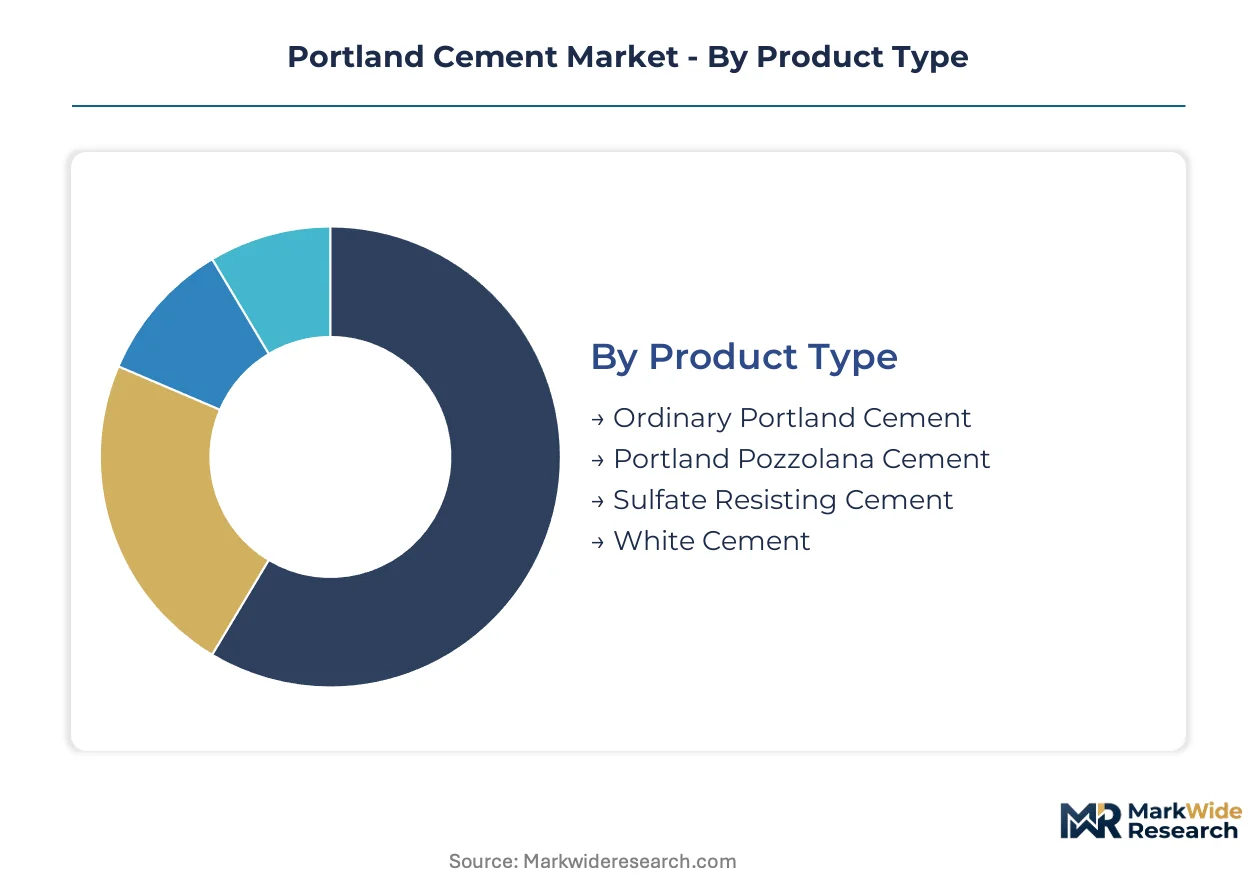
Portland cement segmentation reveals how product chemistry, project scale, and procurement channel determine margin capture. Specification-grade differentiation separates commodity volume from premium positioning across construction verticals.
Product Type:
The customization-to-standardization spectrum spans from mass-market Ordinary Portland Cement to specification-driven White Cement, with performance variants occupying mid-tier positioning.
- Ordinary Portland Cement:Standard calcium silicate composition with 28-day compressive strength grades of 33, 43, and 53 MPa under BIS and ASTM specifications. Demand concentrates in India's affordable housing and Pradhan Mantri Awas Yojana projects, where cost-per-bag sensitivity dominates contractor procurement decisions.
- White Cement:Low-iron clinker formulation below 0.4% Fe₂O₃ content, requiring high-purity limestone and controlled kiln atmosphere. Gulf Cooperation Council commercial facade projects absorb premium volumes, with aesthetic performance justifying 3-4x unit economics over gray cement grades.
- Portland Pozzolana Cement:Fly ash or calcined clay substitution up to 35% by mass, delivering sulfate resistance and reduced embodied carbon for coastal infrastructure.
- Sulfate Resisting Cement:Tricalcium aluminate limitation below 5%, specified for sewage treatment plants and marine foundation work.
Most installed capacity flows through Ordinary Portland Cement. Expansion is steepest in Portland Pozzolana Cement.
Application:
Volume concentration versus value capture varies sharply across project types, with government-funded infrastructure commanding longest contract tenors.
- Infrastructure Development:Dam, bridge, and metro rail specifications requiring blended cement with 50-year durability warranties. India's smart-city programs and Bharatmala highway corridors channel record procurement volumes through state public works departments.
- Residential Construction:Mass housing and individual home building across tier-2 and tier-3 Indian cities, where 43-grade Ordinary Portland Cement satisfies structural code minimums at lowest delivered cost.
- Commercial Construction:High-rise office and retail complexes specifying higher-grade concrete with pumped placement requirements.
- Road Construction:Pavement concrete and rigid highway surfacing using rapid-hardening formulations for minimized traffic closure windows.
Residential Construction absorbs the greatest tonnage. Infrastructure Development is climbing the fastest.
Distribution Channel:
Channel selection reflects buyer scale, with bulk procurement favoring direct mill relationships while fragmented demand routes through intermediaries.
- Wholesale:Bulk bag and loose cement distribution to ready-mix concrete plants and large project sites, capturing economies through 50-tonne minimum order thresholds.
- Direct Sales:Long-term offtake agreements with fixed carbon-adjusted pricing, now displacing spot purchasing among German and French infrastructure contractors under EU ETS compliance pressure.
- Retail:Bagged cement through building material dealers serving individual builders and small contractors.
- Online Sales:Emerging digital procurement platforms aggregating fragmented demand for price transparency.
Wholesale channels move the largest cement volumes. Direct Sales is gaining share fastest.
End User:
Buyer sophistication determines specification stringency, with public agencies embedding carbon thresholds into bid eligibility while industrial users prioritize process consistency.
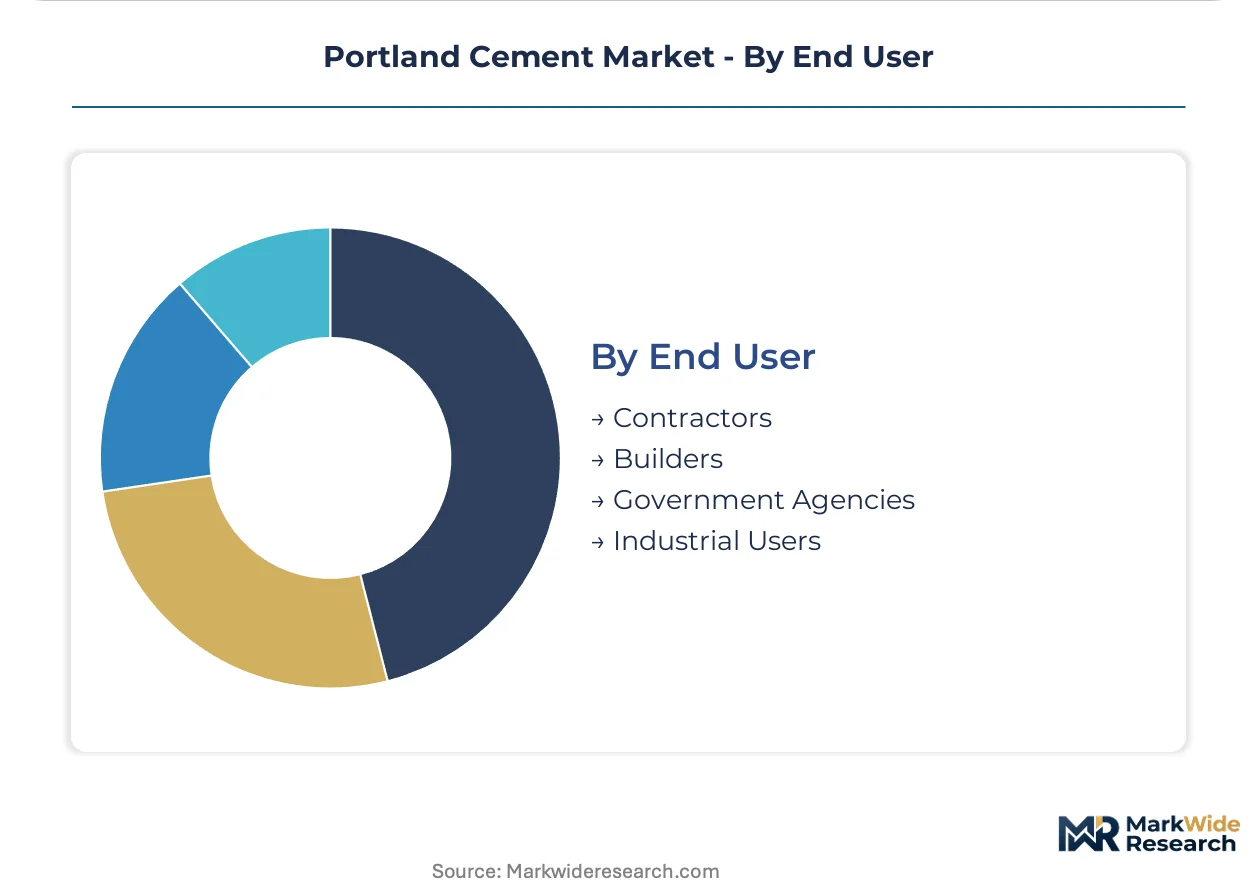
- Government Agencies:Central and state public works departments in India, Brazil, and Vietnam mandating Portland Pozzolana Cement for embodied carbon reduction in bridge and dam tenders.
- Contractors:Tier-1 construction firms managing multi-year infrastructure projects with integrated supply chain control over clinker sourcing.
- Builders:Residential developers optimizing material cost per square meter across high-volume housing estates.
- Industrial Users:Precast concrete manufacturers and cement product fabricators requiring consistent setting time for automated production lines.
Government Agencies command the most structured procurement pipelines. Contractors are expanding specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rajasthan-Gujarat cement belt anchors capacity concentration for the world's most populous democracy, with integrated plants clustered around limestone deposits in Chittorgarh and Sirohi districts.
India
Pradhan Mantri Awas Yojana and smart-city missions absorb record OPC volumes across tier-2 urban centers. BIS mandates 33, 43, and 53 MPa strength grades for structural concrete. UltraTech and Ambuja operate integrated kilns in Gujarat's coastal zone, supplying blended cement for Bharatmala highway corridors.
United States
EPA NESHAP compliance drives kiln retrofits at Texas and California plants serving Sun Belt construction. Infrastructure Investment and Jobs Act funding channels Portland cement into bridge rehabilitation across the Midwest. Eagle Materials and Ash Grove maintain captive limestone positions in the Mountain West to offset fuel cost volatility.
Germany
EU ETS carbon pricing and the F-Gas Regulation constrain clinker-to-cement ratios at Rüdersdorf and Lägerdorf facilities. Heidelberg Materials deploys alternative fuel co-processing to meet EU Green Deal trajectories. The Rhine-Ruhr industrial corridor concentrates grinding capacity for low-clinker LC3 formulations.
Brazil
Minha Casa Minha Vida housing programs sustain PPC demand in São Paulo and Minas Gerais construction markets. ANVISA environmental licensing delays greenfield kiln approvals. Votorantim and InterCement operate integrated coastal plants in Rio de Janeiro state, exporting clinker to African markets.
Saudi Arabia
NEOM and Red Sea Project mega-developments specify white cement for architectural facade applications. SABIC regulatory frameworks mandate emission reductions at Yanbu and Jeddah production bases. Eastern Province limestone quarries supply low-iron carbonate feedstock for premium clinker grades.
Portland Cement Market Key Industry Players
Global majors compete with regional champions across limestone reserve access and coastal distribution reach. The market structures around three tiers: integrated multinationals with captive quarry positions, mid-scale national champions serving protected domestic markets, and specialist white cement producers commanding aesthetic premiums. Strategic moves concentrate on alternative fuel integration and carbon capture retrofits rather than greenfield capacity additions.
Among North American heavy building materials specialists, CRH plc, Eagle Materials, and Martin Marietta occupy positions defined by quarry reserve depth and rail-linked distribution networks. LafargeHolcim and Heidelberg Materials exemplify the integrated multinational archetype through captive limestone control and kiln efficiency investments. Cemex anchors Latin American competitive dynamics via coastal clinker logistics and blended cement portfolios calibrated to regional sulfate resistance specifications.
| Leading Market Players |
|---|
| CRH plc |
| Eagle Materials |
| LafargeHolcim |
| Ash Grove Cement Company |
| Martin Marietta |
| Heidelberg Materials |
| Buzzi Unicem USA |
| Argos USA Corporation |
| Cemex |
| Others |
Cost & Logistics Intelligence
Clinker energy intensity, consuming 3-4 GJ per tonne in rotary kilns, cascades through three distinct pricing tiers: spot-indexed gray cement for mass housing, contract-anchored blended grades for infrastructure, and premium white cement for architectural specifications. Indian public works departments and German ready-mix suppliers now embed carbon-adjusted clauses into multi-year offtake agreements, compressing margin volatility for integrated producers while exposing merchant traders to EU ETS pass-through costs.
Pricing Analysis
Input-cost pass-through from fossil fuel and electricity tariffs dominates pricing formation, with European producers facing steeper adjustment trajectories under EU carbon border levies. Three-tier pricing structure across premium white, standard gray, and economy blended grades separates aesthetic-performance specifications from mass-market structural codes. Pricing pressure stems from alternative fuel co-processing investments required for EU Green Deal compliance, elevating capital recovery burdens. Government agencies exhibit highest price sensitivity through competitive tendering, while Gulf commercial facade developers absorb premium multiples for low-iron clinker.
Supply Chain Analysis
Regional distribution centers in Chittorgarh, Sirohi, and Gujarat's coastal belt feed hub-and-spoke networks radiating toward Mumbai, Delhi, and Bangalore construction corridors. Geographic supply concentrates in India, China, and Vietnam, with limestone quarry clustering creating captive reserve positions for integrated multinationals. Raw material dependencies span high-purity carbonate feedstock, petroleum coke, and waste-derived alternative fuels. Single-source vulnerability runs through concentrated limestone deposits in Rajasthan's Aravalli range. Distribution runs through bulk rail and coastal barge networks serving ready-mix concrete plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities crystallize where EU carbon border costs exceed Indian production economics by meaningful margins, rewarding clinker export positioning from low-emission intensity kilns.
For Market Incumbents: Deepen captive limestone reserve positions in Gujarat and Rajasthan to defend against geopolymer substitution threats in non-structural applications. Prioritize alternative fuel integration and LC3 grinding capacity to meet EU F-Gas Regulation clinker-ratio constraints without pyroprocessing rebuilds. For New Entrants and Emerging Players: Calcined clay activation technology offers a technology-first wedge into Brazilian and Colombian dam and highway specifications where 50% clinker reduction satisfies durability codes. Target India's tier-2 smart-city infrastructure programs through blended cement procurement channels. Pursue direct mill relationships with state public works departments bypassing wholesale intermediaries. For Investors and Strategic Acquirers: Consolidation pressure builds where limestone reserve depletion intersects with carbon capture retrofit capital requirements, favoring asset-light grinding operations over integrated kiln positions. Long-term viability centers on low-clinker product portfolios and coastal logistics networks. Watch EU ETS price trajectories as the inflection signal for stranded asset risk concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fuel Integration | Waste-derived biomass co-processing at Heidelberg Materials' Rüdersdorf facility reduces fossil fuel exposure under EU Green Deal trajectories. |
| LC3 Grinding Capacity Expansion | Calcined clay cement reconfiguration enables 50% clinker reduction without kiln rebuilds, piloted across Brazilian infrastructure contractors. |
| Carbon Capture Retrofit Deployment | Post-combustion amine scrubbing opens compliance pathways for legacy assets facing EU ETS tightening at German integrated plants. |
| Long-term Offtake Agreement Structuring | Fixed carbon-adjusted pricing clauses displace spot purchasing among French and German ready-mix suppliers under border adjustment pressure. |
| Coastal Distribution Network Optimization | Integrated clinker logistics from Rio de Janeiro state kilns anchor Latin American export competitiveness for Cemex and Votorantim. |
Research Approach
Multiple input streams — primary interviews with kiln operations managers, procurement leads at Indian public works departments, and European ready-mix concrete suppliers; secondary validation through BIS strength-grade specifications, EU ETS transaction registries, and SEC 10-K filings from North American heavy building materials specialists; plus customs and trade flow data — were reconciled through bottom-up capacity modeling and top-down demand triangulation.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning product chemistry grades, application durability specifications, and procurement channel concentration. CAGRs were derived from installed capacity utilization rates, clinker-to-cement ratio trajectories under EU F-Gas Regulation constraints, and urbanization-driven cement intensity coefficients for Indian infrastructure programs. Forecast inputs incorporated alternative fuel substitution timelines and carbon border adjustment phase-in assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU ETS price volatility, geopolymer binder substitution rates in non-structural applications, and limestone reserve depletion curves in India's Aravalli belt. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
United States Construction Materials Market
Building Materials
Concrete and Cement Market
Building Materials
Construction Repair Composites Market
Building Materials
Glass Facade Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Italy Facade Market
Building Materials
Cribbing Blocks Market
Building Materials
United States Architectural Coatings Market
Building Materials
Door Frame Metal Market
Building Materials
Roof Cover Boards Market
Building Materials
Cementitious Waterproofing Market
Building Materials
Africa Green Cement Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
US Contract Glazing Market