
 European Cross-Laminated Timber Market | 2026-2036
European Cross-Laminated Timber Market Size, Share, and Industry Trends Forecast 2026-2036
European Cross-Laminated Timber Market Intelligence
Prefabrication services bundled with structural engineering support is realigning what European CLT suppliers actually sell. Stora Enso leverages its Nordic timber base to anchor large-format panel supply across Northern Europe. Binderholz GmbH sustains vertical control from sawmill to finished CLT, competing on cost discipline in German-speaking markets. KLH Massivholz GmbH specializes in architect-specified custom dimensions, dominating premium residential and institutional segments.
Cross-laminated timber consists of odd-numbered layers of lumber boards stacked perpendicular to one another, bonded with structural adhesives under pressure, typically achieving panel thicknesses from 50mm to 500mm and spanning capabilities exceeding 15 meters. Its primary purpose is to replace steel and concrete in load-bearing walls, floors, and roofs of mid-rise buildings. Softwood CLT occupies the volume core due to spruce and pine availability, while hybrid CLT commands margin premiums by integrating hardwood layers for concentrated load zones. Residential construction leads application demand, though educational structures represent the fastest-growing specification channel as public procurement rules in Austria and Germany mandate embodied carbon disclosure.
The EU Green Deal, CE marking under the Construction Products Regulation, and national building codes in Germany and Austria govern structural fire safety, seismic performance, and carbon accounting for CLT assemblies. ECHA scrutiny of formaldehyde and isocyanate emissions from adhesives is tightening product standard thresholds, filtering smaller producers from certified supply chains. Stakeholders must monitor whether the EU Deforestation Regulation extends traceability burdens to temperate forestry, reshaping raw material cost structures and supplier qualification timelines.
Market Dynamics
The EU Green Deal's building decarbonization mandates are compressing project timelines and forcing developers to abandon steel and concrete specifications for engineered wood systems. This regulatory pressure is redrawing competitive boundaries between Alpine manufacturers and Nordic forestry-based suppliers.
Growth Catalysts
- CE marking under the Construction Products Regulation:Harmonized structural fire safety and seismic performance standards are eliminating national technical barriers across Germany, Austria, and Benelux markets.
- Multi-story residential construction:Urban densification policies in Vienna, Munich, and Zurich are mandating timber-first procurement for public housing developments exceeding four stories.
- Hybrid CLT technology:Integration of hardwood load-bearing layers into softwood cores is opening institutional and commercial specifications previously reserved for reinforced concrete.
Market Restraints
- Adhesive input cost volatility:ECHA scrutiny of formaldehyde and isocyanate emissions is tightening certified adhesive supply chains and filtering smaller producers from qualified supplier pools.
- Alpine manufacturing concentration:Overreliance on Austrian and southern German production clusters creates vulnerability to regional energy price shocks and transport bottlenecks.
- Steel substitution resilience:Established concrete and steel engineering expertise among European contractors slows specification switching despite embodied carbon advantages.
Strategic Opportunities
- Benelux underpenetration:Belgium and the Netherlands currently import over 60% of structural timber needs, creating white space for Nordic suppliers with captive spruce reserves.
- Educational structures procurement:Austrian and German public procurement rules mandating embodied carbon disclosure are accelerating CLT specification in university and school construction.
- Prefabrication-service bundling:Engineering-support contracts attached to panel supply are capturing margin previously captured by third-party structural consultants.
Industry Challenges
- Fire engineering certification timelines:Extended testing protocols for multi-story assemblies under German and Austrian building codes are delaying project mobilization by 8-14 months.
- Cross-laminated timber erection skill scarcity:Shortages of certified installers capable of managing large-format panel crane logistics are constraining build-speed commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | European Cross-Laminated Timber Market |
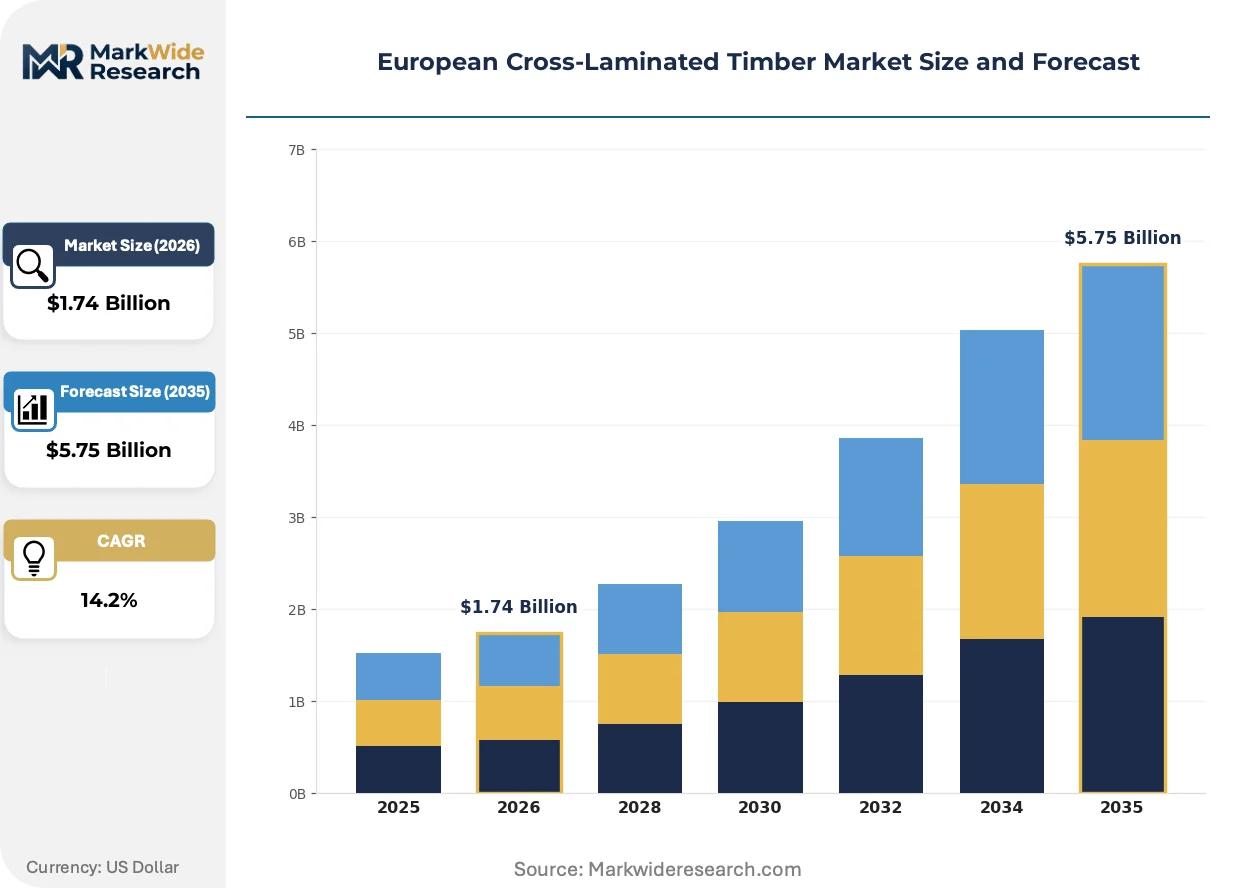
| Market Size in 2026 | $1.74 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softwood CLT, Hardwood CLT, Hybrid CLT, Pre-fabricated CLT Application: Residential Construction, Commercial Buildings, Educational Structures, Industrial Facilities Installation: DIY Projects, Professional Installations, Modular Construction, Custom Builds End User: Architects, Builders, Contractors, Homeowners |
| Companies Covered | Mayr-Melnhof Holz, Stora Enso, Binderholz GmbH, HASSLACHER Holding GmbH, KLH Massivholz GmbH, Schilliger Holz AG, Eugen Decker Holzindustrie KG, Pfeifer Holding GmbH, Mosser Leimholz, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
European Cross-Laminated Timber Market Strategic Shifts & Innovations
Digital fabrication and adhesive chemistry advances are compressing the gap between architectural design intent and manufacturing tolerances. These developments are enabling specification complexity that concrete and steel systems struggle to match at equivalent carbon intensity.
Hybrid CLT incorporating beech or oak hardwood layers into spruce-pine cores is expanding into high-load commercial floors and long-span institutional roofs previously dominated by post-tensioned concrete. German and Austrian architects specify these assemblies for atriums and gymnasiums requiring 15-meter clear spans. The technology is expanding into premium segments by delivering structural performance without the embodied carbon penalty of steel reinforcement.
EU Deforestation Regulation traceability requirements are forcing sawmill-to-site documentation systems that favor vertically controlled supply chains over fragmented procurement networks. ECHA emission thresholds for structural adhesives are simultaneously accelerating water-based and bio-based bonding chemistry adoption. Nordic producers with captive forestry certification are responding fastest, locking in preferred supplier status with German developers facing 2025 compliance deadlines.
Architects and developers in Austria and Germany now bundle structural engineering services directly with panel procurement, displacing traditional consultant-led specification processes. This model compresses design-to-delivery timelines by 20-30% for mid-rise residential projects. Vienna and Munich municipal housing authorities are the most visible adopters, requiring single-source accountability for performance warranties.
European Cross-Laminated Timber Market Segmentation
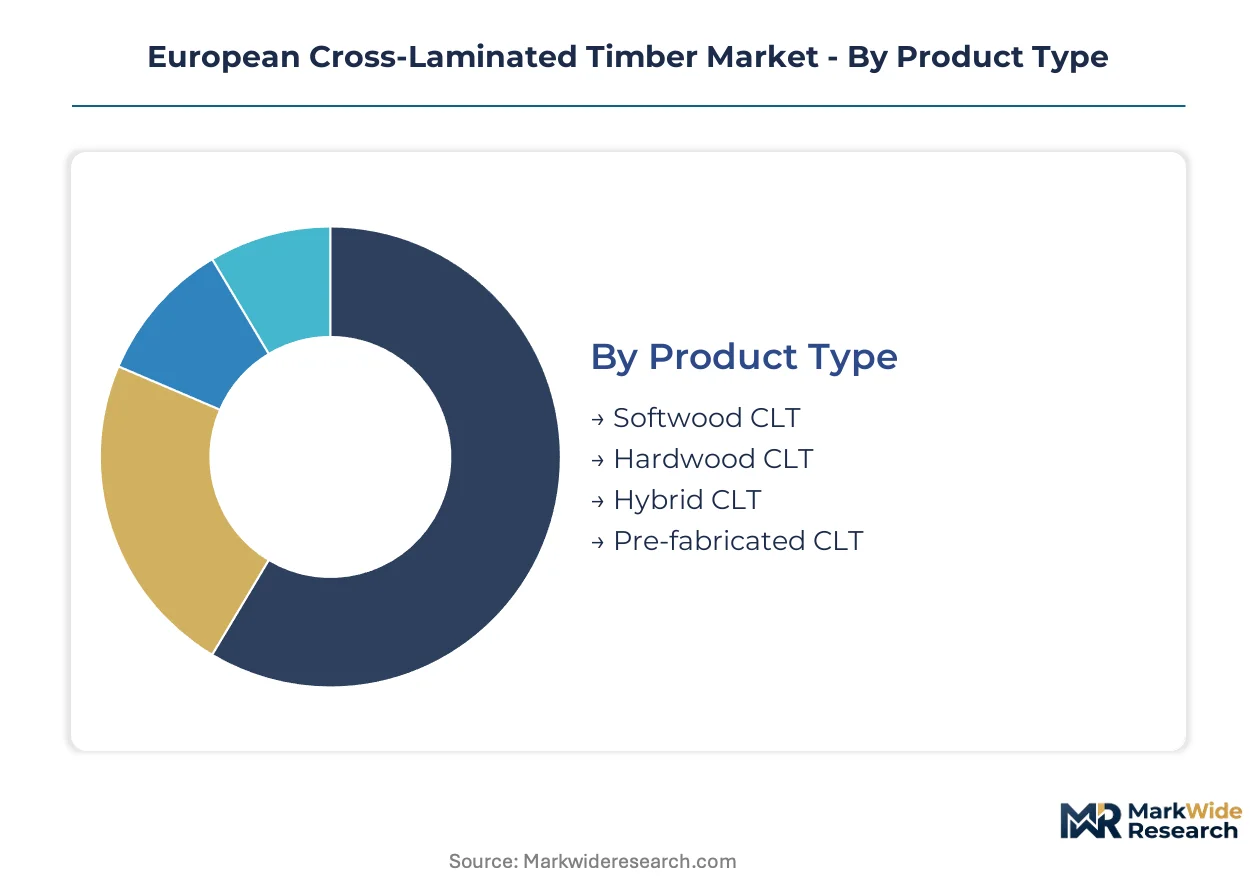
Engineered wood procurement in Europe fragments across specification complexity, project scale, and buyer technical sophistication. Understanding these divides reveals where margin concentrates and where volume commoditizes.
Product Type:
Buyers differentiate primarily by load-bearing requirements and carbon accounting rigor, not aesthetic preference.
- Softwood CLT:Spruce and pine laminations bonded under pressure deliver standard load-bearing capacity for walls and floors up to six stories. German and Austrian housing associations specify this grade for municipal residential blocks where cost discipline outweighs span requirements.
- Hybrid CLT:Hardwood load-bearing layers integrated into softwood cores enable 15-meter clear spans for institutional atriums and gymnasiums. Vienna and Munich architects specify these assemblies where embodied carbon disclosure mandates exclude steel reinforcement alternatives.
- Hardwood CLT:Dense beech or oak laminations serve specialized acoustic and fire-rated applications in premium commercial interiors.
- Pre-fabricated CLT:Factory-cut panels with integrated service channels reduce on-site labor hours for modular residential developers in Benelux markets.
Volume sits with Softwood CLT; growth tilts toward Hybrid CLT.
Application:
Project type determines regulatory exposure and procurement timeline compression.
- Residential Construction:Multi-story urban housing dominates tonnage, with Vienna, Munich, and Zurich municipal authorities mandating timber-first specifications for public developments exceeding four stories. CE marking harmonization accelerates cross-border procurement for standardized apartment typologies.
- Educational Structures:Austrian and German public procurement rules mandating embodied carbon disclosure accelerate university and school construction specifications. These projects demand extended fire engineering certification timelines that filter less experienced suppliers.
- Commercial Buildings:Office and retail developers specify CLT for brand positioning around sustainability credentials, though steel substitution resilience persists among established contractors.
- Industrial Facilities:Warehouse and logistics structures adopt CLT for roof decks where span-to-weight ratios favor engineered wood over precast concrete.
Residential Construction commands current volume; Educational Structures are climbing the fastest.
Installation:
Site labor availability and crane logistics separate viable projects from deferred commitments.
- Professional Installations:Certified crews manage large-format panel crane logistics and precision alignment for multi-story assemblies. Scarcity of these teams constrains build-speed commitments across Alpine and Nordic markets.
- Modular Construction:Factory-controlled assembly of complete volumetric units compresses weather-dependent schedules and reduces on-site skill requirements. Dutch and Belgian developers favor this route given import dependence for structural timber.
- Custom Builds:Architect-specified non-standard dimensions require close coordination between design teams and manufacturing schedulers.
- DIY Projects:Small-format garden structures and single-story extensions represent marginal volume with minimal regulatory engagement.
Professional Installations anchor revenue; Modular Construction gains share fastest.
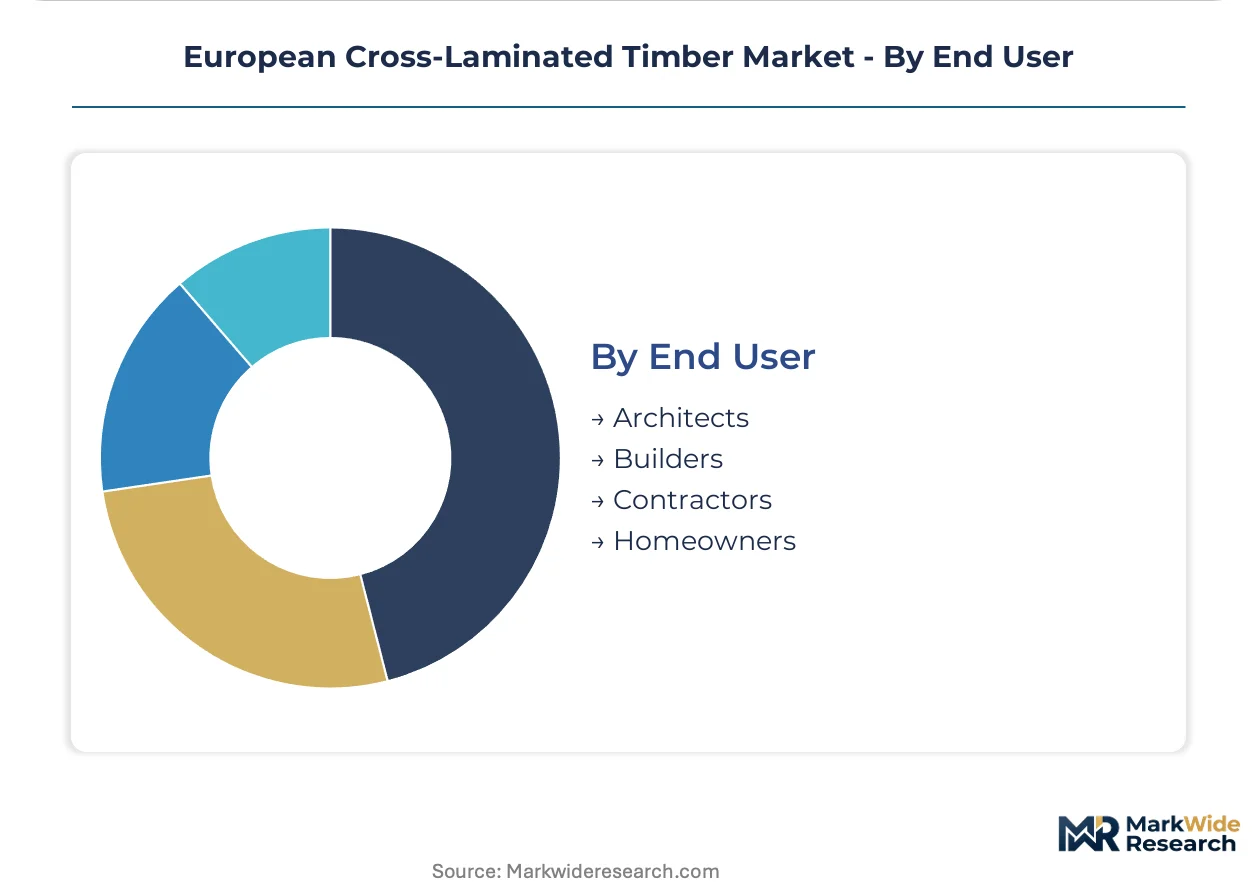
End User:
Technical authority over specification varies sharply across the value chain.
- Architects:Design professionals in Austria and Germany increasingly bundle structural engineering services directly with panel procurement, displacing traditional consultant-led processes. This compression of design-to-delivery timelines favors vertically controlled suppliers.
- Builders:Mid-sized construction firms purchasing on developer mandate seek single-source accountability for performance warranties and fire safety certification.
- Contractors:Established concrete and steel engineering expertise slows specification switching despite embodied carbon advantages, creating friction in project mobilization.
- Homeowners:Individual purchasers drive negligible volume, concentrated in rural single-family custom construction with limited influence on manufacturing scale.
Builders represent current volume concentration; Architects are displacing traditional procurement channels fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Alpine manufacturing clusters while consumption spreads across Northern and Western European urban centers. Austrian and German sawmill-to-CLT operations supply panels to Benelux and Nordic markets with limited domestic capacity. Transport logistics and CE marking harmonization determine cross-border procurement feasibility.
Germany
Munich and Berlin municipal housing authorities mandate timber-first specifications for public developments exceeding four stories. The national building code governs structural fire safety certification timelines that extend 8-14 months for multi-story assemblies. Bavarian manufacturing clusters around Rosenheim and Garmisch-Partenkirchen anchor softwood CLT supply for domestic and export markets.
Austria
Vienna's urban densification policies accelerate specification for mid-rise residential blocks in municipal procurement. The EU Green Deal's building decarbonization mandates filter through national technical standards for embodied carbon disclosure. Alpine production corridors in Tyrol and Carinthia sustain vertical integration from sawmill to finished panel.
Sweden
Stockholm and Gothenburg developers source large-format panels from Nordic forestry reserves for commercial and institutional specifications. CE marking under the Construction Products Regulation eliminates technical barriers with Continental European procurement. Västerbotten and Dalarna forestry regions supply captive spruce feedstock to integrated manufacturers.
Netherlands
Rotterdam and Amsterdam construction imports over 60% of structural timber needs, creating dependence on German and Austrian supply chains. Dutch building codes adopt EU harmonized standards for seismic performance and fire engineering. Modular construction developers in Randstad urban corridors favor factory-cut panels with integrated service channels.
Switzerland
Zurich and Geneva architects specify hybrid CLT for institutional atriums requiring 15-meter clear spans under cantonal sustainability mandates. Swiss building codes exceed EU baseline requirements for carbon accounting in public procurement. Alpine manufacturing partnerships with Austrian suppliers bridge domestic production gaps for premium residential segments.
European Cross-Laminated Timber Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a bifurcated supply structure. Alpine manufacturers with captive sawmill capacity dominate volume supply, while Nordic forestry-based suppliers anchor large-format panel distribution across Northern Europe. Three archetypes define competitive positioning: vertically integrated sawmill-to-CLT operators, specialist custom-dimension fabricators, and prefabrication-service bundlers. Capacity expansion and strategic partnerships with municipal housing authorities constitute the dominant competitive moves.
Among Austrian-based integrated producers, Mayr-Melnhof Holz and HASSLACHER Holding GmbH exemplify the sawmill-to-finished-panel archetype with captive timber supply. Stora Enso represents Nordic forestry-based supply chain control, leveraging Västerbotten reserves for cross-border panel distribution. KLH Massivholz GmbH occupies a position within the specialist tier, anchoring architect-specified custom dimension production for premium residential and institutional segments.
| Leading Market Players |
|---|
| Mayr-Melnhof Holz |
| Stora Enso |
| Binderholz GmbH |
| HASSLACHER Holding GmbH |
| KLH Massivholz GmbH |
| Schilliger Holz AG |
| Eugen Decker Holzindustrie KG |
| Pfeifer Holding GmbH |
| Mosser Leimholz |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between CE-marked structural panels and uncertified commodity laminates manifests in both pricing premiums and supply chain qualification timelines. German developers facing EU Green Deal compliance deadlines pay structural fire safety certification premiums that filter smaller Austrian producers from qualified supplier pools, while Benelux buyers absorbing transport costs from Alpine manufacturing clusters face landed price spreads that reshape procurement geography.
Pricing Analysis
Cost-down pressure on standard softwood CLT accelerates as municipal housing associations in Vienna and Munich consolidate procurement volumes. Three-tier pricing structure across custom-dimension hybrid, standard softwood, and economy-grade panels separates architect-specified institutional projects from commodity residential blocks. ECHA adhesive emission thresholds tighten certified supply chains, pushing price differentiation toward CE marking tier and vertical integration depth. Municipal buyers exhibit highest price sensitivity; premium institutional developers prioritize span performance over unit economics.
Supply Chain Analysis
Certified erection crew shortages in Tyrol and Carinthia production corridors constrain panel throughput regardless of manufacturing capacity. Supply concentrates in Austrian and southern German sawmill-to-CLT operations, with Nordic forestry reserves in Västerbotten anchoring large-format distribution across Northern Europe. Raw material flows draw from spruce and pine feedstocks, structural adhesive formulations, and hardwood laminations for hybrid grades. Single-source vulnerability sits with Alpine energy price exposure. Distribution runs through direct mill-to-site contracts for major developers and specialized distributors for fragmented project demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installer scarcity props structural panel pricing across the European CLT market, with capacity bottlenecks in fire engineering certification and crane-logistics crews limiting build-speed commitments regardless of manufacturing expansion.
For Market Incumbents: Anchor market position through captive forestry certification under EU Deforestation Regulation traceability requirements and backward integration into adhesive chemistry to offset ECHA emission compliance costs. Defend against Nordic suppliers penetrating Benelux import dependence by locking long-term offtake contracts with Rotterdam and Amsterdam modular developers. Prioritize fire engineering certification capacity expansion to compress 8-14 month project mobilization timelines. For New Entrants and Emerging Players: Capture white space in Netherlands and Belgium educational structures procurement where embodied carbon disclosure mandates accelerate CLT specification against limited domestic manufacturing. Target Dutch modular construction developers in Randstad urban corridors seeking factory-cut panels with integrated service channels. Enter through engineering-service bundling partnerships that displace traditional consultant-led specification processes. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical sawmill-to-CLT operators with captive forestry certification and established municipal housing authority relationships. Long-term viability across the analysis window hinges on EU Green Deal building decarbonization enforcement durability and adhesive chemistry transition costs. Watch ECHA formaldehyde threshold tightening velocity as inflection indicator for supplier filtration intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Chemistry | ECHA emission compliance accelerates water-based bonding chemistry adoption among certified producers. |
| Fire Engineering Certification Capacity Expansion | German and Austrian building code timelines constrain project mobilization for uncertified suppliers. |
| Long-term Supply Agreement with Municipal Housing | Vienna and Munich timber-first mandates create anchor demand for qualified panel suppliers. |
| Engineering-Service Bundling Partnership | Architects in Alpine markets displace traditional consultants through single-source accountability models. |
| Forestry Certification Lock-in | EU Deforestation Regulation traceability requirements favor vertically controlled supply chains. |
Research Approach
Document review covered trade customs data, EU Construction Products Regulation filings, and ECHA chemical safety dossiers, complemented by interviews with CLT plant managers, structural engineering consultants, municipal procurement officers, and adhesive supply specialists. Secondary validation drew from national building code repositories, forestry certification databases, and construction project tracking systems. Bottom-up volume modeling triangulated against top-down sectoral spend analysis.
Cross-referencing historical production capacity utilization against panel manufacturer capex disclosures and municipal housing procurement pipelines anchored the analytical framework. Segmentation dimensions modeled include product type tier, application vertical, installation method, and end-user technical authority across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating EU Green Deal compliance trajectory and adhesive input cost volatility.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA emission threshold enforcement, Alpine energy price shocks, and Benelux import substitution velocity. Forecasts reflect documented assumptions around regulatory compliance timelines and certified labor pool expansion. Material deviation in EU Deforestation Regulation temperate forestry extension or adhesive chemistry transition costs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Wood House Frame Market