
 Europe Green Buildings Market | 2026-2036
Europe Green Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Green Buildings Market Insights
European green building material production is expanding across the Rhine-Ruhr industrial belt and northern Italy's precast concrete corridor. Wienerberger anchors clay block and façade system supply through its Central European kiln network. Skanska competes on integrated design-build contracts that bundle BREEAM certification with operational energy guarantees. HOLCIM extends low-carbon cement and recycled aggregate portfolios to meet EN 15804-compliant environmental product declarations.
Europe green buildings are structures designed, constructed, and operated to minimize energy consumption, water use, and embodied carbon across their full lifecycle, typically achieving thermal transmittance values below 0.15 W/m²K for envelopes and primary energy demand under 50 kWh/m² annually. Their commercial purpose centers on reducing operational expenditure for owners while satisfying tenant ESG mandates and securing green financing premiums. Residential building type leads volume as national renovation waves target multifamily housing stock, though commercial certification commands margin concentration through BREEAM Outstanding and LEED Platinum specifications. Smart technology construction is gaining fastest as IoT-enabled building management systems integrate with grid-responsive heat pumps and on-site solar generation.
EU Green Deal renovation targets, the Energy Performance of Buildings Directive, and national transpositions through Germany's Building Energy Act and France's RE2020 regulation are reshaping permit requirements and retrofit obligations. EMA and national regulators are not directly involved, but ECHA's REACH restrictions on high-GWP blowing agents and flame retardants constrain insulation material formulations. Stakeholders must monitor how the EU AI Act and incoming CSRD reporting standards will layer algorithmic building optimization and embodied carbon disclosure onto existing energy compliance frameworks.
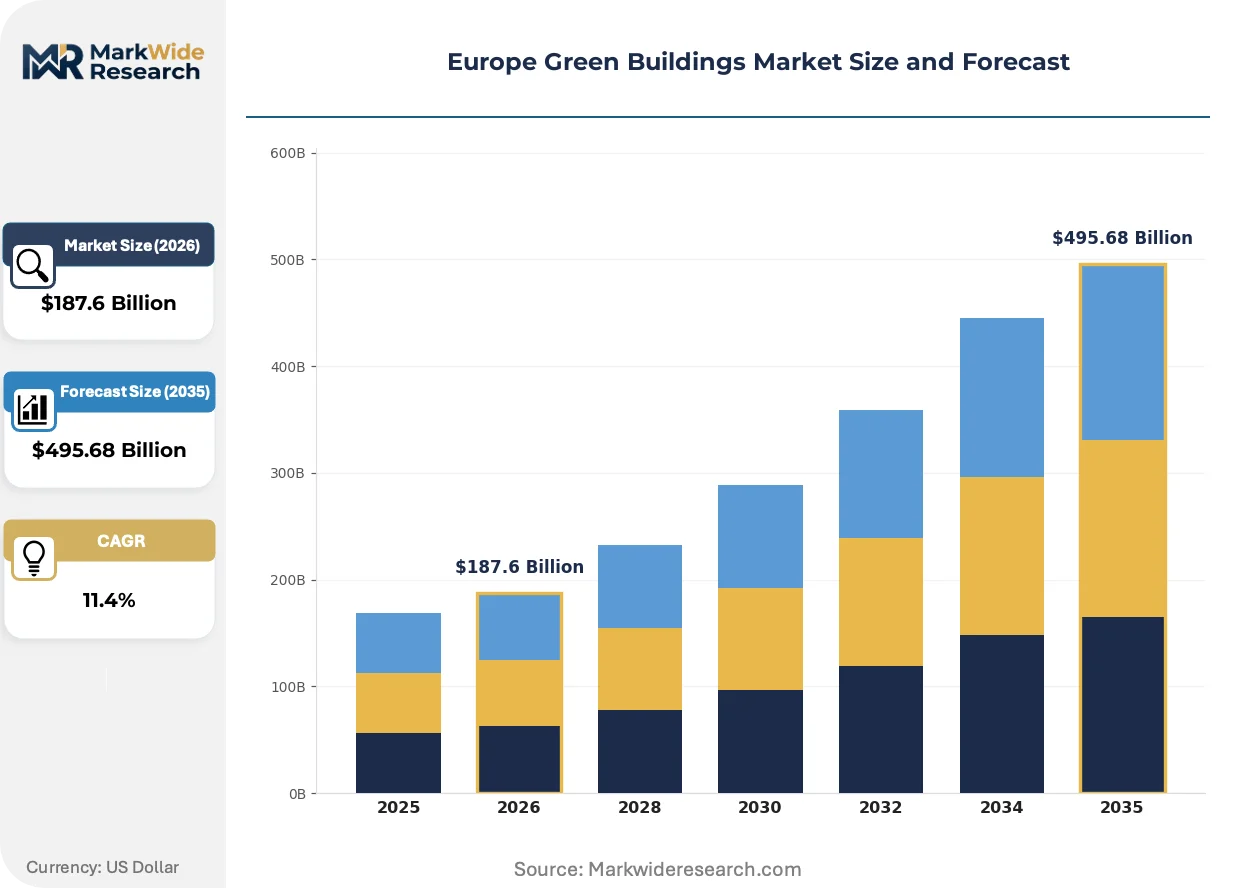
Market Dynamics
The EU Green Deal's building renovation requirements are compressing retrofit timelines and forcing capital reallocation toward envelope upgrades and heat pump integration across commercial and residential portfolios.
Growth Catalysts
- EPBD Transposition:National implementations of the Energy Performance of Buildings Directive are mandating near-zero energy standards for new permits in Germany's Rhine-Ruhr corridor and France's Île-de-France region.
- F-Gas Phase-Down:The tightening EU F-Gas Regulation is accelerating the replacement of high-GWP refrigerants in commercial HVAC systems, driving heat pump retrofits in Dutch logistics facilities.
- Green Financing Spreads:ESG-linked loan premiums are narrowing for assets with BREEAM Outstanding or LEED Platinum certification, pulling institutional capital into certified office development.
Market Restraints
- Low-Carbon Cement Scarcity:EN 15804-compliant environmental product declarations remain limited for structural concrete, constraining embodied carbon targets in high-rise construction.
- Insulation Input Volatility:ECHA REACH restrictions on high-GWP blowing agents and halogenated flame retardants are disrupting supply continuity for rigid foam formulations.
- Certification Bottlenecks:BREEAM assessor capacity concentrates in London and Amsterdam, creating queue delays for projects in secondary Polish and Romanian markets.
Strategic Opportunities
- Smart Building Convergence:IoT-enabled building management systems integrating with grid-responsive heat pumps and on-site solar generation are opening performance-contracting revenue streams.
- CSRD-Ready Disclosure:The incoming Corporate Sustainability Reporting Directive is creating first-mover advantage for firms with automated embodied carbon tracking across construction supply chains.
- Nordic Renovation Wave:Sweden and Finland's multifamily housing stock built during the 1960s-1970s expansion offers concentrated envelope retrofit potential under national subsidy schemes.
Industry Challenges
- Deep Retrofit Coordination:Sequencing envelope, HVAC, and electrical upgrades in occupied buildings requires specialized project management capabilities that remain scarce outside Berlin and Paris.
- Skills Mismatch:Heat pump installation and building physics modeling expertise lags behind permit issuance rates in Italy's northern precast corridor and Spain's Mediterranean coast.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Green Buildings Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Residential, Commercial, Industrial, Institutional Construction Technology: Prefabricated, Modular, Sustainable, Smart Technology Energy Source: Solar, Wind, Geothermal, Biomass Certification Standard: BREEAM, LEED, DGNB,HQE |
| Companies Covered | Bauder Ltd, AECOM, Skanska, Turner Construction Company, DuPont de Nemours Inc., Wienerberger, Alumasc Group PLC, Forbo International SA, HOLCIM, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Green Buildings Market Trends and Innovations
Digital twin technology and AI-driven energy optimization are compressing the gap between design-phase modeling and operational performance, forcing recalibration of how green building value is measured and guaranteed.
Dynamic building envelopes incorporating electrochromic glazing and phase-change materials are rewriting thermal performance assumptions for commercial facades. Logistics developers in the Netherlands and Germany are specifying these systems to meet tightening operational energy caps. The technology is compressing payback calculations for high-performance envelopes from decade-long horizons toward single-digit year returns.
The EU AI Act's risk-classification framework for building automation systems is reshaping vendor liability and insurance structures. Algorithmic control of HVAC and lighting now triggers conformity assessment obligations that extend procurement cycles. Commercial office developers in France and Germany are front-loading compliance documentation to avoid construction-phase delays.
Tenant ESG mandates are fragmenting lease structures into performance-guarantee clauses with operational energy and carbon disclosures. Institutional asset managers in London and Stockholm are unbundling base rent from utility pass-throughs, creating direct financial exposure to building efficiency outcomes. This shift is most visible in logistics and data center leases where power usage effectiveness ratios now drive renewal negotiations.
Europe Green Buildings Market Segmentation
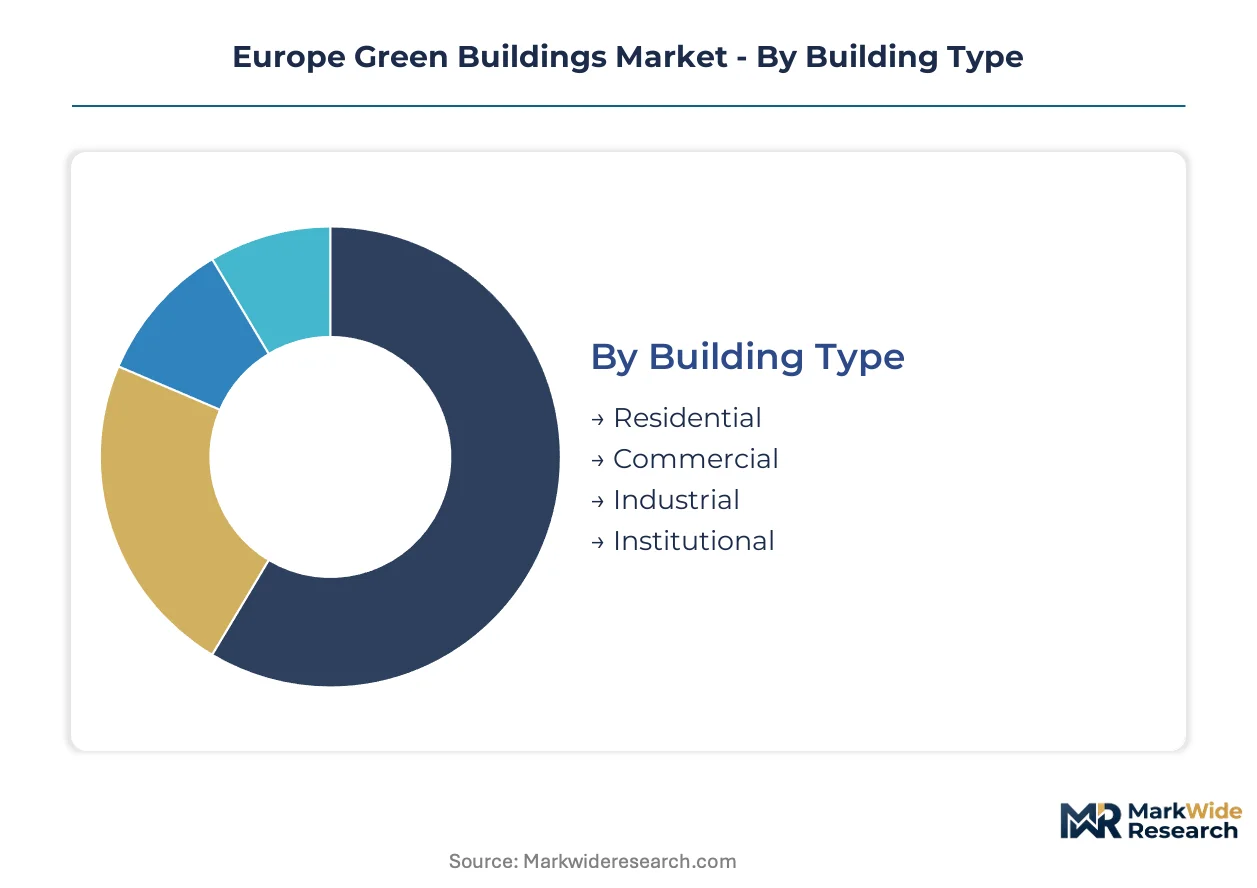
Europe's green building market fragments across four distinct dimensions, each shaping capital allocation and regulatory compliance differently. Building type determines subsidy eligibility and renovation wave targeting, while certification standards gate access to green financing premiums. Construction technology and energy source choices increasingly interconnect as integrated design-build contracts bundle performance guarantees.
Building Type:
Residential volume dominates permit counts, yet commercial assets concentrate margin through certification premiums and institutional capital flows.
- Residential:Multifamily housing stock built during the 1960s-1970s expansion across Sweden, Finland, and Germany's Rhine-Ruhr corridor drives envelope retrofit demand under national subsidy schemes. Municipal building codes in Berlin-Brandenburg now mandate near-zero energy performance for new construction permits, compressing timelines for deep renovation coordination.
- Commercial:Certified office and logistics assets in Germany, France, and the Netherlands command narrowing ESG-linked loan spreads through BREEAM Outstanding and LEED Platinum specifications. Tenant ESG mandates are fragmenting lease structures into performance-guarantee clauses with direct financial exposure to building efficiency outcomes.
- Industrial:Manufacturing facilities face tightening F-Gas Regulation compliance for process cooling and HVAC replacement schedules.
- Institutional:Healthcare and education buildings navigate EU Green Deal renovation targets with extended operational disruption constraints.
Today's leader: Residential. Tomorrow's challenger: Commercial.
Construction Technology:
Smart technology integration is climbing the fastest as IoT-enabled systems rewrite procurement specifications and vendor liability structures.
- Prefabricated:Northern Italy's precast concrete corridor scales EN 15804-compliant environmental product declarations for low-carbon structural elements. Factory-controlled production environments reduce embodied carbon variance compared to site-cast alternatives.
- Modular:Repeatable unit construction compresses project timelines for multifamily residential developments in secondary Polish and Romanian markets where BREEAM assessor capacity remains scarce.
- Sustainable:Clay block and façade system supply from Wienerberger's Central European kiln network anchors mass-market green material availability.
- Smart Technology:Grid-responsive heat pumps and on-site solar generation integration trigger EU AI Act conformity assessment obligations that extend procurement cycles for French and German commercial office developers.
Prefabricated methods currently capture the largest project pipeline. Smart technology offers the steepest expansion trajectory through performance-contracting revenue models.
Energy Source:
Solar and geothermal deployments concentrate where grid interconnection regulations and drilling permissions align most favorably.
- Solar:On-site photovoltaic integration with building management systems dominates Dutch logistics facilities and German commercial portfolios seeking operational energy caps compliance.
- Geothermal:Ground-source heat pump retrofits accelerate across the Netherlands where F-Gas phase-down timelines compress HVAC replacement decisions.
- Wind:Building-integrated micro-turbines remain niche, constrained by urban planning height restrictions and noise ordinances.
- Biomass:District heating feedstock competition from industrial offtakers limits residential building adoption in Nordic markets.
Solar maintains installed base leadership. Geothermal is gaining share fastest as heat pump mandates harden.
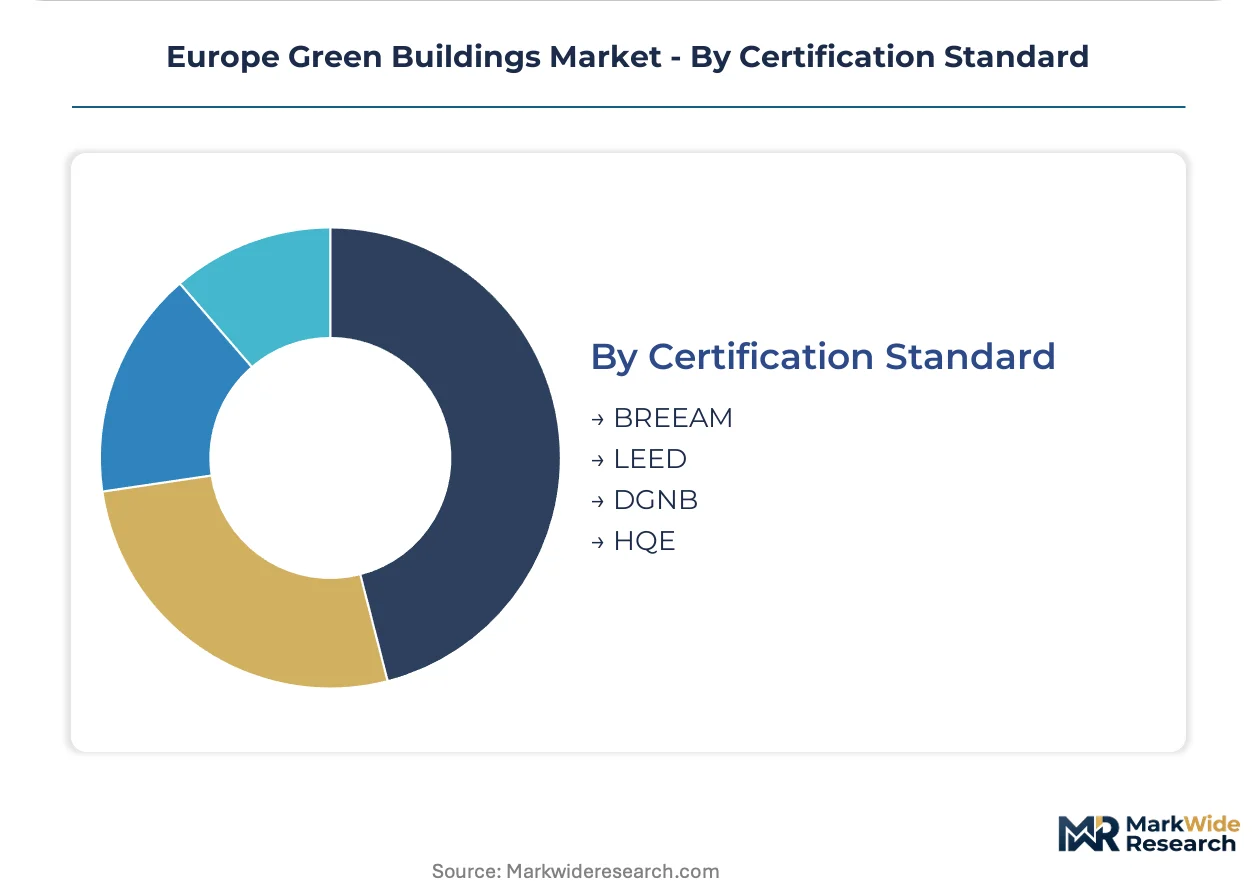
Certification Standard:
Assessment capacity geography determines project queue lengths and developer standard selection in secondary markets.
- BREEAM:Assessor concentration in London and Amsterdam creates bottleneck delays for Polish and Romanian projects, pushing some developers toward alternative standards. Outstanding-rated assets secure the narrowest green financing spreads.
- LEED:Platinum specifications attract US institutional capital deploying into European commercial real estate, particularly in France's Île-de-France region.
- DGNB:Germany's national system aligns tightly with Building Energy Act transpositions of EPBD requirements.
- HQE:France's reference standard integrates with RE2020 regulation for new construction energy performance.
BREEAM holds cross-border recognition leadership. DGNB and HQE are consolidating national regulatory alignment advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in certified commercial stock, while the Netherlands compresses retrofit timelines through stricter municipal enforcement than either neighbor.
Germany
The Building Energy Act mandates near-zero energy performance for new construction permits across Berlin-Brandenburg and the Rhine-Ruhr corridor. ECHA REACH restrictions on high-GWP blowing agents constrain rigid foam insulation formulations. Skanska competes on integrated design-build contracts bundling BREEAM certification with operational energy guarantees in these dense urban clusters.
France
RE2020 regulation enforces stringent lifecycle carbon limits on new buildings in the Île-de-France region. The HQE certification system aligns tightly with national energy performance requirements. HOLCIM extends low-carbon cement portfolios to meet EN 15804-compliant environmental product declarations for Paris commercial developments.
Netherlands
F-Gas Regulation phase-down timelines accelerate heat pump retrofits in Dutch logistics facilities concentrated around Rotterdam and Eindhoven. Municipal building codes now mandate operational energy caps for industrial permits. Grid-responsive solar integration dominates warehouse specifications as developers seek ESG-linked financing premiums.
Sweden
National subsidy schemes target multifamily housing stock built during the 1960s-1970s expansion across Stockholm and Malmö. The EU Green Deal renovation targets compress envelope retrofit coordination timelines. Wienerberger anchors clay block supply through its Central European kiln network to serve Nordic thermal performance demands.
Italy
Northern Italy's precast concrete corridor scales EN 15804-compliant environmental product declarations for low-carbon structural elements. Factory-controlled production reduces embodied carbon variance versus site-cast alternatives. DuPont de Nemours Inc. occupies a position within material innovation archetypes serving Mediterranean climate adaptation requirements.
Europe Green Buildings Market Competitive Landscape
Central European producers anchor one tier; Nordic and Anglo-Dutch specialists hold differentiated positions in certification-integrated service delivery. The vendor base organizes around three strategic archetypes: integrated design-build contractors, building material manufacturers with low-carbon portfolios, and engineering consultancies with lifecycle assessment capabilities. Capacity expansion and portfolio diversification dominate competitive moves as firms respond to tightening embodied carbon disclosure requirements.
Within the integrated contracting tier, Skanska and Turner Construction Company exemplify archetypes bundling certification attainment with performance guarantees. Among material specialists, Wienerberger and HOLCIM occupy positions anchored to regional production networks. Engineering consultancies represented by AECOM sit within the technical advisory segment where building physics modeling and regulatory compliance documentation concentrate expertise. Bauder Ltd, Alumasc Group PLC, and Forbo International SA represent specialized component suppliers serving envelope and interior finish specifications. DuPont de Nemours Inc. anchors the advanced materials tier where formulation chemistry responds to ECHA REACH restrictions on high-GWP inputs.
| Leading Market Players |
|---|
| Bauder Ltd |
| AECOM |
| Skanska |
| Turner Construction Company |
| DuPont de Nemours Inc. |
| Wienerberger |
| Alumasc Group PLC |
| Forbo International SA |
| HOLCIM |
| Others |
Pricing and Supply Chain Analysis
Heat pump installation expertise concentrated in Germany's Rhine-Ruhr corridor and the Netherlands widens pricing-tier spreads between certified and uncertified building projects, as labor-cost differentials compound material premiums for BREEAM Outstanding specifications.
Pricing Analysis
Capacity additions in northern Italy's precast concrete corridor are reshaping price floors for low-carbon structural elements as EN 15804-compliant environmental product declarations proliferate. Three-tier pricing structure across premium, standard, and economy levels separates BREEAM Outstanding assets with operational energy guarantees from code-minimum compliance projects. Cost compression in the standard tier is intensifying because Wienerberger's Central European kiln network achieves scale efficiencies in clay block production. Logistics developers in the Netherlands exhibit highest price sensitivity due to thin margins on warehouse specifications, while institutional office investors in Paris and Stockholm absorb premium pricing for CSRD-ready embodied carbon tracking.
Supply Chain Analysis
Workforce availability constraints in Germany, France, and the Netherlands are extending procurement cycles for smart building integration projects subject to EU AI Act conformity assessments. The supply chain draws from HOLCIM's low-carbon cement kilns in France, Wienerberger's clay block network across Central Europe, and DuPont's advanced materials formulations responding to ECHA REACH restrictions. Single-source vulnerability concentrates in rigid foam insulation formulations where high-GWP blowing agent phase-downs disrupt qualified supplier pools. Distribution runs through integrated design-build contractors like Skanska bundling certification with performance guarantees, rather than fragmented material spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through premium-tier certification concentration, as operational energy guarantees command financing spreads that offset embodied carbon compliance costs.
For Market Incumbents: Extend backward integration into low-carbon cement and recycled aggregate production to secure EN 15804-compliant supply chains before scarcity hardens. Consolidate BREEAM assessor capacity in Warsaw and Bucharest to capture queue delays plaguing secondary markets. Certification investment in DGNB and HQE national systems defends against US institutional capital flows favoring LEED Platinum specifications in Paris and Frankfurt. For New Entrants and Emerging Players: AI-driven building energy optimization algorithms offer a technology-first wedge into performance-contracting revenue streams where incumbents lack algorithmic audit capabilities. Target Poland's multifamily residential renovation wave where assessor scarcity delays BREEAM certification timelines. Partner with municipal housing authorities on envelope retrofit coordination to bypass established contractor relationships in Berlin-Brandenburg. For Investors and Strategic Acquirers: Integrated real estate developers with captive sustainability consulting arms are the most active acquirer in this space, consolidating lifecycle assessment capabilities ahead of CSRD disclosure mandates. Firms with automated embodied carbon tracking across construction supply chains represent the most defensible acquisition profile. Monitor F-Gas Regulation enforcement intensity in Dutch logistics facilities as an inflection indicator for heat pump retrofit capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Materials | Captive supply of EN 15804-compliant cement secures embodied carbon targets for high-rise Paris developments. |
| Smart Building Platform Integration | Grid-responsive heat pump and solar integration triggers EU AI Act compliance documentation requirements. |
| Certification Capacity Expansion | BREEAM assessor networks in Warsaw and Bucharest reduce queue delays for Polish and Romanian projects. |
| Performance Contracting Revenue Models | Operational energy guarantees align landlord incentives with tenant ESG mandates in Stockholm logistics leases. |
| CSRD-Ready Disclosure Systems | Automated embodied carbon tracking creates first-mover advantage for construction supply chain transparency. |
Research Methodology
Bottom-up building type and certification standard modeling reconciled against top-down material production tracking forms the analytical core of this study. Primary interviews with commercial real estate developers, BREEAM assessors, municipal building code officials, and EPC contractors combined with secondary validation from EU Green Deal implementation reports, national transpositions of the Energy Performance of Buildings Directive, and EN 15804 environmental product declaration databases. Trade data on low-carbon cement flows and heat pump installation permits triangulate supply-side constraints against demand projections.
Input-output matrices map construction technology adoption rates against regulatory compliance thresholds across the projection horizon. Segmentation dimensions include building type, certification standard, construction technology, and energy source, with regional regulatory clusters capturing EPBD transposition variance. CAGRs derive from permit issuance trajectories, renovation wave subsidy allocations, and green financing spread compression observed in ESG-linked loan markets. Forecast inputs incorporate F-Gas Regulation phase-down schedules and EU AI Act risk-classification timelines for building automation systems.
The model holds under steady EPBD enforcement and CSRD disclosure implementation; deviation in national subsidy scheme continuity or REACH restriction scope expansion would shift retrofit capital allocation timing. Practitioners should monitor municipal building code amendments in Germany's Berlin-Brandenburg corridor and the Netherlands' operational energy cap enforcement for early signals of regulatory acceleration or deceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
Rubble Sacks Market
Building & Construction Materials
Acoustic Panel Market
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
US Parking Deck Coatings Market